
 Calcium Glycerophosphate Market | 2026-2036
Calcium Glycerophosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Glycerophosphate Market Analysis
Pharmaceutical-grade calcium glycerophosphate is redrawing competitive boundaries as buyers enforce stricter USP and EP monograph compliance. SEPPIC leverages its specialty chemical expertise to sustain premium positioning in European nutraceutical channels. American Elements anchors North American supply through vertically integrated rare earth and mineral compound operations. Global Calcium competes on cost-efficient bulk production for Asian pharmaceutical formulators.
Calcium glycerophosphate is a calcium salt of glycerophosphoric acid, typically supplied as a white crystalline powder with specified calcium content between 18-20% and phosphorus content of 14-16%, manufactured through neutralization of glycerophosphoric acid with calcium hydroxide or carbonate for use as a bioavailable calcium and phosphorus source in human and animal nutrition. The nutritional supplements segment dominates volume as aging populations prioritize bone density maintenance, while the pharmaceuticals segment commands superior margins due to injectable and parenteral grade certification requirements. Food additives applications are maturing in fortified dairy alternatives, whereas personal care represents an emerging outlet where mineral complexes support skin barrier formulations.
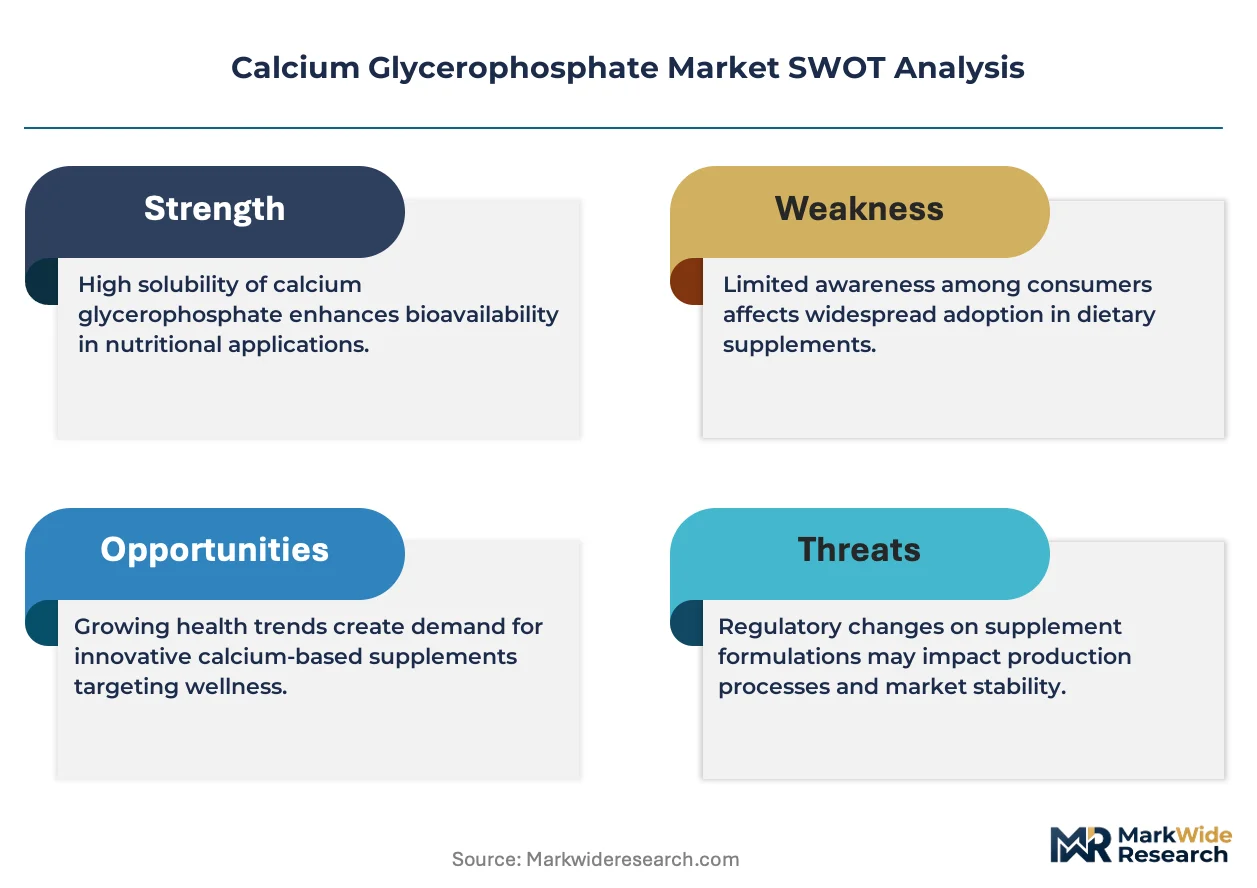
FDA dietary supplement cGMPs, EMA pharmacopeial standards, and FSSAI food additive notifications collectively elevate purity thresholds and documentation burdens for cross-border suppliers. REACH registration requirements in Europe restrict non-compliant importers, while India's BIS certification for food-grade mineral salts creates additional market access filters. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF and EP monographs to anticipate specification drift that could obsolete existing inventory or trigger reformulation costs.
Market Dynamics
Pharmaceutical-grade certification requirements are restructuring competitive boundaries as buyers enforce stricter USP and EP monograph compliance, forcing suppliers to upgrade purification infrastructure or exit premium segments entirely.
Growth Catalysts
- Aging demographics in developed economies:Populations over 65 in Japan, Germany, and Italy are expanding calcium supplementation regimens, driving sustained volume demand for bioavailable mineral salts in bone-health formulations.
- REACH registration thresholds:ECHA compliance mandates in Europe are filtering out non-compliant importers, consolidating market access for registered suppliers with documented supply chain transparency.
- Injectable-grade manufacturing expansion:Parenteral nutrition compounders are qualifying calcium glycerophosphate for intravenous applications, opening higher-margin pharmaceutical channels beyond oral supplements.
Market Restraints
- Phosphoric acid feedstock volatility:Fluctuating phosphate rock prices from Moroccan and Chinese suppliers compress margin predictability for neutralization-based production.
- European supply concentration:REACH-registered production capacity clusters in Germany and France, creating single-source vulnerability for buyers requiring EU-origin documentation.
- Tricalcium phosphate substitution:Lower-cost calcium salts with comparable elemental calcium content threaten volume in price-sensitive food fortification applications.
Strategic Opportunities
- Indian pharmaceutical formulators:CDSCO and BIS certification requirements are maturing, creating first-mover advantage for suppliers establishing local technical partnerships before regulatory harmonization completes.
- Personal care mineral complexes:Skin barrier formulations incorporating bioavailable calcium are emerging in South Korean and Japanese cosmetic pipelines, diversifying beyond traditional nutrition applications.
- US IRA domestic manufacturing incentives:Critical mineral processing tax credits are subsidizing North American production facility upgrades for dietary supplement ingredient manufacturing.
Industry Challenges
- Analytical chemistry talent scarcity:USP and EP monograph testing requires specialized ion chromatography expertise that competes with broader pharmaceutical quality assurance labor markets.
- Multi-jurisdiction certification timelines:Simultaneous FDA cGMP, EMA GMP, and FSSAI food-grade approvals extend product launch cycles by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Glycerophosphate Market |
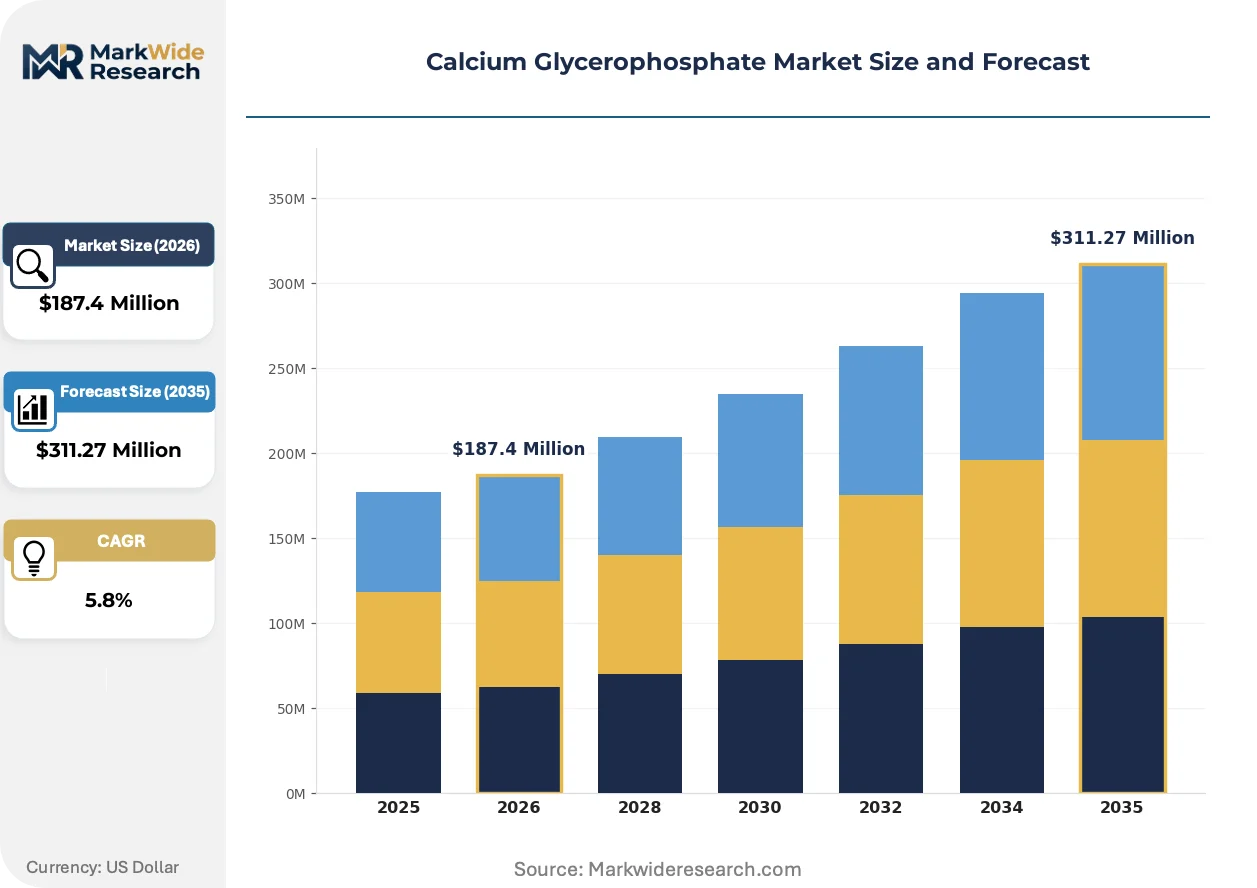
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Food Additives, Nutritional Supplements, Cosmetics Application: Dietary Supplements, Oral Health, Animal Feed, Personal Care End User: Healthcare Providers, Nutraceutical Companies, Food Manufacturers, Cosmetic Brands Distribution Channel: Online Retail, Drugstores, Supermarkets, Specialty Stores |
| Companies Covered | Sri Vyjayanthi Labs, Chempol, SEPPIC, Anmol Chemicals, American Elements, Penta Manufacturer, Global Calcium, Jai Radhe Sales, Nitika Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Glycerophosphate Market Emerging Trajectories
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times while regulatory data integrity mandates are reshaping documentation architectures across calcium salt production.
Membrane filtration-based purification is displacing traditional solvent crystallization in pharmaceutical-grade calcium glycerophosphate production. European injectable compounders are adopting this technology to reduce residual solvent burdens and accelerate batch release timelines. The shift is compressing capital requirements for new entrants while raising purity benchmarks that legacy precipitation methods struggle to meet economically.
EMA's revised GMP Annex 1 for sterile manufacturing is mandating enhanced environmental monitoring and closed-system processing for parenteral-grade mineral salts. The regulation is forcing retrofit investments in isolator technology and automated filling lines. Parenteral nutrition manufacturers in Italy and Spain are consolidating supplier bases to partners with pre-validated sterile processing capabilities.
Direct-to-supplement-brand procurement is consolidating traditional distributor intermediaries in North American nutraceutical channels. Large contract manufacturers are establishing preferred supplier agreements with calcium salt producers, bypassing regional chemical distributors. This channel compression is most advanced in California and Utah, where vertically integrated supplement brands control formulation and packaging in-house.
Calcium Glycerophosphate Market Segmentation
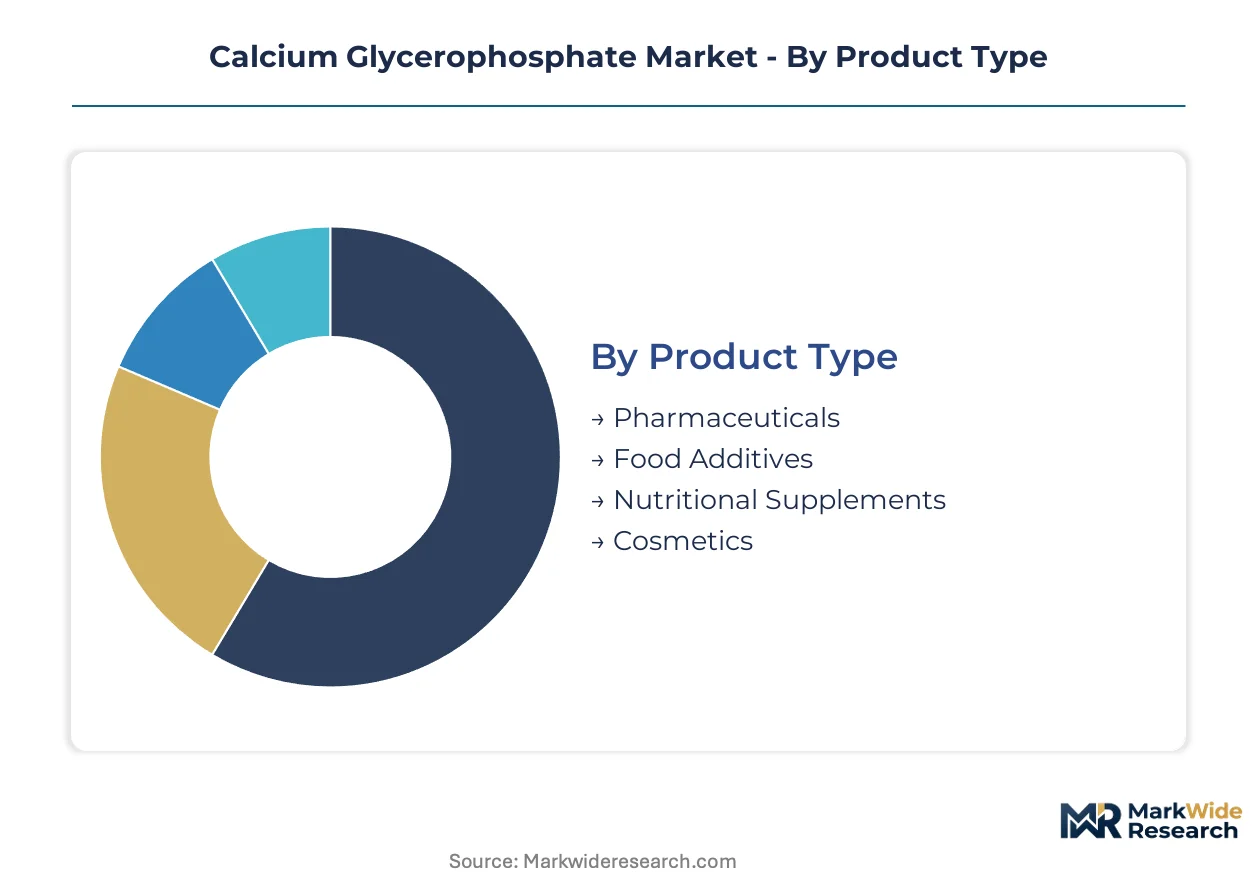
Calcium glycerophosphate specifications diverge sharply across end-use categories, with pharmaceutical and food-grade certifications imposing incompatible purity thresholds. Suppliers must maintain parallel production trains or sacrifice margin by over-engineering lower-specification segments.
Product Type:
Pharmaceutical-grade output dominates export flows to regulated European and North American markets, while food additive and cosmetic grades concentrate in domestic Asian supply chains.
- Pharmaceuticals:Injectable and parenteral grades require USP-NF or EP monograph compliance with residual solvent limits below 50 ppm. Demand concentrates in Italy and Germany where sterile compounding facilities source EU-origin documentation for EMA GMP compliance. REACH registration and closed-system manufacturing mandates filter out non-European suppliers.
- Nutritional Supplements:Oral-grade material with 18-20% calcium content serves capsule and tablet formulators in Utah and California. FDA cGMP dietary supplement rules enforce identity testing and supplier qualification documentation. Direct procurement from compounders is compressing distributor margins.
- Food Additives:Fortified dairy alternatives and plant-based beverages in South Korea and Japan absorb technical-grade material with relaxed heavy metal specifications compared to pharmaceutical tiers.
- Cosmetics:Mineral complexes for skin barrier formulations represent emerging offtake in Japanese and South Korean cosmetic pipelines, with bioavailability claims driving specification creep toward pharmaceutical-adjacent purity.
Pharmaceuticals holds the largest share; momentum sits with cosmetics as mineral skincare claims gain formulation traction.
Application:
Cost tiers separate clinical prescription channels from mass-market consumer segments, with veterinary applications occupying a distinct pricing band.
- Dietary Supplements:Bone health formulations targeting populations over 65 in Japan, Germany, and Italy drive volume demand. Bioavailability marketing claims favor calcium glycerophosphate over carbonate or citrate alternatives despite elemental calcium disadvantage. Aging demographics sustain replenishment cycles.
- Oral Health:Enamel remineralization products in professional dental channels command premium positioning. Japanese and German dental product manufacturers specify sub-micron particle size distributions for topical application efficacy.
- Animal Feed:Pet nutrition and livestock mineral premixes in India and Brazil absorb technical-grade material with reduced documentation burdens. FSSAI and MAPA regulations govern feed-grade mineral salt specifications.
- Personal Care:South Korean cosmetic pipelines are incorporating calcium mineral complexes into barrier repair serums and overnight masks, diverting supply from traditional nutrition channels.
Dietary Supplements commands volume leadership; Personal Care is climbing the fastest as cosmetic mineralization trends accelerate.
End User:
Customer type determines procurement sophistication, with healthcare providers enforcing vendor qualification protocols that exclude commodity traders.
- Healthcare Providers:Hospital pharmacies and parenteral nutrition compounders in Spain and Italy require sterile-grade material with batch-specific certificates of analysis. EMA GMP Annex 1 compliance mandates isolator technology and environmental monitoring documentation.
- Nutraceutical Companies:Vertically integrated supplement brands in California and Utah control formulation, encapsulation, and packaging in-house, establishing preferred supplier agreements that bypass regional distributors.
- Food Manufacturers:Fortified beverage producers specify technical-grade material with FSSAI or state-level food additive registrations. Documentation requirements trail pharmaceutical tiers but exceed feed-grade thresholds.
- Cosmetic Brands:South Korean and Japanese skincare houses are qualifying mineral suppliers for clean beauty claims, imposing heavy metal and microbial testing beyond traditional cosmetic-grade standards.
Healthcare Providers dominate value capture; Cosmetic Brands are gaining share fastest as mineral skincare expands beyond niche positioning.
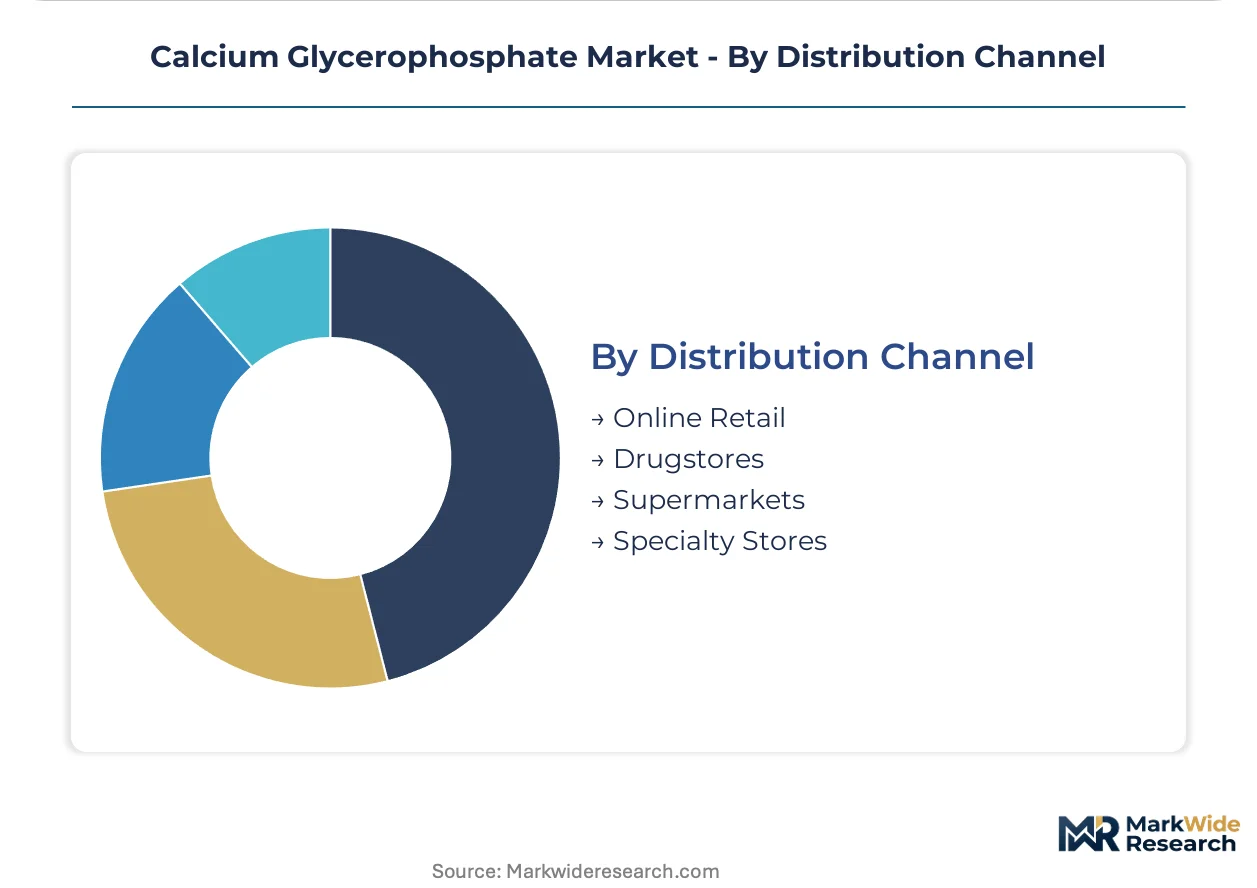
Distribution Channel:
Channel structure reflects buyer sophistication, with institutional procurement consolidating through direct manufacturer relationships while consumer segments fragment across retail formats.
- Drugstores:Pharmacy chains in Germany and Japan stock professional-grade supplements with pharmacist consultation positioning. Regulatory classification as OTC or quasi-drug determines shelf access and promotional restrictions.
- Online Retail:Direct-to-consumer supplement brands in the United States bypass traditional wholesale tiers, compressing margin pools for legacy distributors. Amazon and specialized wellness platforms concentrate volume in standardized formulations.
- Supermarkets:Mass-market fortified foods and basic supplements in European and North American grocery channels compete on price with private label alternatives. Tricalcium phosphate substitution threatens calcium glycerophosphate placement in economy tiers.
- Specialty Stores:Professional supplement retailers and compounding pharmacy suppliers in Italy and France serve practitioner-directed regimens with higher-margin, clinically positioned products.
Drugstores retains the largest share; Online Retail is expanding most quickly as direct procurement reshapes channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical compounders export parenteral-grade calcium glycerophosphate to Italian and Spanish hospital networks under EMA GMP documentation requirements. This trade corridor channels high-margin sterile material through centralized procurement hubs in Milan and Barcelona.
United States
Utah and California nutraceutical manufacturers drive bulk demand for oral-grade material in capsule and tablet formulations. FDA dietary supplement cGMPs enforce identity testing and supplier qualification protocols that filter out undocumented importers. Salt Lake City vertically integrated supplement brands control encapsulation, formulation, and packaging in-house, establishing preferred supplier agreements that bypass regional distributors.
Germany
Injectable compounders in Frankfurt and Hamburg source REACH-registered material for parenteral nutrition applications with residual solvent limits below 50 ppm. ECHA compliance mandates documented supply chain transparency that consolidates market access for registered suppliers. Bavarian sterile processing facilities are retrofitting isolator technology to meet EMA GMP Annex 1 environmental monitoring requirements.
Italy
Milan hospital pharmacies and parenteral nutrition facilities absorb EU-origin pharmaceutical-grade output for sterile compounding. EMA GMP Annex 1 mandates closed-system processing and enhanced environmental monitoring documentation. Emilia-Romagna manufacturing clusters are consolidating supplier bases to partners with pre-validated sterile capabilities.
Japan
Tokyo and Osaka dental product manufacturers specify sub-micron particle size distributions for enamel remineralization formulations. METI oversees quasi-drug classification that determines shelf access and promotional restrictions for professional oral health channels. Kanto region aging populations over 65 sustain replenishment cycles for bone health supplement regimens.
South Korea
Seoul cosmetic pipelines are incorporating calcium mineral complexes into barrier repair serums and overnight masks. MFDS regulates functional cosmetic claims that drive specification creep toward pharmaceutical-adjacent purity thresholds. Busan-Ulsan skincare houses are qualifying mineral suppliers for clean beauty positioning with heavy metal testing beyond traditional cosmetic-grade standards.
Calcium Glycerophosphate Market Vendor Landscape
Listed leaders compete with private specialists across certification-grade tiers, creating a bifurcated structure where public filers scale bulk production while family-held operations dominate premium pharmaceutical channels. The vendor base clusters around three strategic archetypes: European REACH-registered specialists with sterile processing capabilities, North American vertically integrated mineral compounders, and Asian cost-efficient bulk producers serving domestic pharmaceutical formulators. Capacity expansion and backward integration into phosphate rock sourcing represent the dominant competitive moves as feedstock volatility compresses margin predictability.
Among European REACH-registered specialists, SEPPIC exemplifies premium positioning through specialty chemical expertise in nutraceutical channels. American Elements anchors North American supply through in-house production of rare earth and mineral compounds. Global Calcium occupies a position within the cost-efficient bulk tier, serving Asian pharmaceutical formulators with scaled output.
| Leading Market Players |
|---|
| Sri Vyjayanthi Labs |
| Chempol |
| SEPPIC |
| Anmol Chemicals |
| American Elements |
| Penta Manufacturer |
| Global Calcium |
| Jai Radhe Sales |
| Nitika Chemicals |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for pharmaceutical-grade material concentrate pricing power with REACH-registered German and French suppliers, while nutraceutical buyers in Utah and California compress lead times through direct procurement agreements that bypass distributor markups. This inventory-lead time structure reinforces tiered margin capture across certification grades, with sterile processing capabilities commanding premium positioning over oral-grade alternatives.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize feedstock pass-through mechanisms. Pricing stratifies across pharmaceutical, nutraceutical, and food-grade tiers, with USP-NF and EP monograph compliance driving premium-mid-economy differentiation. Cost compression in food additive segments intensifies because tricalcium phosphate substitution threatens volume placement, rendering fortified beverage manufacturers most price-sensitive while parenteral nutrition compounders remain least sensitive due to regulatory lock-in.
Supply Chain Analysis
Phosphate rock sourcing from Morocco and China constitutes the critical upstream chokepoint that constrains margin predictability for neutralization-based producers. Manufacturing concentrates in Germany, France, and India, with sterile compounding facilities in Italy and Spain drawing from EU-origin documentation clusters. Supply chain risk centers on single-source vulnerability for REACH-registered material, as ECHA compliance filters out non-European alternatives. Distribution runs through direct manufacturer relationships with large contract manufacturers, compressing traditional chemical distributor roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are emerging as calcium glycerophosphate specifications fragment across incompatible purity thresholds, with interoperability between pharmaceutical, nutraceutical, and cosmetic grade ecosystems creating winner-take-most dynamics for suppliers mastering multi-certification production trains.
For Market Incumbents: Consolidate sterile processing capabilities through isolator technology investments that satisfy EMA GMP Annex 1 mandates, while backward integration into phosphate rock sourcing mitigates feedstock volatility from Moroccan and Chinese suppliers. SEPPIC and American Elements exemplify defensive positioning through REACH registration maintenance and in-house mineral compound production respectively. For New Entrants and Emerging Players: Personal care mineral complex formulation services represent an underserved white space where South Korean and Japanese cosmetic pipelines demand pharmaceutical-adjacent purity without established supplier relationships. Targeting clean beauty qualification protocols with heavy metal testing capabilities offers the most penetrable entry vector, with technical partnership structures accelerating MFDS compliance timelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because multi-jurisdiction certification timelines extending 18-24 months create durable barriers against commoditization. Acquisition targets should display pre-validated sterile capabilities and existing USP-NF or EP monograph compliance, with the signal to watch being pharmacopeial harmonization between USP-NF and EP specifications that could obsolete non-aligned inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive supply from Moroccan and Chinese sources insulates margin predictability against commodity volatility. |
| Sterile Processing Facility Retrofit | Isolator technology investments satisfy EMA GMP Annex 1 mandates for Italian and Spanish parenteral nutrition compounders. |
| Multi-Certification Production Train | Parallel pharmaceutical, nutraceutical, and cosmetic grade capabilities capture specification creep in South Korean skincare pipelines. |
| Direct Manufacturer Procurement Agreements | Preferred supplier relationships with Utah and California vertically integrated brands bypass distributor margin compression. |
| Clean Beauty Qualification Protocol | Heavy metal and microbial testing beyond cosmetic-grade standards unlocks Japanese and South Korean mineral skincare demand. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with pharmaceutical formulators, nutraceutical procurement leads, sterile compounding facility managers, and cosmetic R&D directors; and secondary validation through FDA cGMP guidance documents, EMA GMP Annex 1 revisions, REACH registration databases, and USP-NF monograph specifications. Bottom-up volume estimates from grade-tier production capacity were triangulated against top-down demand aggregation from end-use application forecasts.
Across the analysis window, the forecasting framework modeled segmentation dimensions including certification grade tier, end-use industry, and regional regulatory cluster complexity. CAGRs were derived from elasticity-adjusted demand projections incorporating aging demographic trajectories in Japan, Germany, and Italy, alongside parenteral nutrition application expansion in Italian and Spanish hospital networks. Forecast inputs included phosphate rock price volatility indices and pharmacopeial harmonization monitoring between USP-NF and EP specifications.
Underlying assumptions cover sustained REACH enforcement in Europe, FDA cGMP dietary supplement rule stability, and MFDS functional cosmetic claim expansion in South Korea, with deviation risk concentrated in feedstock supply disruptions from Moroccan and Chinese phosphate rock sources and regulatory specification drift that could trigger inventory obsolescence. Practitioners should keep alternative scenarios live as pharmacopeial harmonization timelines and sterile processing technology adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Mexico Food Hydrocolloids Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Food Premix Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Polyunsaturated Fatty Acids Market