
 Germany Food Preservatives Market | 2026-2036
Germany Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Food Preservatives Market Foresight
German ready-meal manufacturing is pivoting toward natural preservation systems as consumer skepticism toward synthetic additives deepens. BASF SE leverages its antioxidant R&D pipeline to serve reformulating bakery and meat clients. Corbion NV specializes in fermentation-derived solutions that help processors navigate clean-label transitions. Kerry Group PLC extends its application labs across southern Germany to anchor technical service relationships with mid-tier food manufacturers.
Food preservatives comprise chemical and biological substances added to food matrices to inhibit microbial spoilage, oxidative rancidity, and enzymatic degradation, typically dosed at 0.01% to 0.5% by weight depending on substrate and target pathogen. Their primary commercial purpose is to extend distribution shelf life while maintaining sensory and nutritional integrity under ambient or chilled supply chain conditions. Antimicrobials dominate value contribution in meat processing applications where Listeria control commands premium formulation spending. Natural antioxidants from the acids segment capture the fastest expansion trajectory as beverage and dairy processors replace butylated hydroxyanisole with rosemary and citric extracts. Powder and granule forms retain manufacturing scale advantages in high-throughput bakery and confectionery plants where dosing precision and flowability reduce line contamination risk.
EFSA maintains centralized safety assessments for all novel preservative submissions under EU regulation 1333/2008, while Germany's BfR conducts national exposure evaluations that frequently inform member-state objection procedures. REACH compliance and the EU Green Deal's chemical sustainability targets are forcing reformulation roadmaps that favor bio-based and fermentation-derived preservation pathways. Stakeholders must monitor EFSA re-evaluation schedules for legacy additives and pre-position alternative ingredient portfolios before sunset clauses activate.
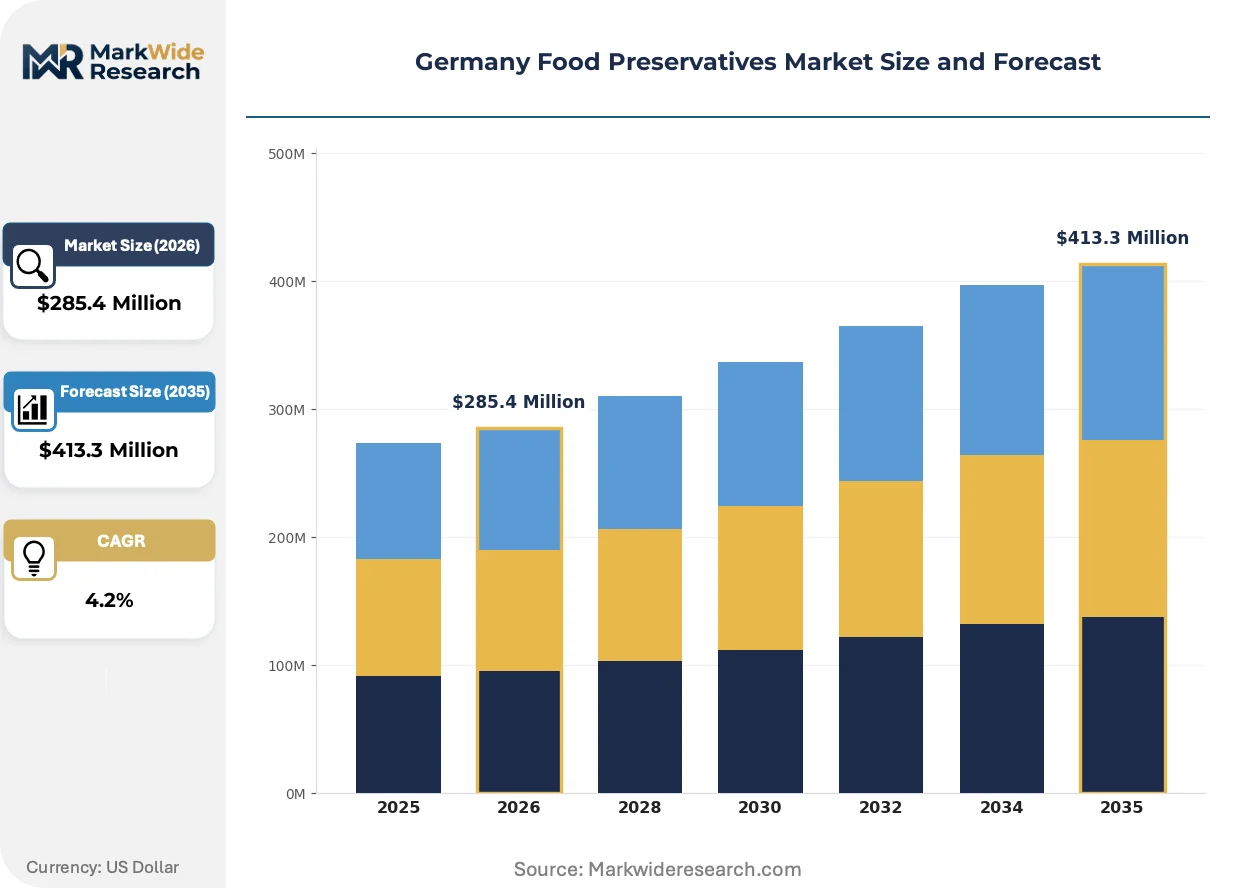
Market Dynamics
EFSA's additive re-evaluation schedule is compressing formulation timelines across German meat and dairy processing, forcing ingredient portfolios to pivot before legacy preservatives face sunset clauses.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Bio-based preservation pathways gain preferential regulatory treatment, accelerating fermentation-derived antioxidant adoption in Bavarian manufacturing corridors.
- Clean-label meat processing:German processors reformulate cured products using natural antimicrobials to meet retailer specification sheets banning synthetic nitrite declarations.
- Ready-meal shelf-life extension:Chilled prepared food manufacturers invest in hurdle-technology combinations to replace chemical preservatives without compromising distribution reach.
Market Restraints
- Natural extract input volatility:Rosemary and green tea extract prices fluctuate with Mediterranean harvest yields, compressing margin predictability for clean-label formulators.
- REACH compliance costs:Novel bio-based preservatives face extended toxicological evaluation timelines that delay commercial launch by multiple regulatory cycles.
- Technical substitution limits:Natural antimicrobials fail to match synthetic benzoate performance in high-pH beverage matrices, restricting reformulation scope.
Strategic Opportunities
- Baden-Württemberg dairy clusters:Fermentation-derived protective cultures remain underdeployed in yogurt and fresh cheese applications relative to northern German meat processing adoption rates.
- Bakery mold-control innovation:Sourdough-derived antifungal peptides offer clean-label positioning for industrial bread manufacturers seeking propionate replacement.
- Carbon-accounting integration:EU Green Deal scope-three reporting requirements create premium positioning for preservatives with verified bio-based carbon content.
Industry Challenges
- Clean-label formulation expertise scarcity:Food technologists skilled in hurdle-technology design command premium compensation, constraining mid-tier manufacturer reformulation capacity.
- Dual-label inventory complexity:Parallel synthetic and natural preservative stockkeeping units multiply warehousing and changeover costs for contract manufacturers serving multiple retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Food Preservatives Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $413.3 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Antimicrobials, Acids, Enzymes, Emulsifiers, Stabilizers Application: Bakery, Meat Processing, Dairy Products, Beverages, Confectionery, Ready Meals End User: Food Manufacturers, Catering Services, Food Retailers, Wholesale Distributors, Food Packaging Companies Form: Liquid, Powder, Granules, Crystals, Gel, Oil |
| Companies Covered | Koninklijke DSM NV, DuPont de Nemours Inc., Corbion NV, BASF SE, Barentz, Cargill Incorporated, Kerry Group PLC, Archer Daniels Midland Company, Kemin Industries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Food Preservatives Market Shifts & Advancements
Preservation technology is bifurcating between precision-fermentation biologics and plant-extract standardization, with German processors piloting both tracks to hedge regulatory uncertainty.
High-pressure processing equipment is converging with natural antimicrobial coatings to create non-thermal preservation systems for ready-to-eat meats. Bavarian processors are deploying these hybrid lines at pilot scale. This convergence is compressing the viable price premium for clean-label products toward mass-market accessibility.
EFSA's systematic re-evaluation of legacy additives under EU regulation 1333/2008 is narrowing the approved substance list for synthetic antioxidants. German bakery manufacturers face reformulation deadlines for butylated hydroxytoluene replacement. The acids segment is capturing displaced volume through accelerated citric and ascorbic extract approvals.
Retail specification sheets now mandate preservative-free declarations for premium private-label tiers. Discounters Aldi and Lidl are propagating these requirements into mid-market product lines. Southern German co-manufacturers report compressed switching cycles as retail buyers consolidate supplier panels around dual-capability formulators.
Germany Food Preservatives Market Segmentation
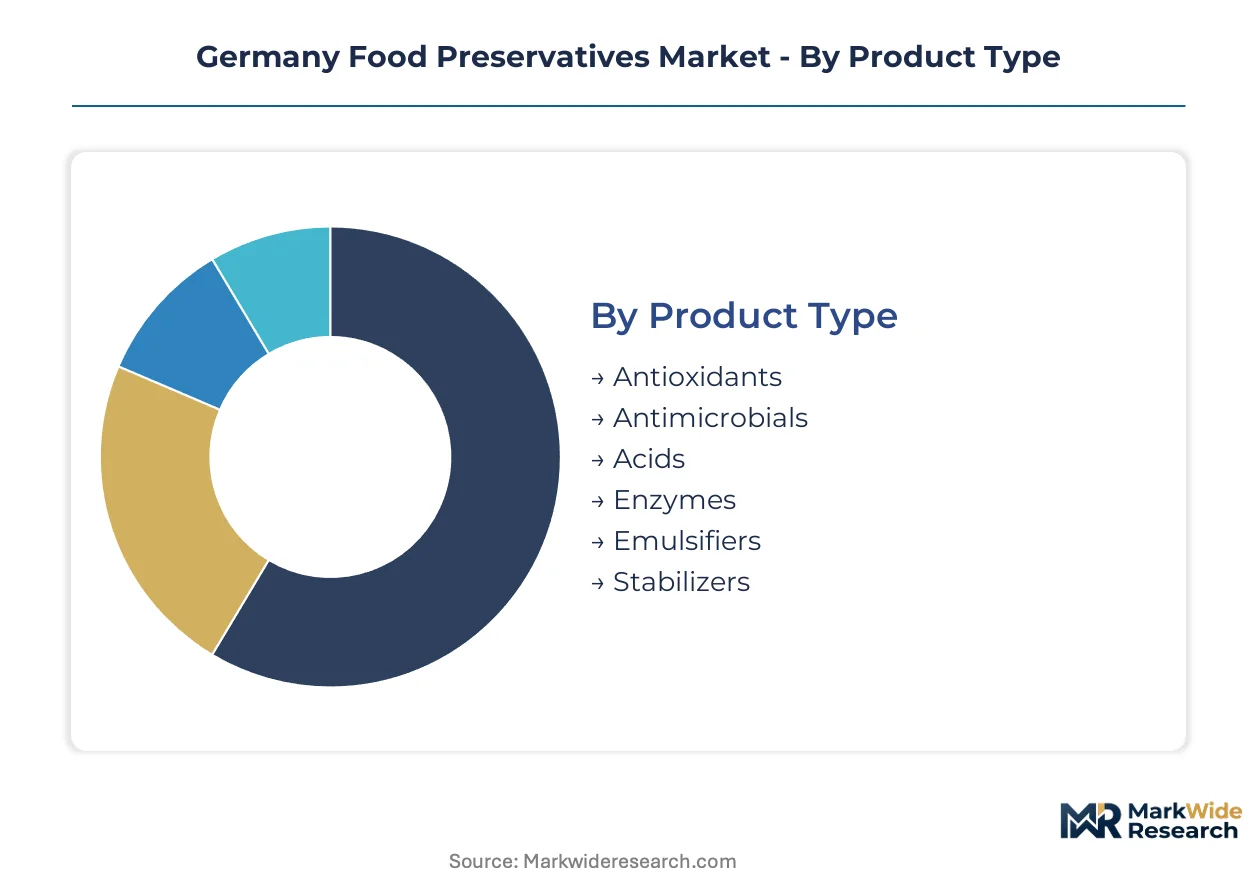
German food processors select preservatives based on substrate compatibility, regulatory clearance timelines, and clean-label positioning requirements. Procurement teams weight technical performance against EFSA re-evaluation risks when building ingredient portfolios.
Product Type:
Formulation cost tiers drive sourcing decisions, with premium natural extracts commanding multiples over synthetic benchmarks.
- Antioxidants:These compounds interrupt free-radical chain reactions in lipid substrates. Bavarian meat processors deploy rosemary-derived and tocopherol-based systems to replace butylated hydroxytoluene ahead of EFSA sunset clauses.
- Antimicrobials:Inhibit bacterial and fungal propagation through membrane disruption or metabolic interference. Clean-label cured meat manufacturing in northern Germany concentrates demand for fermentation-derived protective cultures as synthetic nitrite alternatives.
- Acids:pH reduction and chelation mechanisms extend shelf life in high-moisture applications. Citric and ascorbic variants displace synthetic options in beverage processing.
- Enzymes:Catalytic proteins targeting specific spoilage pathways. Limited penetration outside dairy applications due to temperature stability constraints.
- Emulsifiers:Surface-active agents preserving texture and preventing phase separation. Bakery and confectionery sectors dominate offtake.
- Stabilizers:Hydrocolloid and protein matrices maintaining structural integrity. Ready-meal manufacturers leverage these for freeze-thaw resistance.
Volume sits with Antimicrobials; growth tilts toward Acids.
Application:
End-use maturity varies sharply, with established meat processing channels contrasting emerging ready-meal preservation requirements.
- Meat Processing:Listeria control and color retention dominate formulation priorities. Cured and fermented product lines in Lower Saxony drive antimicrobial spending.
- Ready Meals:Chilled prepared foods require hurdle-technology combinations to achieve distribution shelf life without synthetic declarations. Technical complexity elevates formulation service intensity.
- Bakery:Mold inhibition and anti-staling systems preserve sensory attributes. Propionate replacement initiatives accelerate natural antifungal adoption.
- Dairy Products:Yogurt and fresh cheese applications favor protective cultures over chemical preservation. Baden-Württemberg clusters show underdeployment relative to meat sector adoption rates.
- Beverages:High-pH matrices limit natural antimicrobial efficacy, constraining reformulation scope in soft drink and juice segments.
- Confectionery:Oxidative rancidity prevention in fat-containing products. Lower preservatory intensity versus meat or dairy categories.
Revenue concentrates in Meat Processing; expansion accelerates fastest in Ready Meals.
End User:
Customer scale and technical capability determine service model differentiation between commodity supply and co-development partnerships.
- Food Manufacturers:Integrated production facilities with in-house R&D capabilities. Direct technical relationships with ingredient suppliers enable rapid reformulation cycles.
- Food Retailers:Private-label specification power shapes preservative acceptance criteria. Aldi and Lidl mandate clean-label declarations across premium and mid-market tiers.
- Catering Services:Central kitchen operations with shorter distribution chains and reduced preservation intensity versus packaged goods.
- Wholesale Distributors:Inventory holding functions with limited formulation influence. Price-sensitive procurement of commodity preservatives.
- Food Packaging Companies:Emerging active packaging integration requiring antimicrobial coating compatibility.
Procurement authority rests with Food Manufacturers; specification power is migrating toward Food Retailers.
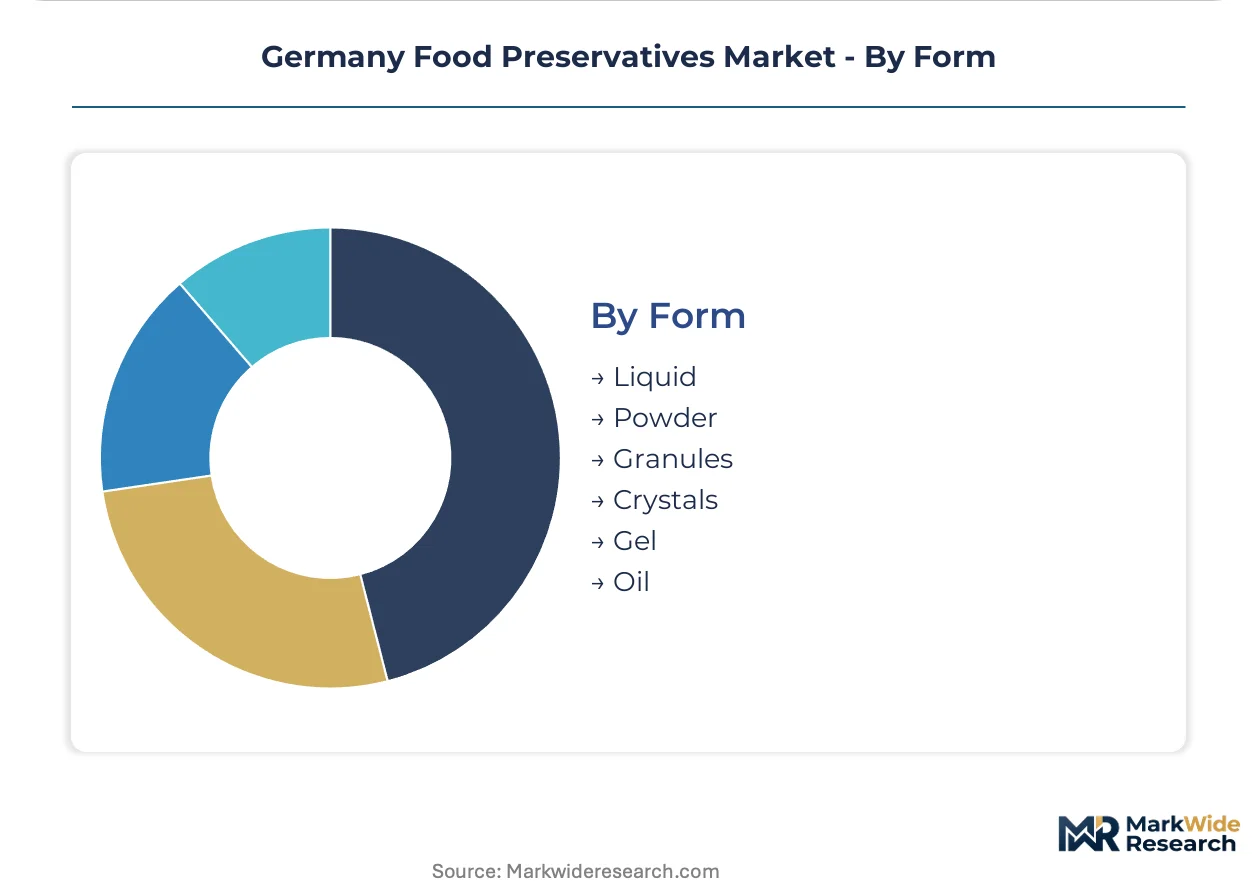
Form:
Manufacturing throughput requirements and dosing precision dictate physical format selection across plant configurations.
- Powder:Free-flowing particulates enabling precise gravimetric dosing. High-throughput bakery and confectionery lines favor this format for reduced contamination risk.
- Liquid:Homogeneous solutions facilitating spray application and uniform distribution. Meat brine injection systems prefer liquid antimicrobial delivery.
- Granules:Agglomerated particles balancing flowability with reduced dust generation. Intermediate handling characteristics between powder and crystal forms.
- Crystals:Defined particle size supporting dissolution control. Acid applications in beverage processing favor crystalline citric and ascorbic forms.
- Gel:Viscous matrices for surface coating and localized antimicrobial deployment. Limited scale outside specialty meat applications.
- Oil:Lipid-soluble antioxidant carriers for fat-rich substrates. Bakery and confectionery fat preservation uses tocopherol-in-oil systems.
Throughput leadership belongs to Powder; flexibility advantages accrue to Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's food manufacturing corridor concentrates preservative demand through tax-advantaged industrial zones near Munich and Nuremberg. EFSA regulatory pressure and retailer clean-label mandates reshape procurement patterns across German sub-regions.
Bavaria
Meat processing and ready-meal manufacturing dominate preservant consumption in the Munich-Nuremberg corridor. BfR exposure evaluations inform local reformulation timelines ahead of EFSA sunset clauses. Industrial bakeries in Upper Bavaria pilot sourdough-derived antifungal systems to replace propionates.
North Rhine-Westphalia
Dairy and beverage processors drive acid-segment demand for pH management and shelf-life extension. REACH compliance costs delay novel bio-based preservative launches from regional chemical clusters. Cologne-based co-manufacturers maintain dual-label inventories to serve Aldi and Lidl specification tiers.
Baden-Württemberg
Protective culture adoption lags meat-sector penetration in yogurt and fresh cheese applications. EU Green Deal scope-three reporting requirements incentivize bio-based carbon verification for Stuttgart-area dairy processors. Freiburg fermentation startups supply protective cultures to regional cheese makers.
Lower Saxony
Cured meat production in the Oldenburg region commands premium antimicrobial spending for Listeria control. EFSA re-evaluation schedules compress formulation timelines for synthetic nitrite alternatives. Wolfsburg-area meat processors integrate high-pressure processing with natural antimicrobial coatings.
Hesse
Frankfurt's logistics hub distributes preservatives to central German food manufacturers. FrankfurtRheinMain's chemical sector supplies antioxidant precursors to bakery and confectionery clients. Darmstadt technical service centers support hurdle-technology design for ready-meal reformulation.
Germany Food Preservatives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates dominating antioxidant supply and fermentation-derived specialists capturing clean-label growth. The vendor base organizes around three strategic archetypes: diversified chemical majors with R&D pipelines, fermentation-focused biotech specialists, and application-service-oriented ingredient distributors. M&A activity concentrates on acquiring fermentation capabilities and expanding technical service footprints. Geographic expansion into southern German manufacturing corridors represents the second dominant competitive vector.
Among Dutch- and Irish-based specialists, Corbion NV and Kerry Group PLC exemplify the fermentation-derived and application-service archetypes respectively. BASF SE anchors the diversified chemical major tier with antioxidant R&D infrastructure. These three occupy positions spanning the value chain from raw material synthesis to formulation technical service.
| Leading Market Players |
|---|
| Koninklijke DSM NV |
| DuPont de Nemours Inc. |
| Corbion NV |
| BASF SE |
| Barentz |
| Cargill Incorporated |
| Kerry Group PLC |
| Archer Daniels Midland Company |
| Kemin Industries Inc. |
| Others |
Supply & Pricing Matrix
Rosemary extract and fermentation-derived input costs cascade through three pricing tiers before reaching Bavarian meat processors and Baden-Württemberg dairy manufacturers. Mediterranean harvest volatility and bio-based carbon certification premiums stratify procurement budgets across clean-label and conventional formulation lines.
Pricing Analysis
Short lead-time premiums command substantial markups as EFSA re-evaluation deadlines compress reformulation windows for German processors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from natural extract input volatility squeezing margin predictability for clean-label formulators. Mid-tier manufacturers exhibit highest price sensitivity due to dual-label inventory burdens, while integrated majors absorb premiums through captive antioxidant R&D pipelines.
Supply Chain Analysis
Regional distribution centers in FrankfurtRheinMain and Munich-Nuremberg operate hub-and-spoke patterns feeding southern German manufacturing corridors. Supply concentrates in Netherlands, Ireland, and domestic German chemical clusters for fermentation-derived and synthetic antioxidant feedstocks. Raw material dependencies include rosemary biomass, citric acid precursors, and protective culture fermentation media. Single-source vulnerability in Mediterranean herb extracts threatens continuity. Distribution runs through B2B ingredient distributors with technical service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
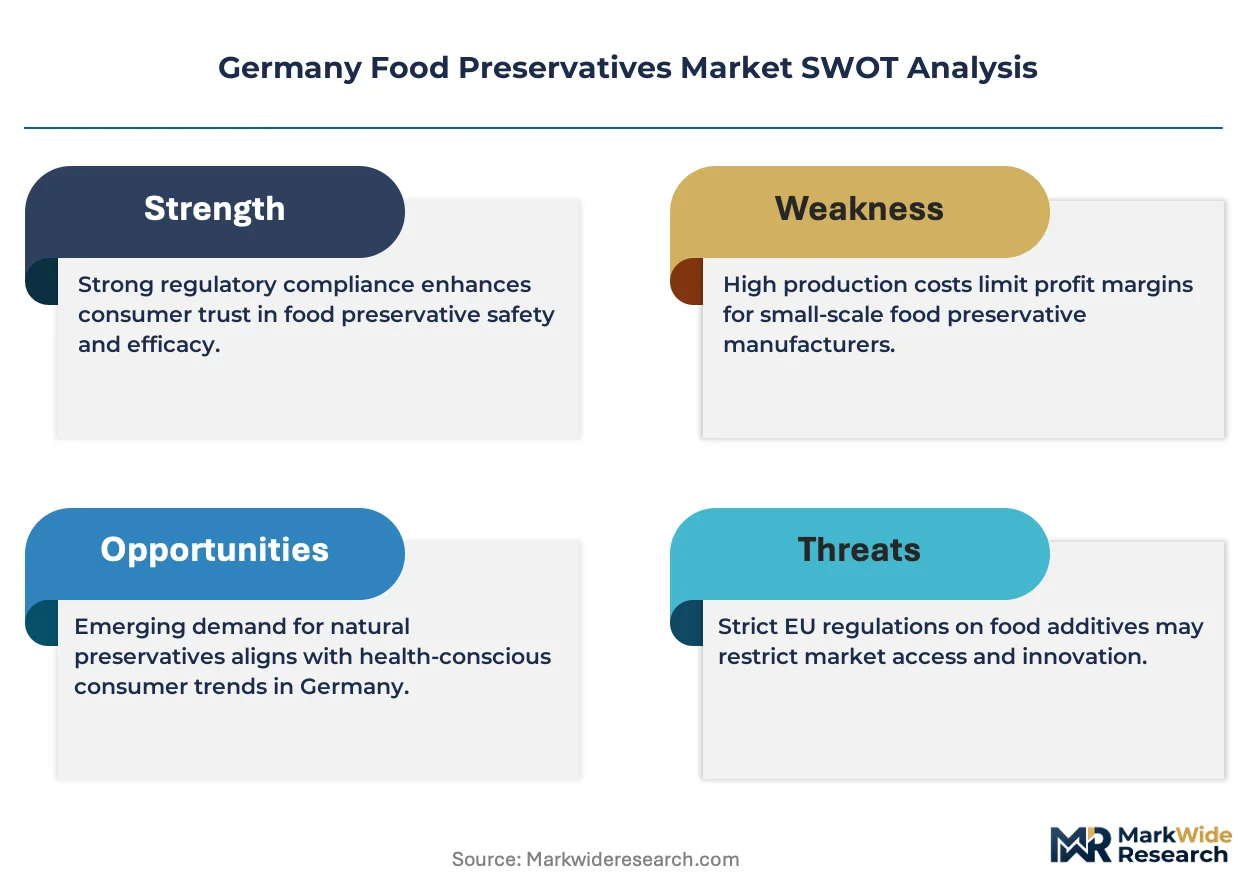
Vertical integration into fermentation capacity and upstream botanical extraction represents the decisive competitive race as bio-based preservation pathways gain regulatory preference.
For Market Incumbents: Cement formulation service relationships through expanded application labs across Bavaria and Baden-Württemberg. Acquire protective culture fermentation capabilities before sunset clauses activate for legacy synthetic portfolios. Channel control through co-development partnerships with Aldi and Lidl specification teams anchors volume commitments against emerging biotech specialists.
For New Entrants and Emerging Players: Capture underdeployed protective culture opportunities in Baden-Württemberg yogurt and fresh cheese applications relative to meat-sector penetration rates. Freiburg fermentation startups demonstrate viable regional supply models. Direct technical engagement with mid-tier dairy processors lacking in-house hurdle-technology expertise offers the most penetrable entry vector.
For Investors and Strategic Acquirers: EFSA additive re-evaluation announcements are the leading indicator that reformulation service demand will spike across German processor portfolios. Five-to-ten year viability favors fermentation-derived specialists with verified bio-based carbon credentials and established BfR exposure evaluation track records. Acquisition targets should show technical service density in southern German manufacturing corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captures EU Green Deal preferential regulatory treatment for bio-based preservation pathways. |
| Backward Integration into Botanical Extraction | Secures rosemary and green tea supply chains against Mediterranean harvest yield volatility. |
| Application Laboratory Network Extension | Anchors technical service relationships with mid-tier manufacturers in Bavarian corridor. |
| Protective Culture Portfolio Acquisition | Accelerates clean-label positioning ahead of synthetic nitrite sunset clauses. |
| Carbon-Accounting Certification Program | Enables premium positioning under EU Green Deal scope-three reporting requirements. |
Research Methodology
Multi-period observation of EFSA re-evaluation schedules, BfR exposure evaluations, and retail specification sheet evolution anchored the trend analysis, supplemented by interviews with formulation technologists at meat and dairy processors, procurement leads at ingredient distributors, regulatory affairs directors, and technical service managers. Secondary validation drew from EU regulation 1333/2008 filings, REACH compliance databases, BfR opinion archives, and customs trade records for rosemary extract and fermentation input flows. Bottom-up segment sizing triangulated against top-down manufacturing value-add estimates.
Segment-weighting approaches distributed value across product type, application, end user, and physical form dimensions, with additional granularity for clean-label versus conventional positioning. CAGRs were derived from regression-adjusted trend extrapolation across the analysis window, incorporating EFSA sunset clause timelines and EU Green Deal implementation pacing as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA re-evaluation acceleration, Mediterranean climate patterns affecting botanical extract yields, and REACH toxicological evaluation timeline extensions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Food Can Coatings Market