
 China Food Hydrocolloids Market | 2026-2036
China Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
China Food Hydrocolloids Market Outlook
China's dual carbon goals is realigning procurement priorities across the food hydrocolloids supply chain, pushing manufacturers toward lower-emission extraction and processing methods. Cargill Inc leverages its global supply network to secure consistent raw material flows into Chinese processing facilities. Zhenpai Hydrocolloids Co. Ltd anchors its competitive position through deep specialization in domestically sourced agar and seaweed-derived colloids. Hebei Xinhe Biochemical Co Ltd dominates northern China's hydrocolloid manufacturing corridor with integrated fermentation and refining capabilities.
Food hydrocolloids are water-soluble biopolymers—typically polysaccharides or proteins—that hydrate in aqueous systems to form viscous solutions, gels, or stabilizing matrices, with functional parameters including gel strength measured in Bloom grams for gelatin and viscosity ranges from 500 to 2,500 cP for xanthan gum solutions. These compounds serve primarily as texture modifiers, stabilizers, and water-binding agents in processed food systems where shelf stability and mouthfeel consistency determine commercial viability. Gelatin maintains the largest revenue share among product types due to entrenched demand from confectionery and pharmaceutical capsule sectors, though pectin exhibits the fastest structural growth trajectory driven by clean-label formulation mandates in premium dairy alternatives. Plant-based sources command expanding margin pools as food manufacturers reformulate away from animal-derived stabilizers to meet retailer sustainability scorecards and consumer preference shifts.
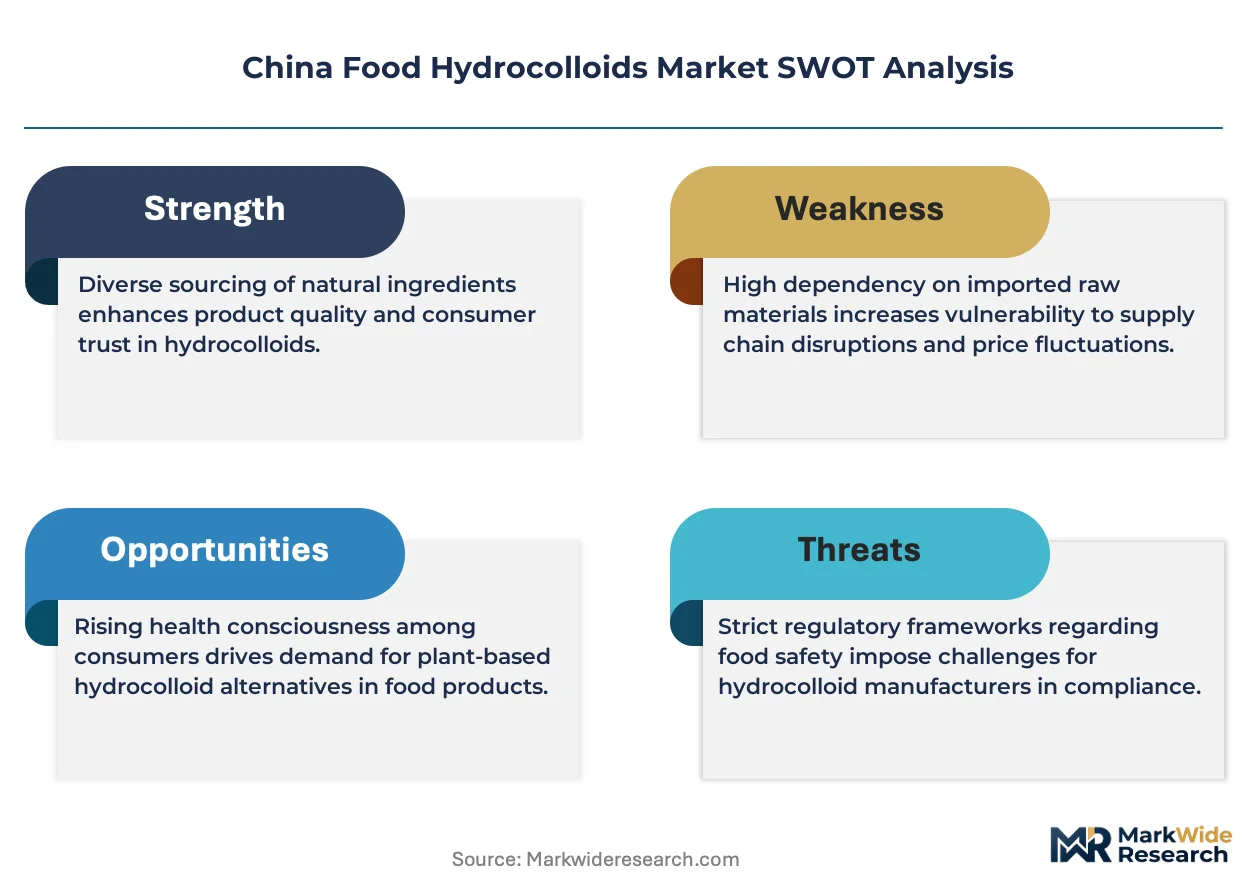
SAMR enforces GB standards for food additive purity and labeling transparency, while NMPA oversees hydrocolloid use in functional food and nutraceutical applications, creating a dual-track compliance environment that elevates entry costs for smaller domestic producers. MIIT's industrial policy directives incentivize microbial fermentation capacity expansion, directly shaping capital allocation toward xanthan gum and pullulan production platforms. Stakeholders must monitor how China's evolving national food safety standards integrate with carbon intensity benchmarks, as this convergence will determine which production technologies and source materials retain market access over the coming decade.
Market Dynamics
China's dual carbon goals are compressing timelines for decarbonizing hydrocolloid extraction and fermentation processes, forcing processors to reengineer energy-intensive refining operations or face exclusion from state procurement channels.
Growth Catalysts
- Clean-label mandates:SAMR's tightening GB standards on additive transparency are compelling dairy alternative manufacturers to replace synthetic stabilizers with pectin and agar in premium formulations.
- Fermentation capacity expansion:MIIT's industrial policy directives are channeling capital toward microbial platforms for xanthan gum and pullulan production, lowering import dependency.
- Coastal manufacturing concentration:Demand clustering around Shanghai and Guangdong province is creating specialized logistics infrastructure that reduces inland distribution costs for hydrocolloid suppliers.
Market Restraints
- Seaweed supply volatility:Weather-dependent harvests of kelp and red algae in Fujian and Shandong provinces create input cost instability for agar and carrageenan processors.
- Dual-track compliance burden:Parallel SAMR and NMPA oversight for food additives versus functional food applications elevates registration costs and extends time-to-market for smaller domestic producers.
- Animal-derived stabilizer lock-in:Confectionery and pharmaceutical capsule sectors maintain entrenched gelatin specifications that resist plant-based substitution despite sustainability pressures.
Strategic Opportunities
- Western province penetration:Underdeveloped hydrocolloid processing infrastructure in Sichuan and Chongqing offers first-mover advantages for regional distribution hubs serving interior food manufacturers.
- Carbon-intensity benchmarking:Emerging MEE protocols linking production emissions data to market access are creating premium positioning for low-carbon fermentation-derived colloids.
- Precision fermentation convergence:Novel microbial strain engineering is enabling customized hydrocolloid functionality profiles that command margin premiums in clean-label personal care crossovers.
Industry Challenges
- Skilled fermentation technician scarcity:Microbial hydrocolloid production requires specialized bioprocess engineering expertise that outpaces vocational training pipeline output in northern manufacturing corridors.
- Legacy equipment retrofit complexity:Existing thermal extraction installations face costly upgrades to meet tightening MEE emissions standards without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Hydrocolloids Market |
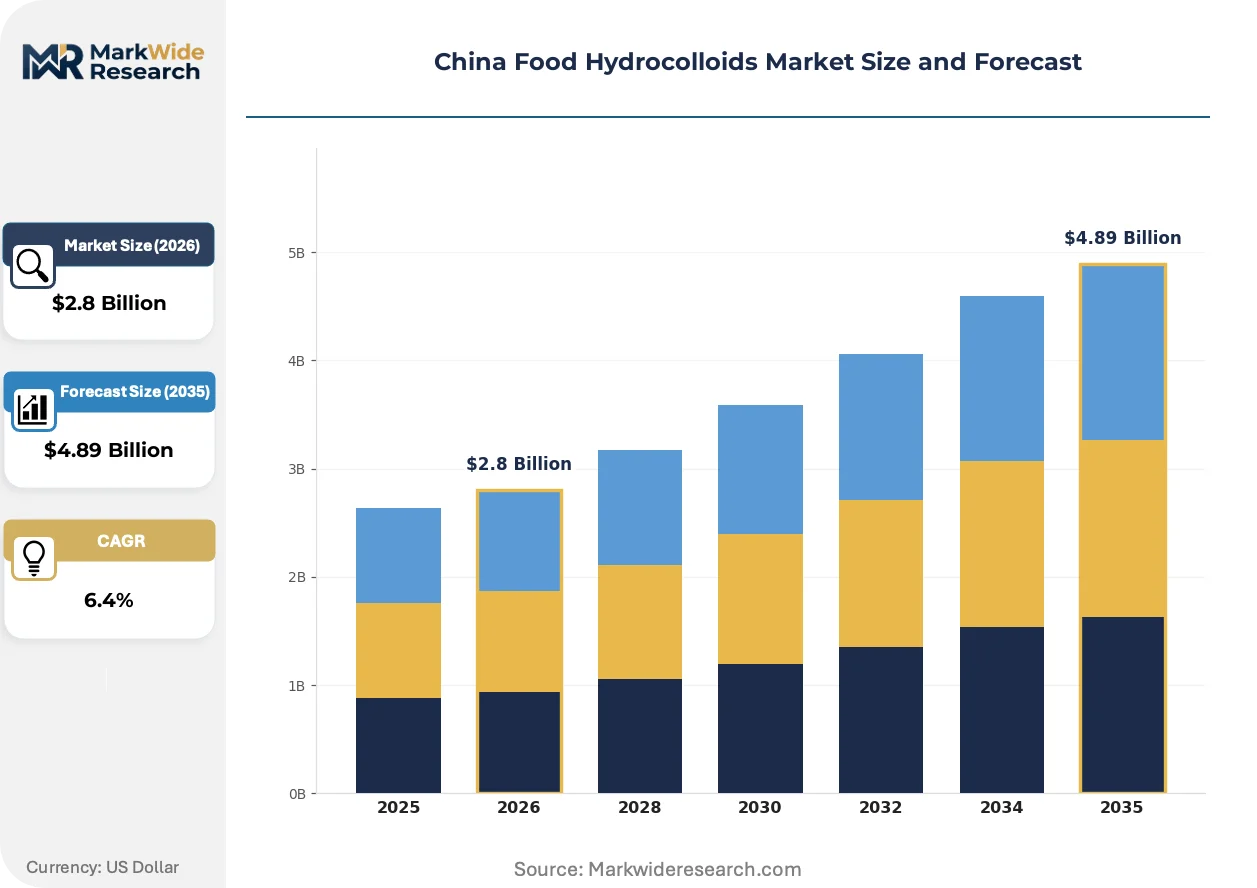
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Agar, Xanthan Gum, Pectin Application: Dairy Products, Bakery, Sauces, Beverages Source: Plant-Based, Animal-Based, Synthetic, Microbial End User: Food Manufacturers, Restaurants, Retailers, Consumers |
| Companies Covered | Cargill Inc, Ashland Global Holdings Inc, Zhenpai Hydrocolloids Co. Ltd, Koninklijke DSM NV, Behn Meyer Deutschland Holding AG & Co. KG, Hebei Xinhe Biochemical Co Ltd, Archer Daniels Midland Co, Rousselot (M) SDN. BHD., CP Kelco US Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Hydrocolloids Market Strategic Shifts
Processing technology and procurement logic are simultaneously transforming how hydrocolloid suppliers capture value, with carbon accountability now embedded in commercial specifications rather than treated as peripheral certification.
Precision fermentation for customized polysaccharide structures is converging with AI-driven strain optimization to reduce development cycles for texture-targeted hydrocolloids. Clean-label dairy alternative manufacturers in Zhejiang and Jiangsu are piloting these platforms at commercial scale. This convergence is compressing R&D timelines that previously required 18-24 months into 8-12 month windows, enabling faster response to retailer sustainability scorecards.
SAMR's evolving GB standards for food additive purity and carbon disclosure are mandating supply chain traceability that exceeds current industry data infrastructure. Processors must now document energy consumption per kilogram of finished hydrocolloid to maintain market access. Northern China's integrated fermentation facilities are responding fastest due to existing utility metering systems, while smaller coastal extractors face compliance gaps.
Direct procurement relationships between hydrocolloid processors and dairy alternative brands are displacing traditional distributor intermediaries in coastal manufacturing clusters. Buyers in Shanghai and Guangdong are consolidating vendor lists to three-to-five preferred suppliers with verified carbon credentials. This consolidation is most visible in premium oat milk and almond yogurt segments where texture consistency failures carry immediate shelf consequences.
China Food Hydrocolloids Market Segmentation
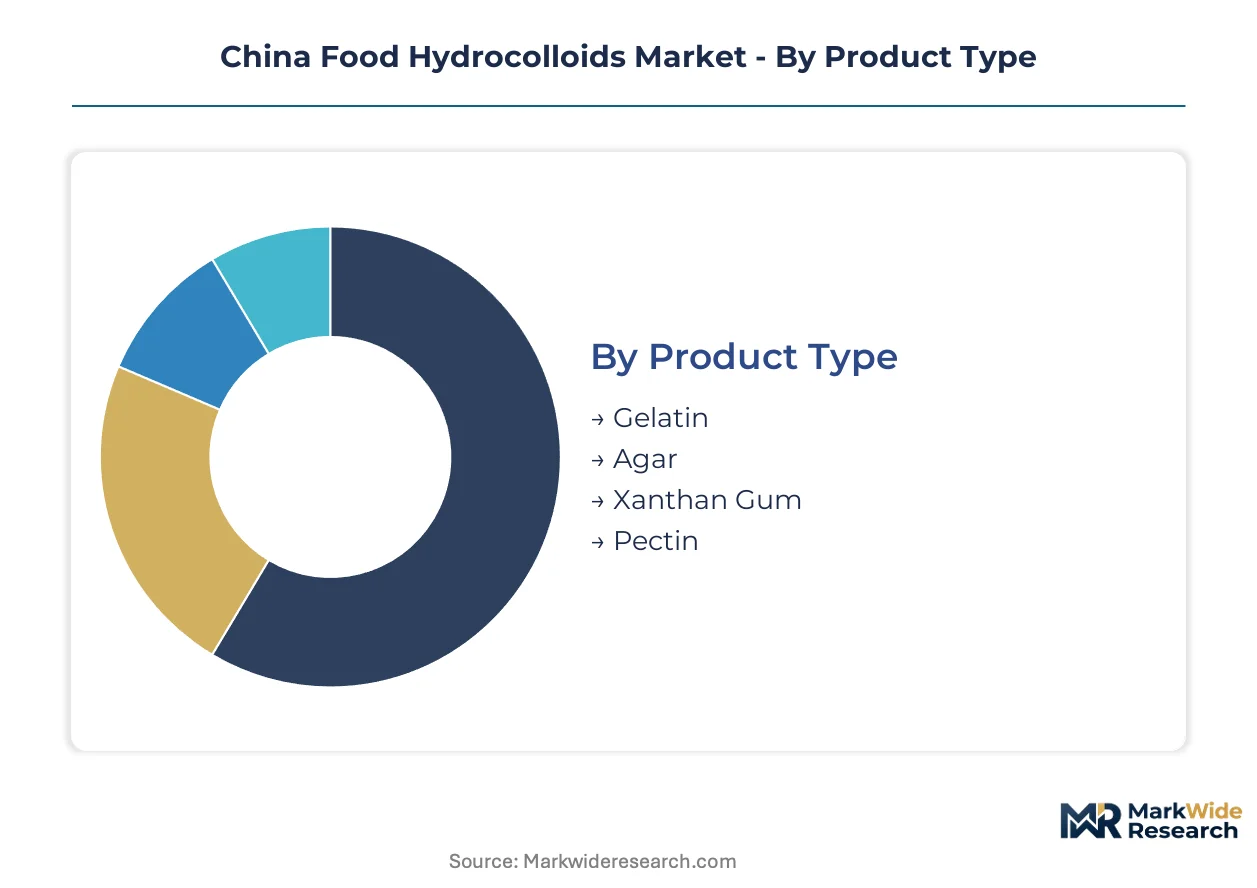
China's food hydrocolloids market fragments along functional performance requirements and regulatory compliance pathways. Each segmentation dimension reveals distinct procurement priorities shaped by SAMR's GB standards and coastal manufacturing cluster demands.
Product Type:
Supply concentration in northern China's fermentation corridors and Fujian's seaweed processing zones directly shapes competitive positioning across hydrocolloid categories.
- Gelatin:Derived from collagen hydrolysis of porcine and bovine sources with Bloom strength specifications ranging from 50 to 300 grams. Pharmaceutical capsule manufacturers in Jiangsu province and confectionery processors in Guangdong anchor procurement volumes despite carbon-intensity scrutiny under MEE protocols.
- Xanthan Gum:Microbial exopolysaccharide produced via Xanthomonas campestris fermentation achieving viscosity of 500-2,500 cP in solution. Hebei's integrated fermentation facilities supply dairy alternative formulators in Shanghai seeking clean-label stabilizers with verified low-carbon credentials.
- Agar:Red algae extract from Gelidium and Gracilaria species with gel strength dependent on harvest seasonality in Shandong waters.
- Pectin:Citrus and apple peel-derived polygalacturonan gaining traction among premium plant-based yogurt brands in Zhejiang.
Today's leader: Gelatin. Tomorrow's challenger: Xanthan gum.
Application:
Cost tier stratification separates commodity-grade hydrocolloid deployments from premium functional formulations targeting retailer sustainability scorecards.
- Dairy Products:Plant-based milk and yogurt applications demand hydrocolloid systems combining mouthfeel replication with clean-label positioning. Oat milk processors in Jiangsu and almond yogurt manufacturers in Guangdong specify pectin-agar blends to meet SAMR's tightening additive transparency mandates.
- Bakery:Gluten-free bread and pastry segments require hydrocolloid matrices for moisture retention and crumb structure. Xanthan gum dominates this application due to freeze-thaw stability and compatibility with high-speed production lines in Shanghai's industrial baking corridor.
- Sauces:Emulsion stabilization in salad dressings and condiments relies on xanthan-guar synergies for shear-thinning rheology.
- Beverages:Pulp suspension and mouthfeel modulation in juice and functional drinks drives agar and pectin uptake.
Dairy applications command premium pricing. Bakery volumes scale fastest.
Source:
Volume concentration in coastal manufacturing clusters is accelerating procurement shifts toward domestically available raw material streams.
- Plant-Based:Seaweed-derived agar and citrus-extracted pectin align with clean-label mandates and dual carbon compliance. Fujian's kelp harvesters and Sichuan's citrus processors supply hydrocolloid extractors serving Zhejiang's dairy alternative brands.
- Animal-Based:Porcine and bovine gelatin retains entrenched positions in pharmaceutical and confectionery specifications despite sustainability pressures. Northern China's rendering infrastructure and Shandong's gelatin refineries maintain cost advantages through backward integration into slaughterhouse byproduct streams.
- Synthetic:Chemically modified cellulose derivatives face declining preference as SAMR's GB standards tighten disclosure requirements.
- Microbial:Xanthan gum and pullulan from controlled fermentation offer reproducible quality and traceable carbon footprints.
Plant-based sources lead positioning. Microbial platforms gain share fastest.
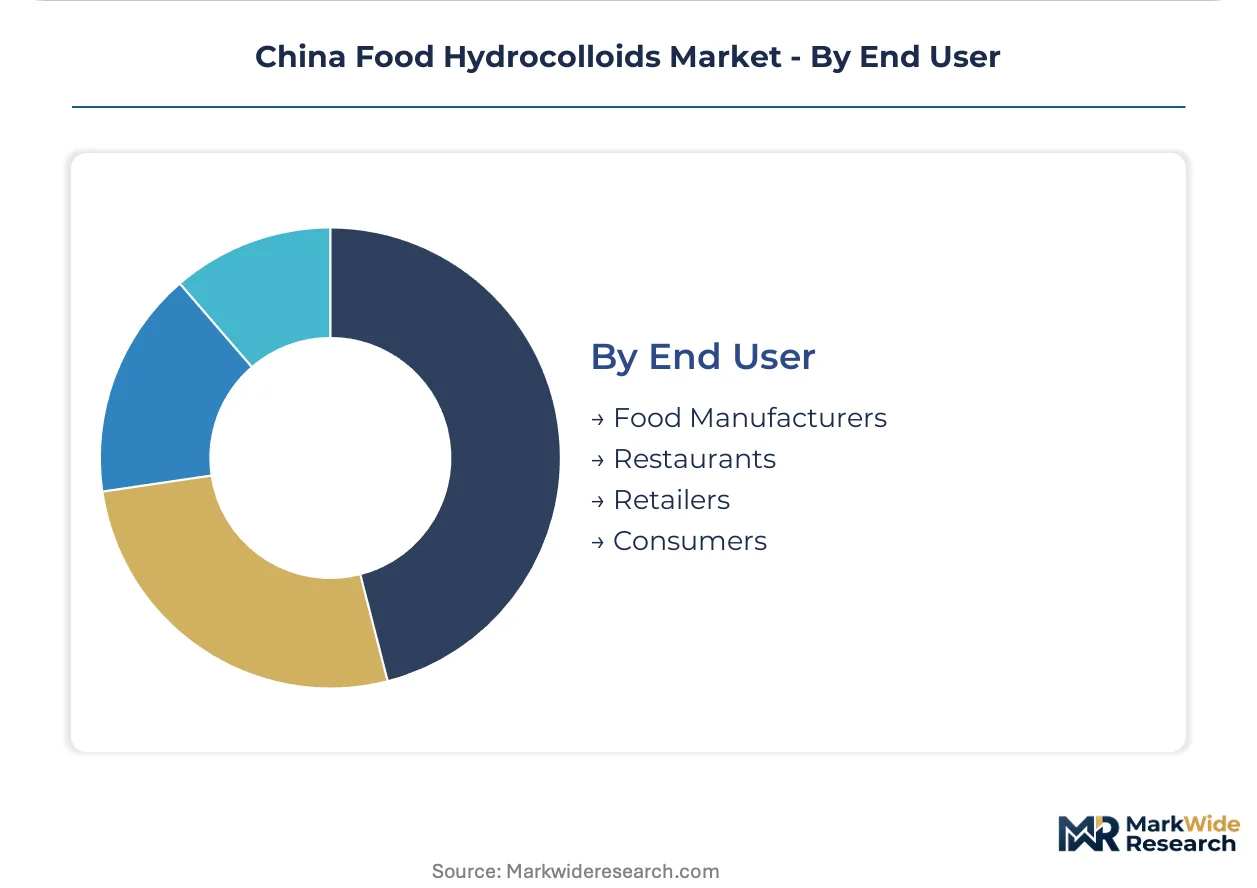
End User:
Customer type determines specification stringency, with direct processor relationships displacing distributor intermediaries in coastal clusters.
- Food Manufacturers:Integrated dairy, bakery, and beverage producers in Shanghai and Guangdong provinces consolidate vendor lists to three-to-five preferred hydrocolloid suppliers with verified carbon credentials and batch-to-batch consistency guarantees.
- Restaurants:Central kitchen operations and chain restaurant groups in Beijing and Shenzhen specify hydrocolloid systems for sauce consistency and dessert texture standardization across outlet networks.
- Retailers:Private-label food brands under supermarket banners in Jiangsu and Zhejiang are specifying clean-label hydrocolloid formulations to differentiate shelf positioning.
- Consumers:Direct hydrocolloid sales remain marginal, concentrated in home baking enthusiasts and specialty diet adherents.
Food manufacturers dominate procurement scale. Retailer private-label represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's food hydrocolloids industry traces its modern scaling to the 1990s fermentation corridor buildout in Hebei and Shandong provinces, where state-directed investment established microbial polysaccharide capacity that now supplies coastal dairy alternative manufacturers.
Yangtze River Delta
Oat milk and almond yogurt processors in Jiangsu and Zhejiang drive premium pectin and agar procurement. SAMR's GB standards on additive transparency compel reformulation away from synthetic stabilizers. Shanghai's integrated logistics hubs enable just-in-time delivery to dairy alternative production lines with verified carbon credentials.
Pearl River Delta
Guangdong's confectionery and beverage clusters sustain entrenched gelatin demand despite sustainability pressures. MIIT's industrial policy directs capital toward microbial fermentation platforms to reduce import dependency. Shenzhen's central kitchen networks specify hydrocolloid systems for sauce consistency standardization across outlet chains.
Beijing-Tianjin-Hebei
Pharmaceutical capsule manufacturers in Hebei anchor bovine and porcine gelatin procurement volumes. MEE protocols linking emissions data to market access favor northern China's integrated fermentation facilities with existing utility metering infrastructure. Tianjin's port infrastructure supports raw material inflows for hydrocolloid refineries.
Shandong Peninsula
Kelp and red algae harvesters in Qingdao and Yantai supply agar processors with weather-dependent input streams. Dual carbon goals compress timelines for decarbonizing seaweed extraction operations. Weihai's gelatin refineries maintain cost advantages through backward integration into slaughterhouse byproduct networks.
Sichuan-Chongqing
Underdeveloped hydrocolloid processing infrastructure creates first-mover opportunities for regional distribution hubs serving interior food manufacturers. Citrus peel waste streams from Sichuan's fruit processing sector feed emerging pectin extraction capacity. Chongqing's expanding dairy alternative production base demands localized stabilizer supply chains.
China Food Hydrocolloids Market Competitive Environment
Premium-margin players sit above commodity-margin players across carbon-credential and clean-label certification dimensions. The vendor base organizes into three tiers: multinational traders with global raw material networks, integrated domestic fermenters with northern corridor infrastructure, and coastal extractors specializing in seaweed-derived colloids. Consolidation pressures favor players with verified low-carbon production platforms as MEE protocols tighten market access requirements. Dominant competitive moves include direct procurement relationship formation with dairy alternative brands and fermentation capacity expansion under MIIT policy incentives.
Within the integrated domestic tier, Hebei Xinhe Biochemical Co Ltd and Zhenpai Hydrocolloids Co Ltd exemplify divergent specialization strategies—one anchored in northern China's fermentation corridor, the other in coastal seaweed extraction. Cargill Inc represents the multinational trader archetype with global supply network leverage into Chinese processing facilities. These three occupy positions that reflect broader structural segmentation between microbial fermentation platforms and plant-based extraction specializations.
| Leading Market Players |
|---|
| Cargill Inc |
| Ashland Global Holdings Inc |
| Zhenpai Hydrocolloids Co. Ltd |
| Koninklijke DSM NV |
| Behn Meyer Deutschland Holding AG & Co. KG |
| Hebei Xinhe Biochemical Co Ltd |
| Archer Daniels Midland Co |
| Rousselot (M) SDN. BHD. |
| CP Kelco US Inc |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Fujian and Shandong provinces anchor seaweed-derived hydrocolloid extraction, their concentrated ownership enabling long-term supply contracts that buffer coastal dairy alternative manufacturers from spot market volatility while maintaining pricing discipline through backward integration into kelp harvesting networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates carbon-certified fermentation-derived colloids from commodity-grade seaweed extracts and generic gelatin grades. Price differentiation rests on MEE emissions verification and SAMR GB standard compliance tier, with premium tiers commanding spreads due to documented energy consumption per kilogram. Cost compression in standard-tier gelatin is intensifying because Shandong rendering facilities face margin pressure from slaughterhouse byproduct competition. Food manufacturers in Shanghai demonstrate lowest price sensitivity, while interior provincial bakeries exhibit highest elasticity to xanthan gum quotations.
Supply Chain Analysis
Dual-sourcing requirements from dairy alternative brands in Jiangsu and Zhejiang mandate qualified supplier lists spanning Hebei fermentation corridors and Fujian seaweed processing zones. Geographic supply concentration centers on China for xanthan gum and agar, with import dependency for specialty pectin grades drawing from citrus processors in Brazil and Argentina. Raw material dependencies encompass kelp harvests from Shandong waters, corn glucose feedstocks for microbial fermentation, and porcine skins from northern China's slaughterhouse networks. Single-source vulnerability pervades red algae supply during Fujian typhoon seasons. Distribution runs through Shanghai bonded logistics hubs serving just-in-time delivery to oat milk production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through carbon-intensity benchmarking that rewards low-carbon fermentation platforms with premium positioning, while standard-tier extractors face compression from MEE protocol compliance costs.
For Market Incumbents: To counter consolidation pressure from dairy alternative brands shrinking vendor lists to three-to-five preferred suppliers, Hebei Xinhe and comparable integrated fermenters should deepen backward integration into captive glucose supply and secure SAMR carbon disclosure pre-certification ahead of GB standard tightening. Capacity addition in Chongqing distribution hubs addresses western province penetration gaps before competitors establish regional logistics infrastructure. For New Entrants and Emerging Players: Begin with Sichuan-Chongqing pectin extraction from citrus peel waste streams, where underdeveloped hydrocolloid processing infrastructure creates first-mover advantages for regional distribution hubs serving interior dairy alternative manufacturers. Target carbon-credential verification as the primary go-to-market angle, leveraging MEE protocols linking emissions data to market access for premium positioning against incumbent coastal extractors. For Investors and Strategic Acquirers: Valuations sit cheapest among northern China's integrated fermentation facilities with existing utility metering infrastructure, where MIIT policy incentives channel capital toward xanthan gum capacity expansion. Long-term viability over the coming decade hinges on convergence between SAMR food safety standards and carbon intensity benchmarks. Watch for MEE protocol enforcement timing as the inflection indicator determining which production technologies retain market access.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Certified Fermentation Capacity Expansion | MIIT incentives lower capital costs for xanthan gum platforms serving Zhejiang dairy alternatives. |
| Backward Integration into Kelp Harvesting | Fujian extractors secure weather-dependent input streams against Shandong supply volatility. |
| SAMR GB Standard Pre-Compliance Investment | Early carbon disclosure documentation prevents market access exclusion under tightening protocols. |
| Western Province Distribution Hub Establishment | Chongqing logistics infrastructure captures Sichuan dairy alternative demand before competitor entry. |
| Precision Fermentation Strain Engineering Partnership | Novel microbial platforms enable customized texture profiles commanding margin premiums in clean-label crossovers. |
Study Parameters
Direct dialogue with fermentation plant managers, hydrocolloid procurement leads at dairy alternative OEMs, distribution channel partners in Shanghai logistics hubs, and SAMR regulatory affairs specialists grounded qualitative assessment, cross-referenced with MIIT industrial policy directives, SAMR GB standard documentation, MEE emissions protocol drafts, and coastal province customs records for hydrocolloid import flows. Bottom-up capacity surveys across Hebei and Shandong facilities triangulated against top-down demand modeling from dairy alternative production volumes.
Bottom-up segmentation analysis modeled product type, application, source origin, and end-user channel across the projection horizon, with CAGRs derived from trend extrapolation of carbon-credential premium spreads and clean-label reformulation rates. Forecast inputs incorporated MIIT microbial fermentation capacity buildout timelines and SAMR additive transparency mandate enforcement phases.
Several conditions sit outside the modeled scope, including abrupt shifts in China's dual carbon goal implementation pace, kelp harvest collapses from extreme weather events in Fujian waters, and pharmaceutical capsule sector gelatin specification changes. Deviation in MEE protocol linkage between emissions data and market access timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Europe Food Preservatives Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
India Food Hydrocolloids Market