
 Brazil Diabetes Drugs Market | 2026-2036
Brazil Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Diabetes Drugs Market Outlook
Domestic pharmaceutical production capacity in Brazil is decoupling from historical import dependence for critical diabetes therapies. Novo Nordisk A/S leverages its integrated insulin manufacturing presence to sustain supply security for Brazilian patients. Sanofi anchors its position through deep distribution reach into the public healthcare channel. Eli Lilly competes by specializing in next-generation GLP-1 receptor agonist formulations tailored to regional prescribing patterns.
Brazil diabetes drugs comprise pharmacological agents designed to regulate blood glucose levels through mechanisms including insulin supplementation, pancreatic beta-cell stimulation, incretin pathway modulation, and hepatic glucose output suppression. These therapeutics serve the primary purpose of preventing microvascular and macrovascular complications in patients with type 1 and type 2 diabetes mellitus. GLP-1 agonists represent the fastest-expanding product category as Brazilian endocrinologists shift toward cardiometabolic-protective prescribing protocols. The homecare end-user segment is gaining structural importance as pen-based delivery systems reduce hospital dependency for routine administration.
ANVISA governs market authorization, post-market surveillance, and bioequivalence standards for diabetes drugs circulating in Brazil, while the country's national pharmaceutical regulator enforces good manufacturing practice compliance across domestic and imported supply chains. Brazil's public procurement framework under the Ministry of Health shapes volume allocation through centralized tenders for the Unified Health System. Stakeholders must monitor how ANVISA's evolving biosimilar guidance and SUS reimbursement revisions will reconfigure competitive positioning between originator and local manufacturers.
Market Dynamics
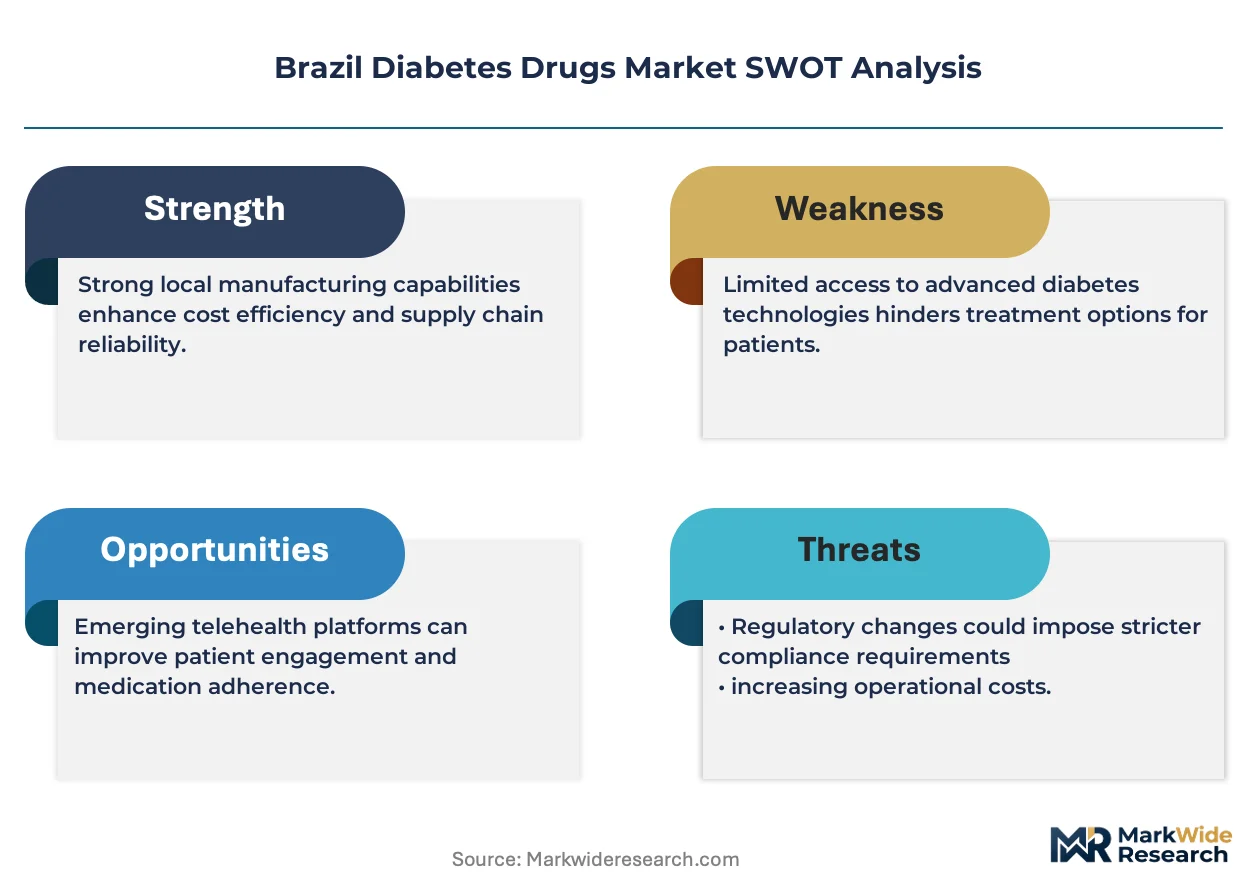
ANVISA's accelerated biosimilar approval pathways are compressing originator exclusivity windows and forcing pricing recalibration across Brazil's public procurement channels. This regulatory pressure is redistributing volume toward domestic manufacturers while reshaping how multinational suppliers defend their hospital formulary positions.
Growth Catalysts
- SUS Centralized Tenders:Brazil's Unified Health System procurement framework aggregates demand into multi-year volume contracts, creating predictable offtake for insulin and GLP-1 manufacturers serving the public network.
- Cardiometabolic Protocol Adoption:Brazilian endocrinology societies are embedding cardiovascular outcome data into prescribing guidelines, redirecting patient flows toward SGLT-2 inhibitors and GLP-1 receptor agonists with proven heart failure benefit.
- Homecare Pen Systems:Disposable insulin pen devices are displacing vial-and-syringe administration in São Paulo state's metropolitan corridor, reducing hospital dependency and expanding addressable patient populations.
Market Restraints
- Active Pharmaceutical Ingredient Import Concentration:Brazil's domestic formulation capacity remains tethered to imported API supplies from India and China, exposing manufacturers to freight cost volatility and customs clearance delays.
- ANVISA Bioequivalence Requirements:Stringent pharmacokinetic study mandates for biosimilar insulins extend registration timelines and inflate development costs for local entrants targeting the SUS channel.
- Oral Antidiabetic Substitution:Fixed-dose metformin formulations continue capturing first-line therapy initiation in primary care settings, compressing the addressable market for injectable advanced therapies at disease onset.
Strategic Opportunities
- Northeast Region Underpenetration:Pernambuco and Bahia states exhibit diabetes prevalence rates comparable to São Paulo but carry substantially lower GLP-1 and insulin analog penetration, creating whitespace for distribution network expansion.
- Telemedicine Integration:Remote endocrinology consultations are embedding continuous glucose monitoring data into prescribing workflows, opening channels for sensor-integrated insulin delivery system adoption.
- ANVISA RDC 55/2010 Revisions:Anticipated updates to biological product registration guidelines may streamline biosimilar interchangeability designations, accelerating pharmacy-level substitution authority.
Industry Challenges
- Cold Chain Integrity:Temperature excursion risks during last-mile distribution to Amazonas and Pará interior municipalities degrade product efficacy and trigger SUS contract penalty clauses.
- Specialist Workforce Density:Brazil's endocrinologist concentration in São Paulo and Rio de Janeiro metropolitan areas leaves Ceará and Minas Gerais underserved, constraining advanced therapy initiation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Diabetes Drugs Market |
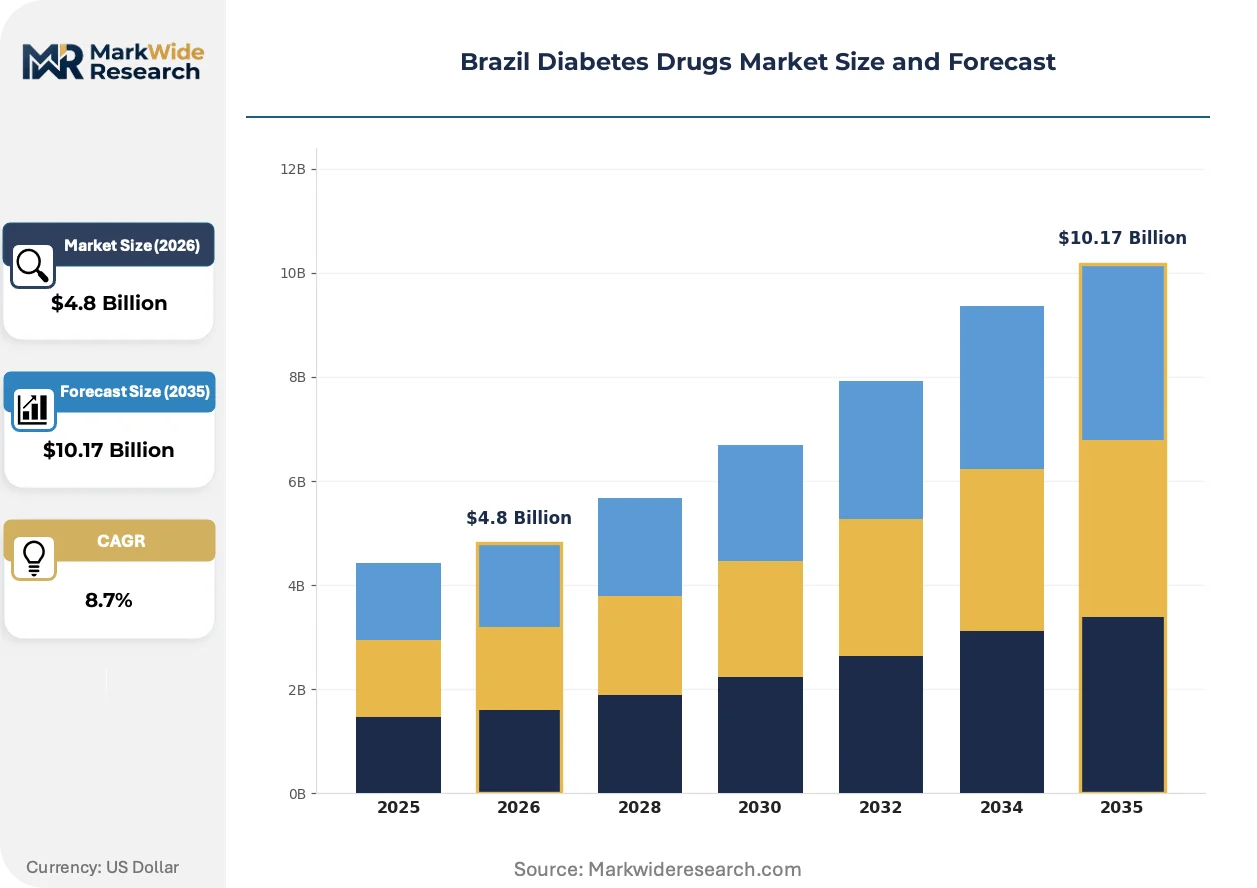
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Sulfonylureas, DPP-4 Inhibitors, GLP-1 Agonists Form: Tablets, Injections, Pens, Extended-Release End User: Hospitals, Clinics, Homecare, Pharmacies Delivery Mode: Subcutaneous, Oral, Intravenous, Transdermal |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly, AstraZeneca, Merck & Co., Boehringer Ingelheim, EMS Sigma Pharma, Ache Laboratorios Farmaceuticos, Cristália Produtos Químicos, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Diabetes Drugs Market Strategic Shifts
Connected delivery devices and algorithm-driven dosing support are converging to transform patient self-management from episodic intervention to continuous metabolic control. This shift is compressing the role of traditional clinic-based monitoring while elevating data interoperability as a competitive differentiator.
Smart insulin pens with dose logging and Bluetooth connectivity are overtaking conventional disposable devices in Brazilian private pharmacy channels. Endocrinology practices in São Paulo's Jardins and Moema districts are prescribing these systems to type 1 patients seeking reduced hypoglycemia exposure. The technology is enabling pharmaceutical manufacturers to capture adherence data and defend premium positioning against SUS-procured standard alternatives.
ANVISA's RDC 338/2022 framework for real-world evidence submissions is accelerating post-approval label expansion pathways for cardiometabolic indications. Manufacturers can now supplement randomized trial data with Brazilian registry outcomes to support formulary inclusion arguments. SUS technology assessment committees are incorporating these evidence packages into their cost-effectiveness deliberations for high-cost antidiabetic therapies.
Patient acquisition through digital therapeutics platforms is displacing traditional physician-detailing models for GLP-1 initiation. Apps integrating nutrition coaching, medication reminders, and teleconsultation access are capturing prediabetic populations in Rio de Janeiro and Brasília before clinical progression triggers specialist referral. This behavioral shift is most visible among employed, insured demographics seeking convenience over conventional clinic queue systems.
Brazil Diabetes Drugs Market Segmentation
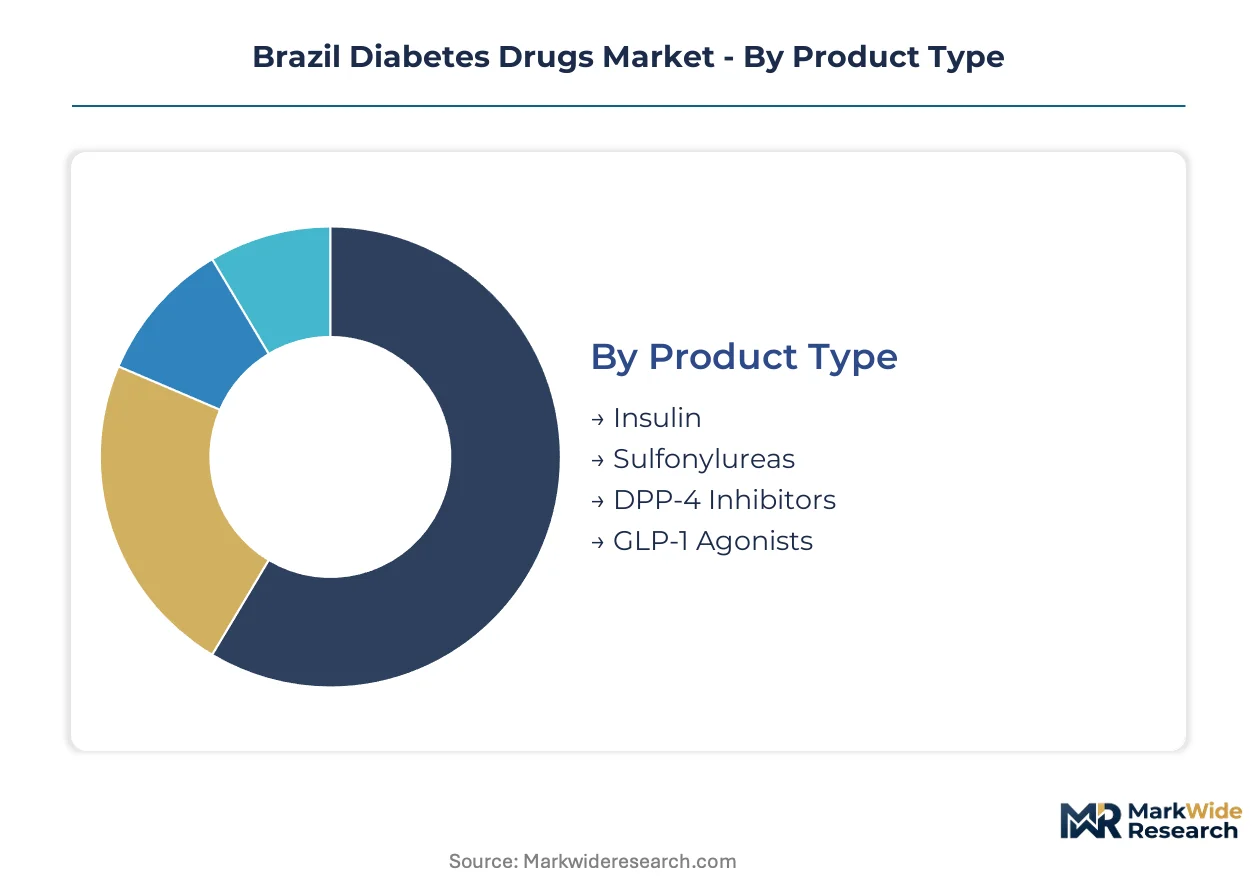
Segmentation of Brazil's diabetes drugs market reveals how ANVISA approval pathways, SUS procurement tiers, and regional care infrastructure differentially shape commercial access across product categories. Understanding these fracture lines enables manufacturers to align registration investment with addressable patient populations and reimbursement velocity.
Product Type:
ANVISA's bioequivalence requirements vary sharply across these pharmacological classes, with biological products facing extended pharmacokinetic study mandates that compress margins for local entrants while protecting originator positions in hospital tenders.
- Insulin:Human and analog formulations remain the backbone of SUS procurement, with biosimilar registration pathways under ANVISA RDC 55/2010 revisions accelerating pharmacy-level substitution authority in São Paulo's metropolitan corridor.
- GLP-1 Agonists:These incretin-based therapies require cold chain integrity certification and cardiovascular outcome data packages for formulary inclusion, concentrating demand in São Paulo and Rio de Janeiro's integrated specialty care centers where endocrinologist density supports protocol adoption.
- Sulfonylureas:Glimepiride and gliclazide formulations dominate first-line therapy in Brazil's primary care network, anchored by mature ANVISA registrations and predictable SUS tender pricing.
- DPP-4 Inhibitors:Sitagliptin and linagliptin compete for oral therapy escalation slots, with ANVISA's RDC 338/2022 real-world evidence framework enabling post-approval label expansion for cardiometabolic indications.
Leading the category by volume: Insulin. Growing fastest: GLP-1 Agonists.
Form:
Cost tier stratification separates premium device-integrated delivery systems from economy vial formulations, with pen-based systems commanding 3-4x unit pricing in private channels while SUS tenders standardize on basic presentations.
- Injections:Vial-and-syringe administration persists in SUS hospital wards and rural municipalities where cold chain infrastructure limits pen device adoption, though patient satisfaction scores lag disposable alternatives.
- Pens:Disposable and reusable insulin pen devices concentrate in São Paulo's private pharmacy network and Jardins district endocrinology practices, with Bluetooth-enabled smart pens capturing adherence data to defend premium positioning.
- Tablets:Metformin and DPP-4 inhibitor tablets anchor oral therapy initiation across Brazil's 5,500 municipal health secretariats, with ANVISA bioequivalence requirements for generics shaping competitive intensity.
- Extended-Release:Once-daily metformin XR and glipizide XL formulations reduce pill burden for employed, insured demographics in Brasília and Curitiba seeking regimen simplification.
Highest volume concentration: Injections. Steepest expansion trajectory: Pens.
End User:
Customer type determines reimbursement velocity and prescriber authority, with hospital-based procurement aggregating volume into multi-year SUS contracts while homecare channels fragment across 70,000+ retail pharmacy points.
- Hospitals:Tertiary care centers in São Paulo, Rio de Janeiro, and Belo Horizonte administer advanced insulin analogs and GLP-1 agonists through centralized pharmacy committees, with ANVISA GMP inspections conditioning formulary access.
- Homecare:Pen-based self-administration is displacing clinic visits for stable type 2 patients in metropolitan corridors, reducing hospital dependency and expanding addressable populations through telemedicine-integrated monitoring.
- Clinics:Private endocrinology practices in Moema and Jardins districts drive GLP-1 initiation for cardiometabolic protection, with prescription patterns influenced by cardiovascular outcome trial data.
- Pharmacies:Retail dispensing concentrates generic oral antidiabetics and biosimilar insulins, with ANVISA's anticipated interchangeability designations poised to accelerate substitution authority at the counter.
Dominant volume channel: Hospitals. Fastest-growing segment: Homecare.
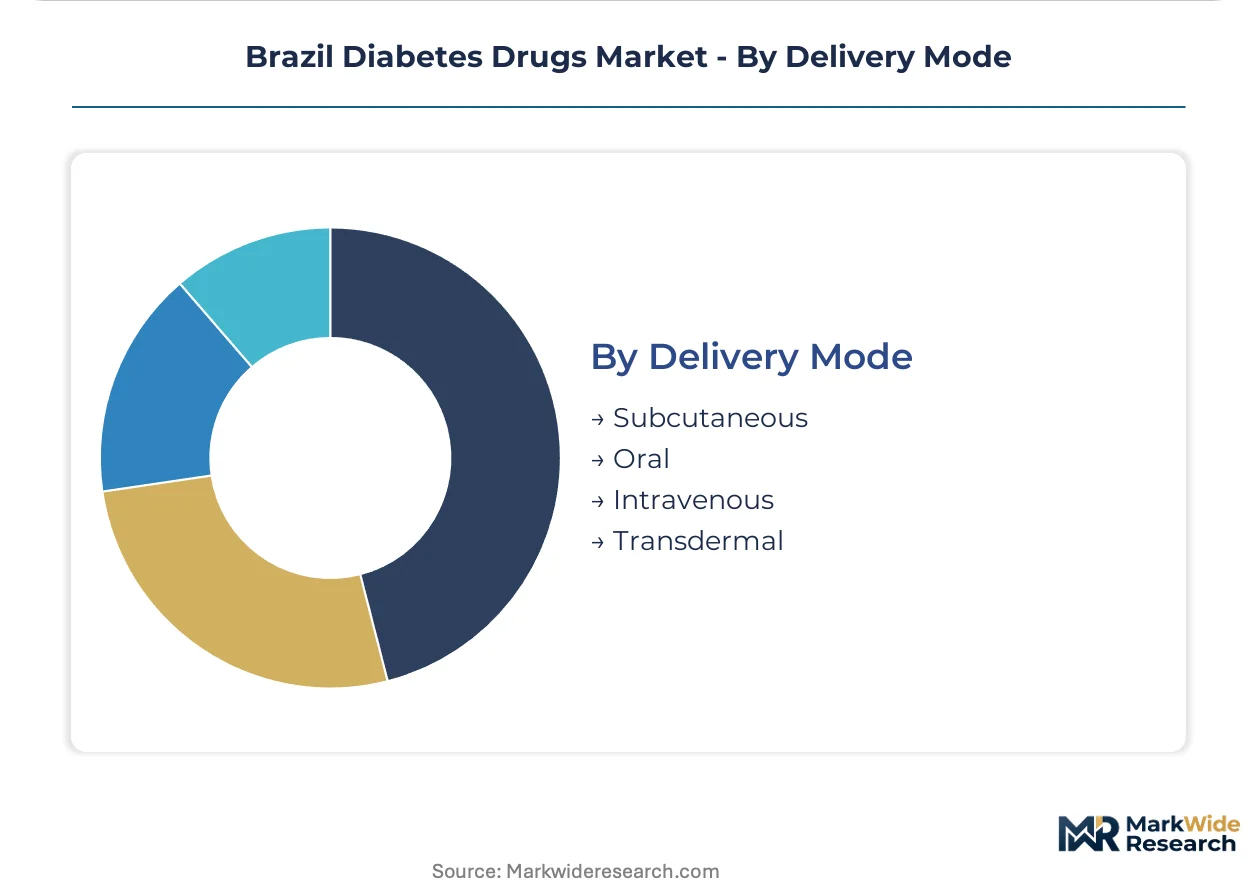
Delivery Mode:
Application infrastructure requirements create divergent margin profiles, with subcutaneous device systems demanding training investment and cold chain logistics while oral formulations leverage existing tablet manufacturing capacity.
- Subcutaneous:Pen and syringe-based insulin and GLP-1 delivery requires patient education programs and refrigeration infrastructure, concentrating manufacturer investment in São Paulo state's distribution network.
- Oral:Metformin, sulfonylureas, and DPP-4 inhibitors bypass cold chain constraints entirely, enabling distribution to Amazonas and Pará interior municipalities where temperature excursion risks degrade injectable efficacy.
- Intravenous:Hospital-only insulin infusion for diabetic ketoacidosis and perioperative glycemic control anchors demand in tertiary emergency departments, with ANVISA sterile manufacturing standards limiting local production.
- Transdermal:Experimental patches and microneedle systems remain pre-commercial in Brazil, with ANVISA innovation pathways for novel delivery technologies awaiting definitive clinical evidence packages.
Volume leader: Subcutaneous. Expansion outlook: Oral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient feedstocks for Brazil's diabetes drug formulations concentrate in São Paulo state's petrochemical corridor, with formulation capacity radiating toward regional distribution hubs serving the Unified Health System.
São Paulo
Metropolitan São Paulo generates the highest per-capita consumption of GLP-1 agonists and insulin analogs, driven by endocrinologist density and integrated specialty care centers. ANVISA's accelerated biosimilar approval pathways under RDC 55/2010 revisions are compressing originator exclusivity windows in the Jardins and Moema districts, where private endocrinology practices drive cardiometabolic-protective prescribing protocols.
Minas Gerais
Belo Horizonte anchors southeastern demand for oral antidiabetics through its municipal health secretariat procurement networks, though specialist workforce density lags São Paulo. The state's pharmaceutical distribution infrastructure connects to SUS centralized tenders, with cold chain logistics extending into interior municipalities where temperature excursion risks challenge injectable therapy access.
Rio de Janeiro
Rio's private pharmacy channels concentrate smart insulin pen adoption among employed, insured demographics seeking telemedicine-integrated monitoring. The state health secretariat participates in multi-year SUS volume contracts for human insulin, while tertiary care centers in the metropolitan area administer advanced therapies through centralized pharmacy committees.
Bahia
Salvador and surrounding municipalities exhibit diabetes prevalence rates comparable to São Paulo but carry substantially lower GLP-1 and insulin analog penetration, creating whitespace for distribution network expansion. ANVISA bioequivalence requirements for generics shape competitive intensity in oral therapy dispensing across the state's municipal health secretariats.
Rio Grande do Sul
Porto Alegre's integrated healthcare networks participate in SUS procurement frameworks, with hospital-based pharmacy committees managing advanced antidiabetic therapy allocation. The state's formulation capacity supports regional supply security for critical diabetes therapies, though API import dependence from Asian suppliers exposes manufacturers to freight cost volatility.
Brazil Diabetes Drugs Market Competitive Environment
Global majors compete with regional champions across distribution reach and SUS procurement access, with market structure consolidating around originator biologicals and emerging biosimilar entrants. Danish and French pharmaceutical groups anchor originator positions through integrated manufacturing presence, while Brazilian domestic laboratories capture volume through public tender participation. Three archetypes dominate: multinational biological specialists, diversified European pharmaceutical conglomerates, and local formulation manufacturers. Competitive moves center on ANVISA registration velocity and cold chain infrastructure investment for last-mile penetration.
Within the multinational biological specialist tier, Novo Nordisk A/S and Sanofi occupy positions defined by insulin manufacturing footprint and hospital formulary anchoring. Eli Lilly represents the GLP-1 receptor agonist specialization archetype, with portfolio concentration reflecting cardiometabolic outcome data integration into Brazilian prescribing guidelines. Among domestic champions, EMS Sigma Pharma and Ache Laboratorios Farmaceuticos exemplify the local formulation and distribution archetype, with competitive positioning tied to SUS tender participation and generic oral antidiabetic volume capture.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly |
| AstraZeneca |
| Merck & Co. |
| Boehringer Ingelheim |
| EMS Sigma Pharma |
| Ache Laboratorios Farmaceuticos |
| Cristália Produtos Químicos |
| Others |
Value Chain & Pricing Dynamics
ANVISA's RDC 55/2010 biosimilar interchangeability revisions gate both qualified supply and premium-tier pricing access in Brazil's diabetes drugs market, compressing originator exclusivity windows while elevating cold chain certification as a cost-of-entry barrier for SUS contract participation.
Pricing Analysis
Service bundling separates SUS-procured standard formulations from private-channel premium positioning, with patient education programs and telemedicine integration included in smart pen systems commanding 3-4x unit pricing. Three-tier pricing structure across premium device-integrated, standard pen-based, and economy vial formulations reflects ANVISA bioequivalence certification tiers and cold chain reliability guarantees. Cost compression in the economy tier intensifies as domestic manufacturers exploit accelerated biosimilar pathways, while public procurement managers exhibit highest price sensitivity compared to private endocrinology practices prioritizing cardiometabolic outcome data.
Supply Chain Analysis
ANVISA's domestic-content mandates for biological product registration are reshaping sourcing strategies, pushing manufacturers toward local formulation partnerships despite API import dependence. Active pharmaceutical ingredient supply draws from India and China, with insulin analog feedstocks additionally sourcing from European fermentation facilities. Freight cost volatility and customs clearance delays constitute the primary structural risk, degrading margin predictability for SUS tender participants. Distribution runs through São Paulo state's radiating hub-and-spoke network, with last-mile cold chain integrity determining pharmacy-level substitution authority in interior municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's diabetes drugs market sits in a device-to-digital transition phase, with Bluetooth-enabled smart insulin pens and continuous glucose monitoring integration displacing conventional disposable administration systems.
For Market Incumbents: Acquire cold chain logistics assets in Northeast region distribution corridors to defend SUS contract positions against biosimilar entrants exploiting ANVISA's accelerated approval pathways. Deepen backward integration into insulin analog API sourcing to mitigate Indian and Chinese supply volatility, while embedding cardiovascular outcome data into real-world evidence submissions under RDC 338/2022 to protect premium formulary access.
For New Entrants and Emerging Players: Capture whitespace in Pernambuco and Bahia states where diabetes prevalence matches São Paulo but GLP-1 penetration lags substantially behind specialist care density. Target municipal health secretariat procurement networks through abbreviated bioequivalence study investments, leveraging telemedicine-integrated patient education programs as the primary go-to-market angle for homecare pen system adoption.
For Investors and Strategic Acquirers: ANVISA's anticipated RDC 55/2010 interchangeability designation updates are the leading indicator that pharmacy-level substitution authority will accelerate, compressing originator biological margins within the medium-term window. Acquisition targets should prioritize domestic formulation laboratories with established SUS tender participation and certified cold chain infrastructure, watching for biosimilar insulin portfolio expansions as the definitive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Expansion | Refrigeration certification in Amazonas and Pará interior municipalities unlocks SUS contract eligibility for injectable therapies. |
| Real-World Evidence Submission | RDC 338/2022 cardiovascular outcome data packages accelerate post-approval label expansion for cardiometabolic indications. |
| Biosimilar Registration Investment | ANVISA bioequivalence study completion compresses originator exclusivity windows in public procurement channels. |
| Telemedicine Platform Integration | Remote endocrinology consultations embed continuous glucose monitoring data into prescribing workflows for sensor-integrated delivery. |
| Northeast Distribution Network Buildout | Pernambuco and Bahia state logistics hubs address underpenetration comparable to São Paulo prevalence rates. |
Study Parameters
Multi-period observation of ANVISA registration timelines, SUS tender award patterns, and biosimilar approval velocity anchored the trend analysis, supplemented by interviews with regulatory affairs specialists at domestic laboratories, formulary directors at tertiary care hospital pharmacy committees, endocrinologists in São Paulo's Jardins and Moema districts, and procurement managers within the Ministry of Health's centralized purchasing division. Secondary validation drew from ANVISA RDC filings, SUS technology assessment committee deliberation records, Brazilian endocrinology society prescribing guideline updates, and pharmaceutical import customs data. Bottom-up patient population modeling and top-down healthcare expenditure triangulation reconciled volume estimates across the analysis window.
Input-output matrices mapped insulin analog and GLP-1 agonist demand across product type, administration form, end-user channel, and regional regulatory cluster dimensions. CAGRs were derived from segmented growth rate reconciliation against macro healthcare spending trajectories. Forecast inputs incorporated ANVISA approval pathway velocity assumptions, SUS reimbursement revision probabilities, and cold chain infrastructure expansion schedules without year-specific anchoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA biosimilar interchangeability designation timing, API import tariff fluctuations, and specialist workforce density expansion in underserved interior states. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Acetylcholine Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Short-Acting Beta-Agonists Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market