
 Hyoscine Market | 2026-2036
Hyoscine Market Size, Share, and Industry Trends Forecast 2026-2036
Hyoscine Market Analysis
Multi-source API procurement is hardening across the hyoscine supply base as manufacturers diversify away from concentrated botanical extraction networks. Boehringer Ingelheim leverages captive cultivation partnerships in Eastern Europe to secure raw scopolamine alkaloid streams. Teva Pharmaceutical Industries Ltd. competes through vertical integration into tablet and transdermal patch finishing, while Sun Pharmaceutical Industries Ltd. anchors its position with cost-optimized injectable capacity serving institutional buyers across South Asia and Africa.
Hyoscine, also known as scopolamine, is a tropane alkaloid derived primarily from Datura and Brugmansia species, functioning as a competitive antagonist at muscarinic acetylcholine receptors with clinical utility in parasympathetic inhibition. The compound serves core therapeutic roles in motion sickness prophylaxis, perioperative nausea suppression, and gastrointestinal spasmolysis, with dosage forms ranging from 0.3 mg oral tablets to 1.5 mg transdermal patches delivering steady-state plasma levels over 72 hours. Transdermal patch applications for motion sickness and postoperative nausea now command the most favorable margin pools as patient compliance advantages sustain premium positioning against generic oral alternatives. Injectable formulations for anesthesia and pain management co-administration retain structural importance in hospital formularies despite slower volume expansion, while home care distribution channels are gaining share as post-acute settings shift administration away from traditional inpatient wards.
FDA bioequivalence standards for generic scopolamine products govern market access for new entrants seeking abbreviated new drug approval pathways, while the EMA's centralized marketing authorization framework shapes competitive dynamics for patch formulations across European Union member states. The WHO Essential Medicines List inclusion of hyoscine butylbromide for gastrointestinal indications creates procurement leverage for public health systems in lower-income markets, indirectly steering manufacturer portfolio priorities. Stakeholders must monitor evolving pharmacovigilance requirements for anticholinergic burden accumulation as combination therapies expand in elderly surgical populations.
Market Dynamics
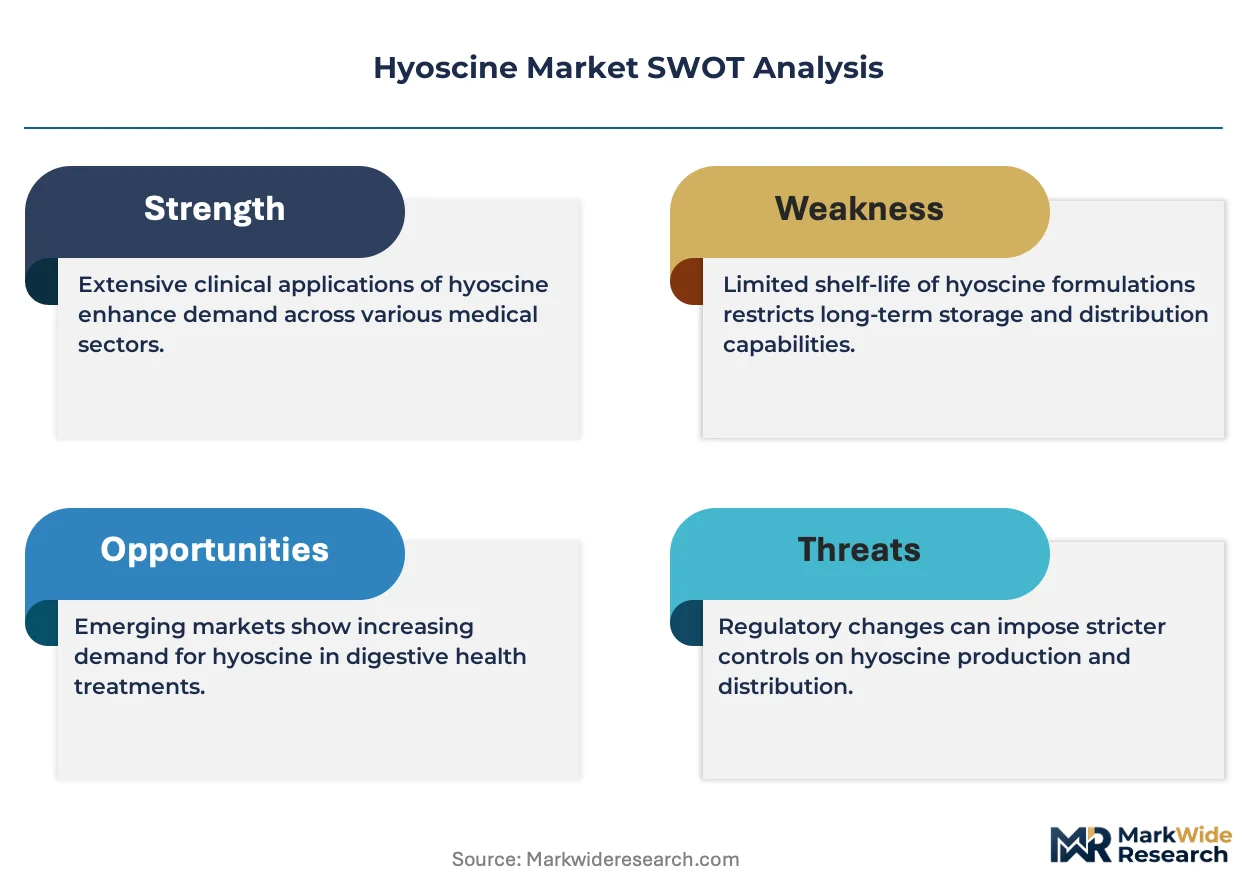
FDA bioequivalence tightening for generic scopolamine products is forcing manufacturers to restructure compliance investments and API sourcing strategies, compressing margins for non-integrated producers while advantaging those with captive alkaloid supply chains.
Growth Catalysts
- Postoperative nausea protocol standardization:Ambulatory surgical centers in the United States are embedding transdermal hyoscine patches into perioperative care pathways, creating institutional demand pull.
- WHO Essential Medicines List inclusion:Hyoscine butylbromide designation for gastrointestinal indications unlocks public procurement budgets across lower-income health systems.
- Transdermal delivery technology maturation:Steady-state plasma concentration over 72 hours improves patient compliance versus oral alternatives in motion sickness prophylaxis.
Market Restraints
- Botanical extraction network concentration:Raw scopolamine alkaloid supply concentrates in Eastern European cultivation partnerships, creating single-source vulnerability.
- Anticholinergic burden accumulation:Pharmacovigilance scrutiny intensifies for elderly surgical populations receiving combination therapies with hyoscine.
- Generic oral substitution:Cost-pressured institutional formularies in South Asia and Africa favor cheaper hyoscine butylbromide tablets over premium patch formulations.
Strategic Opportunities
- Home care channel expansion:Post-acute administration shifts away from traditional inpatient wards toward home care distribution, opening patient-direct fulfillment models.
- EMA centralized marketing authorization:Streamlined patch formulation approvals across European Union member states reduce regulatory duplication for manufacturers.
- Gastrointestinal spasmolysis underpenetration:Functional dyspepsia and irritable bowel syndrome indications remain underserved relative to antiemetic applications.
Industry Challenges
- Multi-source API qualification timelines:Manufacturers diversifying away from concentrated botanical networks face extended validation cycles for alternative alkaloid streams.
- Transdermal patch manufacturing scale-up:Adhesive matrix uniformity and release-rate consistency require specialized equipment investments that strain mid-cap producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyoscine Market |
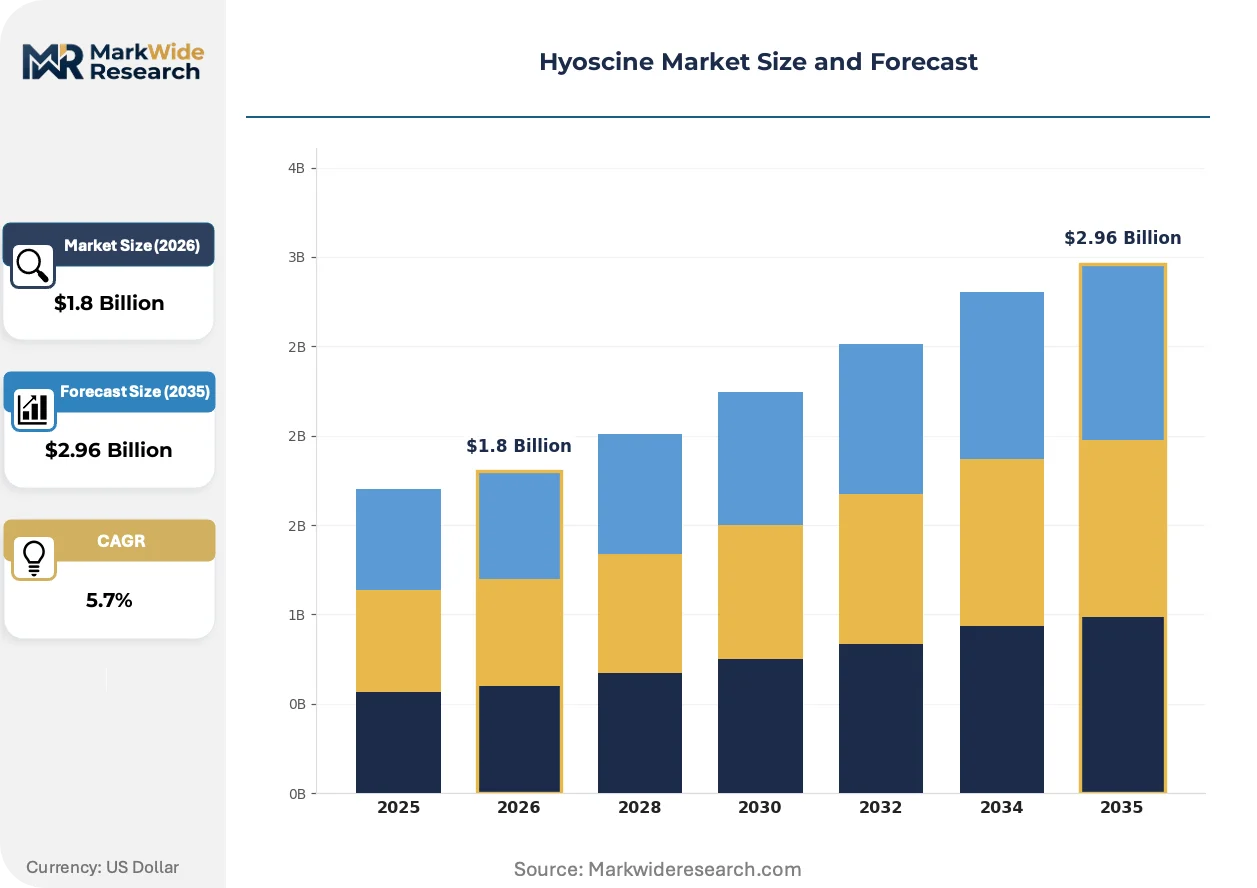
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable, Transdermal Patch, Oral Solution End User: Hospitals, Clinics, Pharmacies, Home Care Application: Motion Sickness, Gastrointestinal Disorders, Anesthesia, Pain Management Distribution Channel: Direct Sales, Online Pharmacies, Retail Pharmacies, Wholesale Distributors |
| Companies Covered | Boehringer Ingelheim, Novartis AG, Teva Pharmaceutical Industries Ltd., Baxter International, GSK plc, Sun Pharmaceutical Industries Ltd., Caleb Pharmaceuticals, Inc., Perrigo Company plc, Cipla Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyoscine Market Emerging Trajectories
Active pharmaceutical ingredient sourcing strategies are converging with advanced extraction technologies, reshaping how manufacturers secure tropane alkaloid feedstocks. Three developments are compressing legacy supply models.
Supercritical CO2 extraction is converging with molecular distillation protocols to improve scopolamine yield purity from Datura biomass. Eastern European cultivation partners are adopting these hybrid systems to meet FDA botanical drug substance guidelines. The technology is converging with quality-by-design frameworks, enabling manufacturers to bypass traditional solvent-based purification bottlenecks.
REACH registration requirements for imported alkaloid intermediates are tightening documentation burdens on non-EU suppliers. ECHA substance evaluation workflows now mandate full supply chain transparency for botanical APIs entering European patch formulation facilities. German and French pharmaceutical manufacturers are responding by consolidating procurement through Swissmedic-certified toll processors.
Ambulatory surgical center buying consortia are consolidating injectable hyoscine purchasing through specialized group purchasing organizations. Traditional wholesale distribution is yielding to direct manufacturer contracts with multi-facility networks. This pattern is most visible across the southeastern United States, where regional ASC chains now negotiate formulary exclusivity in exchange for volume commitments.
Hyoscine Market Segmentation
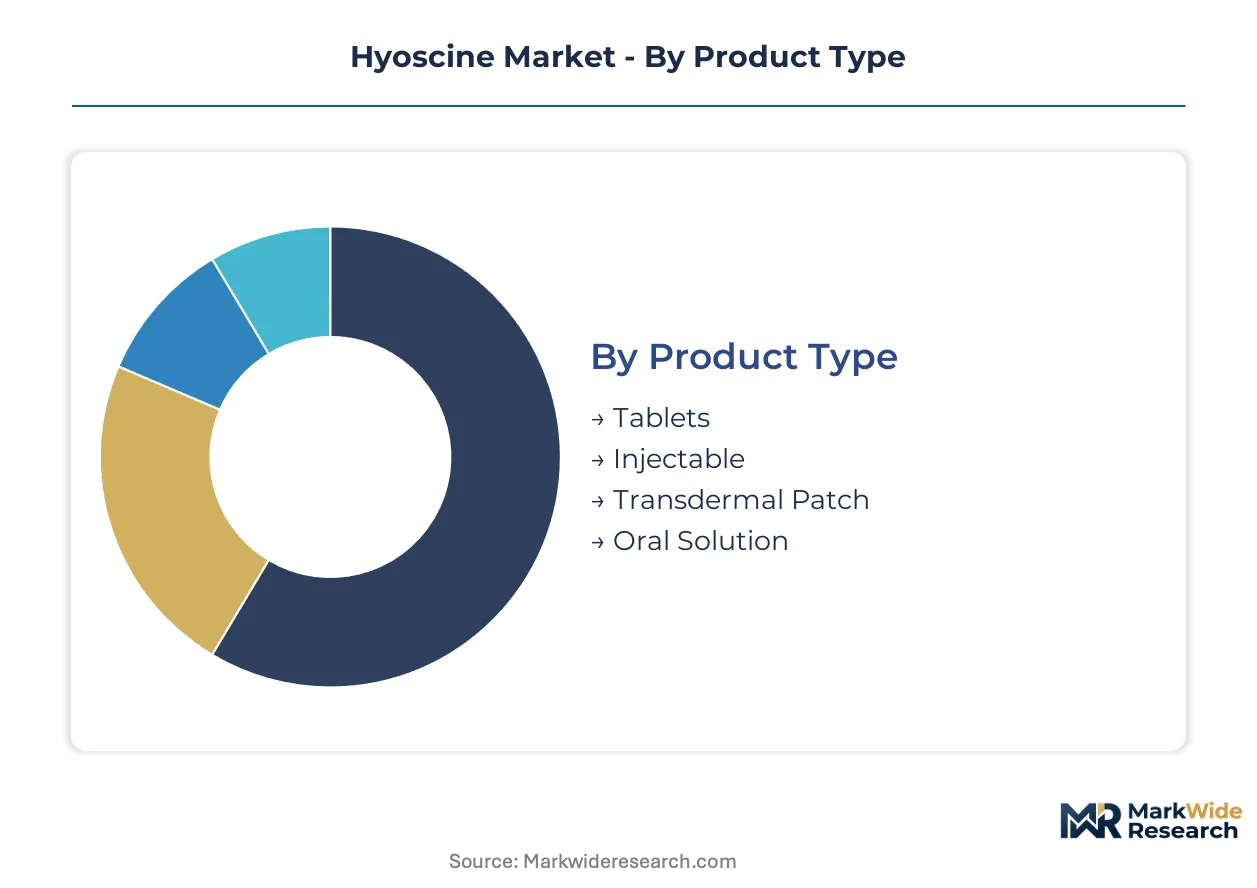
Hyoscine's therapeutic versatility across anticholinergic indications fragments manufacturing investment across four distinct formulation technologies. Each product category commands divergent margin profiles and regulatory compliance burdens, forcing portfolio prioritization trade-offs among API suppliers and finished dose manufacturers.
Product Type:
Supply concentration for scopolamine alkaloid feedstocks disproportionately advantages manufacturers with captive cultivation networks, tilting competitive dynamics toward integrated producers across all four formulation categories.
- Transdermal Patch:Adhesive matrix systems delivering 1.5 mg scopolamine over 72 hours through rate-controlling membranes. Ambulatory surgical centers in the United States embed these patches into perioperative nausea protocols, driving institutional procurement volume through specialized group purchasing organizations.
- Injectable:Parenteral formulations for anesthesia co-administration and acute antiemetic intervention in surgical settings. Hospital formularies retain structural commitment despite slower volume expansion as post-acute administration shifts toward alternative settings.
- Tablets:Oral 0.3 mg scopolamine and hyoscine butylbromide variants for gastrointestinal spasmolysis. Cost-pressured institutional buyers across South Asia and Africa favor these over premium patch alternatives.
- Oral Solution:Liquid formulations enabling dose titration for pediatric and geriatric populations with swallowing difficulties. Niche positioning limits scale economics relative to solid dose alternatives.
Transdermal patch manufacturing absorbs the bulk of installed capacity; oral solution is expanding most quickly as home care channels seek patient-compliant alternatives.
End User:
Procurement authority concentration reshapes pricing leverage across patient care settings, with institutional buyers extracting volume discounts unavailable to fragmented retail channels.
- Hospitals:Tertiary care facilities and integrated delivery networks commanding largest absolute hyoscine injectable volumes. FDA bioequivalence tightening for generic scopolamine products forces formulary managers toward qualified suppliers with documented API provenance.
- Home Care:Post-acute administration settings gaining procurement share as surgical recovery shifts outside traditional inpatient wards. Patient-direct fulfillment models bypass wholesale distribution markups.
- Clinics:Outpatient surgical and gastroenterology practices with concentrated motion sickness and spasmolysis demand. Limited cold chain requirements favor tablet procurement over injectable inventory.
- Pharmacies:Community and outpatient dispensaries serving acute prescription needs and over-the-counter motion sickness prophylaxis. Retail margin compression favors generic oral alternatives.
Hospitals absorb the bulk of installed capacity; home care is climbing the fastest as reimbursement frameworks incentivize post-acute discharge.
Application:
Clinical evidence accumulation and protocol standardization determine reimbursement access, creating divergent growth trajectories across therapeutic indications.
- Motion Sickness:Prophylactic transdermal patch application dominates consumer and institutional demand. Steady-state plasma concentration over 72 hours sustains premium positioning against oral alternatives.
- Gastrointestinal Disorders:Hyoscine butylbromide tablets for functional dyspepsia and irritable bowel syndrome. WHO Essential Medicines List inclusion unlocks public procurement budgets across lower-income health systems.
- Anesthesia:Perioperative nausea and vomiting suppression through injectable and patch co-administration. Standardized postoperative protocols embed hyoscine into ambulatory surgical center care pathways.
- Pain Management:Adjunctive anticholinergic use in multimodal analgesia regimens. Smaller addressable market relative to core antiemetic applications.
Motion sickness absorbs the bulk of installed capacity; gastrointestinal disorders are gaining share fastest as functional dyspepsia protocols expand.
Distribution Channel:
Channel consolidation and direct manufacturer contracting are displacing traditional wholesale intermediaries, compressing margin pools for non-integrated distributors.
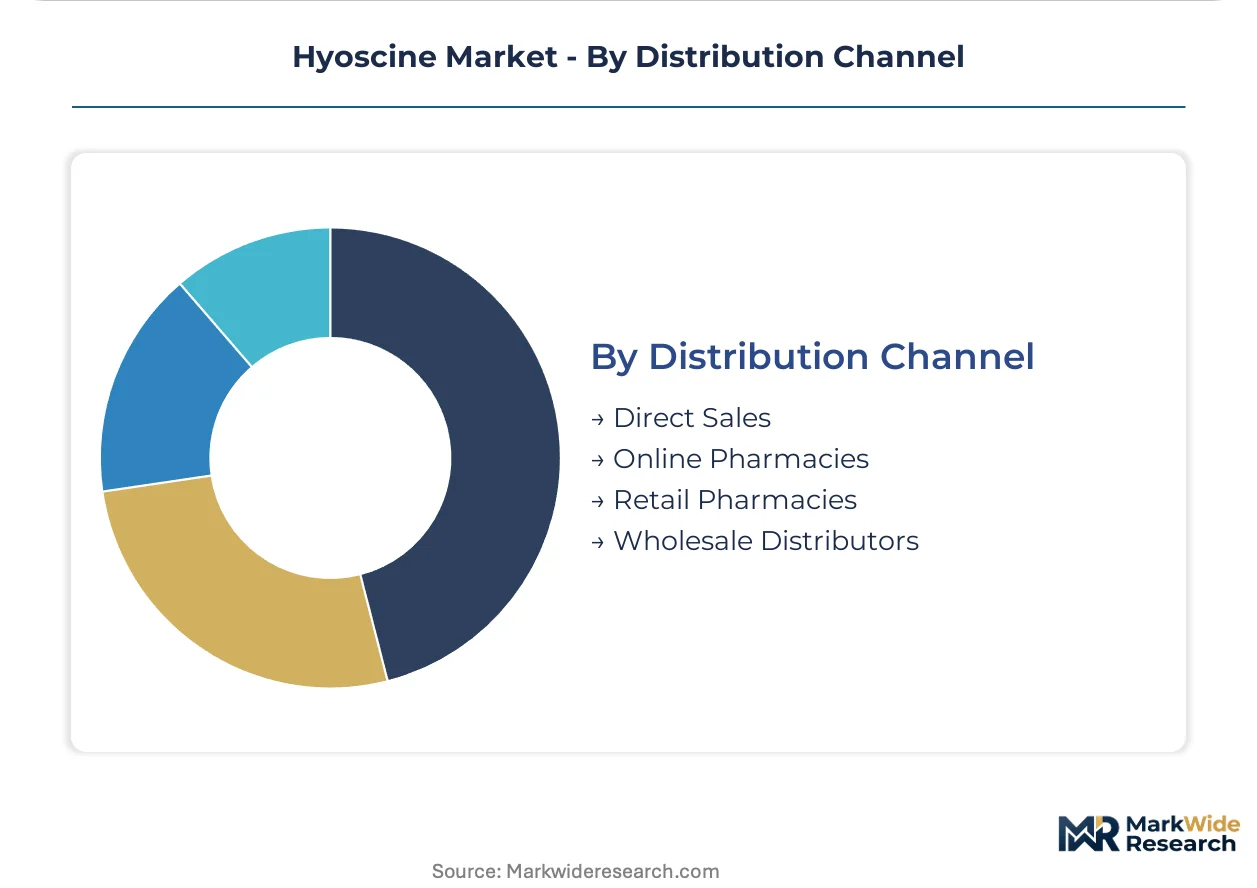
- Direct Sales:Manufacturer contracts with multi-facility ambulatory surgical center networks and hospital buying consortia. Southeastern United States regional ASC chains negotiate formulary exclusivity in exchange for volume commitments.
- Wholesale Distributors:Traditional three-tier pharmaceutical distribution yielding share to specialized group purchasing organizations. Inventory carrying costs disadvantage smaller regional players.
- Retail Pharmacies:Community dispensaries serving acute prescription and over-the-counter demand. Generic oral substitution pressures premium patch stocking decisions.
- Online Pharmacies:Patient-direct fulfillment models expanding in post-acute and chronic prophylaxis segments. Regulatory compliance with state-level pharmacy licensure creates operational complexity.
Direct sales absorb the bulk of installed capacity; online pharmacies are expanding most quickly as home care channels seek fulfillment efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ambulatory surgical centers now rank among the largest volume purchasers of hyoscine injectables, while hospital procurement of transdermal patch formulations expands as postoperative nausea protocols standardize. Demand concentrates in specific national markets where regulatory frameworks and reimbursement structures align with formulation innovation.
United States
FDA bioequivalence tightening for generic scopolamine products is reshaping manufacturer compliance investments and API sourcing strategies. Ambulatory surgical center buying consortia in the southeastern United States now negotiate formulary exclusivity directly with manufacturers. Regional ASC chains across Florida and Georgia embed transdermal patches into perioperative care pathways, displacing traditional wholesale distribution.
Germany
EMA centralized marketing authorization streamlines patch formulation approvals across European Union member states, reducing regulatory duplication for manufacturers serving German hospital networks. REACH registration requirements for imported alkaloid intermediates tighten documentation burdens on non-EU suppliers. Pharmaceutical manufacturers in Baden-Württemberg consolidate procurement through Swissmedic-certified toll processors to ensure supply chain transparency.
India
WHO Essential Medicines List inclusion of hyoscine butylbromide unlocks public procurement budgets across lower-income health systems, steering manufacturer portfolio priorities toward cost-optimized tablet production. CDSCO regulatory oversight governs generic scopolamine product approvals for domestic and export markets. Sun Pharmaceutical Industries anchors institutional supply across South Asia and Africa from manufacturing clusters in Maharashtra and Gujarat.
Japan
PMDA marketing authorization requirements maintain stringent quality standards for transdermal delivery systems, favoring manufacturers with documented API provenance and specialized adhesive matrix capabilities. METI industrial policy supports domestic pharmaceutical production through targeted incentives. Tokyo-Osaka pharmaceutical corridors concentrate formulation expertise for motion sickness prophylaxis products serving aging demographic demand.
Switzerland
Swissmedic certification serves as a gateway standard for botanical API toll processing, with German and French manufacturers routing Eastern European alkaloid streams through Swiss intermediaries. The country's regulatory reputation enables premium positioning for finished dose exports. Basel-area pharmaceutical clusters specialize in transdermal patch technology transfer and quality-by-design implementation for scopolamine products.
Hyoscine Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek captive alkaloid supply and specialized formulation capabilities. The vendor base organizes around three tiers: integrated producers with botanical cultivation networks, mid-cap finishers with patch manufacturing expertise, and generic tablet specialists serving cost-pressured institutional markets. Two strategic archetypes prevail: backward-integrated alkaloid controllers and formulation-differentiated delivery innovators. Competitive intensity centers on API sourcing security and transdermal manufacturing scale-up investments.
Within the integrated producer tier, Boehringer Ingelheim exemplifies backward integration through captive cultivation partnerships in Eastern Europe, securing raw scopolamine alkaloid streams that bypass concentrated botanical extraction vulnerabilities. Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Ltd. represent contrasting geographic archetypes: the former leverages vertical control into tablet and patch finishing from established manufacturing bases, while the latter anchors cost-optimized injectable capacity serving institutional buyers across emerging markets. These three companies collectively illustrate how API access and formulation specialization determine competitive positioning.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Baxter International |
| GSK plc |
| Sun Pharmaceutical Industries Ltd. |
| Caleb Pharmaceuticals, Inc. |
| Perrigo Company plc |
| Cipla Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap alkaloid processors in Eastern Europe anchor supply-side discipline, translating cultivation network control into premium pricing power for transdermal patch feedstocks while squeezing margin pools for non-integrated tablet finishers.
Pricing Analysis
Volume concentration in injectable hyoscine butylbromide tablets runs counter to margin capture in transdermal patch formulations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated patch suppliers from CDSCO-registered generic tablet producers and unbranded oral solution dispensaries. Pricing pressure stems from ambulatory surgical center buying consortia extracting volume discounts through direct manufacturer contracts. Cost-pressured institutional buyers across South Asia and Africa exhibit highest price sensitivity; Japanese PMDA-certified patch manufacturers command lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German and French pharmaceutical manufacturers mandate multi-supplier qualification for scopolamine alkaloid streams. Feedstock extraction concentrates in Bulgaria, Hungary, and Serbia, with Swissmedic-certified toll processors in Basel providing quality-gate functionality. Raw material dependencies encompass Datura biomass cultivation, supercritical CO2 extraction equipment, and rate-controlling membrane polymers. Single-source vulnerability in Eastern European botanical networks creates structural exposure. Distribution runs through direct manufacturer contracts with ambulatory surgical center networks, displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyoscine manufacturing is consolidating around API-provenance capabilities as FDA bioequivalence tightening forces sub-scale producers toward exit or acquisition.
For Market Incumbents: Deploy captive cultivation partnerships as the anchor defensive move. Boehringer Ingelheim's Eastern European sourcing model provides template for backward integration into alkaloid supply. Teva Pharmaceutical Industries should extend patch manufacturing scale-up investments to defend against emerging transdermal specialists. Sun Pharmaceutical Industries must reinforce cost-optimized injectable capacity against Indian CDSCO-registered competitors. For New Entrants and Emerging Players: Direct-to-home-care digital channels offer lowest friction entry path. Online pharmacy fulfillment models bypass wholesale distribution markups and capture post-acute administration shift. Target gastrointestinal spasmolysis indications for functional dyspepsia protocols; this segment remains underpenetrated relative to antiemetic applications. White-label patch manufacturing for regional ASC chains provides fastest revenue validation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap patch finishers with Swissmedic toll-processing relationships in Baden-Württemberg and Basel corridors. Long-term viability hinges on transdermal manufacturing scale-up capabilities and documented API provenance. Watch EMA centralized marketing authorization timelines as inflection indicator for European patch formulation consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivation Partnership | Eastern European Datura networks secure alkaloid supply against botanical extraction bottlenecks. |
| Transdermal Patch Scale-Up | Specialized adhesive matrix investments enable 72-hour steady-state delivery for ASC protocols. |
| Swissmedic Toll Processing Certification | Basel-area quality gates unlock EMA centralized marketing authorization for EU patch formulations. |
| Direct ASC Contracting | Southeastern United States buying consortia negotiate formulary exclusivity for volume commitments. |
| Home Care Channel Expansion | Patient-direct fulfillment models capture post-acute administration shift outside inpatient wards. |
Methodological Framework
Multi-period observation of FDA bioequivalence filing patterns and EMA centralized marketing authorization timelines anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Secondary validation drew from FDA Orange Book listings, EMA EPAR documents, ClinicalTrials.gov entries, and WHO Essential Medicines List procurement databases. Bottom-up formulation-specific demand modeling triangulated against top-down therapeutic class expenditure analysis.
Segment-weighting across product type, end user, application, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from formulation-specific volume trajectories and pricing elasticity parameters. Modeled inputs encompassed ambulatory surgical center procurement volumes, transdermal patch manufacturing capacity utilization, and hyoscine butylbromide tablet substitution patterns in public health systems.
Inputs from FDA bioequivalence guidance documents and EMA Q&A on botanical drug substances were available through the study window; gaps in real-time ambulatory surgical center purchasing data introduce uncertainty bands around institutional volume forecasts. Deviation in FDA enforcement posture toward generic scopolamine products would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market