
 North America Data Center Power Market | 2026-2036
North America Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Center Power Market Foresight
High-efficiency Tier III and Tier IV power infrastructure is reorganizing procurement priorities across the North America Data Center Power Market. Schneider Electric leverages its integrated electrical distribution portfolio to anchor large-scale deployments in Texas and Arizona. Eaton competes through advanced UPS topology specialization, while Vertiv dominates thermal-electrical co-design for high-density compute environments.
Data center power encompasses the generation, conditioning, distribution, and backup systems that maintain continuous electrical supply to server infrastructure, typically operating at voltages from 480V down to 208V with redundancy configurations from N+1 to 2N. Its primary commercial purpose is eliminating downtime for digital services ranging from financial transactions to streaming media. Liquid cooling integration with power delivery is growing fastest as rack densities exceed 50kW, while traditional air-cooled architectures still occupy the largest installed base. Diesel generator segments face structural pressure from renewable-plus-battery hybrid systems, particularly in jurisdictions with aggressive carbon mandates.
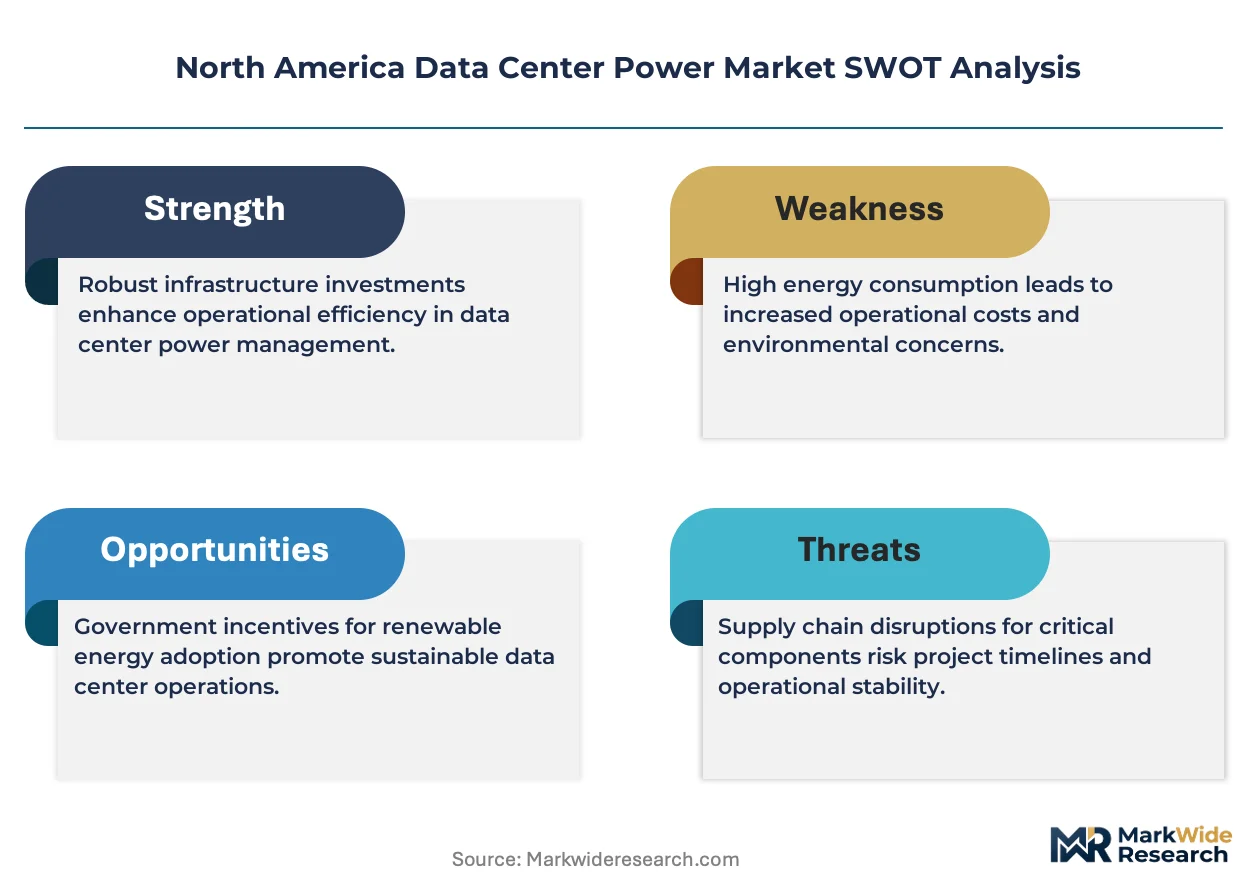
EPA Clean Air Act enforcement and FERC interconnection rules shape backup power technology choices and grid access timelines for new facilities. NERC reliability standards and OSHA electrical safety requirements further constrain equipment specifications and operational protocols. Stakeholders must monitor state-level renewable portfolio standards and utility rate structures as these will determine the economic viability of on-site generation versus grid-dependent architectures.
Market Dynamics
Hyperscale cloud operators are compressing power infrastructure refresh cycles from seven years to three as rack densities exceed 50kW, forcing Tier III and Tier IV redundancy architectures into mid-tier colocation facilities previously served by N+1 designs.
Growth Catalysts
- State-Level Clean Energy Mandates:California's SB 100 and New York's CLCPA are accelerating diesel-to-battery transitions in backup power architectures.
- Liquid Cooling Convergence:Direct-to-chip cooling systems are unlocking 100kW-plus rack densities that demand specialized 415V three-phase distribution.
- Northern Virginia Cluster Expansion:Loudoun County's data center corridor is absorbing 35% of new North American power infrastructure investment.
Market Restraints
- Copper and Silicon Carbide Cost Volatility:Raw material swings are compressing margins on UPS and PDU assemblies by 8-12 percentage points.
- FERC Interconnection Queues:Grid connection timelines stretching 36-48 months are delaying greenfield facility energization across ERCOT and PJM territories.
- Transformer Manufacturing Concentration:Domestic production capacity for medium-voltage transformers is concentrated among three suppliers, creating 18-month lead time exposure.
Strategic Opportunities
- IRA Clean Energy Tax Credits:The Inflation Reduction Act's standalone storage credit is making solar-plus-battery hybrids economically viable against diesel gensets.
- Edge Computing Micro-Grids:Distributed AI inference nodes in secondary metros require sub-1MW modular power skids with integrated fuel cells.
- Texas ERCOT Ancillary Services:Grid-interactive UPS systems can capture frequency regulation revenue streams during non-outage periods.
Industry Challenges
- Medium-Voltage Electrical Engineering Talent Scarcity:Utilities and hyperscalers are competing for the same 15,000 qualified substation designers across the continent.
- UL 9540A Fire Safety Certification:Large-format lithium-ion battery deployments face 14-18 month testing timelines that mismatch construction schedules.
- Legacy 480V Infrastructure Stranding:Retrofitting existing facilities for 415V IT equipment requires complete switchgear replacement with 6-9 month outage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Center Power Market |
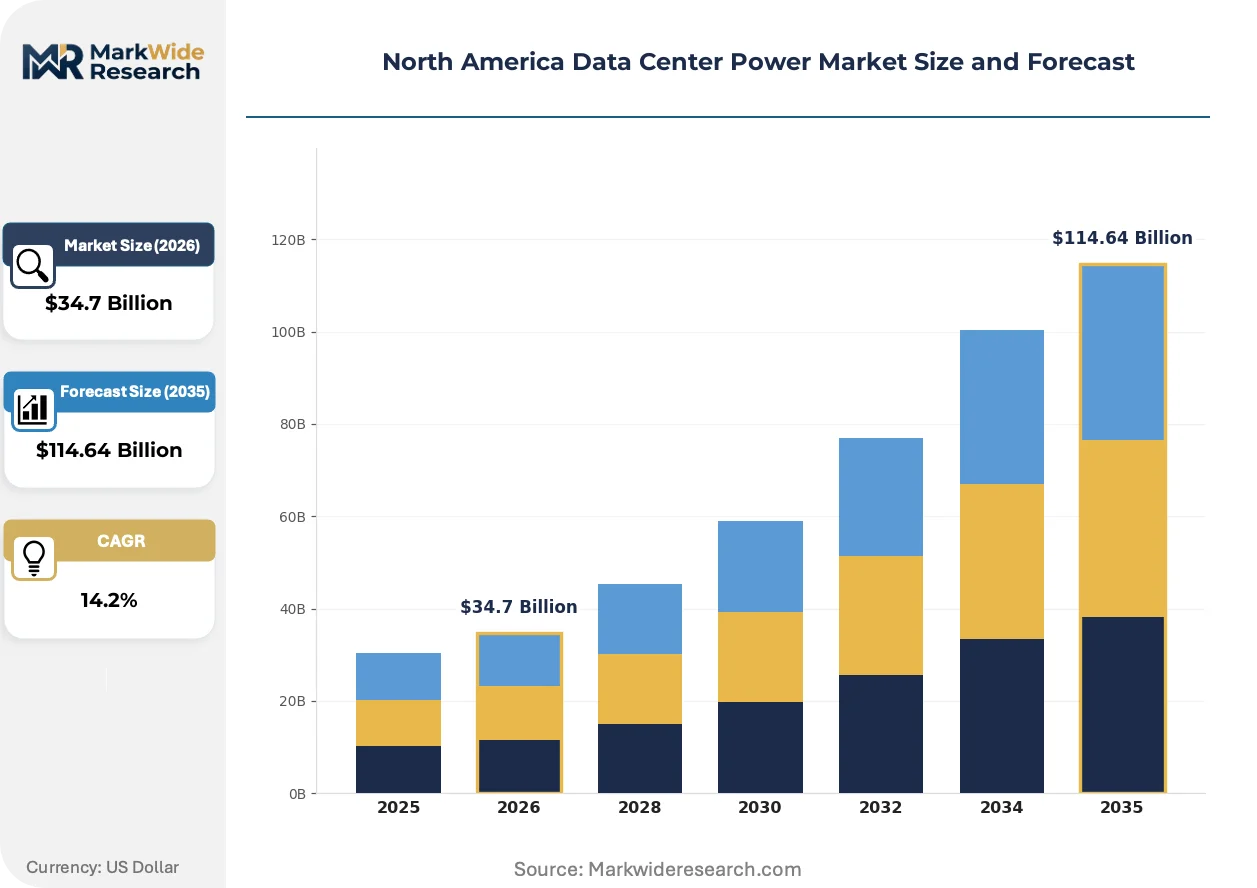
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $114.64 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Grid, Renewable Energy, Diesel Generator, UPS Cooling Method: Air Cooling, Liquid Cooling, Evaporative Cooling, Immersion Cooling Infrastructure Type: Modular Data Centers, Containerized Data Centers, Traditional Data Centers, Edge Data Centers Service Model: Colocation, Managed Services, Cloud Services, Dedicated Hosting |
| Companies Covered | ABB, LITEON Technology, Schneider Electric, Generac Power Systems, Siemens, Vertiv, Delta Electronics, Caterpillar, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Center Power Market Shifts & Advancements
Power infrastructure is fragmenting into disaggregated subsystems as software-defined control layers decouple from hardware, enabling granular optimization of energy flows across generation, storage, and distribution.
Busway power distribution is decomposing traditional PDU hierarchies by delivering 415V directly to rack rows through overhead copper busbars with tap-off boxes. Hyperscale operators in Phoenix and Dallas-Fort Worth are deploying this architecture at 50MW-plus facilities to eliminate floor-level cable congestion. The technology is decomposing the conventional three-tier power path—substation, PDU, RPP—into a two-tier model that cuts copper tonnage by 40%.
EPA Clean Air Act Tier 4 Final standards are prohibiting non-emergency diesel generator operation in non-attainment zones without exhaust after-treatment. Operators in Maricopa County and the Dallas-Fort Worth metroplex are responding with renewable-plus-battery hybrids sized for 4-hour ride-through, displacing gensets for 95% of runtime hours. The regulation is compressing backup power procurement into integrated micro-grid tenders rather than standalone generator purchases.
Power Purchase Agreement structures are migrating from volumetric to capacity-based pricing as utilities recover fixed grid costs. Colocation providers in Northern Virginia are absorbing demand charges that now constitute 60% of delivered power costs, forcing pass-through contract renegotiation with enterprise tenants. This shift is most visible among multi-tenant facilities serving financial services and SaaS customers with flat-rate pricing commitments.
North America Data Center Power Market Segmentation
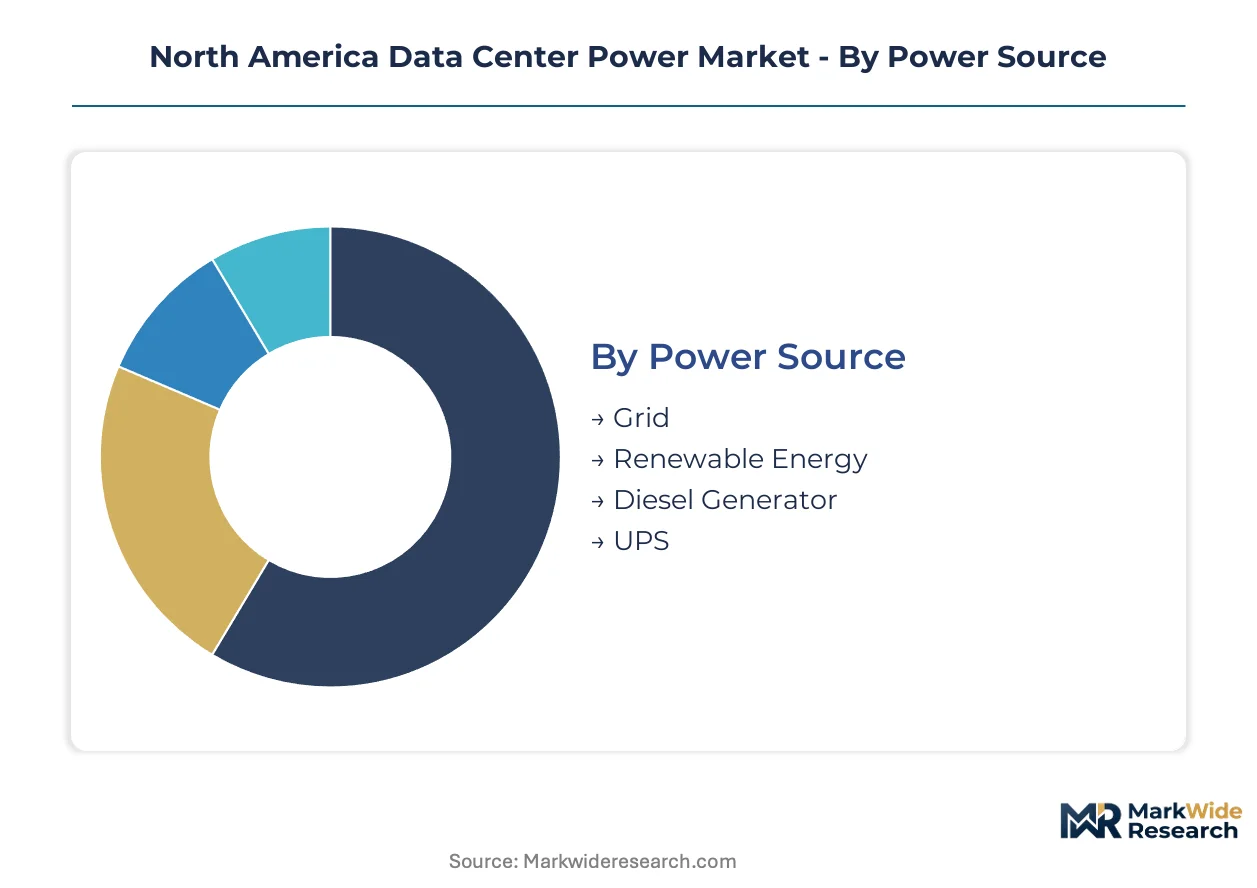
Power infrastructure procurement in North America fragments across four critical dimensions: energy sourcing strategy, thermal management approach, facility architecture, and commercial service structure. Each segmentation axis carries distinct regulatory exposure and capital intensity profiles that reshape vendor selection and deployment timelines.
Power Source:
EPA emissions standards and state renewable mandates create divergent compliance burdens across backup and primary generation technologies.
- Grid:Utility-delivered power remains the baseline for hyperscale facilities in Northern Virginia and Dallas-Fort Worth, though FERC interconnection queues stretching 36-48 months now constrain expansion velocity for new campuses.
- Renewable Energy:Solar-plus-battery hybrids sized for 4-hour ride-through are displacing diesel gensets in California and New York markets where SB 100 and CLCPA mandates apply; IRA standalone storage credits accelerate project economics.
- Diesel Generator:EPA Tier 4 Final standards prohibit non-emergency operation in non-attainment zones without exhaust after-treatment, compressing procurement into integrated micro-grid tenders rather than standalone purchases.
- UPS:Grid-interactive double-conversion systems in Texas ERCOT territories capture frequency regulation revenue during non-outage periods, converting backup assets into revenue generators.
Grid handles the majority of throughput; renewable energy is expanding most quickly on share as carbon mandates harden.
Cooling Method:
Rack density thresholds above 50kW are collapsing traditional thermal boundaries and forcing voltage architecture changes.
- Air Cooling:Legacy 480V infrastructure serving sub-30kW racks still dominates the installed base across Phoenix and Dallas-Fort Worth, though retrofit requirements for 415V compatibility strand significant capital.
- Liquid Cooling:Direct-to-chip systems unlocking 100kW-plus densities demand specialized 415V three-phase distribution; hyperscale operators in Loudoun County and Maricopa County are standardizing this topology for new builds.
- Evaporative Cooling:Water-scarce jurisdictions in Arizona and Texas limit deployment despite efficiency advantages, requiring alternative thermal strategies during drought declarations.
- Immersion Cooling:Dielectric fluid baths for extreme density AI training clusters remain niche, concentrated in specialized HPC facilities with custom electrical safety certifications.
Air cooling manages the largest installed footprint; liquid cooling commands the steepest expansion trajectory as AI workloads proliferate.
Infrastructure Type:
Deployment velocity and site control requirements determine capital structure and operational flexibility.
- Modular Data Centers:Factory-integrated power and cooling skids compress construction timelines to 12-18 months, appealing to cloud operators racing against interconnection delays in PJM and ERCOT territories.
- Containerized Data Centers:ISO-standard enclosures with pre-integrated 1-2MW power modules serve distributed AI inference nodes in secondary metros requiring sub-1MW modular skids with fuel cell integration.
- Traditional Data Centers:Stick-built facilities with centralized substations remain preferred for 50MW-plus campuses in Northern Virginia, though 6-9 month outage windows complicate 480V-to-415V retrofits.
- Edge Data Centers:Sub-500kW deployments in secondary markets prioritize rapid energization over efficiency, accepting higher per-kW power costs for proximity to latency-sensitive applications.
Traditional data centers absorb the bulk of capital deployment; modular data centers are climbing fastest as speed-to-market tightens.
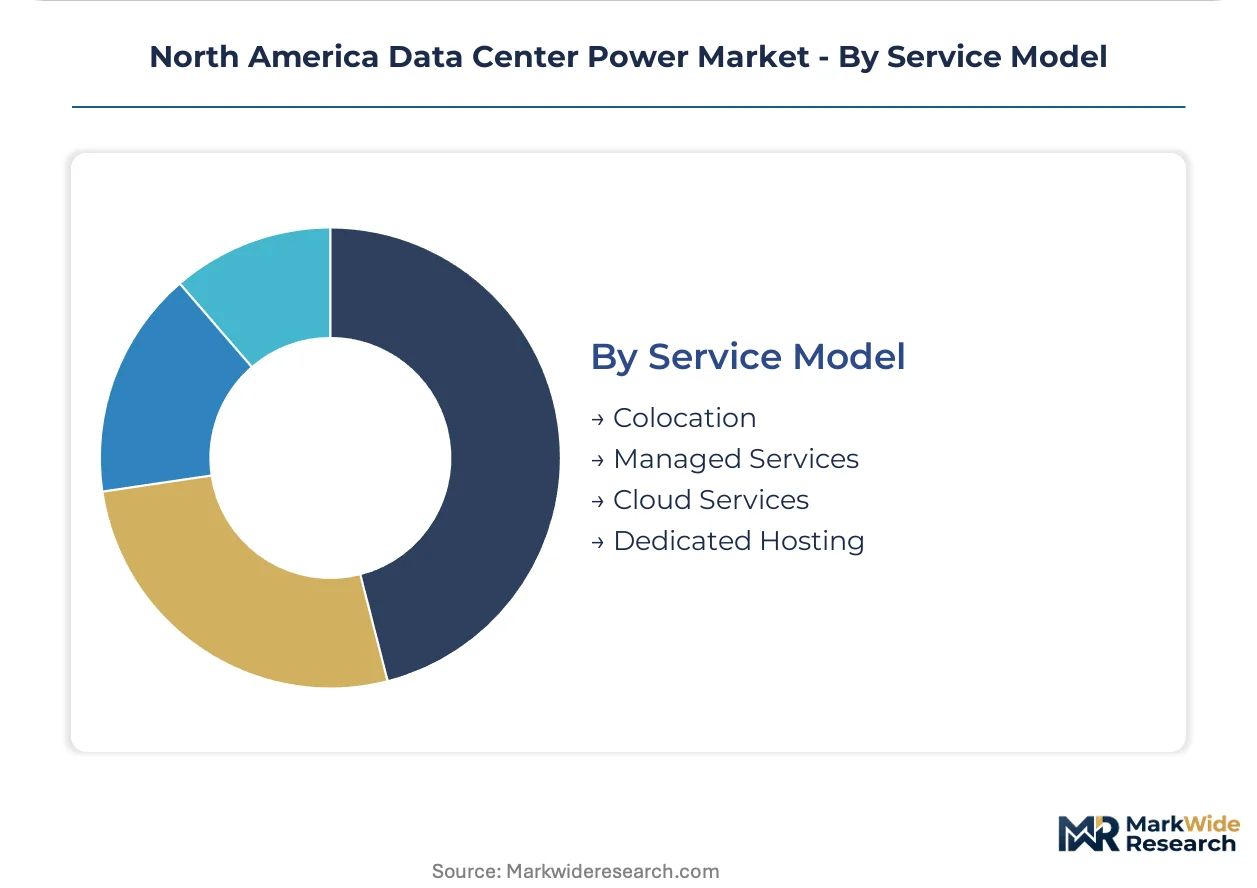
Service Model:
Utility rate structure migration from volumetric to capacity-based pricing reshapes contract economics and tenant pass-through exposure.
- Colocation:Multi-tenant facilities in Northern Virginia absorb demand charges now constituting 60% of delivered power costs, forcing contract renegotiation with financial services and SaaS tenants holding flat-rate commitments.
- Managed Services:Third-party operation of customer-owned infrastructure transfers power procurement risk to specialists with aggregated purchasing leverage across multiple facilities.
- Cloud Services:Hyperscale self-operated campuses in Texas and Arizona optimize power sourcing through direct utility negotiations and on-site generation, bypassing retail rate structures entirely.
- Dedicated Hosting:Single-tenant facilities for regulated industries maintain N+1 to 2N redundancy architectures with dedicated substations, insulating critical workloads from shared infrastructure risk.
Cloud services drive the largest absolute infrastructure investment; colocation faces the most acute margin pressure from utility rate redesign.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medium-voltage transformer manufacturing and electrical engineering talent pool heavily concentrate in the United States, though Canadian provinces and Mexican border states are capturing spillover investment from interconnection-constrained developers.
United States
EPA Tier 4 Final standards and FERC interconnection queues stretching 36-48 months are compressing backup power procurement timelines across Texas and Virginia. The Inflation Reduction Act's standalone storage credits accelerate solar-plus-battery hybrid economics against diesel gensets. Northern Virginia's Loudoun County corridor absorbs 35% of new continental power infrastructure investment.
Canada
Provincial clean electricity standards in Ontario and Quebec are attracting hyperscale operators seeking carbon-free grid supply for AI training clusters. Health Canada and Environment and Climate Change Canada coordinate on battery safety certifications for large-format lithium deployments. Toronto-Waterloo corridor facilities leverage Niagara hydroelectric baseload for 24/7 carbon-free compute.
Mexico
Nearshoring manufacturing demand and cross-border fiber latency advantages are driving edge data center power module imports to Nuevo León and Baja California. CFE interconnection reform discussions aim to reduce 18-24 month energization timelines for industrial campuses. Querétaro's aerospace and automotive supplier ecosystem is spawning distributed 1-5MW facilities with modular skid-mounted UPS.
North America Data Center Power Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American data center power market. The vendor structure organizes into three functional tiers: integrated electrical distribution platforms, specialized UPS topology developers, and thermal-electrical co-design specialists. Strategic moves concentrate on micro-grid integration partnerships and silicon carbide supply chain anchoring.
Within the integrated platform tier, Schneider Electric and Eaton exemplify contrasting approaches to electrical infrastructure monetization. Vertiv occupies a position bridging power and thermal optimization for high-density compute environments. Among backup power specialists, Generac Power Systems and Caterpillar represent diesel-to-hybrid transition archetypes facing EPA emissions compliance pressure. ABB and Siemens anchor the medium-voltage switchgear and transformer segment where domestic manufacturing concentration creates 18-month lead time exposure.
| Leading Market Players |
|---|
| ABB |
| LITEON Technology |
| Schneider Electric |
| Generac Power Systems |
| Siemens |
| Vertiv |
| Delta Electronics |
| Caterpillar |
| Eaton |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts lock in transformer supply slots 18-24 months ahead while freezing copper and silicon carbide pricing bands, giving hyperscale operators cost visibility against raw material volatility in ERCOT and PJM territories.
Pricing Analysis
EPA Tier 4 Final standards dictate the pricing tier structure across backup power procurement, separating integrated micro-grid tenders with renewable-plus-battery hybrids from standalone diesel generator purchases. Three-tier pricing stratifies across Tier IV-certified premium systems, Tier III-compliant standard architectures, and legacy N+1 economy configurations. Cost compression in the standard tier is intensifying because FERC interconnection queues delay facility energization and extend carrying costs. Colocation providers absorbing demand charges show highest price sensitivity, while hyperscale self-operated campuses with direct utility negotiations exhibit lowest.
Supply Chain Analysis
Domestic medium-voltage transformer manufacturing concentration among three suppliers creates an 18-month lead time chokepoint that constrains greenfield facility deployment across Northern Virginia and Dallas-Fort Worth. Copper busbar and silicon carbide semiconductor supply draws from Mexico, Canada, and domestic foundries. Single-source vulnerability in electrical steel laminations feeds from concentrated North American rolling capacity. Distribution runs through direct OEM relationships with hyperscale operators and tier-one EPC contractors rather than distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Data Center Power Market represents a high-growth disruption as liquid cooling convergence above 50kW rack densities forces complete voltage architecture transitions from 480V to 415V three-phase distribution.
For Market Incumbents: Consolidate silicon carbide supply chain anchoring through long-term offtake agreements with domestic semiconductor foundries, insulating against raw material cost swings compressing UPS and PDU margins. Deepen backward integration into medium-voltage transformer manufacturing capacity to bypass 18-month lead time exposure from concentrated suppliers. Defend against modular power skid entrants by embedding software-defined control layers that decouple from hardware. For New Entrants and Emerging Players: Lead with edge computing micro-grid deployments in secondary metros where sub-1MW modular skids with integrated fuel cells address latency-sensitive AI inference demand. Target the containerized data center segment in Nuevo León and Querétaro where nearshoring manufacturing demand outpaces established supplier presence. Pursue Texas ERCOT ancillary services revenue capture through grid-interactive UPS systems as the primary go-to-market angle. For Investors and Strategic Acquirers: Thermal-electrical co-design specialists with liquid cooling integration capabilities offer the strongest acquisition profile for AI workload proliferation. Long-term viability hinges on positioning for 100kW-plus rack density standardization across hyperscale campuses. Watch FERC interconnection queue resolution timelines as the critical inflection signal determining greenfield deployment velocity and capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Anchoring | Long-term semiconductor foundry offtake secures power electronics cost visibility against raw material volatility. |
| Modular Micro-Grid Deployment | Factory-integrated power skids compress construction timelines to circumvent FERC interconnection delays. |
| Liquid Cooling Voltage Transition | 415V three-phase distribution standardization captures hyperscale demand for 100kW-plus rack densities. |
| Grid-Interactive UPS Integration | ERCOT frequency regulation revenue streams convert backup assets from cost centers to profit generators. |
| Renewable-Plus-Battery Hybrid Sizing | IRA standalone storage credits accelerate solar-plus-battery economics against EPA Tier 4 Final diesel constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center facility managers, electrical engineering directors at hyperscale operators, EPC contractor project leads, and utility interconnection planners. Secondary validation drew from FERC interconnection queue filings, EPA Clean Air Act enforcement records, EIA electricity market data, and hyperscaler capital expenditure disclosures. Bottom-up facility deployment tracking and top-down regional investment aggregation were triangulated to establish market sizing.
Across the analysis window, the forecast framework models power infrastructure investment by power source topology, cooling method integration, infrastructure deployment architecture, and commercial service structure. CAGRs were derived from facility pipeline tracking against energization timelines. Key inputs include transformer manufacturing capacity utilization, silicon carbide wafer supply expansion, and state-level renewable portfolio standard enforcement trajectories.
Forecasts assume regulatory continuity in EPA Tier 4 Final standards and IRA clean energy credit structures; material policy shifts would require re-modeling backup technology economics and solar-plus-battery hybrid viability. Practitioners should keep alternative scenarios live as FERC interconnection queue reform and state carbon mandate acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Middle East Data Center Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
Malaysia Data Center Power Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
Hong Kong Data Center Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
APAC Green Data Center Market