
 IT Infrastructure Management Tools Market | 2026-2036
IT Infrastructure Management Tools Market Size, Share, and Industry Trends Forecast 2026-2036
IT Infrastructure Management Tools Market Foresight
Cloud hyperscaler capacity buildouts across Northern Virginia, Frankfurt, and Singapore is realigning how enterprises provision and monitor distributed infrastructure. Datadog leverages native integration density to sustain platform stickiness among DevOps teams. Dynatrace anchors its position through AI-powered root-cause analytics that reduce mean-time-to-resolution for complex microservices environments. ManageEngine OpManager competes aggressively on price-performance for mid-market network operations centers across Asia-Pacific and Latin American markets.
IT Infrastructure Management Tools encompass software systems that discover, monitor, automate, and govern computing, storage, network, and application resources across heterogeneous environments, typically supporting SNMP, WMI, REST API, and agent-based telemetry collection at sub-minute polling intervals. These tools serve the primary commercial purpose of ensuring service availability, optimizing resource utilization, and enforcing configuration compliance across on-premises, cloud, and edge deployments. Monitoring Tools currently occupy the largest revenue share as legacy datacenter estates persist alongside cloud migration, while Automation Solutions represent the fastest-expanding segment as platform engineering teams prioritize infrastructure-as-code and self-healing workflows. Cloud-based technology deployment is displacing on-premises installations in net-new procurement, though Hybrid architectures retain durable demand from regulated industries requiring data sovereignty controls.
The EU AI Act, NIS2 Directive, and GDPR collectively shape product roadmaps by mandating algorithmic transparency, incident reporting timelines, and cross-border data governance capabilities that vendors must embed natively. In the United States, the SEC cybersecurity disclosure rules and NIST Cybersecurity Framework drive C-suite accountability for infrastructure risk visibility, expanding budget allocation toward integrated observability suites. Stakeholders must evaluate whether their tooling stacks can satisfy converging operational resilience and sustainability reporting requirements without fragmenting into disconnected point solutions.
Market Dynamics
The convergence of distributed cloud architectures and algorithmic transparency mandates is compressing procurement cycles for integrated observability platforms. Financial services and automotive manufacturers now demand unified telemetry across hybrid estates to satisfy operational resilience requirements.
Growth Catalysts
- NIS2 Directive compliance deadlines:European critical infrastructure operators must deploy continuous monitoring by October 2024, accelerating replacement of legacy siloed tools with unified platforms.
- Automotive IT modernization:German OEMs are overhauling manufacturing execution systems to support software-defined vehicle pipelines, driving tooling procurement for edge-to-cloud visibility.
- AI-powered root-cause analytics:Platform engineering teams prioritize autonomous incident resolution capabilities that compress mean-time-to-recovery for microservices failures.
Market Restraints
- Specialized talent scarcity:SRE and platform engineering skill shortages in Frankfurt and Singapore inflate implementation costs and extend deployment timelines.
- Hybrid architecture complexity:Data sovereignty requirements force regulated banks and healthcare providers to maintain fragmented on-premises estates alongside cloud workloads.
- API rate limiting constraints:Cloud hyperscaler throttling policies restrict polling frequency for large-scale infrastructure discovery, degrading real-time visibility.
Strategic Opportunities
- Industrial edge expansion:Japanese and South Korean manufacturing conglomerates are deploying predictive maintenance platforms at plant level, creating demand for lightweight agent architectures.
- Sustainability telemetry integration:CSRD mandates require granular carbon accounting for IT estates, positioning infrastructure management tools as compliance infrastructure.
- FinOps capability convergence:Cloud cost optimization modules are merging with traditional monitoring, enabling vendors to capture budget allocation workflows previously owned by standalone tools.
Industry Challenges
- Fragmented toolchain consolidation:Enterprise buyers struggle to rationalize overlapping point solutions for APM, infrastructure monitoring, and log analytics without service disruption.
- Agent deployment at scale:Containerized and serverless environments complicate instrumentation coverage, leaving visibility gaps in ephemeral compute resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Infrastructure Management Tools Market |
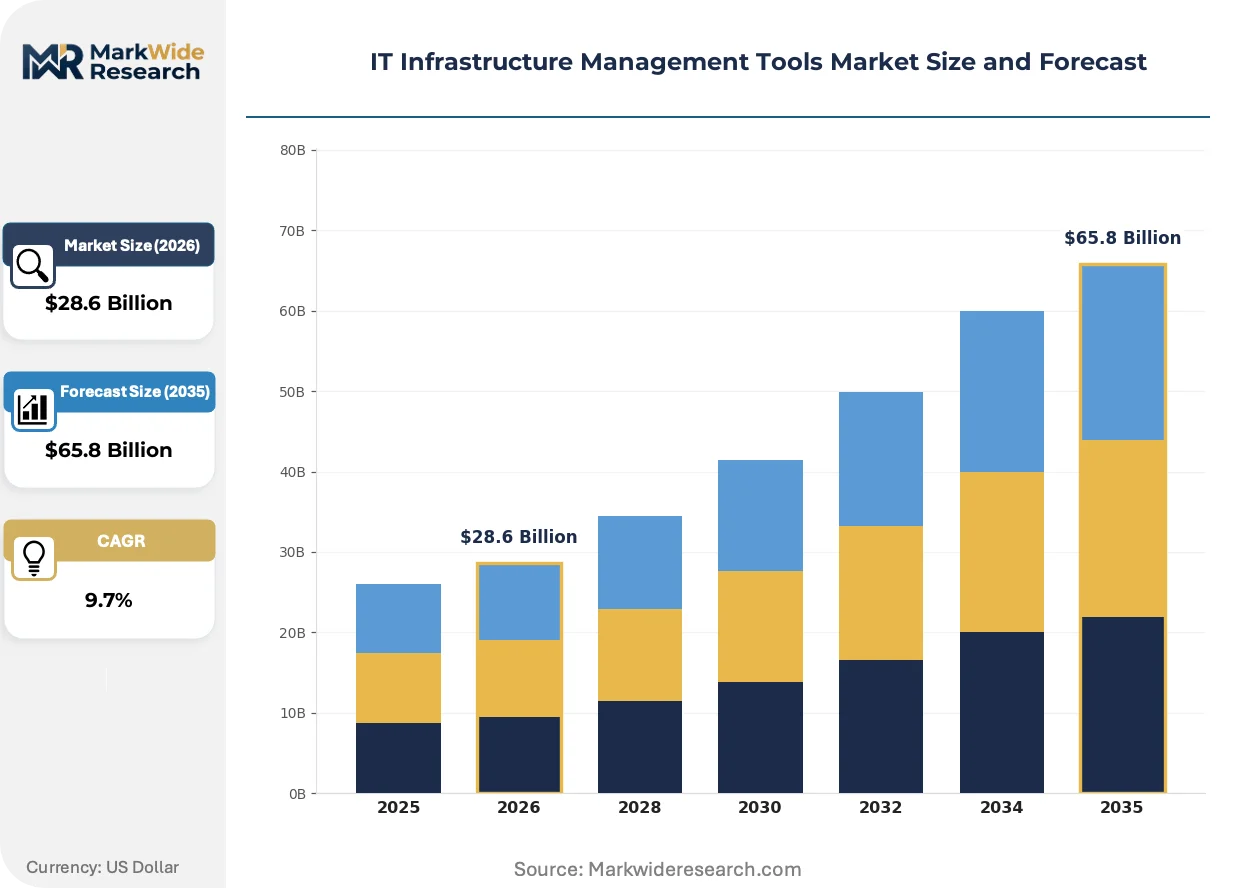
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Tools, Automation Solutions, Configuration Management, Network Management End User: Corporations, SMEs, Managed Service Providers, Government Agencies Technology: Cloud-based, On-premises, Hybrid, Virtualization Solution: Incident Management, Performance Management, Capacity Planning, Patch Management |
| Companies Covered | Dynatrace, Site24x7, Datadog, Sysdig Monitor, Infraon Infinity, ManageEngine OpManager, Splunk Observability Platform, Ivanti Neurons, New Relic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Infrastructure Management Tools Market Shifts & Advancements
OpenTelemetry standardization is collapsing proprietary instrumentation silos, forcing vendors to differentiate on analytics layers rather than data collection lock-in. This shift is redrawing competitive boundaries across the observability stack.
eBPF kernel instrumentation is electrifying how platforms capture system-level telemetry without agent overhead. Cloud-native enterprises in Northern Virginia and Singapore are adopting eBPF-based security and performance monitoring at production scale. This technology is compressing the traditional agent deployment model and enabling sub-second latency for distributed tracing.
The EU AI Act's risk classification framework is mandating algorithmic audit trails for automated infrastructure remediation systems. Vendors must now embed explainability modules that document why autonomous scaling or healing decisions occurred. Financial services operators in Frankfurt and Amsterdam are prioritizing vendors with native compliance documentation to satisfy supervisory scrutiny.
Platform engineering teams are consolidating vendor relationships around full-stack observability suites that span infrastructure, applications, and business metrics. Mid-market enterprises previously buying point solutions for network, server, and cloud monitoring are now demanding unified contracts with single-pane-of-glass interfaces. This preference shift is most visible in German automotive supply chains and US healthcare systems undergoing digital transformation.
IT Infrastructure Management Tools Market Segmentation
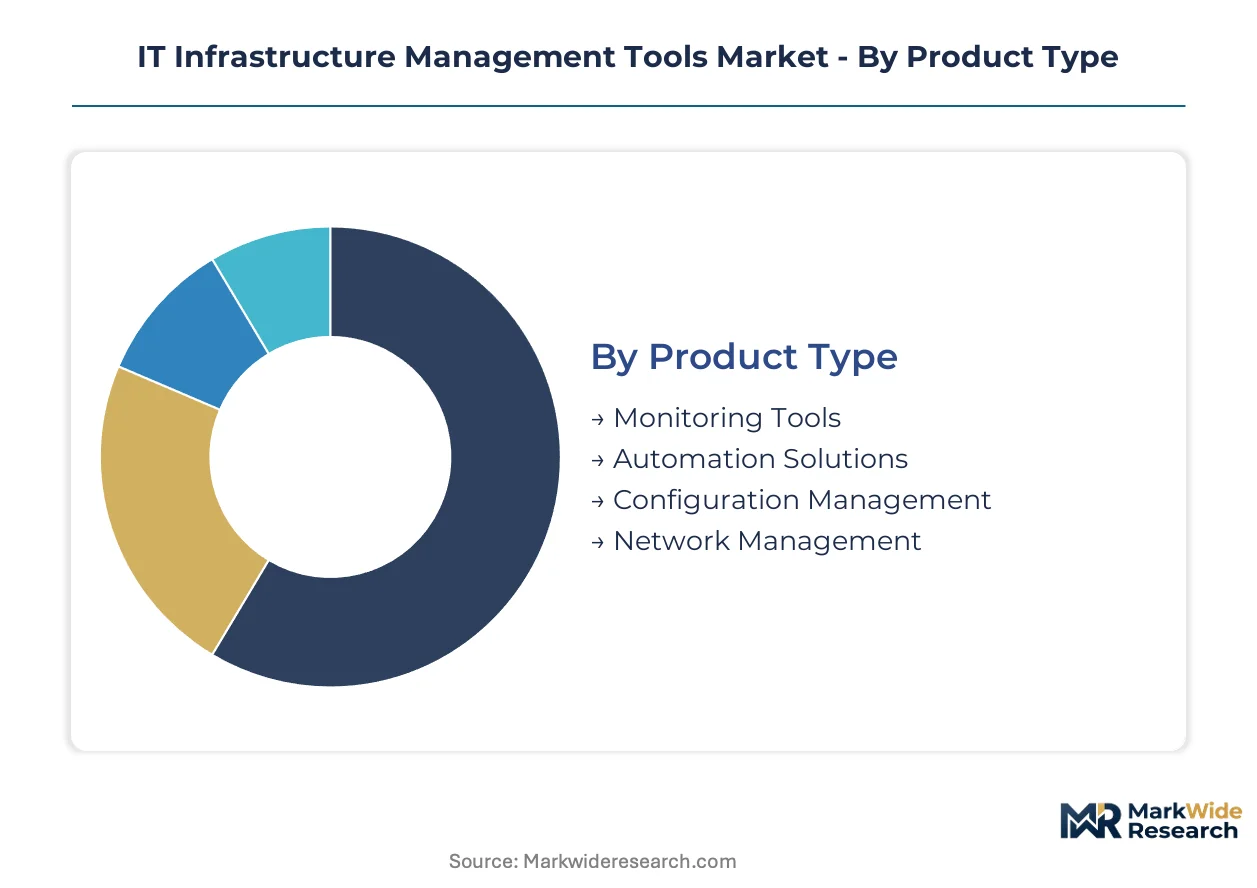
IT infrastructure management tools fragment across four critical dimensions that determine procurement priorities and vendor positioning. Upgrade cycles and architectural transitions create divergent demand patterns across product types, end-user scale, deployment models, and functional solutions.
Product Type:
Replacement timelines compress as legacy datacenter estates coexist with cloud-native workloads, forcing enterprises to rationalize overlapping tool investments.
- Monitoring Tools:These platforms deliver continuous visibility through SNMP, WMI, REST API, and agent-based telemetry collection at sub-minute polling intervals. Financial services operators in Frankfurt and Singapore deploy these for distributed cloud observability to satisfy NIS2 Directive mandates. Volume placements concentrate in Monitoring Tools; the faster expansion belongs to Automation Solutions.
- Automation Solutions:Infrastructure-as-code engines and self-healing workflows enable autonomous provisioning, configuration drift remediation, and policy-driven orchestration across heterogeneous estates. Platform engineering teams in German automotive supply chains prioritize these capabilities to compress deployment cycles for software-defined vehicle pipelines. These solutions are gaining share fastest as DevOps practices mature.
- Configuration Management:Baseline enforcement and drift detection systems maintain desired-state compliance across server, network, and cloud resource inventories.
- Network Management:Traffic analysis, topology mapping, and fault correlation tools address connectivity visibility in hybrid architectures spanning on-premises and cloud networks.
Procurement concentrates in monitoring platforms; automation capabilities show the steepest expansion trajectory.
End User:
Customer scale determines contract structure, with volume discounts and managed service packaging creating distinct commercial tiers.
- Corporations:Large enterprises demand full-stack observability suites with single-pane-of-glass interfaces spanning infrastructure, applications, and business metrics. US healthcare systems undergoing digital transformation consolidate vendor relationships around unified contracts that reduce toolchain fragmentation. Revenue concentrates in this segment due to multi-year enterprise licensing.
- SMEs:Mid-market buyers prioritize price-performance and rapid deployment without specialized SRE talent. ManageEngine OpManager and similar platforms capture this demand across Asia-Pacific and Latin American markets through aggressive pricing and pre-configured monitoring templates. This segment expands most quickly as cloud-native tooling lowers entry barriers.
- Managed Service Providers:Multi-tenant architectures and white-label capabilities enable outsourced infrastructure operations for client portfolios.
- Government Agencies:Sovereign cloud requirements and classified workload constraints drive specialized procurement with enhanced security certifications.
Enterprise contracts dominate absolute spend; SME adoption climbs fastest as cloud delivery models proliferate.
Technology:
Deployment architecture choices reflect data sovereignty requirements, latency constraints, and regulatory jurisdiction.
- Cloud-based:SaaS delivery eliminates infrastructure overhead and enables elastic scaling for variable monitoring loads. Net-new procurement favors this model as hyperscaler capacity buildouts in Northern Virginia, Frankfurt, and Singapore provide regional low-latency endpoints. Volume concentrates here for greenfield deployments.
- Hybrid:Split telemetry processing with edge collection and cloud analytics satisfies regulated industries requiring on-premises data retention. European banks and healthcare providers maintain this architecture to satisfy GDPR and operational resilience mandates. Hybrid retains durable demand despite cloud momentum.
- On-premises:Air-gapped installations persist in defense, critical infrastructure, and jurisdictions with data localization laws.
- Virtualization:Hypervisor-integrated monitoring addresses VM sprawl and resource contention in legacy datacenter estates.
Cloud deployments capture majority net-new procurement; hybrid architectures sustain steady replacement demand.
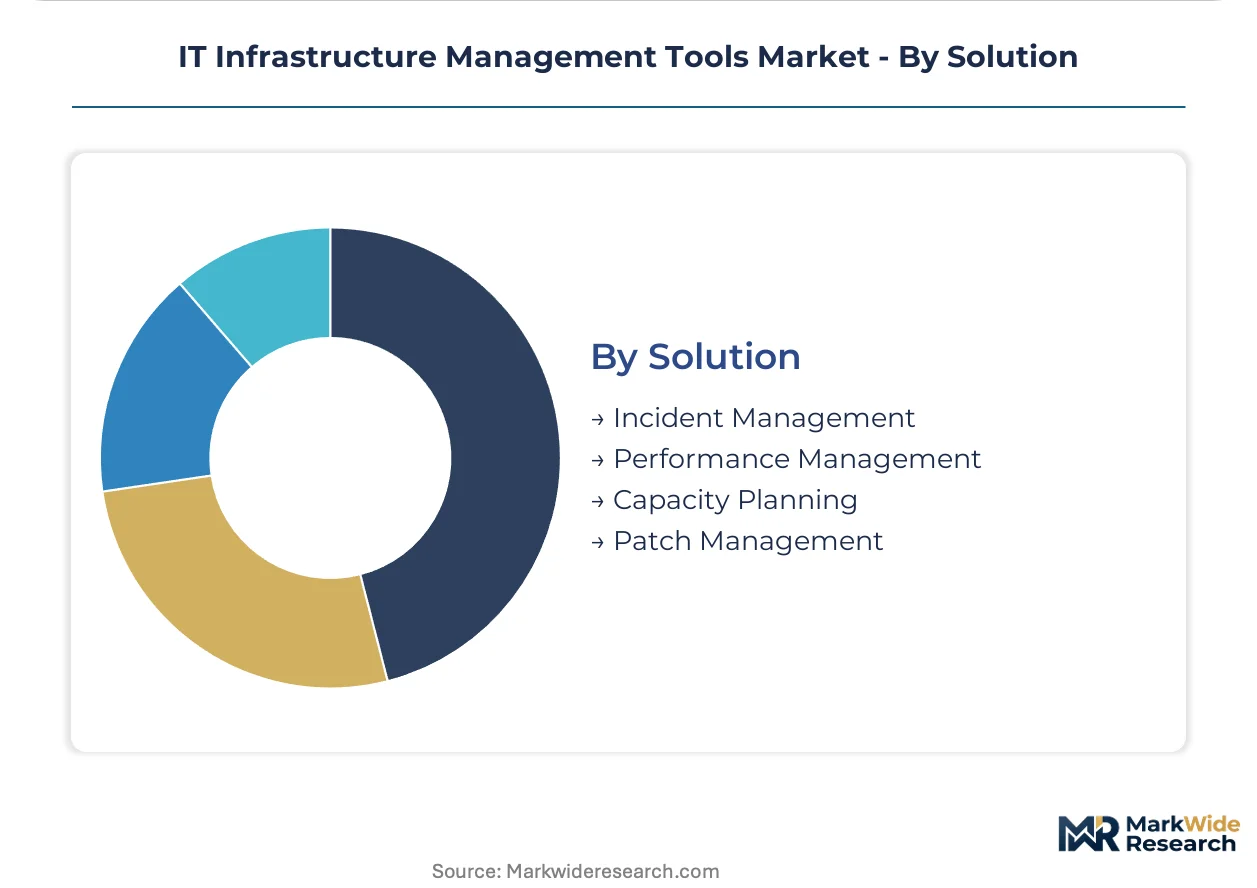
Solution:
Functional modules align with operational workflows, from reactive incident response to proactive capacity optimization.
- Incident Management:Alert correlation, on-call routing, and war-room orchestration compress mean-time-to-resolution for service disruptions. AI-powered root-cause analytics from Dynatrace and similar platforms differentiate this capability for complex microservices environments. This solution category anchors platform stickiness.
- Performance Management:SLA tracking, anomaly detection, and user experience monitoring ensure service quality across distributed architectures. Financial services firms in Amsterdam deploy these capabilities to satisfy SEC cybersecurity disclosure rules and NIST Cybersecurity Framework accountability requirements. This segment shows accelerating expansion.
- Capacity Planning:Predictive modeling and resource forecasting prevent over-provisioning and cloud cost overruns.
- Patch Management:Vulnerability remediation orchestration and compliance reporting address security hygiene at scale.
Incident response capabilities dominate current procurement; performance analytics gain fastest as observability converges with business metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler corridor and Frankfurt's financial hub anchor infrastructure tooling procurement. Cloud capacity buildouts in Northern Virginia, Singapore, and Amsterdam reshape regional demand patterns.
United States
Financial services operators in Manhattan and Northern Virginia deploy observability platforms to satisfy SEC cybersecurity disclosure rules. The NIST Cybersecurity Framework drives C-suite accountability for infrastructure risk visibility. Cloud hyperscalers concentrate capacity in Ashburn and San Jose, compressing procurement cycles for integrated telemetry suites.
Germany
Automotive OEMs in Stuttgart and Munich modernize manufacturing execution systems for software-defined vehicle pipelines. The EU AI Act and NIS2 Directive mandate algorithmic transparency and continuous monitoring for critical infrastructure. Industrial digitization across Bavaria and Baden-Württemberg accelerates edge-to-cloud tooling procurement.
Singapore
Platform engineering teams in the city-state prioritize autonomous incident resolution for microservices failures. The Monetary Authority of Singapore enforces operational resilience standards for financial institutions. Regional cloud hubs attract multinational enterprises seeking low-latency endpoints across Southeast Asia.
United Kingdom
Healthcare systems undergoing digital transformation consolidate vendor relationships around unified observability contracts. The UK National Cyber Security Centre publishes infrastructure security guidelines affecting procurement specifications. London's financial district demands granular carbon accounting telemetry to satisfy emerging sustainability mandates.
Japan
Manufacturing conglomerates in Osaka and Nagoya deploy predictive maintenance platforms at plant level for condition-based monitoring. METI's industrial digitization programs subsidize smart factory infrastructure investments. Lightweight agent architectures gain traction among automotive suppliers seeking edge visibility without datacenter overhead.
IT Infrastructure Management Tools Market Competitive Landscape
Global majors compete with regional champions across integration density and AI-powered analytics. The vendor base stratifies into full-stack observability suites, mid-market price-performance platforms, and specialized container-native tools. Three archetypes dominate: hyperscaler-aligned suites, independent AI-native platforms, and regional managed service enablers. Competitive moves concentrate on strategic partnerships with cloud providers and portfolio expansion through adjacent capability acquisition.
Within the AI-native analytics tier, Dynatrace and Datadog exemplify platform engineering-centric positioning. ManageEngine OpManager occupies the mid-market price-performance segment across Asia-Pacific and Latin American markets. Splunk Observability Platform represents the convergence archetype where security and infrastructure telemetry merge into unified data lakes.
| Leading Market Players |
|---|
| Dynatrace |
| Site24x7 |
| Datadog |
| Sysdig Monitor |
| Infraon Infinity |
| ManageEngine OpManager |
| Splunk Observability Platform |
| Ivanti Neurons |
| New Relic |
| Others |
Supply & Pricing Matrix
eBPF kernel instrumentation adoption is compressing agent-deployment costs while concentrating development talent in Northern Virginia and Singapore, simultaneously lowering marginal delivery economics and tightening supply-side control among vendors with native kernel-level capabilities.
Pricing Analysis
Warranty and managed service bundling separates premium observability contracts from self-hosted deployments. Three-tier pricing structure across premium, standard, and economy levels reflects support SLAs, data retention windows, and AI-powered analytics inclusion. Pricing pressure stems from open-source OpenTelemetry standardization commoditizing data collection layers. SMEs exhibit highest price sensitivity, while financial services operators in Frankfurt prioritize compliance-ready premium tiers regardless of cost.
Supply Chain Analysis
Platform engineering talent scarcity in Frankfurt, Singapore, and Northern Virginia constrains implementation velocity and inflates professional services margins. Development draws from specialized kernel engineering pools, cloud-native certification pipelines, and DevOps consulting networks. Single-source vulnerability concentrates in hyperscaler-dependent SaaS delivery models. Distribution runs through direct enterprise sales, channel partners, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SRE talent bottlenecks in key financial hubs prop vendor pricing power and extend contract durations for implementation-heavy deployments.
For Market Incumbents: Deploy backward integration into specialized kernel engineering capabilities to differentiate as eBPF instrumentation becomes table stakes. Consolidate overlapping point solutions through native AI-powered root-cause analytics that reduce customer toolchain fragmentation. Counter open-source telemetry commoditization by embedding compliance documentation for EU AI Act and NIS2 Directive mandates directly into platform workflows. For New Entrants and Emerging Players: Begin with lightweight agent architectures targeting Japanese and South Korean manufacturing conglomerates deploying predictive maintenance at plant level. Capture mid-market SME demand across Asia-Pacific and Latin American markets through aggressive price-performance positioning against established network operations center platforms. Lead with pre-configured monitoring templates and rapid deployment capabilities that eliminate specialized SRE talent requirements. For Investors and Strategic Acquirers: Re-rating potential sits with AI-native analytics platforms given algorithmic transparency mandates expanding addressable compliance budgets. Long-term viability hinges on convergence of infrastructure observability with FinOps and sustainability telemetry modules. Target acquisition archetypes showing native eBPF instrumentation and embedded explainability for autonomous remediation decisions. Monitor OpenTelemetry adoption velocity as inflection indicator for data collection layer commoditization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified telemetry spanning infrastructure, applications, and business metrics satisfies German automotive supply chain consolidation demands. |
| Acquisition of Specialist Firm | eBPF-native tooling targets cloud-native enterprises in Northern Virginia and Singapore seeking sub-second distributed tracing latency. |
| Strategic Partnership | Hyperscaler marketplace distribution captures net-new cloud procurement cycles across regulated European banking verticals. |
| Product Launch | Explainability modules for autonomous remediation address EU AI Act algorithmic audit trail mandates for Frankfurt financial operators. |
| Geographic Expansion | Edge-to-cloud visibility platforms penetrate Japanese automotive supplier smart factory investments subsidized by METI programs. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents formed the secondary backbone for market sizing and competitive positioning. Primary interviews with platform engineering directors, IT procurement officers, SRE team leads, and channel integration specialists validated deployment timelines and budget allocation patterns. Bottom-up and top-down triangulation cross-checked vendor revenue estimates against enterprise tooling spend surveys.
Bottom-up modeling aggregated individual customer contract values across deployment models, organization sizes, and vertical segments. Segmentation dimensions included technology deployment architecture, end-user scale tier, functional solution module, and regional adoption pattern. CAGRs derived from historical trajectory analysis and forward-looking capacity buildout announcements. Forecast inputs incorporated NIS2 Directive compliance deadline effects and automotive IT modernization pipeline visibility.
Regulatory enforcement delays, hyperscaler API rate limiting policy changes, and open-source instrumentation standardization velocity are the dominant revision risks. Forecasts reflect assumptions around sustained cloud migration momentum and operational resilience mandate adherence timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
South America Data Center Power Market