
 France Data Center Market | 2026-2036
France Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
France Data Center Market Analysis
The EU AI Act is recalibrating capital deployment timelines for French data center operators. OVH Groupe SAS leverages its domestic manufacturing heritage to control server supply chains. Amazon Web Services, Inc. anchors hyperscale expansion through dedicated Paris-Nord zones. DATA4 Group SAS differentiates via sovereign cloud certifications aligned with ANSSI frameworks.
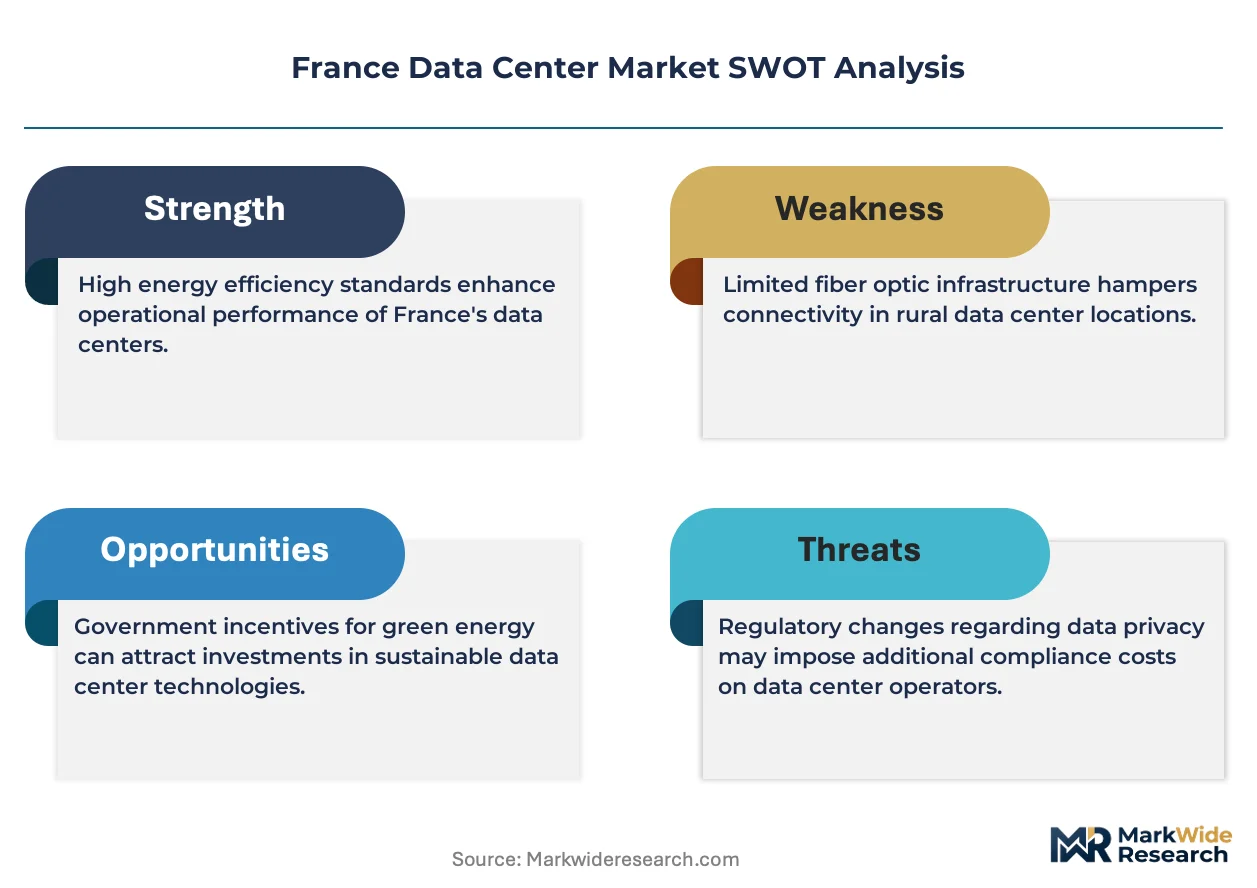
A data center constitutes a dedicated facility housing computing infrastructure—servers, storage arrays, networking equipment, and power distribution systems operating within precise temperature bands of 18-27°C—designed to process, store, and distribute digital workloads for enterprise and consumer applications. Colocation services dominate revenue generation as enterprises exit owned facilities. Edge Computing deployments within the Technology segment represent the fastest structural expansion, driven by latency-sensitive manufacturing automation in Rhône-Alpes. Managed Services commands premium margins where operators integrate cybersecurity operations with infrastructure oversight.
ANSSI, the French cybersecurity agency, mandates certification tiers that filter market access for foreign cloud providers. EMA pharmaceutical data localization rules and GDPR sovereignty requirements compound facility placement decisions across Île-de-France and Provence-Alpes-Côte d'Azur. Stakeholders must weigh sovereign infrastructure mandates against multi-cloud interoperability costs before committing to regional expansion strategies.
Market Dynamics
ANSSI certification tiers and EU AI Act compliance timelines are compressing facility deployment schedules while sovereign cloud mandates redirect capital toward domestic operator partnerships.
Growth Catalysts
- Cloud adoption in financial services:French banking and insurance sectors are migrating core systems off-premise, generating sustained demand for Tier III+ facilities with financial-grade redundancy.
- EMA pharmaceutical data localization:Clinical trial data residency requirements are mandating primary storage within French sovereign territory, pulling biopharma compute workloads toward Île-de-France.
- Edge computing for manufacturing automation:Latency-sensitive robotics deployments in Rhône-Alpes industrial corridors are spawning micro-facility builds outside traditional Paris concentration zones.
Market Restraints
- Grid interconnection bottlenecks:RTE approval timelines for multi-megawatt connections routinely extend 24-36 months, freezing project pipelines regardless of capital availability.
- Server supply chain concentration:Domestic operators remain dependent on Asian ODMs for white-box server assembly, exposing procurement to maritime logistics volatility.
- GDPR-EU AI Act compliance layering:Overlapping audit frameworks from CNIL and future AI Act technical standards are multiplying certification costs without harmonized timelines.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur expansion:Submarine cable landings at Marseille and landlocked backup sites in Nice hinterlands offer latency arbitrage to African and Middle Eastern markets.
- Heat reuse district heating integration:Waste heat recovery partnerships with municipal utilities in Lyon and Grenoble unlock alternative revenue streams and planning consent advantages.
- Liquid cooling retrofit demand:GPU-intensive AI training clusters are rendering legacy air-cooled halls obsolete, creating upgrade cycles for existing facility operators.
Industry Challenges
- Critical facility engineering talent scarcity:France produces fewer than 200 specialized data center mechanical and electrical engineers annually, forcing operators to recruit from UK and German markets.
- Legacy enterprise workload migration complexity:Mainframe-dependent French insurers and government agencies face decade-long decommissioning timelines that delay full cloud transition.
- Permitting coordination across overlapping jurisdictions:DREAL environmental assessments, DRIEAT labor inspections, and municipal urban planning approvals frequently operate on unaligned schedules.
Report Scope
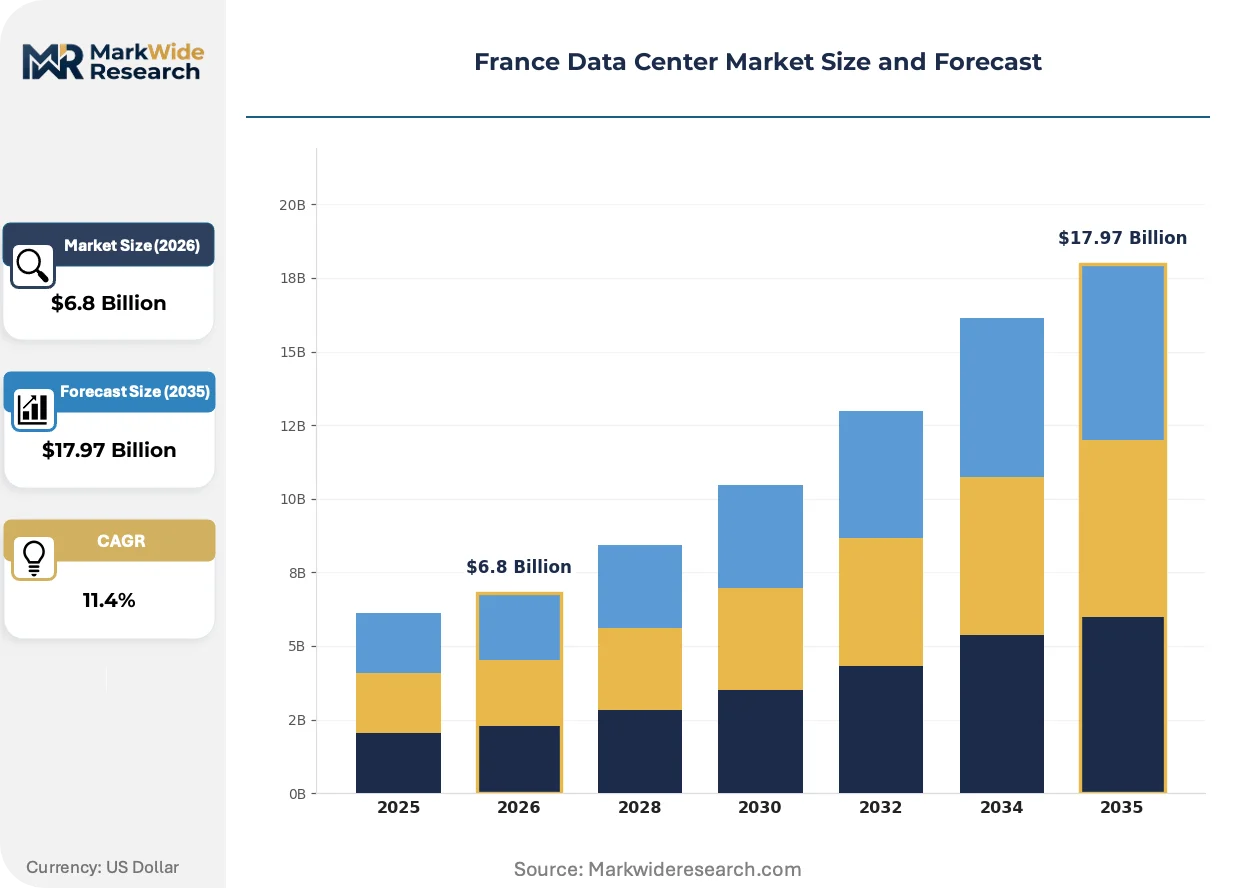
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Data Center Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Disaster Recovery Deployment Model: On-premises, Off-premises, Hybrid, Multi-Cloud End User: IT & Telecom, BFSI, Retail, Government Technology: Virtualization, Automation, AI, Edge Computing |
| Companies Covered | OVH Groupe SAS, Amazon Web Services, Inc., DATA4 Group SAS, Icade SA, Telehouse International Corporation of Europe Ltd., Digital Realty Trust Inc., Microsoft Corporation, CloudHQ LLC, Equinix, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Data Center Market Emerging Trajectories
Facility architecture is pivoting from generic compute housing toward workload-optimized environments with embedded compliance tooling and thermal integration into urban infrastructure systems.
Direct liquid cooling is unifying heat rejection and compute density management in high-performance AI training halls. Hyperscale operators in Paris-Nord zones are deploying single-phase immersion systems for 100kW+ rack densities. This convergence is compressing mechanical footprint requirements while enabling waste heat capture for district heating networks.
The EU AI Act risk-based classification system is mandating technical documentation and conformity assessments for high-risk AI systems hosted in French facilities. Data center operators must now embed audit trails and model registry capabilities into infrastructure service offerings. Financial services and healthcare verticals are prioritizing certified hosts with pre-validated compliance tooling over uncertified alternatives.
Enterprise procurement is fragmenting across multi-cloud and sovereign-cloud strategies simultaneously. French manufacturing mid-caps are splitting workloads between hyperscale elasticity for development and domestic colocation for production data. This bifurcation is visible most acutely in aerospace supply chain clusters around Toulouse, where IT governance committees mandate geographic separation of design and operational data.
France Data Center Market Segmentation
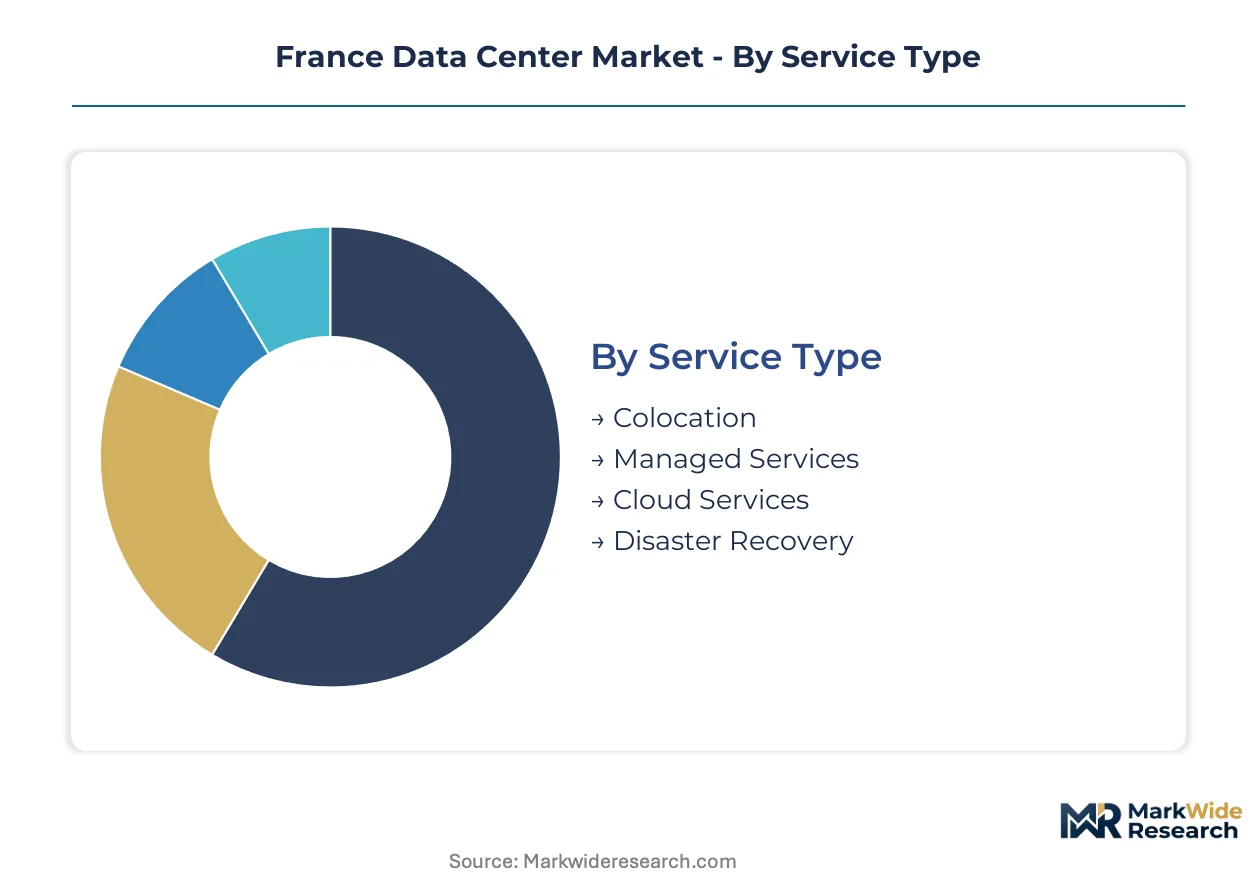
Segmentation in the France Data Center Market reveals how capital allocation, compliance obligations, and latency requirements fragment procurement patterns across buyer types. Understanding these divisions clarifies where infrastructure investment concentrates and which service layers command premium pricing.
Service Type:
Capital intensity peaks where operators must construct purpose-built facilities rather than lease existing space, creating tiered barriers to entry across service models.
- Colocation:Wholesale and retail colocation absorbs the majority of facility investment as enterprises exit owned data centers. French banking groups favor carrier-neutral Paris facilities with cross-connect density to multiple network providers.
- Managed Services:Operators integrate cybersecurity operations, backup orchestration, and infrastructure monitoring under unified SLAs. ANSSI certification requirements drive consolidation toward providers with pre-validated security frameworks.
- Cloud Services:Hyperscale operators deploy dedicated availability zones with sovereign data residency guarantees.
- Disaster Recovery:Secondary site mandates from French financial regulators sustain demand for geographically separated failover infrastructure.
Colocation absorbs the bulk of installed capacity; Managed Services is expanding most quickly as compliance complexity drives outsourcing.
Deployment Model:
Procurement patterns split between control-retentive models favored by regulated industries and elasticity-driven approaches in digital-native sectors.
- Hybrid:French aerospace manufacturers and pharmaceutical groups split sensitive production data across on-premises halls and burst capacity in commercial cloud. This bifurcation satisfies both IT governance committees and R&D velocity requirements.
- Multi-Cloud:Enterprise architects deliberately distribute workloads across hyperscale and sovereign providers to mitigate concentration risk. The EU AI Act's extraterritorial reach intensifies geographic diversification strategies.
- On-premises:Defense contractors and classified government systems maintain captive facilities under direct physical control.
- Off-premises:Mid-market enterprises without specialized engineering staff default to fully outsourced infrastructure consumption.
Hybrid deployments dominate committed capacity; Multi-Cloud configurations are climbing the fastest as procurement governance matures.
End User:
Vertical-specific compliance regimes and data gravity patterns concentrate demand unevenly across buyer categories.
- BFSI:French banking and insurance sectors migrate core banking platforms off mainframe infrastructure. ACPR operational resilience mandates require Tier III+ redundancy with sub-4-hour recovery objectives.
- Government:National cloud initiatives and classified program requirements sustain demand for ANSSI-certified sovereign facilities with domestic ownership structures.
- IT & Telecom:Content delivery networks and telecommunications operators anchor hyperscale absorption in Paris-Nord and Marseille cable landing zones.
- Retail:E-commerce platforms and omnichannel retailers prioritize edge presence for payment processing and inventory synchronization.
BFSI absorbs the bulk of premium facility commitments; Government verticals are gaining share fastest as sovereign cloud procurement accelerates.
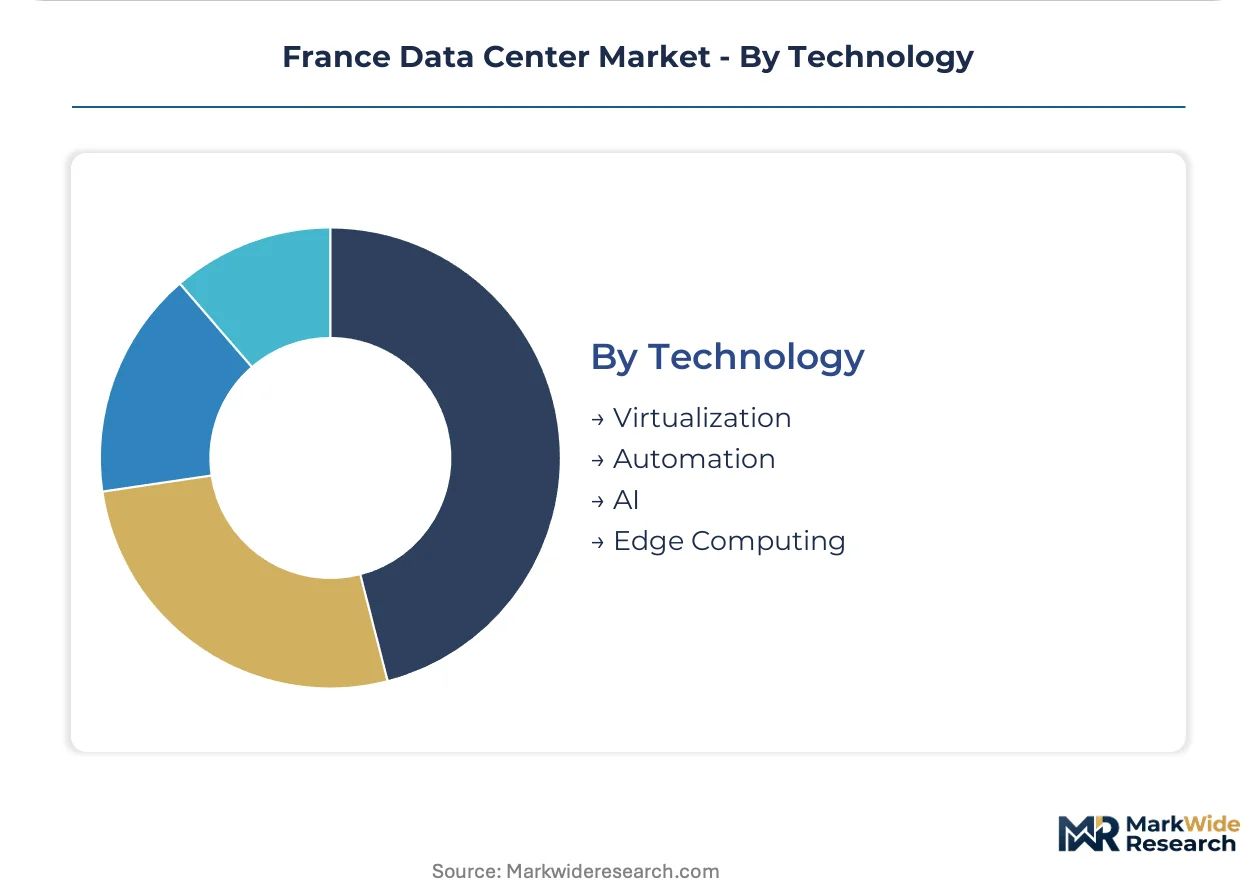
Technology:
Infrastructure architecture differentiates along workload optimization vectors, with thermal management and automation depth determining facility competitiveness.
- Edge Computing:Micro-facilities deployed in Rhône-Alpes industrial corridors support latency-sensitive manufacturing automation. Sub-10 millisecond response requirements for robotics control systems bypass centralized Paris infrastructure.
- AI:GPU-intensive training clusters demand liquid-cooled halls with 100kW+ rack densities. Direct liquid cooling retrofits of legacy air-cooled facilities unlock upgrade revenue for existing operators.
- Virtualization:Software-defined compute and storage pools remain foundational to multi-tenant efficiency in colocation environments.
- Automation:Robotic process automation of facility operations reduces headcount-dependent opex in remote or unmanned edge sites.
Virtualization underpins the bulk of operational infrastructure; Edge Computing is expanding most quickly as manufacturing digitalization propagates beyond Île-de-France.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility investment concentrates heavily in the Paris metropolitan area, though regulatory pressure and latency requirements are redistributing capacity toward southern industrial corridors and Mediterranean cable landing zones.
Île-de-France
Paris-Nord hyperscale zones absorb the majority of new capacity commitments from international cloud operators. ANSSI certification requirements filter market access, privileging operators with pre-validated sovereign cloud frameworks. Banking and insurance groups cluster in carrier-neutral facilities with cross-connect density to multiple network providers.
Auvergne-Rhône-Alpes
Manufacturing automation in Lyon and Grenoble industrial corridors drives edge computing deployments for sub-10 millisecond robotics control. Waste heat recovery partnerships with municipal utilities unlock planning consent advantages and alternative revenue streams. Liquid cooling retrofits address GPU-intensive AI training demands in legacy facilities.
Provence-Alpes-Côte d'Azur
Submarine cable landings at Marseille position the region for latency arbitrage to African and Middle Eastern markets. Landlocked backup sites in Nice hinterlands satisfy disaster recovery mandates from French financial regulators. EMA pharmaceutical data localization rules pull biopharma compute workloads toward the territory.
Hauts-de-France
Grid interconnection advantages and cooler ambient temperatures attract hyperscale operators seeking power cost optimization. RTE approval timelines for multi-megawatt connections remain shorter here than in saturated Paris zones. The region functions as a secondary failover location for Île-de-France primary sites.
France Data Center Market Vendor Landscape
Domestic operators anchor the sovereign cloud tier; international hyperscalers hold capacity leadership in unregulated segments. The market structures around three distinct layers: vertically integrated national champions, platform-scale international providers, and specialist colocation operators. Consolidation pressures intensify as ANSSI certification costs favor scaled players with compliance infrastructure. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Within the domestic sovereign tier, OVH Groupe SAS exemplifies vertical integration through controlled server supply chains. Amazon Web Services, Inc. and DATA4 Group SAS occupy contrasting positions: the former anchors hyperscale availability zones, while the latter differentiates via ANSSI-aligned sovereign cloud certifications. These three operators collectively represent the strategic archetypes reshaping procurement patterns across French regulated industries.
| Leading Market Players |
|---|
| OVH Groupe SAS |
| Amazon Web Services, Inc. |
| DATA4 Group SAS |
| Icade SA |
| Telehouse International Corporation of Europe Ltd. |
| Digital Realty Trust Inc. |
| Microsoft Corporation |
| CloudHQ LLC |
| Equinix, Inc. |
| Others |
Supply Flow & Price Mechanics
French financial institutions migrating core banking systems anchor demand for Tier III+ colocation, compressing procurement timelines and compressing price elasticity for certified sovereign capacity. This buyer concentration elevates ANSSI-certified facilities to premium pricing tiers while spot inventory in uncertified halls trades at substantial discounts.
Pricing Analysis
Lead-time premiums dominate pricing structures in the France data center market, with sub-12-month deployment windows commanding 15-25% uplifts over standard 24-36 month contracted capacity. Three-tier pricing stratifies across ANSSI-certified sovereign cloud, carrier-neutral Tier III colocation, and uncertified economy facilities, with certification grade and cross-connect density as primary differentiation levers. Pricing pressure stems from hyperscale operators absorbing wholesale blocks in Paris-Nord zones, compressing margins for mid-tier retail colocation. Government and defense verticals exhibit lowest price sensitivity due to mandated domestic residency requirements, while mid-market SaaS providers drive hardest bargain hunting.
Supply Chain Analysis
Server assembly rests on Taiwanese and Chinese ODMs for white-box compute, with memory modules and GPU accelerators drawing from South Korean semiconductor fabs. Critical dependencies span precision cooling components from German engineering houses, backup power systems from US and Japanese manufacturers, and specialized electrical switchgear from Italian and Swiss suppliers. Single-source vulnerability concentrates in liquid cooling manifolds and high-density busway systems, where qualified vendors number fewer than five globally. Distribution runs through direct OEM relationships for hyperscale operators and value-added resellers serving mid-market colocation clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid interconnection bottlenecks across Île-de-France sustain supply-constrained conditions, with RTE approval timelines propping pricing power for operators holding energized capacity. This scarcity dynamic favors incumbent asset owners over speculative developers.
For Market Incumbents: To counter hyperscale encroachment into sovereign cloud tiers, domestic operators should deepen backward integration into server supply chains following OVH's manufacturing heritage model, while accelerating ANSSI certification investments to widen compliance moats against uncertified competitors. For New Entrants and Emerging Players: Capture underserved edge computing demand in Rhône-Alpes manufacturing corridors where sub-10 millisecond latency requirements bypass Paris infrastructure concentration. Target liquid cooling retrofit opportunities in legacy air-cooled halls as GPU-intensive AI training clusters render existing facilities obsolete, with heat reuse partnerships unlocking municipal planning consent advantages. For Investors and Strategic Acquirers: The window for entry favors vertically integrated operators with captive server manufacturing and pre-validated ANSSI frameworks over pure-play real estate vehicles. Watch RTE interconnection queue lengths as the inflection signal—compression below 18 months would erode scarcity premiums and reset return expectations.| Strategic Initiative | Industry Significance |
|---|---|
| ANSSI Certification Investment | Pre-validated compliance frameworks filter market access for foreign cloud providers under EU AI Act timelines. |
| Liquid Cooling Retrofit Program | GPU-intensive AI training clusters demand 100kW+ rack densities that obsolete legacy air-cooled infrastructure. |
| Heat Reuse Partnership | Waste heat recovery agreements with Lyon and Grenoble municipal utilities unlock planning consent and alternative revenue. |
| Submarine Cable Landing Expansion | Marseille cable landings position Provence-Alpes-Côte d'Azur for latency arbitrage to African and Middle Eastern markets. |
| Edge Micro-Facility Deployment | Rhône-Alpes robotics control systems require sub-10 millisecond response bypassing centralized Paris infrastructure. |
Methodological Framework
Independent corroboration across facility operators, enterprise IT procurement officers, and RTE grid planning engineers underwrites the qualitative findings in this study. Primary interviews with data center engineering directors, cybersecurity compliance leads at ANSSI-certified operators, and financial services infrastructure architects combined with secondary validation from RTE interconnection databases, ANSSI certification registries, and hyperscaler capex disclosures. Bottom-up capacity installation tracking and top-down demand segmentation from vertical-specific procurement patterns established analytical triangulation.
Comparable historical deployment cycles across the 2019-2024 window anchored projection parameters for the forward analysis window. Segmentation modeling incorporated service type, deployment model, end-user vertical, and technology architecture dimensions, with CAGRs derived from facility absorption rates, power density evolution, and compliance cost trajectories. Forecast inputs included RTE queue length projections, GPU server shipment forecasts, and EU AI Act implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to RTE regulatory reform, EU AI Act technical standard finalization, and maritime logistics volatility affecting Asian ODM delivery schedules. A small set of triggers—RTE queue compression, ANSSI certification tier expansion, and liquid cooling component supplier entry—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Norway Data Center Storage Market