
 Internet Data Center Market | 2026-2036
Internet Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Internet Data Center Market Outlook
Multi-source infrastructure procurement is realigning how enterprises distribute compute workloads across owned and leased facilities. Amazon Web Services leverages its hyperscale build program to anchor capacity in primary and secondary markets. Microsoft sustains competitive pressure through vertical integration into custom silicon and cooling systems. Equinix differentiates via interconnection density and carrier-neutral positioning in metro edge nodes.
An Internet Data Center constitutes a purpose-built facility housing servers, storage systems, networking equipment, and power infrastructure within controlled environments maintaining 18-27°C temperature and 40-60% relative humidity, designed to deliver continuous compute, storage, and connectivity services to enterprise and consumer applications. Colocation services command the largest revenue pool as enterprises exit owned facilities, while edge computing deployments represent the fastest-expanding technology segment driven by latency-sensitive applications. Cloud services capture disproportionate growth in the service type dimension as hybrid architectures become the default enterprise posture.
The US EPA ENERGY STAR program and the EU Energy Efficiency Directive shape facility design standards by mandating power usage effectiveness reporting and carbon intensity disclosures above threshold capacities. China's MIIT enforces GB 50174 data center design standards that restrict power density and location in eastern provinces. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs become a site-selection determinant alongside energy pricing and fiber access.
Market Dynamics
Hyperscale cloud providers are compressing deployment timelines for generative AI infrastructure, forcing facility operators to reconcile power density requirements with constrained utility interconnection queues and evolving cooling architectures.
Growth Catalysts
- AI Training Clusters:Generative AI model development is pulling multi-hundred-megawatt deployments into secondary markets previously bypassed by hyperscalers.
- EU Energy Efficiency Directive:Mandatory power usage effectiveness disclosures above 500 kW are accelerating retrofit investments in legacy European facilities.
- Liquid Cooling Adoption:Direct-to-chip and immersion systems are unlocking rack densities beyond 50 kW per cabinet, enabling footprint consolidation.
Market Restraints
- Transformer Supply Bottlenecks:Lead times for high-voltage electrical transformers now extend 18-24 months, gating new facility energization.
- Water Stress in Southwest US:Cooling-dependent operations face operational risk in Arizona and Nevada as basin allocations tighten.
- Permitting Velocity:Grid interconnection studies in PJM and ERCOT territories now average 36 months, compressing developer returns.
Strategic Opportunities
- Nordic Expansion:Norway and Sweden offer sub-0.05 EUR/kWh renewable power with minimal cooling energy overhead.
- Edge Micro-Facilities:500 kW-2 MW modular deployments are capturing latency-sensitive manufacturing automation workloads.
- Waste Heat Recovery:District heating integration in Amsterdam and Helsinki is converting thermal output into revenue streams.
Industry Challenges
- Electrical Infrastructure Talent:Shortages of medium-voltage technicians and commissioning engineers are extending construction schedules.
- Hybrid Cloud Integration:Enterprises struggle to orchestrate consistent networking and security policies across on-premise, colocation, and hyperscale footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet Data Center Market |
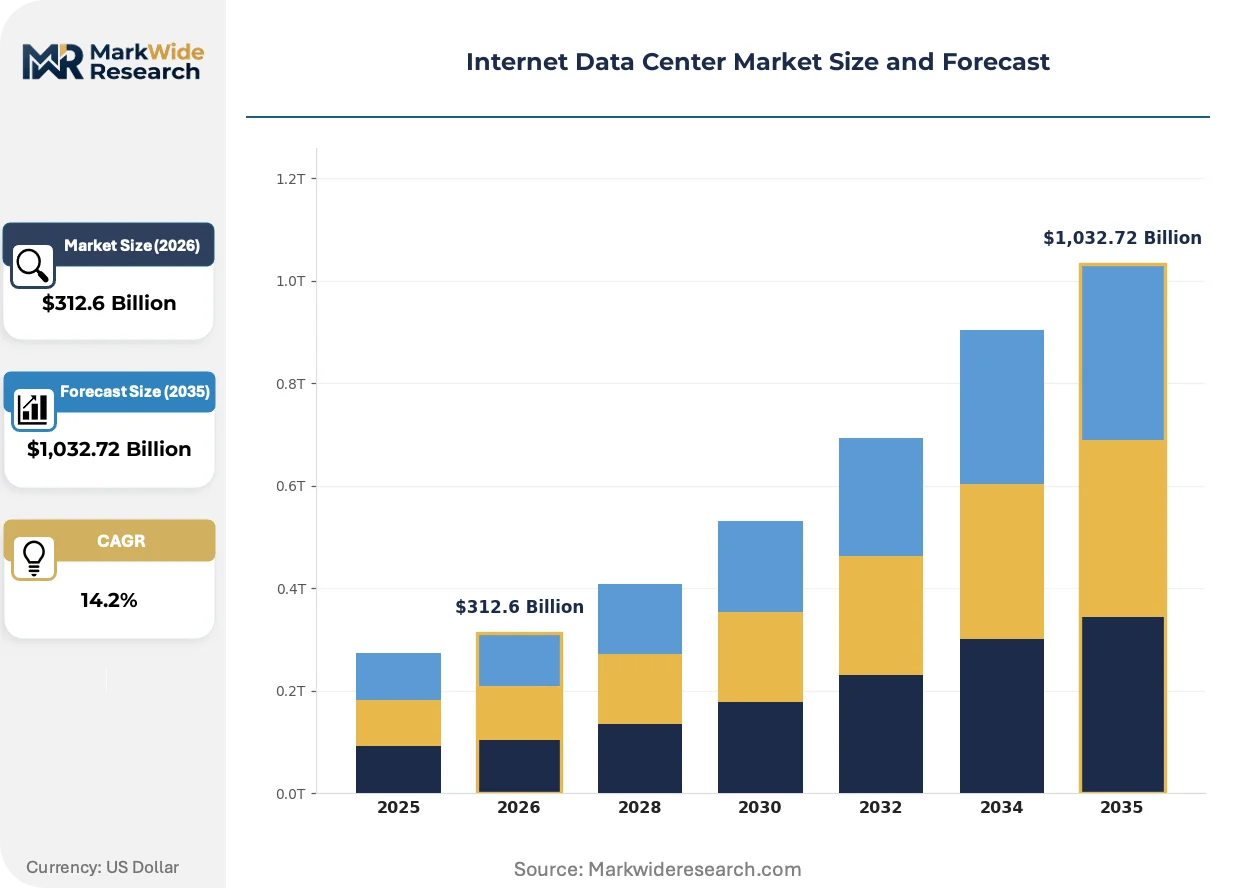
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,032.72 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Hosting, Cloud Services, Hybrid Solutions End User: Healthcare, BFSI, IT & Telecom, Retail Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud Technology: Edge Computing, Virtualization, Networking, Storage Solutions |
| Companies Covered | Amazon Web Services, Microsoft, Google, Meta, Equinix, Digital Realty, NTT Global Data Centers, Dell Technologies, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet Data Center Market Strategic Shifts
Facility architecture is bifurcating between maximal-density AI training campuses and distributed edge nodes, with cooling technology and power contracting emerging as the primary axes of differentiation.
Direct liquid cooling is rewriting thermal management economics for high-density AI infrastructure. Hyperscale operators are retrofitting existing facilities and specifying immersion-ready designs for new builds. This technology is compressing the viable geography for mega-campuses to regions with excess renewable generation and permissive water regulation.
The EU Energy Efficiency Directive is mandating granular power usage effectiveness reporting and carbon intensity disclosures for facilities above 500 kW. Operators must install continuous monitoring infrastructure and submit verified data to national regulators. German and French facilities face the steepest compliance curves due to older building stocks and stricter enforcement timelines.
Enterprise buyers are consolidating vendor relationships around integrated platform contracts spanning colocation, interconnection, and managed services. Systems integrators and traditional value-added resellers are losing relevance as procurement authority centralizes within infrastructure engineering teams. This concentration is most pronounced among North American financial services and healthcare organizations navigating HIPAA and SEC cybersecurity mandates.
Internet Data Center Market Segmentation
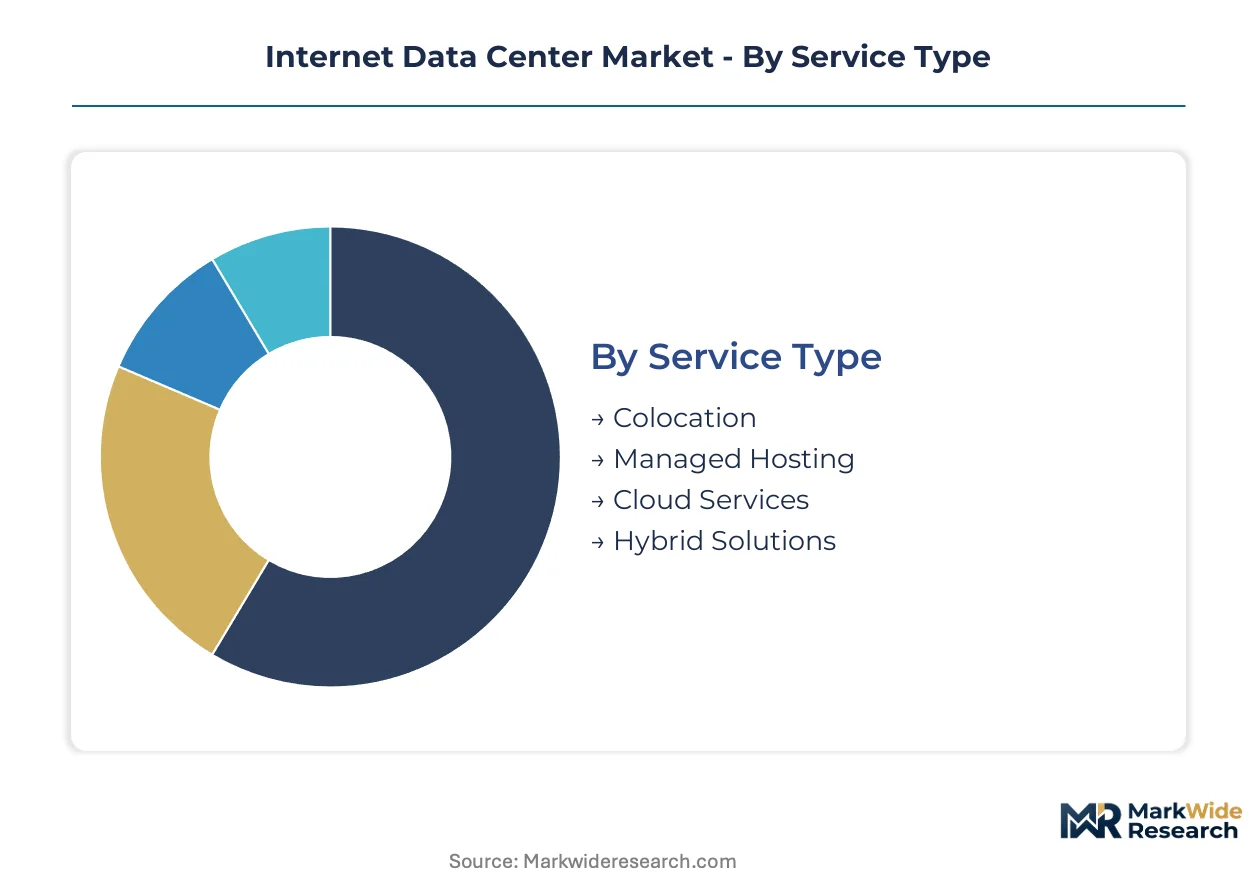
Internet data center segmentation reveals how workload characteristics, compliance requirements, and latency tolerance reshape procurement patterns across service tiers and deployment architectures. Understanding these divisions exposes where margin concentrates and which technology transitions threaten incumbent positioning.
Service Type:
Service type segmentation traces the migration path from asset-heavy ownership to utility-style consumption, with each tier carrying distinct contractual and operational risk profiles.
- Colocation:Third-party facilities providing physical space, power, cooling, and security for customer-owned equipment. Demand concentrates among financial services firms in Northern Virginia seeking proximity to fiber-dense interconnection hubs while offloading facility management burdens.
- Managed Hosting:Providers assume hardware ownership and operational responsibility while delivering dedicated compute resources to single-tenant environments. Healthcare systems in Germany favor this model to satisfy GDPR and national health data sovereignty requirements without building captive facilities.
- Cloud Services:Multi-tenant infrastructure delivered via API-driven consumption models with elastic scaling capabilities.
- Hybrid Solutions:Orchestrated combinations of colocation, managed hosting, and public cloud resources under unified management planes.
Colocation leads on scale; cloud services lead on momentum.
End User:
End user segmentation maps divergent infrastructure priorities across regulated industries, with compliance mandates and latency sensitivity creating distinct procurement patterns.
- Healthcare:Hospitals, payers, and pharmaceutical companies deploying HIPAA-compliant infrastructure for electronic health records and medical imaging archives. Demand clusters in US secondary markets where state-level privacy laws add complexity to federal requirements.
- BFSI:Banks, insurers, and capital markets firms operating low-latency trading infrastructure and disaster recovery sites. Frankfurt and London facilities capture European trading venue proximity requirements, while Singapore anchors Asia-Pacific foreign exchange operations.
- IT & Telecom:Technology vendors and network operators building edge presence for content delivery and 5G core functions.
- Retail:Omnichannel merchants processing transaction spikes and inventory synchronization across distributed store networks.
BFSI dominates absolute spend; healthcare shows the steepest expansion trajectory.
Deployment Model:
Deployment model segmentation captures the architectural tension between control, cost efficiency, and scalability that enterprises navigate across workload categories.
- On-Premises:Captive facilities owned and operated by end-user organizations with full hardware and software stack responsibility. Defense contractors and intelligence agencies in the US maintain these deployments to satisfy classified processing requirements under government security frameworks.
- Public Cloud:Shared infrastructure operated by hyperscale providers with consumption-based pricing and global region availability. Startups and digital-native enterprises in India leverage Mumbai and Hyderabad regions for rapid international expansion without capital commitments.
- Private Cloud:Single-tenant environments delivering cloud-style automation and self-service within dedicated physical or logical boundaries.
- Hybrid Cloud:Integrated environments spanning on-premises, colocation, and public cloud resources with consistent orchestration and security policy enforcement.
Public cloud leads on scale; hybrid cloud leads on momentum.
Technology:
Technology segmentation isolates infrastructure layers where innovation cycles compress and vendor consolidation threatens interoperability.
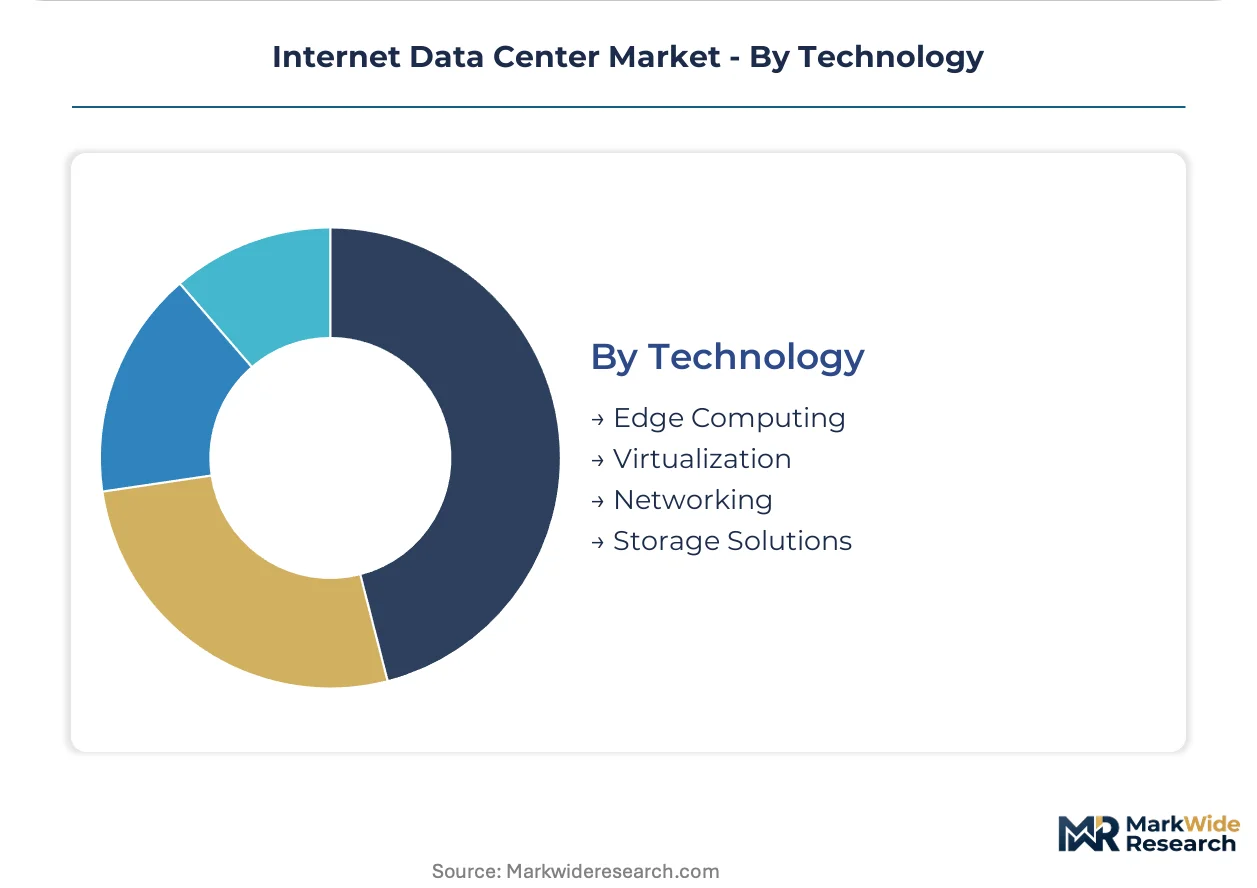
- Edge Computing:Distributed micro-facilities and compute nodes positioned within 10 milliseconds of end users to serve latency-critical applications. Manufacturing automation in Japan's Aichi Prefecture and Germany's Baden-Württemberg region drives modular 500 kW-2 MW deployments for real-time quality control systems.
- Virtualization:Software abstraction layers enabling server consolidation, workload mobility, and infrastructure automation across heterogeneous hardware. VMware and KVM deployments dominate enterprise refresh cycles in Canada as organizations modernize legacy data center footprints.
- Networking:Physical and software-defined interconnects including spine-leaf architectures, optical transport, and programmable fabrics.
- Storage Solutions:Tiered persistence technologies spanning all-flash arrays, object storage, and tape archives for compliance retention.
Virtualization leads on scale; edge computing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's Data Center Alley concentrates the world's largest hyperscale deployments, with fiber density and state tax incentives pulling cloud providers into Loudoun and Prince William counties. Facility operators across four continents are racing to match this scale while navigating divergent regulatory frameworks and power constraints.
United States
Hyperscale cloud providers are compressing deployment timelines for generative AI infrastructure across secondary markets including Phoenix, Dallas, and Columbus. The EPA ENERGY STAR program mandates power usage effectiveness benchmarking for facilities seeking certification, pushing operators toward liquid cooling retrofits. Northern Virginia maintains dominance through pre-approved electrical substations and dark fiber abundance.
Germany
Frankfurt anchors European financial services demand with proximity to trading venues and ECB data sovereignty requirements. The EU Energy Efficiency Directive enforces granular PUE reporting above 500 kW, accelerating retrofit investments in legacy facilities. Berlin-Brandenburg emerges as a secondary cluster where waste heat recovery systems supply district heating networks.
China
MIIT's GB 50174 standards restrict power density and eastern province locations, redirecting capacity toward western renewable-rich regions. The dual carbon goals mandate carbon intensity disclosures for facilities above threshold capacities. Inner Mongolia and Guizhou provinces capture mega-campus investments with sub-0.04 USD/kWh wind and hydroelectric pricing.
India
Mumbai and Hyderabad regions absorb rapid international expansion from digital-native enterprises seeking API-driven consumption without capital commitments. The CEA enforces grid interconnection standards that extend energization timelines, gating new facility development. Maharashtra's Pune corridor attracts modular edge deployments for manufacturing automation quality control systems.
Sweden
Nordic renewable power at sub-0.05 EUR/kWh draws AI training campus investments with minimal cooling energy overhead. The country's national energy regulator mandates waste heat utilization feasibility studies for facilities above 1 MW. Stockholm's data center cluster integrates with municipal district heating, converting thermal output into revenue streams.
Internet Data Center Market Competitive Environment
Global majors compete with regional champions across interconnection density and power contracting structures, creating a tiered market where scale advantages clash with localization requirements. Hyperscale cloud providers anchor capacity through self-build programs in primary and secondary markets simultaneously. Three archetypes dominate: vertically integrated hyperscalers, carrier-neutral colocation specialists, and modular edge fabricators. Competitive moves concentrate on strategic partnerships with utilities for firm power allocation and geographic expansion into Nordic and Asian secondary markets.
Within the hyperscaler tier, Amazon Web Services, Microsoft, and Google occupy positions defined by captive silicon development and cooling system integration. These entities exemplify the vertical integration archetype, controlling hardware design through facility energization. Equinix and Digital Realty represent the carrier-neutral positioning model, differentiating through interconnection density in metro edge nodes rather than proprietary cloud stacks.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Meta |
| Equinix |
| Digital Realty |
| NTT Global Data Centers |
| Dell Technologies |
| Huawei Technologies |
| Others |
Value Chain & Pricing Dynamics
Captive power contracting by hyperscale operators anchors both supply security and pricing power in data center development, allowing Amazon Web Services and Microsoft to lock in decade-long renewable energy purchase agreements that insulate against utility rate volatility while constraining available interconnection capacity for competitors. This vertical integration into energy procurement compresses margins for carrier-neutral colocation providers who must absorb spot-market electricity fluctuations or pass costs to enterprise tenants.
Pricing Analysis
Input-cost pass-through from transformer and electrical equipment shortages is intensifying pricing pressure across new facility development, with lead time extensions forcing developers to absorb carrying costs or renegotiate tenant rates. Pricing stratifies across hyperscale anchor tenants, enterprise colocation suites, and retail cabinet deployments based on power density commitments and interconnection proximity. Cost compression in secondary markets runs through aggressive tax incentive competition between Ohio, Texas, and Arizona jurisdictions. Healthcare systems exhibit the lowest price sensitivity due to HIPAA compliance requirements, while digital-native startups in India drive elasticity through pure cloud consumption models.
Supply Chain Analysis
Reverse-logistics flows for server decommissioning and component refurbishment are emerging as critical supply chain nodes, with Dell Technologies and circular economy specialists recovering memory and storage devices from hyperscale refresh cycles for secondary market distribution. Critical electrical infrastructure concentrates in China, Germany, and the United States, with high-voltage transformers and switchgear drawing from steel and copper supply chains exposed to commodity volatility. Single-source vulnerability sits with semiconductor-based power conversion equipment from Taiwan and South Korea. Distribution runs through direct OEM relationships for hyperscalers and tiered distributor networks for mid-market colocation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Internet Data Center Market functions as a geographic-arbitrage play where Nordic sub-0.05 EUR/kWh renewable power against German grid rates above 0.30 EUR/kWh creates sustained site-selection pull toward Norway and Sweden for AI training workloads.
For Market Incumbents: Hedge against transformer supply bottlenecks by securing multi-year electrical equipment procurement contracts with Siemens and ABB before queue positions deteriorate further. Expand capacity in Nordic secondary markets to capture carbon-neutral positioning as the EU Energy Efficiency Directive tightens disclosure requirements. Liquid cooling retrofit investments defend margin position against power density escalation in legacy European facilities. For New Entrants and Emerging Players: The 40-60% price-point gap between premium Northern Virginia colocation and economy-tier Phoenix deployments creates entry space for modular edge fabricators targeting 500 kW-2 MW manufacturing automation workloads in Germany's Baden-Württemberg region. Capture latency-sensitive quality control systems through direct utility partnerships bypassing congested interconnection queues. Position against hyperscale congestion by emphasizing sub-10 millisecond proximity to industrial zones. For Investors and Strategic Acquirers: Roll-up economics work for regional colocation specialists with established fiber interconnection density because enterprise procurement consolidation favors single-vendor platform contracts spanning multiple metro nodes. Target mid-tier operators with pre-approved substations in constrained markets like Northern Virginia and Frankfurt. Monitor PJM and ERCOT interconnection study velocity as the inflection signal for development pipeline viability.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Power Purchase Agreement | Secures renewable energy at fixed rates, insulating against EU carbon border adjustments and US IRA credit fluctuations. |
| Liquid Cooling Infrastructure Deployment | Enables rack densities above 50 kW, capturing generative AI training workloads that legacy air-cooled facilities cannot serve. |
| Waste Heat Recovery Integration | Converts thermal output into district heating revenue streams in Amsterdam and Helsinki municipal networks. |
| Edge Micro-Facility Expansion | Positions 500 kW-2 MW modular units within 10 milliseconds of manufacturing automation clusters in Japan and Germany. |
| Interconnection Density Investment | Deepens carrier-neutral positioning in metro nodes where financial services firms require proximity to trading venues. |
Study Parameters
Direct dialogue with hyperscale infrastructure planners, colocation procurement directors, utility interconnection managers, and district heating network operators grounded the qualitative foundation of this study. Secondary validation drew from EPA ENERGY STAR certification databases, EU Energy Efficiency Directive disclosure filings, MIIT GB 50174 compliance records, and hyperscaler capital expenditure disclosures. Bottom-up facility-level capacity assessments triangulated against top-down regional demand projections.
Bottom-up modeling of individual facility energization timelines and power contracting structures anchored the analytical framework, cross-referenced against top-down regional demand absorption rates across the analysis window. Segmentation dimensions included service type tiers, deployment model architectures, end-user industry verticals, and technology layer adoption curves. CAGRs were derived from facility pipeline tracking and utility interconnection queue velocity rather than extrapolated historical trends. AI training cluster power density requirements and transformer supply lead times served as critical forecast inputs.
Caveats apply where transformer manufacturing capacity constraints, grid interconnection study delays, or EU carbon border adjustment implementations could materially shift the outlook. Forecasts reflect assumptions about renewable energy buildout rates and hyperscaler capital commitment continuity. Practitioners should monitor PJM and ERCOT interconnection queue velocity, Nordic power purchase agreement pricing spreads, and MIIT eastern province location restrictions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Poland Data Center Rack Market