
 Multi-Tenant Data Center Market | 2026-2036
Multi-Tenant Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Tenant Data Center Market Intelligence
Colocation service revenue is tilting away from basic rack-and-power contracts toward interconnection-rich, software-defined environments. Equinix leverages its global platform of carrier-neutral facilities to capture cross-border enterprise traffic. Digital Realty anchors its position through hyperscale campuses with direct cloud on-ramps to AWS, Microsoft Azure, and Google Cloud. CyrusOne specializes in build-to-suit capacity for Fortune 500 enterprises seeking operational control without capital ownership.
A multi-tenant data center delivers shared physical infrastructure—power, cooling, security, and network connectivity—to multiple customers through individually leased white space or cabinets, typically maintaining tier III or tier IV redundancy with uptime exceeding 99.982 percent. The primary commercial purpose lies in converting fixed infrastructure costs into variable operating expenditure for enterprises that lack scale or geographic reach for self-built facilities. Colocation and cloud services command the largest revenue pools, while managed hosting retains higher per-rack margins by bundling remote hands and infrastructure management. Ultra high power density deployments above 30 kW per rack represent the fastest-expanding capacity segment, driven by GPU-intensive artificial intelligence training clusters.
The US Environmental Protection Agency and Department of Energy enforce energy performance benchmarks for federal-adjacent data center contracts, while the EU Energy Efficiency Directive mandates power usage effectiveness reporting across member states. California's Title 24 building standards and Germany's Federal Emission Control Act further constrain cooling system choices and diesel generator runtime limits. Stakeholders must track evolving carbon border adjustments and local renewable energy procurement rules that will determine site selection economics and tenant pricing power.
Market Dynamics
Hyperscale cloud providers are compressing traditional colocation margins by internalizing capacity planning and demanding bespoke power configurations above 50 kW per rack, forcing multi-tenant operators to restructure lease economics around energy arbitrage rather than space rental.
Growth Catalysts
- GPU-intensive AI training clusters:Enterprise demand for liquid-cooled infrastructure supporting NVIDIA H100 deployments is pulling capacity expansion in Northern Virginia, Frankfurt, and Singapore.
- EU Energy Efficiency Directive:Mandatory power usage effectiveness reporting is accelerating facility retrofits and creating competitive differentiation for operators with sub-1.2 PUE designs.
- Edge computing latency requirements:Autonomous vehicle manufacturers and industrial IoT platforms are contracting for distributed micro-data centers within 10 milliseconds of population centers.
Market Restraints
- Lithium-ion battery supply concentration:Uninterruptible power system manufacturers face procurement risk from Chinese cathode material processing dominance affecting backup power deployment timelines.
- Permitting friction under Germany's Federal Emission Control Act:Diesel generator runtime restrictions and noise ordinances extend commissioning cycles by 18-24 months in key Frankfurt and Berlin submarkets.
- Hyperscale self-build substitution:Amazon Web Services, Microsoft, and Google are constructing proprietary campuses bypassing third-party colocation for core training workloads.
Strategic Opportunities
- Carbon border adjustment mechanisms:The EU's phased implementation of embodied carbon tariffs on imported steel and aluminum creates first-mover advantage for European operators with localized supply chains.
- Submarine cable landing stations:Portugal, Ireland, and Denmark are attracting interconnection-focused investments due to transatlantic fiber density and renewable energy surplus.
- Heat reuse district heating integration:Nordic operators in Finland and Sweden are monetizing waste heat through municipal utility contracts, transforming cost centers into revenue streams.
Industry Challenges
- Critical facilities engineering talent scarcity:Experienced commissioning engineers for tier IV electrical topology and precision cooling systems command 40% salary premiums, constraining expansion velocity.
- Legacy copper network integration complexity:Financial services tenants maintaining mainframe connectivity require hybrid fiber-copper infrastructure extending depreciation schedules and operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Tenant Data Center Market |
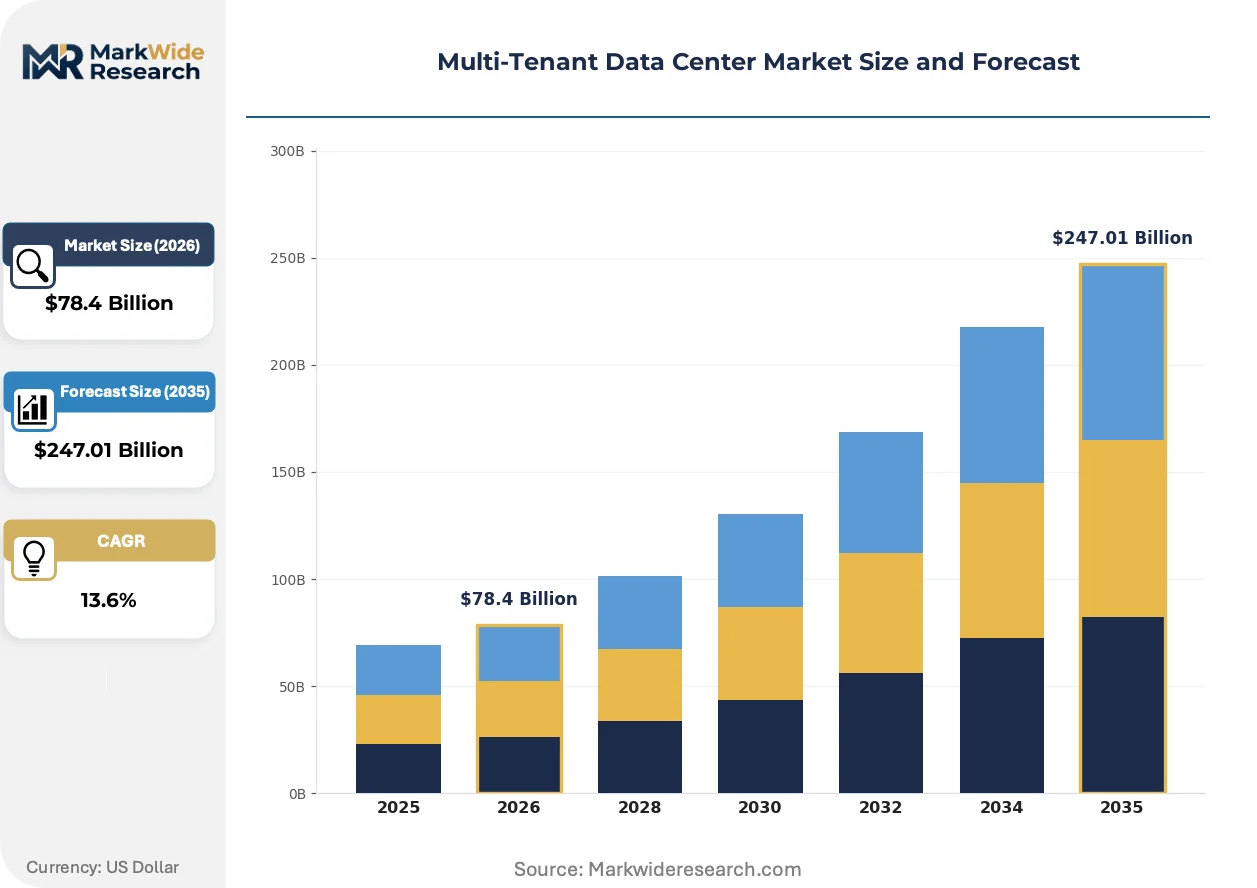
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Hosting, Cloud Services, Disaster Recovery End User: BFSI, IT & Telecom, Retail, Healthcare Technology: Virtualization, Cloud Computing, Networking, Automation Capacity: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | CyrusOne, STACK Infrastructure, Equinix, CoreSite, Vantage Data Centers, Digital Realty, NTT Global Data Centers, DataBank, QTS Data Centers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Tenant Data Center Market Strategic Shifts & Innovations
Software-defined power and cooling orchestration is collapsing the boundary between physical infrastructure and cloud-native workload management, enabling real-time capacity allocation that treats megawatts as fungible compute resources.
Software-defined power distribution is virtualizing the relationship between electrical infrastructure and tenant workloads. Hyperscale customers are deploying API-controlled rack-level power capping to burst above contracted limits during training spikes. This architecture is virtualizing traditional breaker-panel hierarchies into granular, billable energy units that trade on spot electricity markets.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with GWP above 150, prohibiting new installations in commercial cooling systems from 2027. Operators are retrofitting existing chillers with CO2 or ammonia-based alternatives at capital costs exceeding $8 million per 10 MW facility. German and Dutch facilities face the steepest compliance curves due to earlier national implementation timelines.
Enterprise procurement teams are consolidating vendor relationships through master service agreements spanning multiple geographies, displacing site-by-site colocation tenders. This concentration is pressuring mid-tier operators without global footprint parity. Financial services and pharmaceutical verticals in the United States and United Kingdom are most advanced in this consolidation, leveraging procurement leverage to extract interconnection fee waivers and remote hands credits.
Multi-Tenant Data Center Market Segmentation
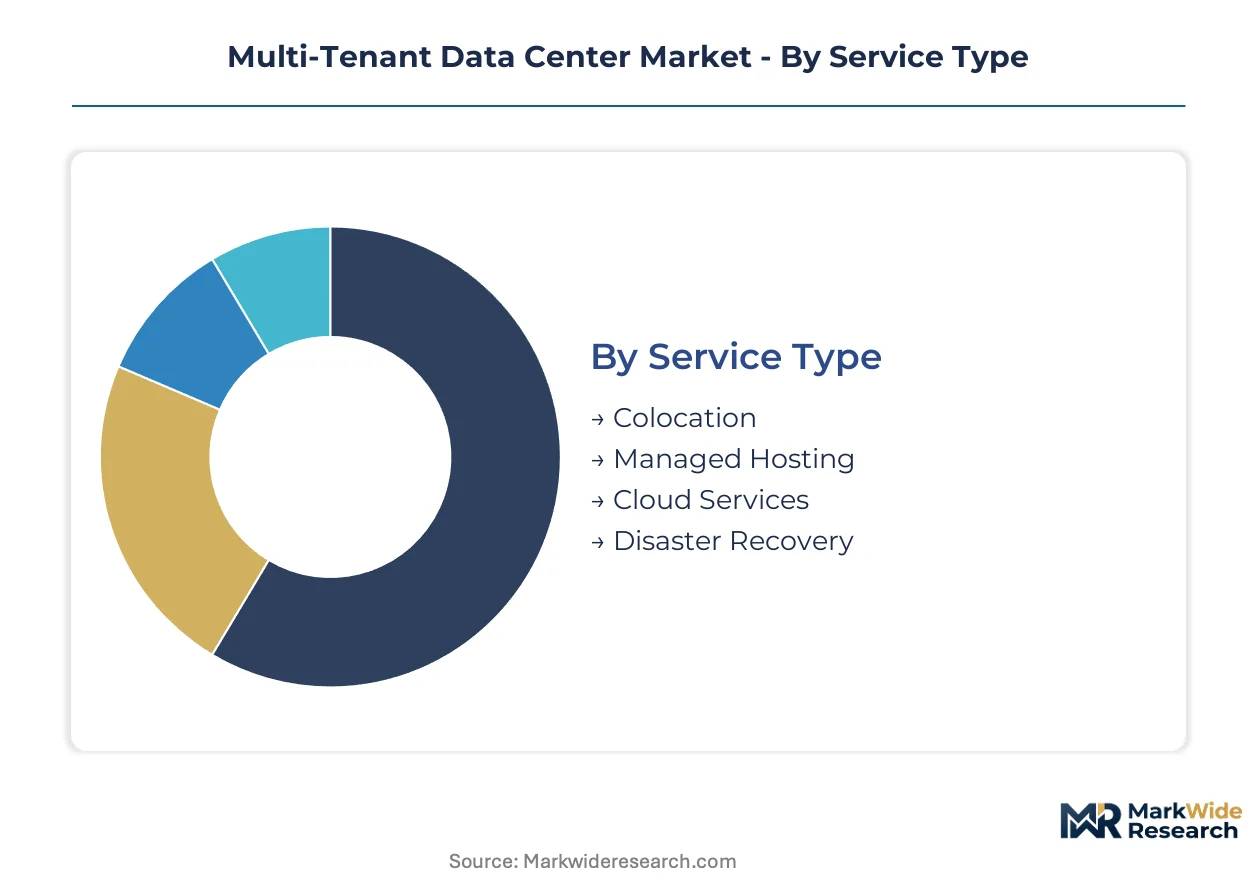
Multi-tenant data center segmentation reveals divergent margin structures and capital intensity profiles across service tiers. Operators must align facility design choices with specific customer power densities and compliance requirements to optimize rack economics.
Service Type:
Mature revenue streams coexist with emerging service architectures as enterprise procurement patterns shift toward integrated platforms.
- Colocation:Rack-and-power leasing with tier III or tier IV redundancy maintains the largest revenue pool. Demand concentrates in Northern Virginia, Frankfurt, and Singapore where hyperscale cloud providers secure contiguous megawatt blocks for training cluster expansion.
- Cloud Services:Direct on-ramps to AWS, Microsoft Azure, and Google Cloud bundle interconnection with physical space. Financial services enterprises in London and New York are contracting for multi-cloud exchange fabrics that collapse cross-connect provisioning from weeks to hours.
- Managed Hosting:Remote hands and infrastructure management bundled with physical tenancy command premium per-rack margins.
- Disaster Recovery:Geographically separated failover capacity with sub-15-minute recovery point objectives addresses regulatory mandates.
Colocation retains volume leadership; Cloud Services holds the steepest expansion curve.
End User:
Customer type determines power density requirements, compliance burdens, and contract duration preferences across facility tiers.
- IT & Telecom:Cloud service providers and content delivery networks drive ultra high power density specifications above 30 kW per rack. Deployment concentrates in Amsterdam and Dublin where submarine cable landing stations intersect with renewable energy surplus.
- BFSI:Financial institutions maintain hybrid mainframe-cloud architectures requiring legacy copper integration alongside fiber connectivity. Frankfurt and London submarkets absorb the majority of tier IV-certified capacity for trading platform latency sensitivity.
- Healthcare:HIPAA-compliant environments with audit-ready access logging support electronic health record hosting.
- Retail:Seasonal demand volatility favors short-term capacity commitments with burst provisions.
IT & Telecom dominates megawatt absorption; BFSI maintains the longest average contract tenures.
Technology:
Infrastructure software layers are collapsing traditional boundaries between physical facilities and cloud-native orchestration.
- Virtualization:Software-defined compute partitioning enables multi-tenant isolation without physical segmentation. VMware and Nutanix deployments concentrate in enterprise-managed hosting environments across Chicago and Dallas.
- Automation:Robotic process automation for provisioning and predictive maintenance reduces mean time to repair. Singapore operators are deploying API-controlled power capping that treats megawatts as fungible compute resources.
- Cloud Computing:Hybrid cloud management platforms unify on-premises and colocated workloads.
- Networking:Software-defined wide area networking optimizes inter-facility traffic routing.
Virtualization anchors current deployment share; Automation is climbing the fastest as operators pursue labor cost containment.
Capacity:
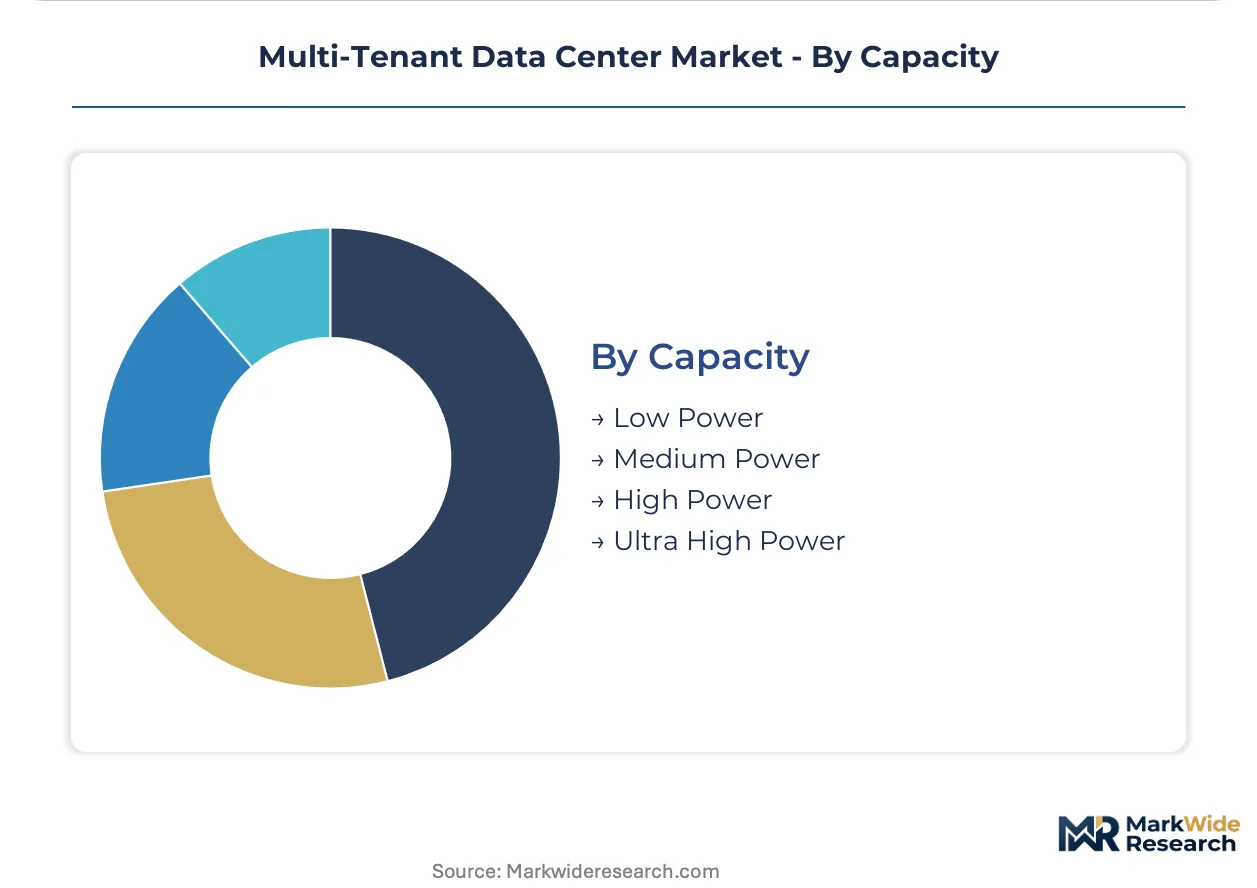
Power density segmentation directly determines cooling architecture, electrical topology, and per-kilowatt pricing structures.
- Ultra High Power:Deployments above 30 kW per rack require liquid cooling infrastructure for NVIDIA H100 GPU clusters. Northern Virginia and Frankfurt are absorbing the majority of new supply as AI training workloads proliferate.
- High Power:15-30 kW rack configurations support dense storage and virtualization platforms. Singapore's tropical climate constraints favor this segment where precision cooling economics remain manageable.
- Medium Power:5-15 kW densities serve mainstream enterprise virtualization and web hosting.
- Low Power:Sub-5 kW legacy deployments retain installed base in secondary markets.
Medium Power retains the largest installed base; Ultra High Power is gaining share fastest through AI infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Singapore and Northern Virginia absorb capacity with minimal price elasticity, while enterprises in secondary German markets negotiate aggressively on power pass-through terms. Frankfurt commands premium lease rates for tier IV certification. Ashburn and Manassas submarkets in Virginia trade density for proximity to fiber interconnection hubs.
United States
Hyperscale cloud providers and AI training clusters drive absorption above 30 kW per rack across Northern Virginia, Phoenix, and Dallas-Fort Worth. The EPA and Department of Energy enforce energy performance benchmarks for federal-adjacent contracts. Ashburn's Data Center Alley hosts the densest fiber interconnection ecosystem globally, with over 70 facilities within a 20-mile radius.
Germany
Frankfurt anchors European demand for latency-sensitive financial services and cloud on-ramps requiring sub-10 millisecond connectivity. The Federal Emission Control Act restricts diesel generator runtime and imposes noise ordinances extending commissioning cycles. Berlin and Hamburg submarkets attract secondary deployments for disaster recovery and data residency compliance.
Singapore
Tropical climate constraints and land scarcity concentrate development in purpose-built hyperscale campuses with liquid-cooled infrastructure for GPU-intensive workloads. The Infocomm Media Development Authority governs data center energy efficiency standards through mandatory green building certifications. Tuas and Changi North industrial zones host the majority of new supply additions.
United Kingdom
Slough and London Docklands submarkets serve financial services tenants requiring hybrid mainframe-cloud architectures with legacy copper integration. The Financial Conduct Authority mandates operational resilience standards affecting facility tier certification requirements. Manchester and Birmingham attract secondary capacity for cost-conscious enterprise workloads outside the capital.
Netherlands
Amsterdam's Schiphol-Rijk and Science Park clusters leverage transatlantic submarine cable landing stations and renewable energy surplus. The Dutch Environmental Management Act implements EU Energy Efficiency Directive requirements through mandatory power usage effectiveness reporting. Eindhoven and Rotterdam submarkets develop edge computing capacity for industrial IoT and autonomous vehicle platforms.
Multi-Tenant Data Center Market Key Industry Players
Capability concentration sits with hyperscale campus developers possessing liquid-cooled infrastructure expertise; scale advantage sits with global platform operators leveraging interconnection density across 50-plus metros. The market structures around three tiers: carrier-neutral exchange operators, wholesale hyperscale specialists, and regional build-to-suit developers. Strategic moves center on energy arbitrage restructuring and master service agreement consolidation spanning multiple geographies.
Within the global platform tier, Equinix and Digital Realty occupy positions defined by interconnection ecosystem scale and cloud on-ramp density respectively. CyrusOne exemplifies the build-to-suit specialist archetype targeting Fortune 500 enterprises seeking operational control without capital ownership. These three operators represent contrasting approaches to lease economics—interconnection fees, wholesale power contracts, and managed infrastructure bundling.
| Leading Market Players |
|---|
| CyrusOne |
| STACK Infrastructure |
| Equinix |
| CoreSite |
| Vantage Data Centers |
| Digital Realty |
| NTT Global Data Centers |
| DataBank |
| QTS Data Centers |
| Others |
Cost & Logistics Intelligence
Chinese lithium-ion cathode material processing dominance concentrates uninterruptible power system supply, anchoring margin pools with European operators who have localized battery assembly and recycling infrastructure. Tier IV-certified facilities in Frankfurt and Northern Virginia extract rent premiums through energy arbitrage rather than space rental, while mid-tier operators face pricing compression from hyperscale self-build substitution.
Pricing Analysis
Remote hands and infrastructure management services drive lifetime value above base rack-and-power contracts. Three-tier pricing structure across premium interconnection-rich, standard wholesale, and economy retail colocation segments reflects certification grade and cloud on-ramp density. Cost compression in standard wholesale tiers is intensifying because hyperscale cloud providers internalize capacity planning and demand bespoke power configurations. Retail enterprises with seasonal demand volatility exhibit highest price sensitivity; financial services tenants with sub-10 millisecond latency requirements demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk for electrical infrastructure components. Critical electrical equipment draws from China, Germany, and the United States; precision cooling systems rest on Japanese compressor technology and Chinese heat exchanger fabrication. Lithium-ion battery cell supply hinges on South Korean and Chinese cathode material processing concentration. Distribution runs through direct OEM relationships for hyperscale campus developers and regional distributor networks for mid-tier facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined power orchestration is collapsing traditional boundaries between physical infrastructure and cloud-native workload management, creating platform-economics inflection through API-controlled energy trading and real-time capacity allocation.
For Market Incumbents: Insulate core interconnection revenue by deepening carrier-neutral exchange density in Northern Virginia and Frankfurt, where fiber ecosystem lock-in creates switching costs. Accelerate liquid-cooled infrastructure certification for NVIDIA H100 deployments before hyperscale self-build substitution erodes wholesale margins. Vertical integration into renewable energy procurement secures power pass-through pricing power under EU Energy Efficiency Directive mandates. For New Entrants and Emerging Players: Build out edge computing micro-data center capacity within 10 milliseconds of European automotive manufacturing clusters in Stuttgart and Wolfsburg, where autonomous vehicle platforms require distributed low-latency infrastructure. Target Portugal and Denmark submarine cable landing stations for interconnection-focused investments, exploiting transatlantic fiber density and renewable energy surplus. Lead with heat reuse district heating integration as differentiated value proposition in Nordic municipal utility partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hyperscale campus developers possessing liquid-cooled infrastructure expertise but lacking global platform scale. Long-term viability hinges on energy arbitrage restructuring capability and master service agreement consolidation across multiple geographies. Monitor EU carbon border adjustment mechanism implementation as inflection indicator for European operators with localized steel and aluminum supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooled Infrastructure Deployment | Enables NVIDIA H100 GPU cluster hosting for AI training workloads in Northern Virginia and Frankfurt. |
| Submarine Cable Landing Station Acquisition | Captures transatlantic interconnection demand in Portugal and Denmark through fiber density proximity. |
| Heat Reuse District Heating Integration | Transforms waste heat cost centers into revenue streams through Finnish and Swedish municipal utility contracts. |
| Software-Defined Power Orchestration | Virtualizes megawatt allocation for API-controlled spot electricity market participation. |
| Master Service Agreement Consolidation | Spans multi-geography vendor relationships to extract interconnection fee waivers from mid-tier operators. |
Research Approach
A standing panel of data center facility directors, hyperscale cloud provider capacity planners, interconnection exchange managers, and critical facilities commissioning engineers provided ongoing calibration across primary fieldwork. Secondary validation drew from EPA energy performance benchmarks, EU Energy Efficiency Directive filings, Infocomm Media Development Authority certifications, FERC interconnection queue data, and hyperscaler capital expenditure disclosures. Bottom-up facility-level absorption modeling triangulated against top-down regional demand aggregation.
Scenario-bracketing framed projections across the analysis window, modeling service type segmentation by colocation, cloud services, managed hosting, and disaster recovery tiers; end user verticals by IT and telecom, BFSI, healthcare, and retail; and capacity tiers by ultra high, high, medium, and low power density. CAGRs derived from facility commissioning pipeline analysis, power purchase agreement contracting velocity, and GPU-intensive workload deployment tracking. Interconnection ecosystem density and renewable energy procurement progress served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers toward proprietary campus construction would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Asia-Pacific Hosting Infrastructure Services Market
Data Center Infrastructure
Composable-Disaggregated Infrastructure Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
DC Powered Servers Market
Data Center Infrastructure
Mini Data Center Market