
 Europe Data Center Physical Security Market | 2026-2036
Europe Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Physical Security Market Insights
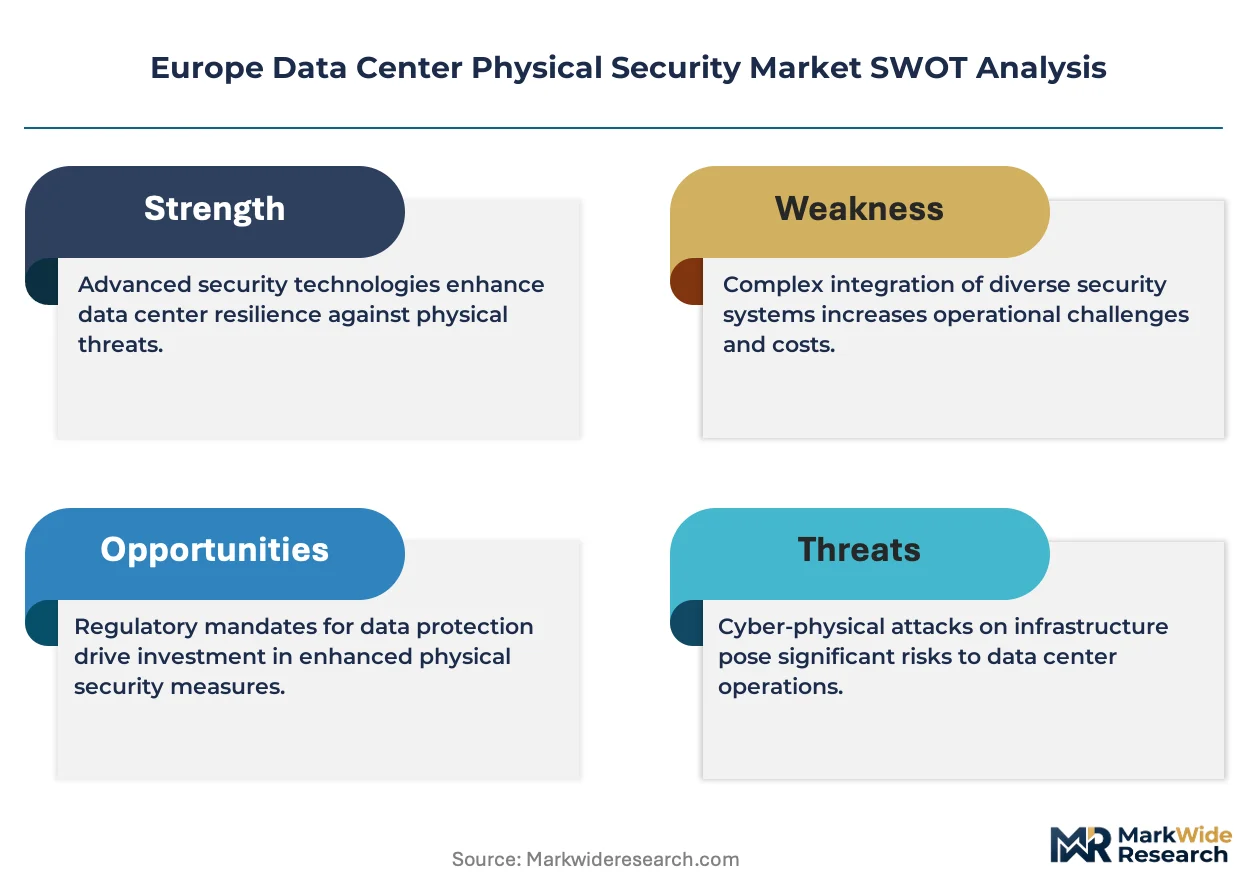
Modular security bundling is recalibrating procurement patterns across European data center operators. Bosch Sicherheitssysteme GmbH leverages its integrated video and access platforms to dominate German-speaking markets. Axis Communications AB specializes in network camera architectures that anchor Nordic and Benelux deployments. Schneider Electric SE extends its building management heritage into environmental monitoring suites for edge facilities.
Europe data center physical security encompasses the hardware, software, and procedural systems that restrict unauthorized physical entry to server rooms, colocation halls, and supporting infrastructure, typically incorporating biometric readers operating at false acceptance rates below 0.001%, perimeter intrusion detection with sub-second response triggers, and video analytics with thermal overlay capabilities. Its primary purpose is maintaining continuity of digital services by preventing equipment theft, sabotage, or environmental damage. Surveillance Systems leads spending among security types due to AI-enabled video analytics refresh cycles across legacy installations. Biometric Authentication within the solution dimension captures disproportionate investment as iris and vein recognition displace card-based access in Tier III and IV facilities. Edge Computing deployments are accelerating fastest among deployment modes, driven by latency-sensitive applications requiring hardened micro-data centers in distributed locations.
The EU AI Act, GDPR, and country-specific critical infrastructure directives from Germany's BSI and France's ANSSI are tightening audit requirements for physical access logs and biometric data handling. CE marking under the EU's Radio Equipment Directive shapes product compliance for wireless intrusion sensors and networked cameras. Facility operators and security vendors must monitor evolving national transpositions of the NIS2 Directive, as these will determine whether physical security spending qualifies as mandatory critical infrastructure investment or discretionary operational expenditure across member states.
Market Dynamics
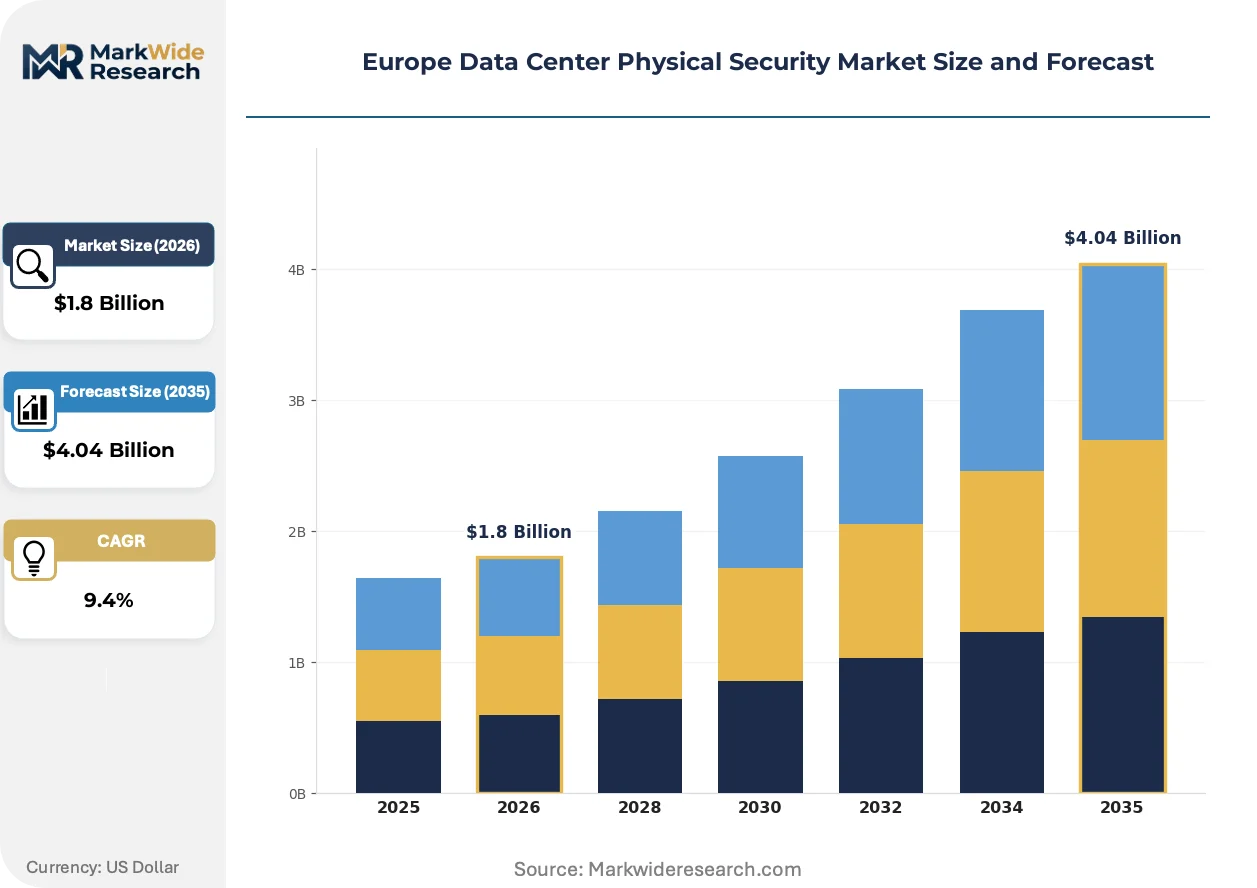
Modular security bundling is recalibrating procurement patterns across European data center operators, as integrated platform vendors displace point-solution providers through unified command-and-control architectures that reduce integration overhead.
Growth Catalysts
- EU AI Act compliance mandates:Critical infrastructure classifications under the EU AI Act require Tier III and IV facilities to deploy biometric access controls with audit-grade logging, forcing hardware refresh cycles.
- Hyperscale campus expansion:Colocation providers in Frankfurt, Amsterdam, and Paris are building multi-tenant facilities that demand layered perimeter and interior surveillance integration.
- Edge computing latency requirements:Distributed micro-data centers for autonomous systems and industrial IoT require hardened physical security in remote locations without on-site personnel.
Market Restraints
- Semiconductor component volatility:Video analytics processors and thermal imaging sensors face supply concentration risks from Asian foundry dependencies, inflating lead times.
- CE marking compliance costs:The EU's Radio Equipment Directive imposes extensive testing protocols on wireless intrusion detection systems, delaying product launches.
- Skilled technician scarcity:Biometric system calibration and AI-enabled video analytics configuration require specialized expertise concentrated in Germany and the Netherlands.
Strategic Opportunities
- Nordic edge facility buildout:Norway and Sweden offer renewable-powered sites for latency-sensitive applications with underdeveloped physical security vendor presence.
- GDPR-aligned biometric data services:Managed access control platforms that handle biometric template storage and deletion protocols create recurring revenue streams.
- Building management convergence:Integration of physical security with environmental monitoring and power distribution systems opens unified procurement channels.
Industry Challenges
- Legacy access control migration:Card-based systems in existing facilities require phased replacement without operational disruption during tenant transitions.
- NIS2 Directive transposition uncertainty:Member states are interpreting critical infrastructure scope differently, creating compliance planning ambiguity for multi-national operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Physical Security Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Type: Access Control, Surveillance Systems, Alarm Systems, Physical Barriers End User: Colocation Providers, Enterprises, Government, Telecommunication Companies Solution: Video Monitoring, Biometric Authentication, Intrusion Detection, Environmental Monitoring Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Bosch Sicherheitssysteme GmbH, Axis Communications AB, Johnson Controls International plc, Honeywell International Inc., Schneider Electric SE, Securitas Technology AB, ABB Ltd, Siemens AG, Convergint Technologies LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Physical Security Market Trends and Innovations
Artificial intelligence is embedding into every layer of physical security infrastructure, transforming reactive surveillance into predictive threat detection while compressing response timelines.
Iris and vein recognition biometrics are expanding into Tier III and IV facilities as primary authentication methods, displacing card-based and fingerprint systems. German and French hyperscale operators are adopting these modalities fastest, driven by GDPR's stringent biometric data handling requirements. Multi-modal biometric platforms are expanding into smaller colocation facilities as component costs decline and integration complexity drops.
The EU AI Act's risk-based classification system is mandating human oversight interfaces for automated security decisions in critical digital infrastructure. Facility operators must deploy explainable AI modules that log decision rationale for regulatory audits. Dutch and German deployments are responding earliest, with French operators accelerating compliance investments ahead of national transposition deadlines.
Security-as-a-service models are unbundling capital expenditure into operational subscriptions, altering how mid-sized colocation providers acquire capabilities. Traditional equipment vendors face displacement by managed service platforms that bundle hardware, software, and remote monitoring. This shift concentrates in the Benelux region and northern Germany where facility operators prioritize cash flow predictability over asset ownership.
Europe Data Center Physical Security Market Segmentation
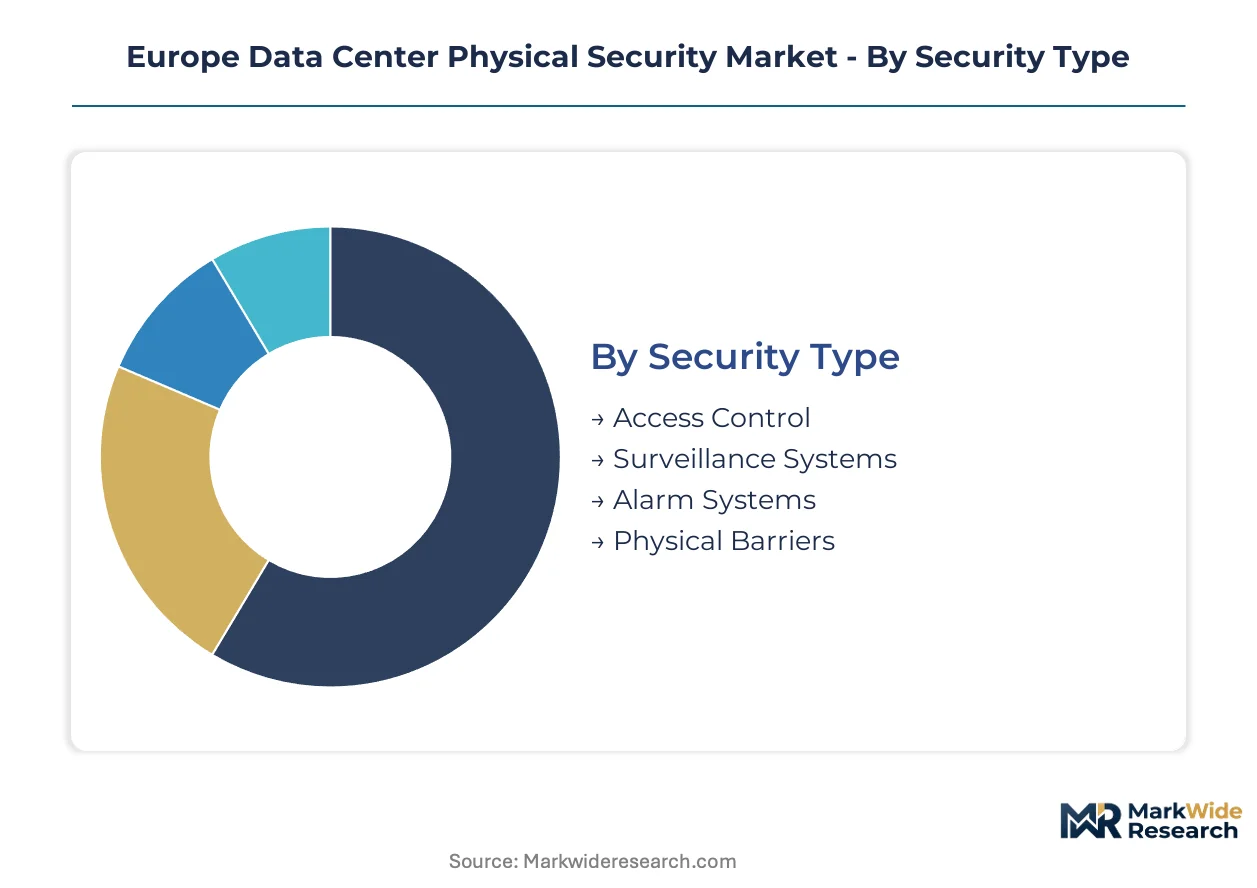
European data center operators segment procurement across security type, end user, solution, and deployment mode to match capital intensity with facility criticality tiers. Procurement patterns diverge sharply between hyperscale campuses requiring integrated platform architectures and distributed edge sites prioritizing modular, rapidly deployable systems.
Security Type:
Capital allocation decisions track facility tier classification and tenant density, with higher-tier facilities commanding multi-layered perimeter-to-cabinet protection stacks.
- Surveillance Systems:AI-enabled video analytics platforms with thermal overlay capabilities and sub-second alert generation anchor perimeter and interior monitoring. Demand concentrates in Frankfurt and Amsterdam hyperscale campuses where multi-tenant environments require continuous audit-grade footage retention under GDPR and EU AI Act mandates.
- Access Control:Biometric readers operating below 0.001% false acceptance rates govern entry to server halls and meet-meet rooms. German Tier III and IV facilities are displacing card-based systems fastest, driven by BSI critical infrastructure directives requiring non-repudiable identity verification.
- Alarm Systems:Perimeter intrusion detection with seismic and infrared tripwire sensors protects unmanned edge locations.
- Physical Barriers:Ballistic-rated fencing and vehicle arrest systems harden facility perimeters against deliberate impact threats.
Volume sits with Surveillance Systems due to legacy refresh cycles; growth tilts toward Access Control as biometric mandates expand beyond Tier IV facilities.
End User:
Facility ownership structure determines procurement sophistication, with multi-tenant operators standardizing across portfolios and single-tenant enterprises customizing to internal risk frameworks.
- Colocation Providers:Multi-tenant facility operators in Frankfurt, Amsterdam, and Paris require layered security architectures that satisfy diverse tenant compliance requirements simultaneously. These providers are consolidating vendor relationships around integrated platform suppliers to reduce integration complexity across expanding campus footprints.
- Enterprises:Financial services and healthcare organizations operate captive data centers with security stacks aligned to sector-specific regulators like France's ACPR and Germany's BaFin.
- Government:National critical infrastructure facilities fall under ANSSI and BSI directives mandating domestic biometric data storage and sovereign cloud integration.
- Telecommunication Companies:Carrier-neutral facilities and 5G edge nodes require hardened physical security in distributed locations with limited on-site personnel.
Revenue concentrates with Colocation Providers; expansion is climbing the fastest among Telecommunication Companies building out 5G infrastructure.
Solution:
Technology selection priorities reflect the tension between authentication precision and operational friction in high-velocity facility environments.
- Biometric Authentication:Iris and vein recognition modalities displace fingerprint and card systems in facilities handling sensitive financial and healthcare data. French hyperscale operators are adopting these systems fastest ahead of CNIL enforcement timelines for biometric data handling.
- Video Monitoring:Network camera architectures with edge-based analytics processing reduce bandwidth requirements and latency for real-time threat response. Dutch facilities lead deployment density due to Amsterdam's concentration of international carrier exchanges.
- Intrusion Detection:Wireless sensor networks with mesh topology protect remote edge sites without structured cabling infrastructure.
- Environmental Monitoring:Integrated temperature, humidity, and particulate sensing extends physical security into environmental threat detection for edge facilities.
Investment flows heaviest into Biometric Authentication; Video Monitoring retains the largest installed base across legacy facilities.
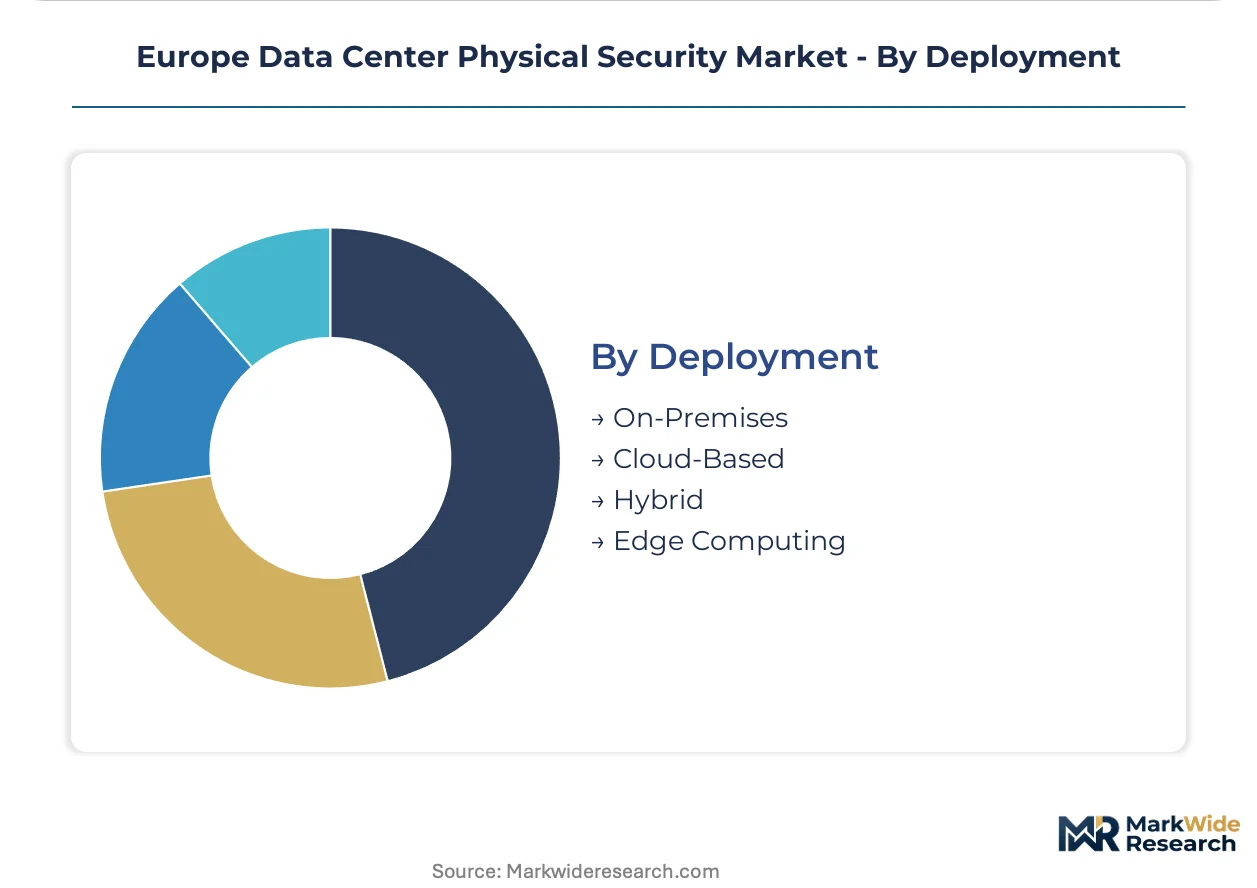
Deployment:
Infrastructure location and connectivity availability dictate whether security systems operate autonomously or integrate with centralized command platforms.
- Edge Computing:Hardened micro-data centers for autonomous systems and industrial IoT require self-contained physical security stacks operable without on-site personnel. Norway and Sweden are attracting renewable-powered edge buildouts with underdeveloped local security vendor presence.
- On-Premises:Traditional data centers maintain dedicated security operations centers with localized video storage and access control servers. German facilities favor this model due to stringent data sovereignty requirements under national cybersecurity frameworks.
- Cloud-Based:Centralized security-as-a-service platforms enable mid-sized colocation providers to unbundle capital expenditure into operational subscriptions.
- Hybrid:Split architectures process sensitive authentication locally while archiving footage to centralized cloud repositories.
Deployment maturity favors On-Premises systems; the steepest expansion trajectory belongs to Edge Computing as latency-sensitive applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's Rhine-Main metropolitan zone concentrates hyperscale investment through municipal tax abatements and grid connectivity incentives. Colocation providers cluster within 50 kilometers of DE-CIX to minimize latency. France and the Netherlands replicate this model through regional development authorities.
Germany
BSI's critical infrastructure directives mandate biometric access controls for Tier III and IV facilities. Frankfurt's Campus Data Center Zone attracts €4 billion in annual facility investment. Bavarian edge sites in Munich and Nuremberg deploy hardened micro-data centers for automotive IoT.
Netherlands
Amsterdam's Schiphol-Rijk corridor houses Europe's densest carrier-neutral exchange density. The Dutch Digitalization Strategy subsidizes renewable-powered data center construction in Groningen and Flevoland. Rotterdam port authorities are converting logistics zones into latency-sensitive edge facilities.
France
ANSSI's cloud security certification program requires sovereign biometric data storage for government-tenant facilities. Paris-Saclay's research cluster drives hyperscale campus expansion. Marseille's submarine cable landing stations anchor Mediterranean connectivity nodes with hardened perimeter requirements.
United Kingdom
NCSC's cyber assessment framework extends to physical security audits for critical national infrastructure. Slough's trading estate concentration hosts financial services captive data centers. Manchester's MediaCityUK attracts broadcast and gaming edge deployments with sub-10 millisecond London latency.
Nordic Region
Norway's Statkraft offers long-term renewable power purchase agreements below continental rates. Stockholm's data center heat recovery mandates create integrated environmental monitoring demand. Luleå's Facebook-established cluster demonstrates Arctic climate advantages for free-cooled facilities.
Europe Data Center Physical Security Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across integrated platform versus point-solution positioning. The market exhibits tiered concentration with three to five integrated vendors commanding hyperscale relationships while regional specialists serve edge deployments. Strategic archetypes include building-automation heritage conglomerates, network-video pure-plays, and security-services integrators. Competitive moves center on modular platform bundling and biometric data management service offerings.
Within the integrated platform tier, Bosch Sicherheitssysteme GmbH and Schneider Electric SE exemplify building-system heritage diversification into unified command architectures. Axis Communications AB occupies a specialist position in network camera architectures. Johnson Controls International plc anchors the security-services integrator archetype through facility management convergence. Honeywell International Inc. and Siemens AG represent industrial conglomerate positioning across environmental and access control integration.
| Leading Market Players |
|---|
| Bosch Sicherheitssysteme GmbH |
| Axis Communications AB |
| Johnson Controls International plc |
| Honeywell International Inc. |
| Schneider Electric SE |
| Securitas Technology AB |
| ABB Ltd |
| Siemens AG |
| Convergint Technologies LLC |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up security integrators across Germany and the Netherlands are consolidating regional specialists into unified platform vendors, tightening pricing discipline on biometric hardware while extending payment terms to upstream semiconductor distributors. This ownership concentration simultaneously compresses margins for component suppliers and elevates bundled-service pricing power toward end-user colocation operators.
Pricing Analysis
Cost-down pressure on Tier III and IV biometric systems accelerates because hyperscale operators in Frankfurt and Amsterdam are consolidating vendor relationships around integrated platform suppliers. Three-tier pricing structure across premium iris-vein multimodal, standard fingerprint-card hybrid, and economy card-only access levels separates authentication precision tiers. Price differentiation hinges on CE marking compliance tier under the EU Radio Equipment Directive and after-sales remote monitoring bundling. Mid-sized colocation providers in the Benelux region exhibit highest price sensitivity, prioritizing SaaS-converted operational expenditure models over capital-intensive hardware ownership.
Supply Chain Analysis
Dual-sourcing mandates from German Tier IV operators require qualified suppliers for both thermal imaging sensors and AI-enabled video analytics processors across Taiwan, South Korea, and Japan. Component supply draws from Asian foundry concentration for edge-computing security gateways, biometric reader chipsets, and wireless intrusion detection modules. Single-source vulnerability in advanced thermal sensor fabrication exposes lead time volatility. Distribution runs through authorized security integrator networks with direct OEM relationships, bypassing traditional IT channel distributors for hyperscale campus deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physical security vendors are racing to capture backward integration into biometric algorithm development and cloud-native security operations platforms, locking in recurring revenue streams that hardware-only competitors cannot replicate.
For Market Incumbents: Anticipate displacement by security-as-a-service platforms by accelerating in-house production of AI-enabled video analytics modules and acquiring regional system integrators in underserved Nordic edge markets. Consolidate around GDPR-compliant biometric data handling certifications to defend against pure-play SaaS entrants targeting mid-sized colocation providers. For New Entrants and Emerging Players: Cloud-native managed access control platforms offer the fastest penetration route into French and Dutch mid-tier colocation facilities seeking operational expenditure conversion. Target Norway and Sweden's renewable-powered edge buildouts where incumbent platform vendor presence remains underdeveloped. Lead with sovereign biometric data storage compliance to differentiate against legacy hardware vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor biometric algorithm specialists with ANSSI or BSI certification traction in France and Germany over hardware-commoditized access control manufacturers. Long-term viability centers on recurring revenue attachment rates from security-as-a-service transitions. Watch NIS2 Directive transposition timelines across member states as the inflection signal for mandatory critical infrastructure spending classification.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Algorithm Acquisition | Captures proprietary iris-vein recognition IP that Tier IV facilities require under BSI directives. |
| Security-as-a-Service Platform Launch | Converts capital expenditure to recurring revenue for Benelux colocation providers prioritizing cash flow predictability. |
| Nordic Edge Facility Partnership | Secures first-mover positioning in Norway and Sweden's renewable-powered micro-data center buildouts. |
| GDPR-Aligned Data Handling Certification | Unlocks French hyperscale contracts ahead of CNIL enforcement timelines for biometric template storage. |
| Building Management System Integration | Opens unified procurement channels with Schneider Electric and Johnson Controls facility management accounts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with data center security directors, biometric system integration specialists, colocation procurement leads, and critical infrastructure compliance officers. BSI technical guidelines, ANSSI cloud security certification documentation, and EU AI Act implementation timelines provided regulatory boundary conditions. Bottom-up facility investment tracking across Frankfurt, Amsterdam, and Paris hyperscale zones triangulated against top-down vendor revenue disclosures.
Granularity-level modeling deployed separate forecast frameworks for security type, solution technology, deployment mode, and facility tier classification across the projection horizon. Biometric authentication adoption curves, video analytics refresh cycle timing, and edge computing facility buildout rates informed segment-specific growth trajectories. CAGRs derived from facility capex pipeline analysis and vendor order backlog visibility.
The model holds under stable NIS2 Directive transposition timelines and continued hyperscale campus expansion in Rhine-Main and Amsterdam corridors; deviation in semiconductor supply chain disruption severity or GDPR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
US Data Center Rack Market