
 New Zealand Data Center Power Market | 2026-2036
New Zealand Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Data Center Power Market Insights
Aftermarket service revenue is tilting toward lifecycle power management contracts as data center operators seek predictable operating expenditure models. Schneider Electric SE leverages its EcoStruxure platform to anchor digital power monitoring across New Zealand facilities. Vertiv Group Corp. competes through thermal and power integration, while Eaton Corporation plc specializes in uninterruptible power supply systems for edge deployments.
Data center power encompasses electrical infrastructure—switchgear, uninterruptible power supplies, power distribution units, and backup generators—engineered to maintain 99.999% uptime for compute environments. This infrastructure converts, conditions, and distributes electricity to servers, storage, and networking equipment across facility scales. The capacity size dimension shows hyperscale facilities commanding capital allocation as international cloud operators establish New Zealand presences, while small and medium scale segments serve enterprise colocation needs in secondary cities. Power source segmentation reveals renewable integration accelerating under national decarbonization policy, with on-site solar and wind procurement reshaping supplier specifications for switchgear and energy storage compatibility.
New Zealand's Commerce Commission regulates electricity transmission pricing that directly affects data center site selection and power contracting structures. The country's national energy regulator governs grid connection standards for large power consumers, while ISO 50001 energy management certification shapes procurement criteria for facility operators. Stakeholders must monitor grid interconnection queue positions and renewable energy certificate availability as hyperscale commitments outpace generation capacity additions.
Market Dynamics
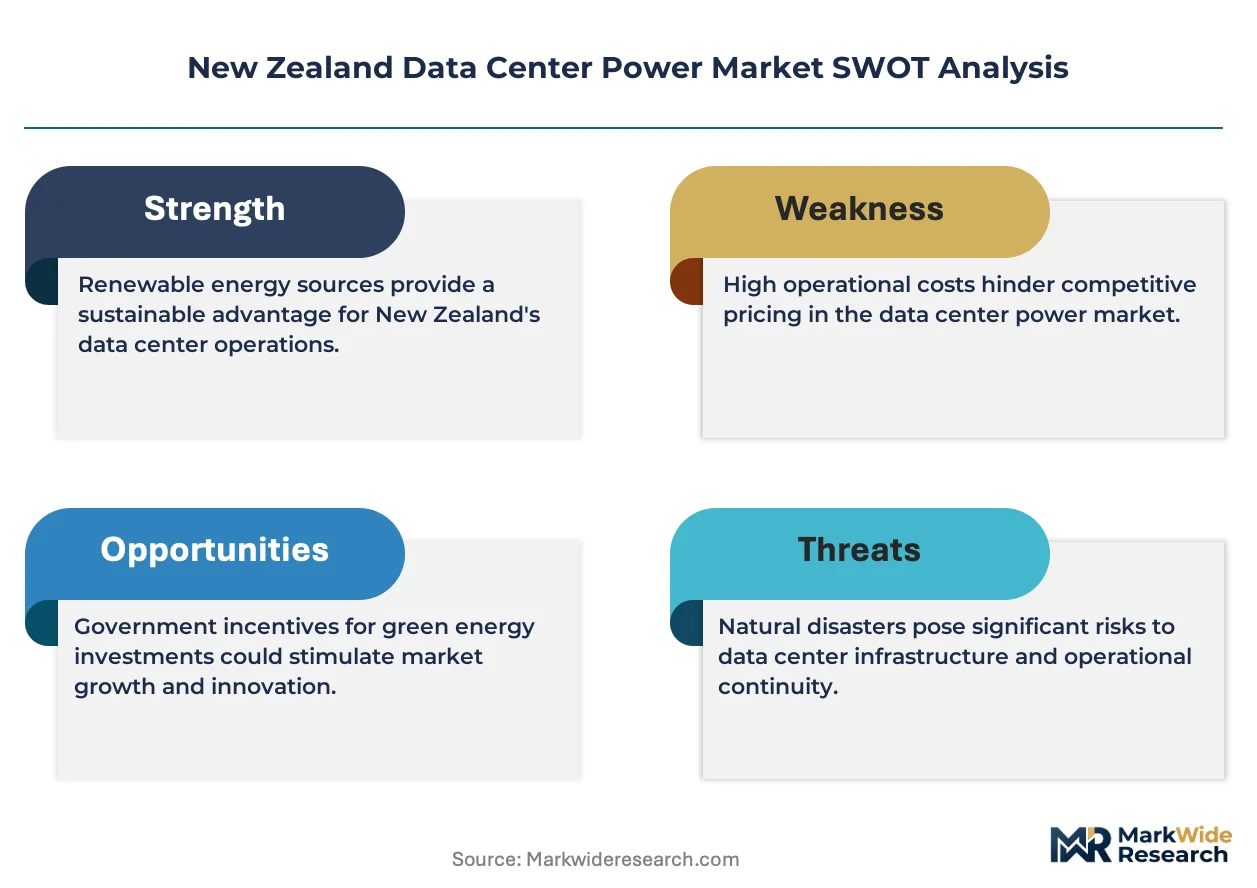
The Zero Carbon Act is compressing data center power infrastructure timelines as facility operators must source renewable electricity while maintaining 99.999% uptime guarantees. This regulatory pressure intersects with Auckland's grid congestion to reshape capital deployment patterns across the North Island.
Growth Catalysts
- Hyperscale facility construction:International cloud operators are establishing presences in Auckland and Christchurch, driving demand for high-capacity switchgear and modular UPS systems.
- ISO 50001 certification mandates:Enterprise colocation providers require energy management certification to secure procurement contracts with financial services and government clients.
- On-site renewable integration:Solar and wind procurement specifications are reshaping supplier requirements for energy storage compatibility and grid-forming inverter technology.
Market Restraints
- Grid interconnection queues:The Commerce Commission's transmission pricing structure creates multi-year delays for large power consumers seeking new connections in Auckland's hyperscale corridor.
- Land scarcity in primary markets:Suitable sites with dual grid feed and fiber access concentrate in limited Auckland industrial zones, inflating site acquisition costs.
- Specialized switchgear lead times:Medium-voltage equipment for 100MW+ facilities faces 18-24 month delivery cycles from European and Asian manufacturers.
Strategic Opportunities
- Christchurch secondary market development:Lower land costs and improving fiber connectivity position the South Island city for enterprise colocation growth.
- Lifecycle power management contracts:Predictable operating expenditure models are displacing transactional maintenance agreements among mid-scale operators.
- Edge computing deployment:Distributed infrastructure for latency-sensitive applications creates demand for compact UPS and generator sets in regional centers.
Industry Challenges
- Electrical engineering talent scarcity:Specialized skills for medium-voltage design and commissioning concentrate among a limited pool of Auckland-based contractors.
- Legacy facility retrofit complexity:Older data centers face integration challenges when upgrading to lithium-ion battery systems and intelligent power monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Data Center Power Market |
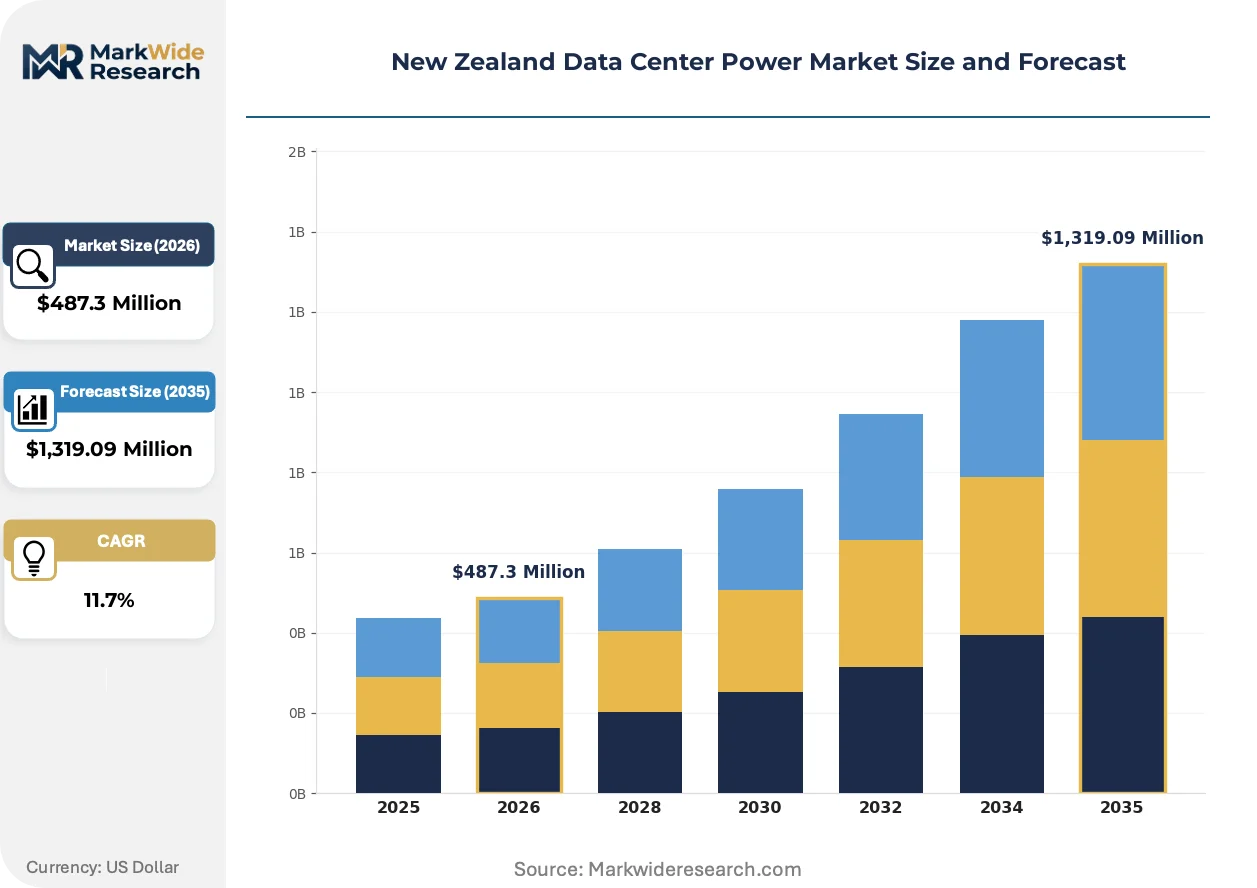
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable, Non-Renewable, Solar, Wind Capacity Size: Small Scale, Medium Scale, Large Scale, Hyper Scale End User Type: Cloud Service Providers, Enterprises, Colocation Providers, Telecommunications Service Type: Managed Services, Infrastructure as a Service, Disaster Recovery, Backup Solutions |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., ABB Ltd., Eaton Corporation plc, Cummins Inc., Rittal GmbH and Co. KG, Fujitsu Limited, Legrand Group, Delta Electronics Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Data Center Power Market Trends and Innovations
Power infrastructure architecture is converging around software-defined energy management as operators seek granular visibility into consumption patterns. This shift is compressing traditional boundaries between electrical and thermal systems.
Intelligent power distribution units with embedded metering and remote switching capability are hybridizing rack-level infrastructure. Hyperscale operators in Auckland are deploying these units at scale to enable dynamic workload placement. The technology is compressing the traditional separation between facility and IT operations teams.
New Zealand's Zero Carbon Act is mandating renewable energy integration for critical infrastructure through binding emissions budgets. Facility operators must now secure renewable energy certificates and on-site generation to maintain social license. The policy is most acute for hyperscale developments where power purchase agreements must align with construction timelines.
Enterprise buyers are consolidating vendor relationships to reduce integration complexity across electrical and thermal systems. Single-source contracting for power and cooling infrastructure is displacing fragmented procurement among mid-scale colocation providers. This concentration is most visible in Wellington's government and financial services verticals where compliance documentation requirements favor streamlined supplier management.
New Zealand Data Center Power Market Segmentation
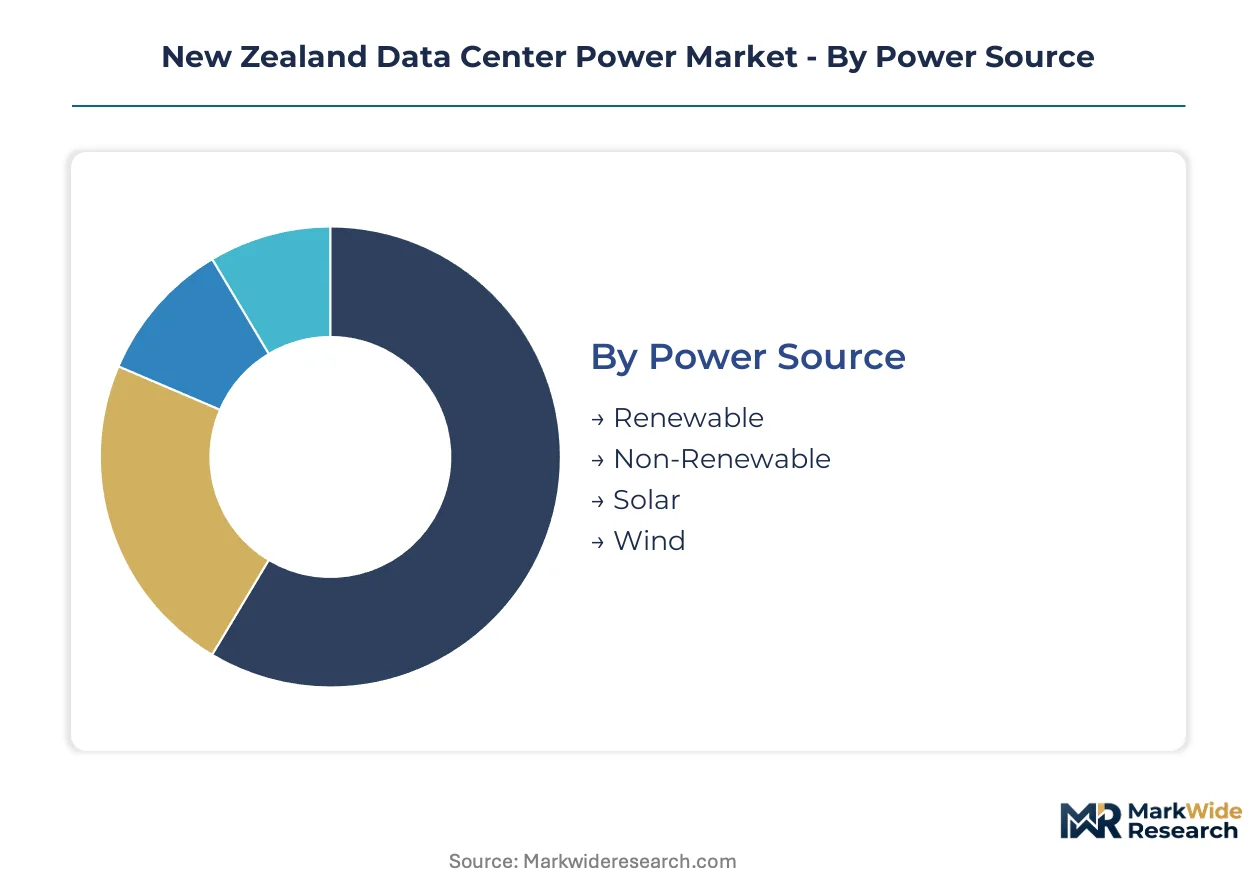
Segmentation in New Zealand's data center power market reveals how regulatory pressure and infrastructure constraints fragment procurement patterns. The Zero Carbon Act and Auckland's grid congestion create divergent requirements across facility scales and power sourcing strategies.
Power Source:
Mature grid-connected supply coexists with emerging on-site generation as operators navigate renewable mandates.
- Renewable:Grid-sourced renewable electricity through power purchase agreements dominates hyperscale procurement in Auckland. The Zero Carbon Act's binding emissions budgets force operators to secure certificates that align with facility commissioning timelines.
- Non-Renewable:Conventional grid power retains critical backup functions for legacy facilities and transitional capacity. Christchurch's secondary market shows higher tolerance for conventional sourcing where renewable certificate availability lags construction schedules.
- Solar:On-site photovoltaic arrays address land-constrained sites through rooftop and carport installations. Wellington government facilities specify solar-integrated switchgear for compliance documentation.
- Wind:Utility-scale wind procurement reshapes supplier specifications for grid-forming inverter compatibility. Canterbury's wind resource concentration drives South Island operator preferences.
Renewable handles the majority of throughput; solar is the fastest mover on share.
Capacity Size:
Cost tier separation between hyperscale capital deployment and mid-scale operational expenditure models defines procurement behavior.
- Hyper Scale:Facilities exceeding 100MW command dedicated medium-voltage infrastructure and multi-year equipment lead times. Auckland's hyperscale corridor concentrates international cloud operator demand where dual grid feed requirements eliminate most candidate sites.
- Large Scale:Enterprise and regional colocation facilities in the 10-50MW range balance capital efficiency with redundancy requirements. Hamilton and Tauranga emerging zones attract this segment seeking lower land costs than Auckland.
- Medium Scale:Secondary city enterprise deployments prioritize modular UPS systems and lifecycle service contracts. Dunedin and Palmerston North show concentration among financial services verticals.
- Small Scale:Edge and remote office infrastructure demands compact generator sets and lithium-ion battery systems. Queenstown's tourism technology sector drives distributed deployment.
Hyper scale absorbs the dominant capital allocation; small scale is expanding most quickly as latency requirements proliferate.
End User Type:
Application-specific uptime requirements and compliance obligations differentiate procurement across buyer categories.
- Cloud Service Providers:Hyperscale operators specify software-defined power management and intelligent PDUs for dynamic workload placement. Auckland and Christchurch presences drive standardization across Asia-Pacific architectures.
- Enterprises:Financial services and government verticals in Wellington mandate ISO 50001 certification and documented renewable sourcing. Procurement favors single-source electrical and thermal contracting to reduce integration risk.
- Colocation Providers:Mid-scale operators compete through predictable operating expenditure models and lifecycle power management contracts. Christchurch secondary market development targets this segment with lower land costs.
- Telecommunications:Distributed infrastructure for 5G edge and rural broadband creates demand for compact UPS and rapid-deployment generator sets. Regional center deployment accelerates under connectivity mandates.
Cloud service providers command the largest facility footprints; telecommunications is gaining share fastest on deployment velocity.
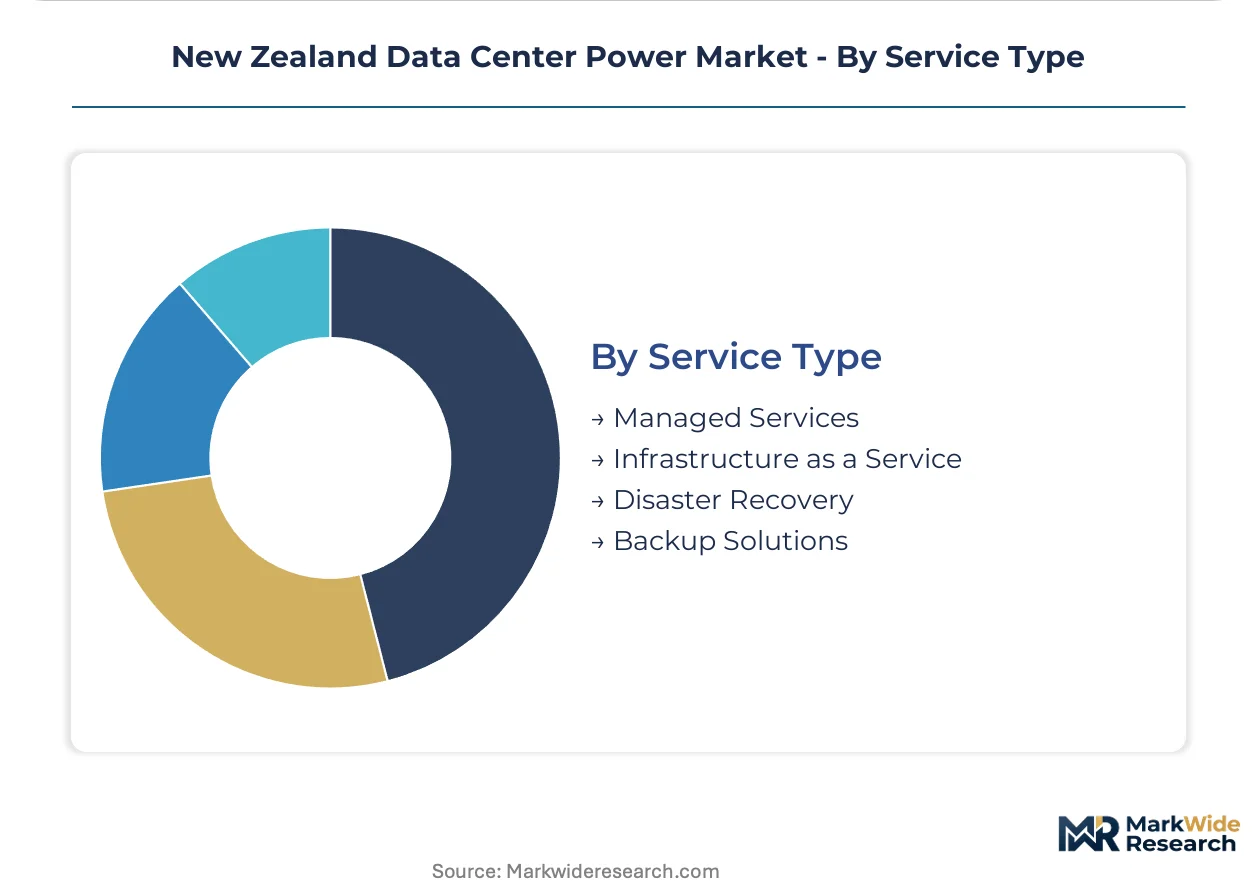
Service Type:
Customer type and margin structure separate transactional infrastructure provision from outcome-based operational contracts.
- Infrastructure as a Service:Power capacity bundled with compute and storage resources shifts capital burden to operator balance sheets. Hyperscale providers in Auckland dominate this segment through scale economies.
- Managed Services:Lifecycle power management contracts with predictable opex models displace transactional maintenance among mid-scale operators. Schneider Electric's EcoStruxure platform anchors digital monitoring penetration.
- Disaster Recovery:Secondary site power redundancy requirements in Christchurch and Wellington specify rapid-start generator sets and battery bridging systems. Financial services procurement drives certification stringency.
- Backup Solutions:Standalone UPS and generator procurement serves legacy facility retrofits and incremental capacity additions. Lithium-ion battery integration challenges create specialist commissioning demand.
Infrastructure as a Service captures the dominant revenue pool; managed services shows the steepest expansion trajectory as opex preferences harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across New Zealand's data center power landscape. Auckland hyperscale operators absorb premium infrastructure costs for scarce grid access, while Christchurch and secondary city buyers prioritize capital efficiency and shorter payback periods.
Auckland
International cloud operators drive demand for 100MW+ facilities with dual grid feed requirements. The Commerce Commission's transmission pricing structure creates multi-year interconnection queues that compress development timelines. Auckland's hyperscale corridor concentrates construction activity where land with fiber and redundant power access commands substantial premiums.
Christchurch
Lower land costs and improving fiber connectivity attract enterprise colocation providers seeking operational expenditure efficiency. Canterbury's wind resource concentration enables renewable power purchase agreements that align with Zero Carbon Act compliance schedules. The South Island city is developing secondary market capacity as Auckland grid constraints harden.
Wellington
Government and financial services verticals mandate ISO 50001 certification and documented renewable sourcing for procurement eligibility. The national energy regulator's grid connection standards apply stringently to capital city facilities serving critical public infrastructure. Wellington's government cluster specifies single-source electrical and thermal contracting to reduce integration risk.
Hamilton
Emerging zone status attracts large-scale operators in the 10-50MW range seeking lower land costs than Auckland. Proximity to Auckland's fiber backbone enables latency-competitive positioning for enterprise workloads. The Waikato region's grid capacity offers faster interconnection timelines than the congested northern corridor.
Queenstown
Tourism technology sector demand drives distributed edge deployment for latency-sensitive applications. Compact lithium-ion battery systems and rapid-deployment generator sets serve remote office infrastructure requirements. The resort city's geographic isolation necessitates self-contained power architecture with limited grid redundancy options.
New Zealand Data Center Power Market Competitive Landscape
Integrated platform providers and specialized infrastructure suppliers split the market into distinct competitive spheres. The vendor base concentrates around electrical and thermal system integration capabilities, with consolidation pressure intensifying as enterprise buyers reduce supplier counts. Two strategic archetypes dominate: full-stack platform vendors leveraging software-defined monitoring, and component specialists commanding premium positioning in backup power and thermal management. Competitive dynamics center on lifecycle service contract capture and geographic expansion into Christchurch's developing secondary market.
Within the integrated platform tier, Schneider Electric SE and Vertiv Group Corp. exemplify contrasting approaches to market positioning. Schneider Electric SE anchors its presence through digital power monitoring platforms that span facility scales. Vertiv Group Corp. occupies a complementary position emphasizing thermal and power integration capabilities. Eaton Corporation plc represents the specialized infrastructure archetype, with its positioning in uninterruptible power supply systems serving edge deployment requirements. These three companies collectively illustrate the competitive structure's bifurcation between comprehensive platform provision and targeted component excellence.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| ABB Ltd. |
| Eaton Corporation plc |
| Cummins Inc. |
| Rittal GmbH and Co. KG |
| Fujitsu Limited |
| Legrand Group |
| Delta Electronics Inc. |
| Others |
Pricing and Supply Chain Analysis
Auckland's hyperscale corridor concentrates procurement leverage for international cloud operators, compressing margins for electrical infrastructure suppliers while amplifying pricing power for contractors with medium-voltage commissioning expertise. The Zero Carbon Act's renewable integration mandates add certification premiums to switchgear and energy storage systems, reshaping total cost of ownership calculations across facility scales.
Pricing Analysis
Lifecycle power management contracts now anchor lifetime value capture as data center operators abandon transactional maintenance for predictable opex models. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 50001 certification status and grid-forming inverter compatibility. Cost compression in standard-tier switchgear intensifies because European and Asian manufacturers face elongated production queues. Mid-scale colocation providers in Christchurch exhibit highest price sensitivity, while Auckland hyperscale operators absorb premiums for dual grid feed assurance.
Supply Chain Analysis
Extended payment terms from New Zealand facility operators to European switchgear manufacturers now stretch 90-120 days, straining working capital for specialized component suppliers. Manufacturing concentrates in Germany, China, and South Korea for medium-voltage equipment and lithium-ion battery systems. Raw material dependencies center on copper busbar, silicon carbide semiconductors, and rare-earth magnet supply for grid-forming inverters. Single-source vulnerability from Taiwan-based power semiconductor foundries creates exposure to geopolitical disruption. Distribution runs through Auckland-based electrical contractors with exclusive relationships to hyperscale developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as hyperscale construction commitments lagged during grid interconnection queue expansion and now accelerate through the Commerce Commission's revised transmission pricing framework.
For Market Incumbents: Insulate recurring revenue streams by converting transactional UPS and generator sales into lifecycle power management contracts with embedded digital monitoring. Deepen backward integration into lithium-ion battery assembly to capture margin compression from raw material volatility. Anchor defensibility through EcoStruxure-type platform stickiness that raises switching costs for enterprise colocation clients. For New Entrants and Emerging Players: Build out Christchurch secondary market presence before land cost arbitrage closes, targeting 10-50MW enterprise colocation facilities underserved by Auckland-centric incumbents. Penetrate the telecommunications edge computing vertical through compact UPS and rapid-deployment generator sets for 5G infrastructure. Lead with grid-forming inverter specialization that aligns with Zero Carbon Act procurement specifications. For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because the Zero Carbon Act creates durable demand for renewable-integrated power systems with 99.999% uptime guarantees. Target acquisition archetypes are mid-scale contractors with medium-voltage commissioning capabilities and established Commerce Commission interconnection relationships. Watch grid interconnection queue clearance rates as the primary inflection signal for construction velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contract Conversion | Schneider Electric's EcoStruxure penetration demonstrates platform stickiness raising customer switching costs. |
| Christchurch Geographic Expansion | Canterbury wind resource concentration enables renewable PPA structures that satisfy Zero Carbon Act timelines. |
| Grid-Forming Inverter Specialization | Compatibility with on-site solar and wind procurement reshapes supplier specifications for hyperscale switchgear. |
| Backward Integration into Energy Storage | Lithium-ion battery assembly capture mitigates margin pressure from 18-24 month European equipment lead times. |
| ISO 50001 Certification Investment | Wellington government and financial services verticals mandate documented energy management for procurement eligibility. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented grid interconnection standards and Commerce Commission transmission pricing structures. Conversations with data center facility operators, electrical engineering contractors, switchgear procurement managers, and renewable energy certificate traders informed demand-side assumptions. Secondary sources include the Electricity Authority's distribution pricing methodologies, ISO 50001 certification databases, and hyperscaler capex disclosure filings. Bottom-up facility deployment tracking and top-down grid capacity modeling were triangulated to constrain variance.
Calibration against historical construction completion rates and interconnection queue clearance patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include power source type, capacity size tier, end user category, and service delivery model. CAGRs were derived from facility pipeline tracking and equipment order book analysis. Industry-specific forecast inputs encompass renewable energy certificate availability trajectories and medium-voltage equipment manufacturer capacity utilization.
Stress conditions across grid interconnection timeline elongation, European switchgear delivery delays, and renewable certificate supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about Commerce Commission pricing reforms and Zero Carbon Act enforcement intensity. Macroeconomic contraction, regulatory rollback, or breakthrough in solid-state battery technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Hong Kong Data Center Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Japan Data Center Construction Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
Virtualized Data Center Market