
 Belgium Data Center Physical Security Market | 2026-2036
Belgium Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Data Center Physical Security Market Insights
The capability gap between integrated platform providers and component specialists is unwinding competitive dynamics across Belgium's data center security landscape. Axis Communications AB leverages its video analytics ecosystem to anchor premium positioning in camera-centric deployments. Bosch Sicherheitssysteme GmbH sustains engineering depth in intrusion detection through in-house sensor manufacturing. Johnson Controls competes on building-automation convergence, merging physical security with HVAC and fire suppression command layers.
Belgium data center physical security encompasses perimeter barriers, biometric access control, video surveillance infrastructure, and intrusion detection systems engineered to protect mission-critical computing facilities against unauthorized physical access, environmental threats, and deliberate sabotage. These systems typically integrate IP-based camera networks with centralized video management platforms capable of real-time analytics and forensic retrieval. Surveillance cameras dominate technology expenditure as operators prioritize AI-enhanced video verification over passive recording. Monitoring services within the service-type dimension capture expanding margin pools as remote guarding replaces on-site personnel at edge facilities. Cloud service providers among end users drive fastest-growing demand through hyperscale buildouts in Hainaut and Antwerp provinces.
Belgium's national cybersecurity authority implements EU NIS2 requirements mandating physical access logs and perimeter resilience audits for operators of essential services. The country's federal police infrastructure protection unit coordinates threat intelligence sharing with data center operators against organized intrusion risks. Stakeholders must weigh the trade-off between cloud-native security platform consolidation and sovereign data residency requirements as Brussels positions itself as a GDPR-compliant hub.
Market Dynamics
The transposition of the EU NIS2 Directive into Belgian national law is compressing procurement timelines as operators race to achieve physical resilience certification before enforcement deadlines tighten.
Growth Catalysts
- Hyperscale colocation buildouts:Cloud service providers are expanding facility footprints across Flanders and Wallonia, driving concentrated demand for multi-layered perimeter protection systems in Brussels-Capital Region clusters.
- NIS2 physical access mandates:Belgium's national cybersecurity authority now requires perimeter resilience audits and granular access logs for operators of essential services, forcing infrastructure upgrades across critical facilities.
- AI-enhanced video verification:Surveillance infrastructure is displacing passive recording as operators prioritize real-time analytics capable of forensic retrieval and automated threat classification.
Market Restraints
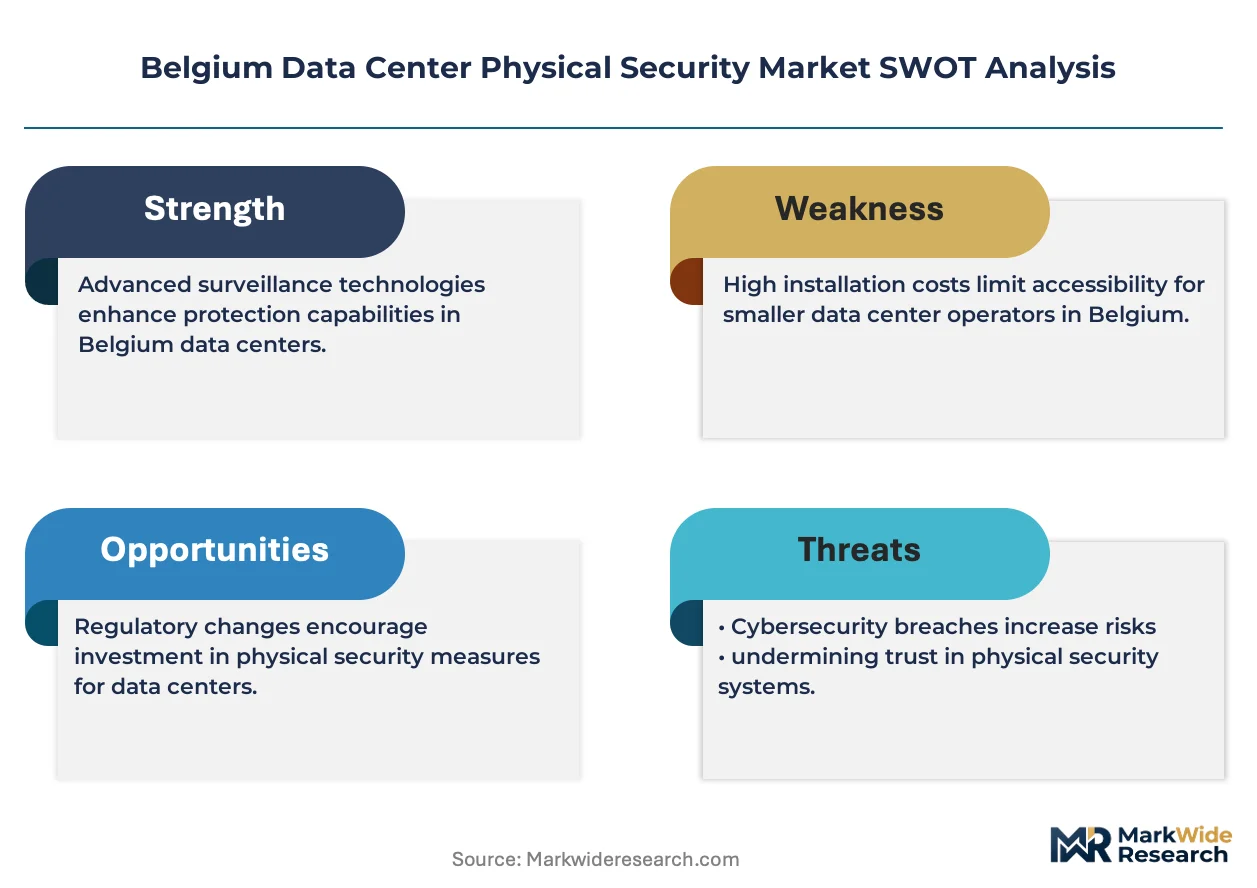
- Specialized engineering talent scarcity:The shallow pool of Belgian technicians certified in integrated building-automation and physical security convergence limits deployment velocity for complex multi-system installations.
- Component supply concentration:High-grade biometric sensors and edge-computing cameras depend on concentrated Asian manufacturing, exposing Belgian integrators to extended lead times and input cost volatility.
- Sovereign data residency friction:Cloud-native security platform consolidation conflicts with GDPR-compliant data localization requirements, complicating vendor selection for Brussels-based operators.
Strategic Opportunities
- Edge facility remote guarding:Monitoring services capture expanding margin pools as distributed computing nodes outside major urban clusters replace on-site personnel with centralized video verification.
- Hainaut province hyperscale corridors:Underpenetrated industrial zones south of Brussels offer greenfield deployment opportunities for integrated perimeter-barrier and intrusion-detection systems.
- Federal police threat intelligence integration:The infrastructure protection unit's coordinated information-sharing protocols create openings for vendors offering predictive analytics aligned with organized intrusion risk profiles.
Industry Challenges
- Multi-system integration complexity:Converging HVAC, fire suppression, and physical security command layers demands cross-functional engineering expertise that Belgian system integrators struggle to staff.
- NIS2 compliance timeline compression:Operators face compressed windows to implement physical access log architectures and perimeter audit documentation before federal enforcement mechanisms activate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Data Center Physical Security Market |
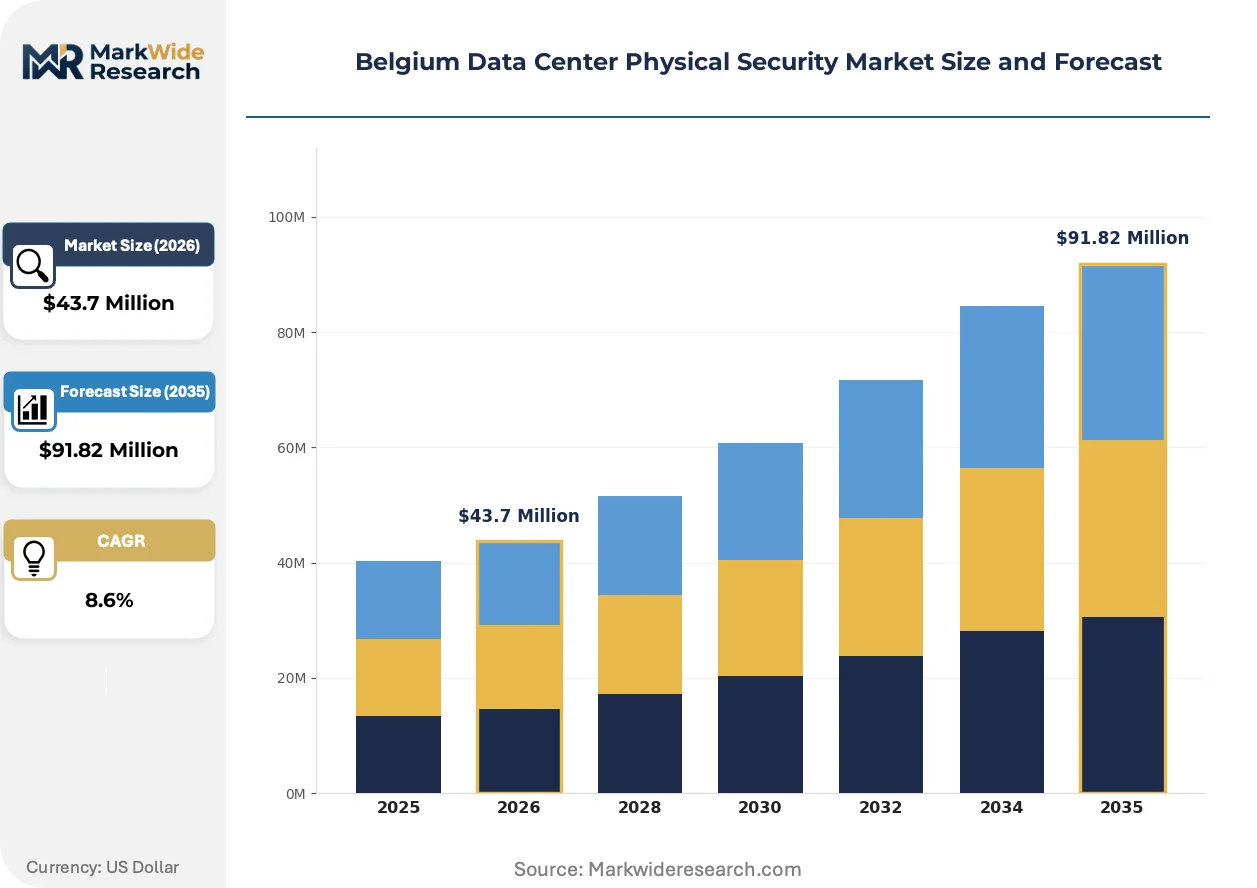
| Market Size in 2026 | $43.7 Million |
| Market Size in 2035 | $91.82 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Cameras, Access Control Systems, Intrusion Detection Systems, Fire Detection Systems Service Type: Installation Services, Monitoring Services, Maintenance Services, Consulting Services End User: Telecommunication Companies, Cloud Service Providers, Financial Institutions, Government Agencies Solution: Integrated Security Solutions, Video Surveillance Solutions, Perimeter Security Solutions, Access Management Solutions |
| Companies Covered | Axis Communications AB, ABB Ltd, Securitas Technology, Bosch Sicherheitssysteme GmbH, Johnson Controls, Honeywell International Inc., Siemens AG, Schneider Electric, Cisco Systems Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Data Center Physical Security Market Trends and Innovations
Belgian data center operators are reconfiguring security architectures around predictive rather than reactive threat detection, compressing the gap between intrusion attempt and system response.
Edge-based video analytics is fragmenting the traditional centralized video management model. IP camera networks now deploy GPU-enabled processing nodes capable of on-device threat classification. Hyperscale operators in Antwerp province are adopting these distributed architectures fastest. The shift is fragmenting vendor relationships as component specialists capture value previously held by integrated platform providers.
The EU NIS2 Directive's Belgian transposition mandates physical resilience audits with documented remediation timelines. Operators must now maintain granular access logs and perimeter breach simulation records. Colocation providers in Brussels-Capital Region face the steepest compliance burden, accelerating procurement of biometric access control systems with immutable audit trails.
Cloud service providers are consolidating vendor relationships around outcome-based service contracts rather than capital equipment purchases. Remote guarding and predictive maintenance subscriptions displace traditional hardware-procurement cycles. This behavioral shift is most visible among hyperscale operators in Hainaut province, where facility buildouts prioritize operational expenditure models over owned security infrastructure.
Belgium Data Center Physical Security Market Segmentation
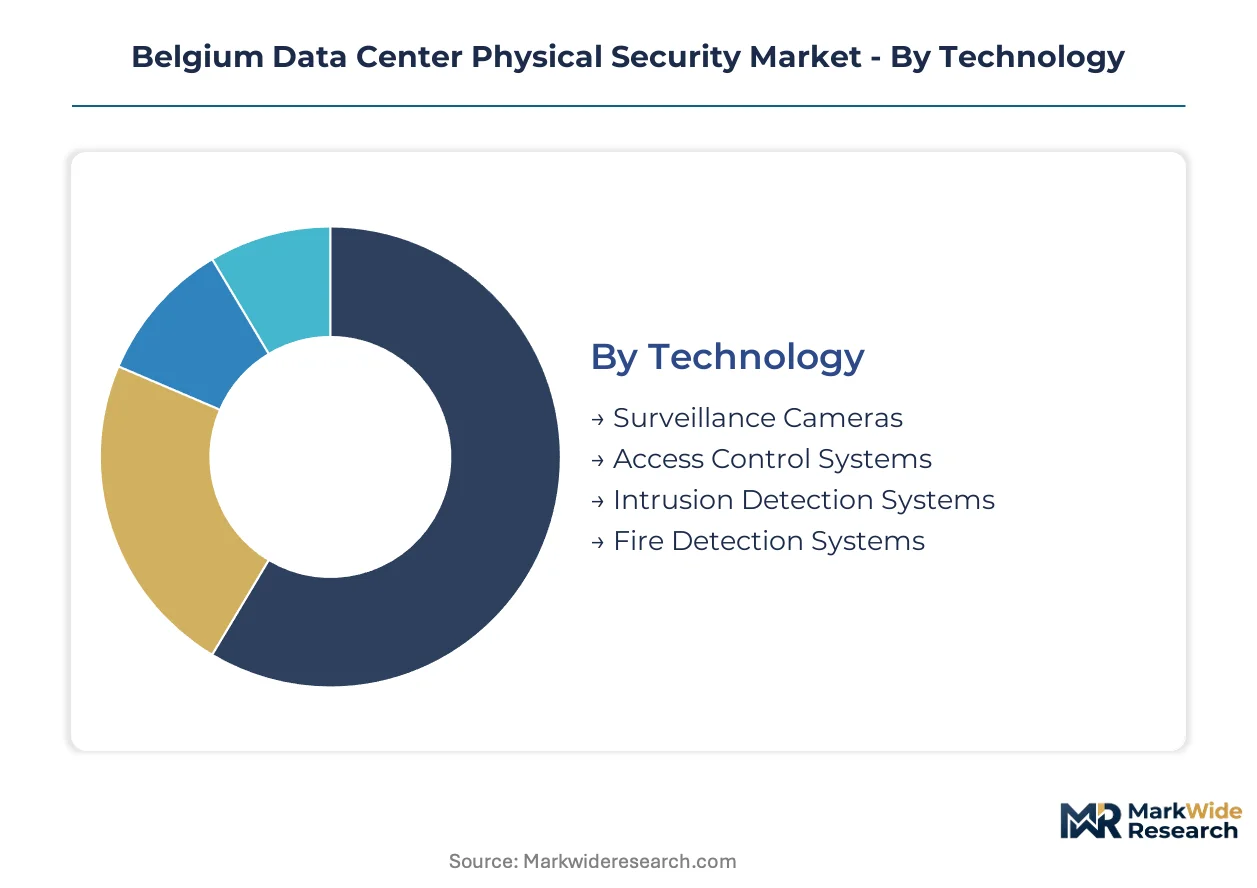
Belgian data center operators configure security procurement around four intersecting dimensions. Technology choices determine capital allocation intensity. Service-type selections shift cost structures between fixed and operational expenditure. End-user profiles dictate compliance stringency. Solution architectures reveal vendor consolidation versus best-of-breed preferences.
Technology:
Margin pools concentrate in video analytics-enabled surveillance infrastructure as operators prioritize AI-enhanced verification over passive monitoring.
- Surveillance Cameras:IP-based camera networks with edge GPU processing enable on-device threat classification. Cloud service providers in Antwerp province deploy these fastest, driven by remote guarding requirements at hyperscale facilities.
- Access Control Systems:Biometric readers and multi-factor authentication terminals form perimeter defense layers. Brussels-Capital Region colocation clusters demand immutable audit trails to satisfy federal cybersecurity authority mandates under NIS2.
- Intrusion Detection Systems:Sensor arrays combining volumetric, seismic, and fiber-optic cable detection protect facility perimeters. Wallonia industrial zones show rising specification for integrated barrier-intrusion combinations.
- Fire Detection Systems:Very early smoke detection apparatus with aspirating sensors protects high-density compute halls. Financial institutions in Brussels mandate redundant detection zones above regulatory minimums.
Surveillance cameras hold installed capacity. Access control systems are rotating up the share rankings.
Service Type:
Cost tier stratification separates capital-intensive installation from recurring-revenue monitoring subscriptions.
- Monitoring Services:Centralized video verification and alarm response centers replace on-site personnel. Edge facilities across Flanders drive fastest expansion as distributed computing nodes proliferate outside urban cores.
- Installation Services:System integration encompassing cabling, device mounting, and platform configuration demands certified technicians. Hainaut province hyperscale buildouts strain available Belgian engineering capacity.
- Maintenance Services:Preventive servicing contracts and firmware update management ensure operational continuity. Government agencies specify longest contract terms to minimize procurement cycle burden.
- Consulting Services:Physical security assessments and NIS2 compliance roadmap development support certification preparation. Brussels-based operators engage these most intensively given enforcement timeline pressure.
Installation services dominate contract value. Monitoring services are climbing the fastest as subscription models displace hardware ownership.
End User:
Application requirements diverge sharply between latency-sensitive telecommunications and sovereignty-focused government deployments.
- Cloud Service Providers:Hyperscale operators in Hainaut and Antwerp provinces drive multi-layered perimeter protection demand. These entities prioritize outcome-based service contracts over capital equipment procurement.
- Telecommunication Companies:Carrier-neutral facilities and edge computing nodes require standardized security architectures. Flanders regional networks concentrate investment in remote monitoring capabilities.
- Financial Institutions:Brussels-based banks and payment processors mandate biometric access control with granular audit logging. Federal financial regulator oversight elevates specification above commercial norms.
- Government Agencies:Federal and regional administrative data centers face strictest physical resilience requirements. classified facility operators procure integrated solutions with sovereign data residency guarantees.
Cloud service providers anchor volume demand. Government agencies are expanding specification fastest as critical infrastructure classification broadens.
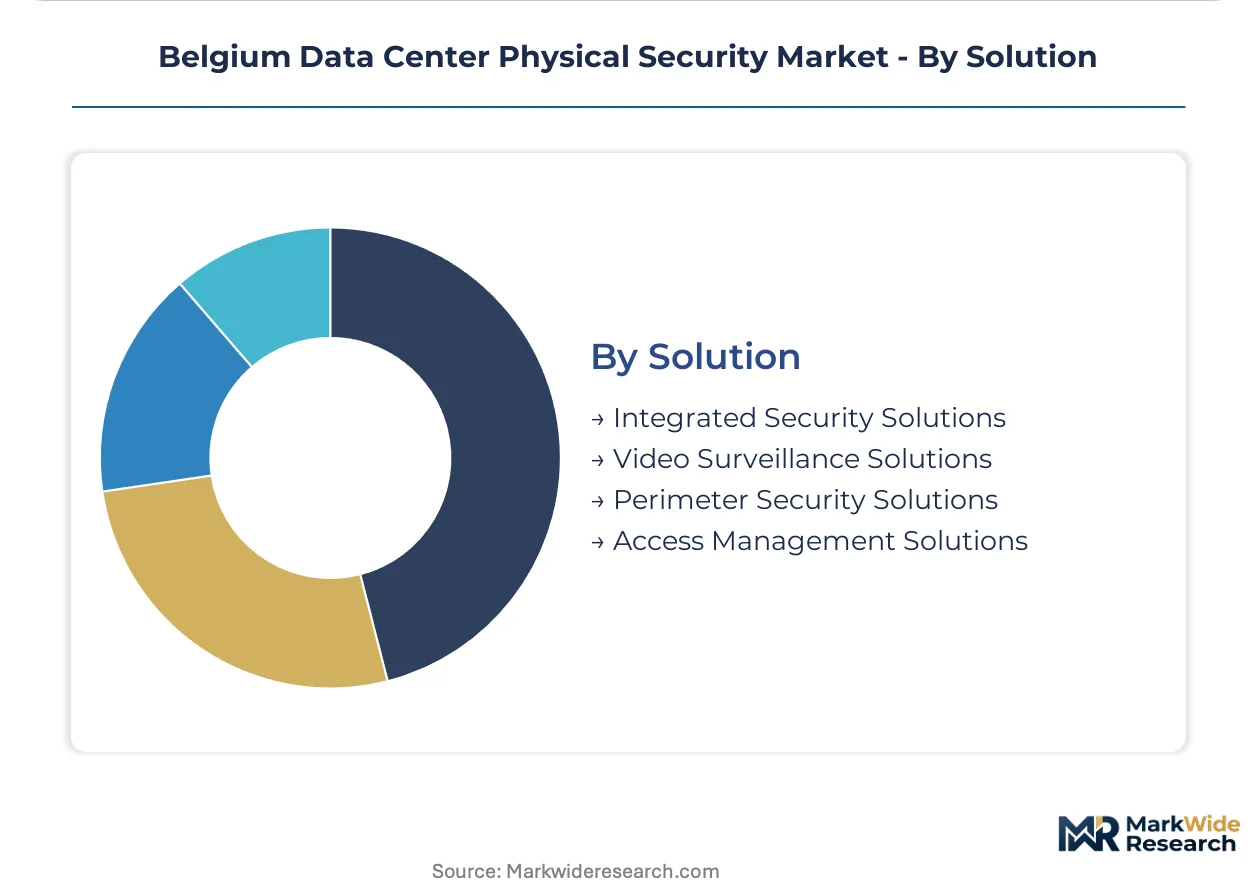
Solution:
Customer type preferences split between unified command platforms and specialized point solutions.
- Integrated Security Solutions:Converged platforms merging video, access, intrusion, and building automation command layers. Large colocation providers in Brussels-Capital Region specify these to reduce multi-vendor complexity.
- Video Surveillance Solutions:Standalone camera networks with centralized or edge-distributed management. Mid-tier operators favor these for procurement flexibility and component upgrade paths.
- Perimeter Security Solutions:Barrier systems, fence detection, and exterior intrusion detection combinations. Greenfield industrial zone developments in Wallonia specify hardened perimeter architectures.
- Access Management Solutions:Credential lifecycle management and visitor processing workflows. Multi-tenant colocation facilities deploy these to segregate client environments.
Integrated security solutions capture premium positioning. Video surveillance solutions are gaining share fastest as edge analytics fragments vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium commands pricing power over Wallonia's industrial zones, while Flanders competes on deployment velocity rather than margin capture. This asymmetry shapes procurement patterns across the country's three linguistic regions.
Brussels-Capital Region
Hyperscale colocation clusters drive multi-layered perimeter protection demand. The national cybersecurity authority enforces NIS2 physical resilience audits with documented remediation timelines. Financial institutions and EU institutions concentrate security procurement in the capital's dense facility corridors.
Flanders
Antwerp province anchors cloud service provider buildouts requiring AI-enhanced video verification systems. The Flemish government coordinates regional infrastructure protection protocols with federal police threat intelligence sharing. Edge computing nodes proliferate outside urban cores, expanding remote guarding subscriptions.
Wallonia
Hainaut province offers greenfield deployment opportunities for integrated perimeter-barrier systems at underpenetrated industrial sites. The Walloon Region's economic development agencies incentivize critical infrastructure resilience investments. Charleroi and Mons corridors attract hyperscale facility construction with hardened security specifications.
Belgium Data Center Physical Security Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting vendor relationships across Belgium's data center security procurement. Integrated platform providers compete on building-automation convergence, while component specialists capture value through edge-analytics specialization. Three archetypes dominate: video-centric technology licensors, intrusion-detection engineering houses, and building-systems integrators. Competitive dynamics center on M&A-driven capability expansion and outcome-based service contract transitions.
Among Swedish-origin video technology specialists, Axis Communications AB exemplifies the analytics-anchored archetype through ecosystem-driven premium positioning. German engineering houses Bosch Sicherheitssysteme GmbH and Siemens AG occupy positions within the integrated building-systems tier, converging physical security with HVAC and fire suppression command layers. Johnson Controls represents the North American building-automation convergence model, merging facility infrastructure management with perimeter protection workflows.
| Leading Market Players |
|---|
| Axis Communications AB |
| ABB Ltd |
| Securitas Technology |
| Bosch Sicherheitssysteme GmbH |
| Johnson Controls |
| Honeywell International Inc. |
| Siemens AG |
| Schneider Electric |
| Cisco Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for GPU-enabled edge cameras from Taiwanese contract manufacturers compress procurement windows and amplify pricing power for distributors holding buffer inventory. Belgian system integrators face margin pressure as cloud service providers shift toward subscription-based remote guarding contracts, decoupling hardware ownership from operational expenditure.
Pricing Analysis
Configured-to-order biometric access systems command a 15-25% premium over standard catalog configurations, reflecting engineering customization for NIS2-compliant audit architectures. Subscription-tiered pricing dominates as hyperscale operators in Hainaut province favor outcome-based service contracts over capital equipment procurement. Price differentiation rests on certification grade—CE-marked versus UL-listed components—and vertical integration depth of sensor manufacturing. Cost compression in mid-tier video surveillance intensifies as Asian OEMs expand direct distribution, eroding traditional integrator markups. Government agencies exhibit lowest price sensitivity due to sovereign data residency mandates, while mid-tier colocation providers face acute margin pressure from multi-system integration requirements.
Supply Chain Analysis
Strait of Malacca transit vulnerability exposes Belgian integrators to disruption in semiconductor-laden camera modules originating from Taiwanese and South Korean fabrication facilities. High-grade biometric sensors and edge-computing GPUs draw from concentrated manufacturing in China, Taiwan, and South Korea, creating single-source dependency for facial recognition algorithms. Supply chain risk centers on tariff exposure as EU-China trade friction escalates input cost volatility for IP camera networks. Distribution runs through authorized distributor networks serving Brussels-Capital Region colocation clusters, with direct OEM relationships gaining share among hyperscale operators seeking volume pricing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping vendor consolidation as edge-analytics fragmentation enables component specialists to capture value previously held by integrated building-automation providers. Interoperability standards around ONVIF and MQTT protocols accelerate ecosystem unbundling.
For Market Incumbents: Secure firmware update architectures and immutable audit trail capabilities to defend against cloud-native security platform entrants. Deepen in-house production of AI-enabled video analytics chips to reduce dependency on Taiwanese semiconductor foundries. Channel control through certified installer networks remains critical as Belgian engineering talent scarcity limits deployment velocity for complex multi-system installations. For New Entrants and Emerging Players: Anchor in Hainaut province's underpenetrated industrial corridors where greenfield hyperscale buildouts lack established vendor relationships. Target edge facility remote guarding as the most penetrable service segment, where distributed computing nodes outside urban cores seek centralized video verification. A direct-to-operator SaaS model bypassing traditional integrator markups offers the clearest go-to-market angle against incumbent platform providers. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because physical resilience mandates under EU NIS2 Directive transposition create durable compliance-driven demand. Acquisition targets should display edge-analytics software stacks with federal police threat intelligence integration capabilities. The signal to watch is enforcement timeline acceleration by Belgium's national cybersecurity authority, which would compress procurement cycles and favor pre-certified vendor portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Analytics Platform Integration | GPU-enabled on-device threat classification displaces centralized video management in Antwerp hyperscale facilities. |
| NIS2 Compliance Certification Investment | Immutable access log architectures satisfy federal cybersecurity authority mandates for Brussels colocation operators. |
| Remote Guarding Service Launch | Subscription-based monitoring captures margin pools as Flanders edge facilities replace on-site personnel. |
| Threat Intelligence Partnership | Federal police infrastructure protection unit integration enables predictive analytics aligned with organized intrusion profiles. |
| Biometric Sensor Manufacturing Scale-Up | In-house production of multi-factor authentication terminals reduces Asian supply chain concentration exposure. |
Research Methodology
Operator-level perspectives from data center security directors, federal infrastructure protection officers, and Belgian system integrator technical leads anchored the qualitative base for this analysis. Primary interviews with cloud service provider procurement teams and colocation facility managers combined with secondary validation from EU NIS2 implementation guidance documents, federal police threat assessment publications, and customs trade data on security equipment imports. Bottom-up facility buildout tracking across Brussels-Capital Region, Flanders, and Wallonia triangulated against top-down market sizing from technology expenditure disclosures.
Sensitivity analysis around enforcement timeline scenarios and hyperscale capex cycles informed the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, service-type cost structure, end-user compliance stringency, and solution architecture preference. CAGRs were derived from installed base growth rates and replacement cycle compression. Industry-specific forecast inputs encompass NIS2 physical resilience audit penetration rates and edge facility proliferation patterns outside major urban clusters.
Decision-makers should treat outputs as directional under assumptions of steady EU regulatory enforcement and continued hyperscale investment in Belgian industrial zones; material deviation in either would warrant model refresh. Forecasts reflect base-case assumptions around supply chain normalization and engineering talent availability. Practitioners should keep alternative scenarios live as federal cybersecurity authority enforcement mechanisms and EU-China trade policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Spain Data Center Physical Security Market