
 Leadless Pacing Systems Market | 2026-2036
Leadless Pacing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Leadless Pacing Systems Market Foresight
Hospital procurement committees are unwinding their historical preference for conventional transvenous systems as outpatient cardiology clinics gain implant share. Medtronic plc anchors its position through captive manufacturing of miniaturized pulse generators. Abbott Laboratories differentiates via wireless communication protocols integrated into dual-chamber platforms. Boston Scientific Corporation competes on R&D intensity in arrhythmia-specific device architectures.
Leadless pacing systems are self-contained implantable cardiac rhythm devices that eliminate transvenous leads through catheter-based deployment of miniaturized pulse generators directly into the right ventricle or atrium, typically operating on lithium-carbon monofluoride cells with projected service lives exceeding twelve years. Single-chamber devices dominate current implant volumes due to established reimbursement and simpler deployment protocols, while dual-chamber systems represent the fastest-growing product category as atrioventricular synchrony technology matures. Among end users, cardiology clinics are capturing margin pools previously held by hospital catheterization labs as ambulatory surgical center certifications expand.
FDA premarket approval requirements and EU MDR conformity assessments shape product development timelines and market access trajectories for manufacturers seeking multi-region commercialization. The EPA oversees lithium battery disposal protocols affecting end-of-life device management, while ISO 14155 governs clinical investigation standards that underpin regulatory submissions across jurisdictions. Stakeholders must monitor evolving CMS reimbursement determinations for leadless systems versus conventional devices as cost-effectiveness data accumulates.
Market Dynamics
Cardiology clinics are displacing hospital catheterization labs as the primary implant venue, driven by ambulatory surgical center certifications and reimbursement realignment toward minimally invasive outpatient procedures. This structural shift is compressing traditional supply chains and forcing manufacturers to reconfigure distribution networks.
Growth Catalysts
- CMS reimbursement determination:The Centers for Medicare and Medicaid Services reimbursement structures in the United States favor minimally invasive cardiac procedures, accelerating leadless system adoption over transvenous alternatives.
- EU MDR conformity assessment:Streamlined CE marking pathways under the EU Medical Device Regulation are accelerating product introductions in Germany and other member states.
- Lithium-carbon monofluoride cell chemistry:Advances in battery technology are extending device service lives beyond twelve years, reducing replacement cycle frequency and total cost of ownership.
Market Restraints
- Device retrieval complexity:Leadless pacemakers lack extraction leads, complicating end-of-life removal and creating liability exposure for implanting physicians.
- Single-source component dependencies:Miniaturized pulse generator manufacturing concentrates among captive suppliers, creating supply vulnerability.
- EPA lithium battery disposal protocols:End-of-life device management requirements impose compliance costs and logistical constraints on healthcare facilities.
Strategic Opportunities
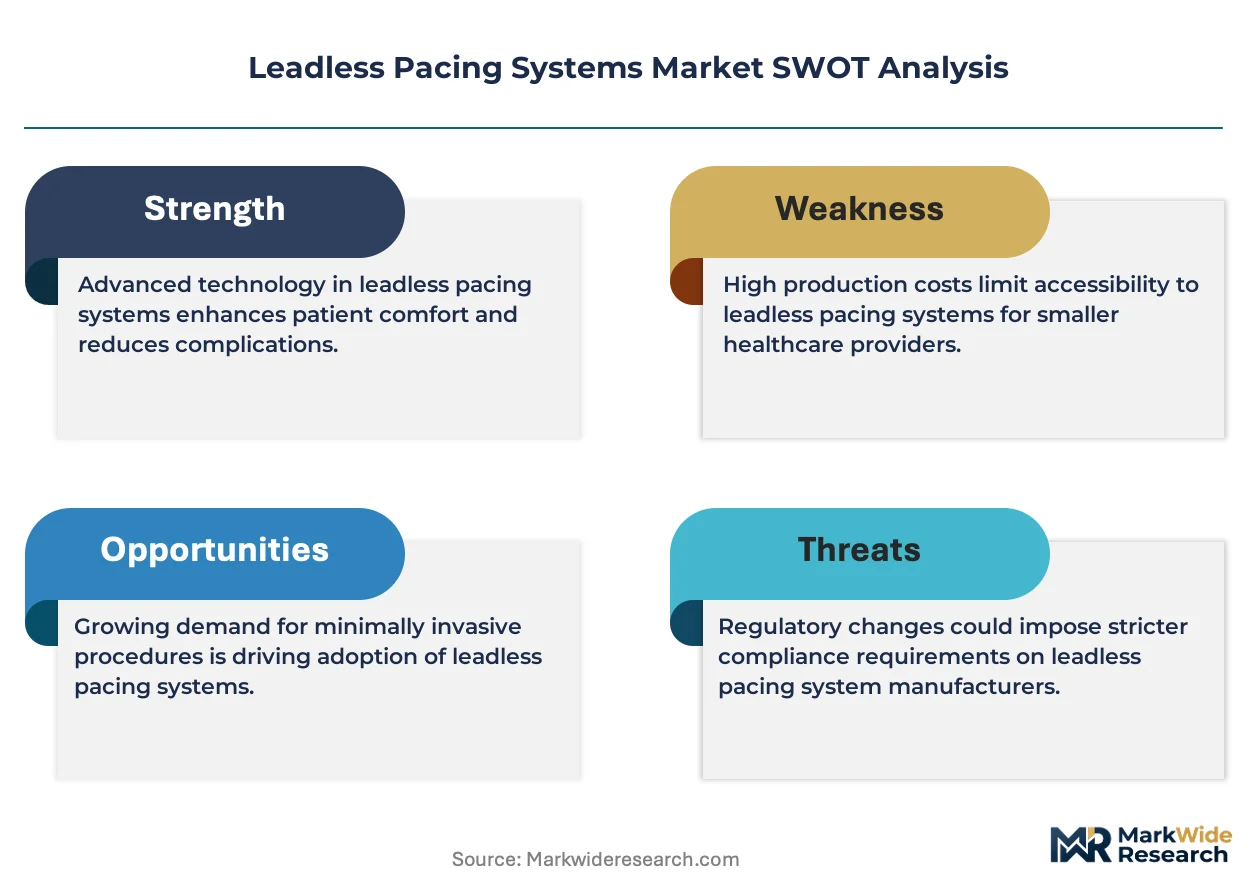
- Dual-chamber atrioventricular synchrony:Maturing two-chamber technology represents underpenetrated white space as current volumes concentrate in single-chamber devices.
- Ambulatory surgical center channel expansion:Outpatient clinic certifications are creating new margin pools outside traditional hospital procurement committees.
- ISO 14155 clinical investigation standards:Harmonized trial protocols enable simultaneous multi-jurisdiction regulatory submissions, compressing time-to-market.
Industry Challenges
- Physician training bandwidth:Catheter-based deployment techniques require specialized skills that outpace current fellowship program output.
- FDA premarket approval timelines:PMA pathway durations create capital lockup and competitive window risk for emerging dual-chamber platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leadless Pacing Systems Market |
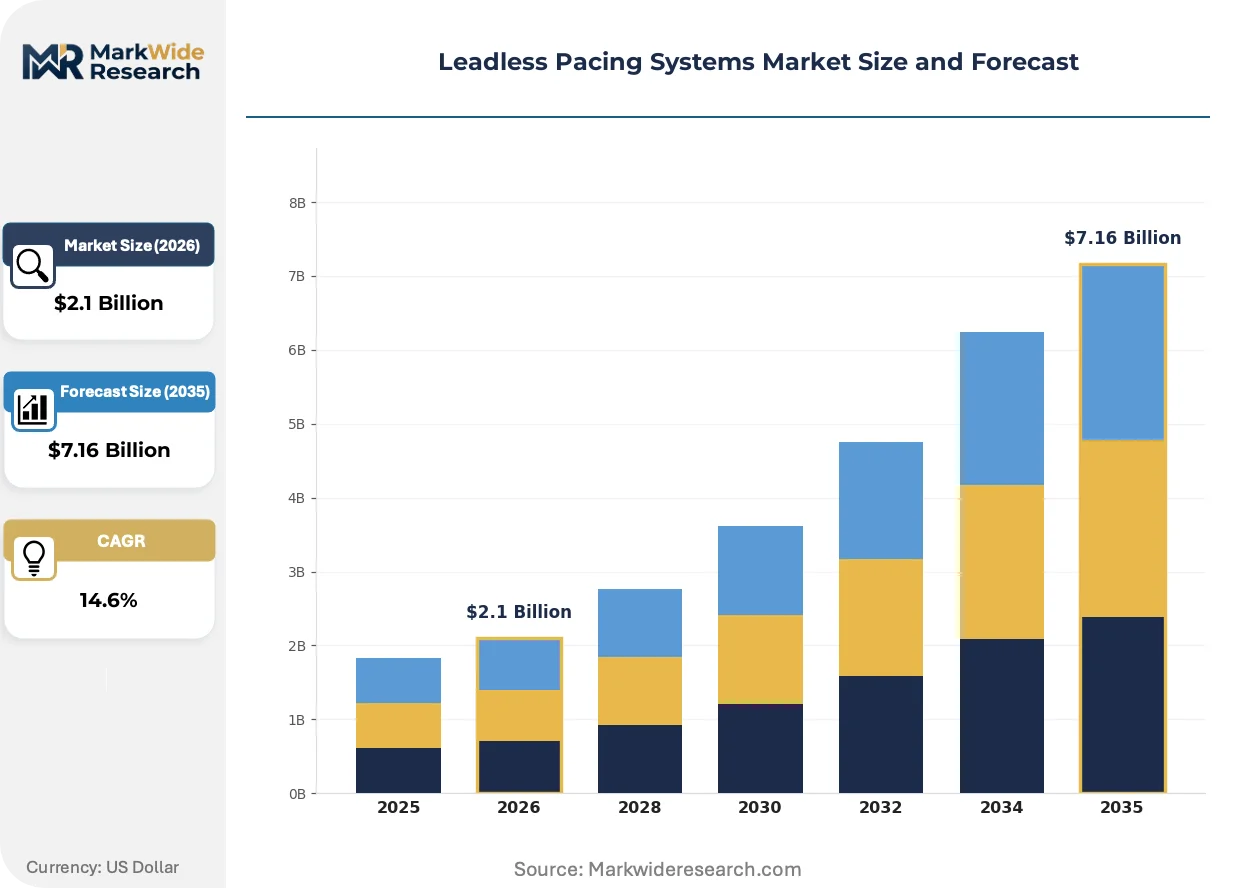
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Chamber, Dual-Chamber, CRT-D, Others End User: Hospitals, Cardiology Clinics, Specialty Centers, Research Institutes Technology: Wireless, Miniaturized, Leadless, Implantable Application: Arrhythmia Management, Heart Failure Treatment, Pacing Indications, Others |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, EBR Systems, Inc., Biotronik SE & Co. KG, MicroPort Scientific Corporation, Osypka Medical GmbH, Lepu Medical Technology, Shree Pacetronix Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leadless Pacing Systems Market Shifts & Advancements
Wireless communication architectures and miniaturization advances are redefining competitive differentiation in cardiac rhythm management. Three converging developments are reshaping product development priorities and go-to-market strategies.
Dual-chamber leadless platforms are fragmenting the historical single-chamber dominance as atrioventricular synchrony technology matures. Cardiology clinics in the United States are adopting these systems at accelerating pace as physician training broadens. This technology is fragmenting established reimbursement codes and forcing payers to develop new coverage determinations.
EU MDR conformity assessments are compressing product development timelines for manufacturers seeking European market access. The regulation's enhanced clinical evidence requirements are redirecting R&D spending toward post-market surveillance infrastructure. Dual-chamber systems face the steepest compliance burden given their novel synchronization algorithms.
Hospital procurement committees are losing implant volume share to specialized outpatient cardiology clinics. Ambulatory surgical center certifications are replacing traditional catheterization lab purchasing as the decisive buying center. This channel rotation is most visible in the United States, where reimbursement structures explicitly favor site-of-service migration.
Leadless Pacing Systems Market Segmentation
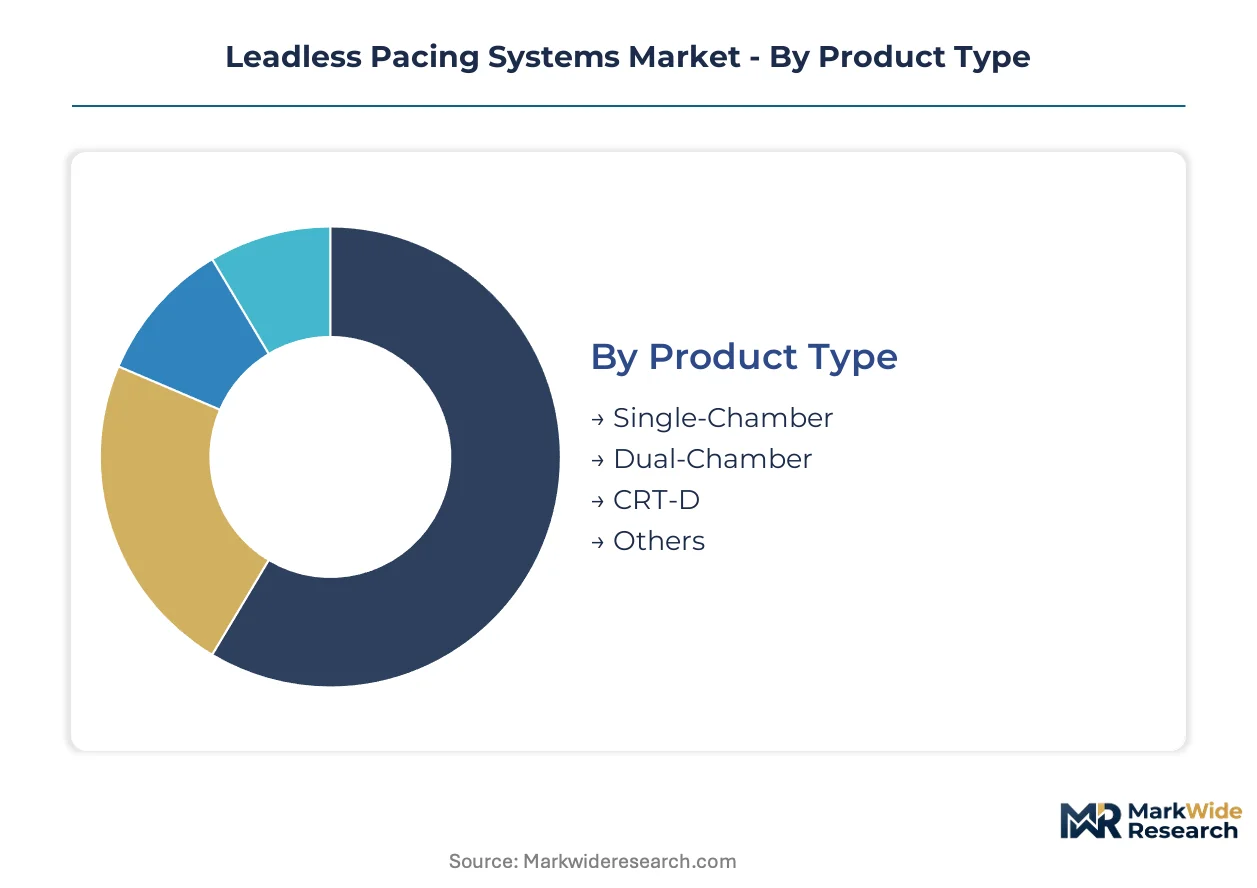
Segmentation in leadless pacing systems reveals how margin pools concentrate around procedural complexity and site-of-service economics. Manufacturers configure product portfolios and distribution networks differently across these dimensions.
Product Type:
Margin capture varies sharply by chamber complexity and synchronization capability.
- Single-Chamber:Miniaturized pulse generators deploy directly into the right ventricle via catheter-based techniques. Demand concentrates in United States cardiology clinics where CMS reimbursement favors established outpatient protocols and simpler deployment logistics.
- Dual-Chamber:Atrioventricular synchrony technology integrates separate right atrial and ventricular units with wireless communication. United States hospital systems are adopting these systems where physician training bandwidth supports complex catheter navigation and payers develop new coverage determinations.
- CRT-D:Cardiac resynchronization therapy defibrillator configurations combine pacing with shock delivery.
- Others:Emerging multi-site pacing architectures and investigational leadless platforms.
The dominant share belongs to Single-Chamber, while Dual-Chamber is expanding most quickly as atrioventricular synchrony technology matures.
End User:
Procurement authority is migrating from hospital committees to specialized outpatient venues.
- Hospitals:Traditional catheterization labs retain complex dual-chamber and CRT-D implant volumes where device retrieval capabilities and cardiac surgery backup address complication risk.
- Cardiology Clinics:Ambulatory surgical center certifications enable these sites to capture margin pools previously held by hospital procurement committees through streamlined single-chamber deployment.
- Specialty Centers:Electrophysiology-focused facilities concentrate high-volume physician operators and advanced imaging infrastructure.
- Research Institutes:Academic medical centers drive clinical investigation under ISO 14155 standards and FDA premarket approval pathways.
Cardiology clinics now lead volume growth, though hospitals maintain procedural complexity premiums.
Technology:
Competitive differentiation hinges on wireless architecture maturity and power management.
- Wireless:Radiofrequency or inductive communication protocols enable device-device synchronization and external programmer connectivity. United States manufacturers prioritize these architectures for dual-chamber platforms.
- Miniaturized:Pulse generator volumes below one cubic centimeter enable femoral venous delivery without surgical pocket creation. Cardiology clinics favor these specifications for outpatient efficiency.
- Leadless:Elimination of transvenous leads removes extraction risk and vascular access complications.
- Implantable:Self-contained units with lithium-carbon monofluoride cells exceeding twelve-year service lives.
Miniaturized platforms command the installed base, with wireless architectures gaining share fastest.
Application:
Clinical indication breadth determines addressable patient populations and reimbursement coding.
- Arrhythmia Management:Bradycardia and conduction disorder treatment represents the foundational indication with established CPT codes and broad physician familiarity.
- Heart Failure Treatment:CRT-D applications for ventricular dyssynchrony require more complex patient selection and device programming.
- Pacing Indications:Atrioventricular block and sinus node dysfunction drive single-chamber volume.
- Others:Investigational applications in hypertrophic cardiomyopathy and pediatric populations.
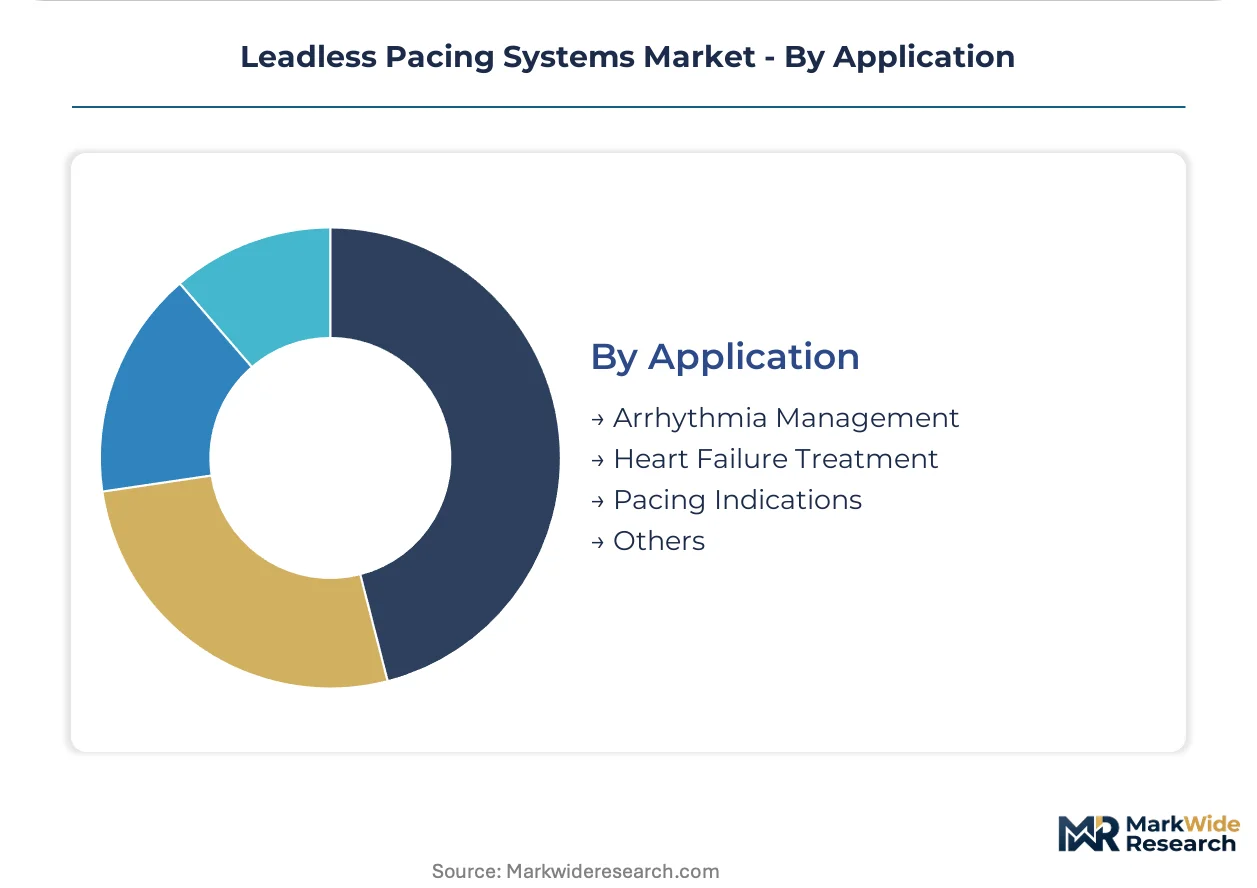
Arrhythmia management holds the dominant position, while heart failure treatment shows the steepest expansion trajectory as CRT-D technology advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States drive premium-tier volume, while cardiology clinics in Germany and ambulatory centers in Japan capture shifting margin pools through site-of-service migration.
United States
CMS reimbursement structures favor minimally invasive outpatient procedures, accelerating leadless system adoption over transvenous alternatives. The FDA premarket approval pathway shapes product development timelines for dual-chamber platforms. Minneapolis and Boston anchor manufacturer headquarters and clinical trial infrastructure.
Germany
EU MDR conformity assessments under streamlined CE marking pathways accelerate product introductions for cardiac rhythm devices. The country's national medical device regulator enforces enhanced clinical evidence requirements for novel synchronization algorithms. Berlin and Munich concentrate electrophysiology-focused specialty centers with advanced imaging infrastructure.
Japan
PMDA regulatory frameworks govern approval timelines for miniaturized pulse generators with lithium-carbon monofluoride cell chemistry. METI industrial policy supports domestic manufacturing of implantable cardiac devices. Tokyo and Osaka metropolitan areas host high-volume physician operators and academic medical centers driving clinical investigation.
China
NMPA approval pathways and GB standards for active implantable medical devices structure market access for foreign manufacturers. The country's dual carbon goals influence battery chemistry research and end-of-life device management protocols. Shanghai and Beijing clusters concentrate cardiology clinics adopting catheter-based deployment techniques.
Switzerland
Swissmedic regulatory frameworks align with EU MDR standards while maintaining distinct conformity assessment procedures for cardiac rhythm management devices. The country's precision manufacturing ecosystem supports miniaturized pulse generator component supply. Zurich and Basel anchor research institutes conducting ISO 14155-governed clinical trials.
Leadless Pacing Systems Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with captive cardiac rhythm management divisions. Consolidation around vertically integrated manufacturers with in-house miniaturization capabilities defines the competitive structure. Three archetypes dominate: diversified conglomerates with broad cardiovascular portfolios, specialized cardiac rhythm management pure-plays, and emerging Asia-Pacific challengers with cost-optimized manufacturing. Competitive moves center on dual-chamber technology licensing and ambulatory surgical center distribution partnerships.
Among diversified medical technology conglomerates, Medtronic plc and Abbott Laboratories exemplify scale-driven positioning through broad cardiovascular device portfolios. Boston Scientific Corporation occupies a specialist position within the cardiac rhythm management tier. These three entities anchor the premium-product vector through established regulatory submission capabilities and multi-jurisdiction commercialization infrastructure.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| EBR Systems, Inc. |
| Biotronik SE & Co. KG |
| MicroPort Scientific Corporation |
| Osypka Medical GmbH |
| Lepu Medical Technology |
| Shree Pacetronix Ltd. |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for lithium-carbon monofluoride cells concentrate pricing power with captive manufacturers of miniaturized pulse generators, compressing margins for downstream distributors while amplifying procurement leverage for hospital systems negotiating dual-chamber platform contracts.
Pricing Analysis
Single-chamber versus dual-chamber versus next-generation CRT-D configurations stratify across premium, standard, and economy tiers, with FDA PMA tier certification and wireless protocol maturity driving price differentiation. Pricing pressure stems from cardiology clinic procurement committees consolidating volumes under GPO frameworks. Hospital catheterization labs exhibit lowest price sensitivity due to complication-risk premiums, while ambulatory surgical centers negotiate aggressively on single-chamber devices.
Supply Chain Analysis
Strategic stockpiling of miniaturized semiconductor components and battery cells dominates inventory strategy over just-in-time approaches given FDA premarket approval timeline uncertainties. Manufacturing concentrates in the United States, Switzerland, and Germany for pulse generator assembly, drawing from Taiwanese wafer foundries and Japanese precision component suppliers. Single-source dependencies on lithium-cell chemistry create vulnerability to EPA disposal protocol changes. Distribution runs through manufacturer-direct hospital contracting and specialized cardiology clinic distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leadless pacing systems markets recover cyclically as CMS reimbursement determinations for outpatient cardiac procedures reset every three to five years, creating predictable windows for volume expansion.
For Market Incumbents: Fortify dual-chamber technology moats through captive manufacturing of wireless synchronization chipsets, blocking emerging entrants from matching atrioventricular timing precision. Secure ambulatory surgical center distribution partnerships before GPO consolidation locks out independent clinic access. Vertical integration into lithium-carbon monofluoride cell production mitigates EPA disposal cost pass-through.
For New Entrants and Emerging Players: Post-implant remote monitoring service gaps where incumbents under-serve create attach-rate opportunities for software-native competitors. Target Japan's PMDA approval pathway for miniaturized single-chamber devices, where domestic manufacturing incentives reduce effective regulatory burden. Lead with cardiac resynchronization therapy defibrillator configurations in hospital systems retaining surgery-backup capabilities.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dual-chamber R&D intensity and FDA premarket approval capital requirements exceed standalone venture scale. Acquisition candidates cluster around wireless communication protocol specialists and ISO 14155 clinical investigation service providers. Watch CMS national coverage determinations for leadless versus transvenous systems as the volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA submissions for dual-chamber platforms lock up capital for eighteen to thirty-six months, deterring underfunded competitors. |
| CE Marking Pathway | EU MDR conformity assessments accelerate German market access while redirecting R&D toward post-market surveillance infrastructure. |
| Hospital System Partnership | Contracting directly with catheterization labs preserves procedural complexity premiums for CRT-D and retrieval-capable implants. |
| Software Companion Development | Remote monitoring applications capture recurring revenue streams and defend against pure-play digital health entrants. |
| Reimbursement Strategy | CMS coverage determination lobbying shapes site-of-service economics favoring cardiology clinic migration. |
Research Methodology
Desk research of FDA PMA filings, EU MDR technical documentation, and CMS national coverage determinations preceded structured interviews with electrophysiologists, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers specializing in cardiac rhythm devices. Secondary validation drew from ISO 14155 clinical trial registries, EPA lithium battery disposal enforcement records, and manufacturer SEC disclosures. Bottom-up implant volume estimates triangulated against top-down addressable bradycardia patient population models.
Variance decomposition across product type, end-user channel, technology architecture, and application indication structured the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical transvenous pacemaker substitution patterns, adjusted for physician training bandwidth constraints and reimbursement cycle timing. Modeled inputs included ambulatory surgical center certification trajectories and lithium-cell chemistry longevity improvements.
Forecasts assume regulatory continuity in FDA premarket approval and EU MDR conformity assessment regimes; material policy shifts would require re-modeling. Revision becomes warranted when CMS reimbursement determination timelines for leadless systems deviate from historical precedent by more than twelve months.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Carotid Stents Market
Medical Devices
Electromagnetic Navigation Bronchoscopy Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Pen Injectors Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
3D Printed Implants Market
Medical Devices
Snare Devices Market
Medical Devices
Syringeless Injector Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Liposuction Devices Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Robotic Catheterization Systems Market