

Otoacoustic Emissions Hearing Screener Market Size, Share, and Industry Trends Forecast 2026-2036
Otoacoustic Emissions Hearing Screener Market Insights
Silicon-based microelectromechanical microphones are consolidating as the dominant acoustic sensor in next-generation otoacoustic emissions hearing screener hardware, displacing traditional ceramic transducers and reducing per-unit material costs by enabling wafer-scale fabrication. Grason-Stadler leverages its long-standing calibration infrastructure to sustain precision advantages in clinical-grade systems. MAICO Diagnostics anchors its position through dedicated pediatric audiology specialization across European and North American distribution channels. Natus competes by extending its neonatal care ecosystem into integrated screening workflows.
An otoacoustic emissions hearing screener is a diagnostic instrument that detects sound waves generated by the cochlea's outer hair cells in response to acoustic stimuli, typically operating across frequency ranges of 500 Hz to 8 kHz with stimulus levels between 40 and 75 dB SPL to identify sensorineural hearing loss. Its primary purpose is to enable non-invasive, objective hearing assessment in populations unable to participate in behavioral audiometry, particularly neonates and infants. Distortion product otoacoustic emissions equipment dominates hospital procurement due to established clinical validation and reimbursement alignment, while transient evoked systems represent the fastest-growing deployment category as portable platforms penetrate school and occupational health settings. Handheld screeners occupy emerging margin pools where battery-optimized designs and Bluetooth connectivity reduce total cost of ownership for mobile screening programs.
FDA 510(k) clearance requirements and IEC 60601-1-10 electromagnetic compatibility standards shape device development timelines and testing expenditures for manufacturers seeking U.S. market access. The Joint Commission's ambulatory care accreditation criteria and state-level Early Hearing Detection and Intervention mandates collectively determine institutional purchasing priorities and replacement cycles. Stakeholders must monitor evolving FDA guidance on artificial-intelligence-enabled diagnostic algorithms, as machine-learning-based otoacoustic emissions classification may trigger de novo regulatory pathways distinct from traditional predicate-device routes.
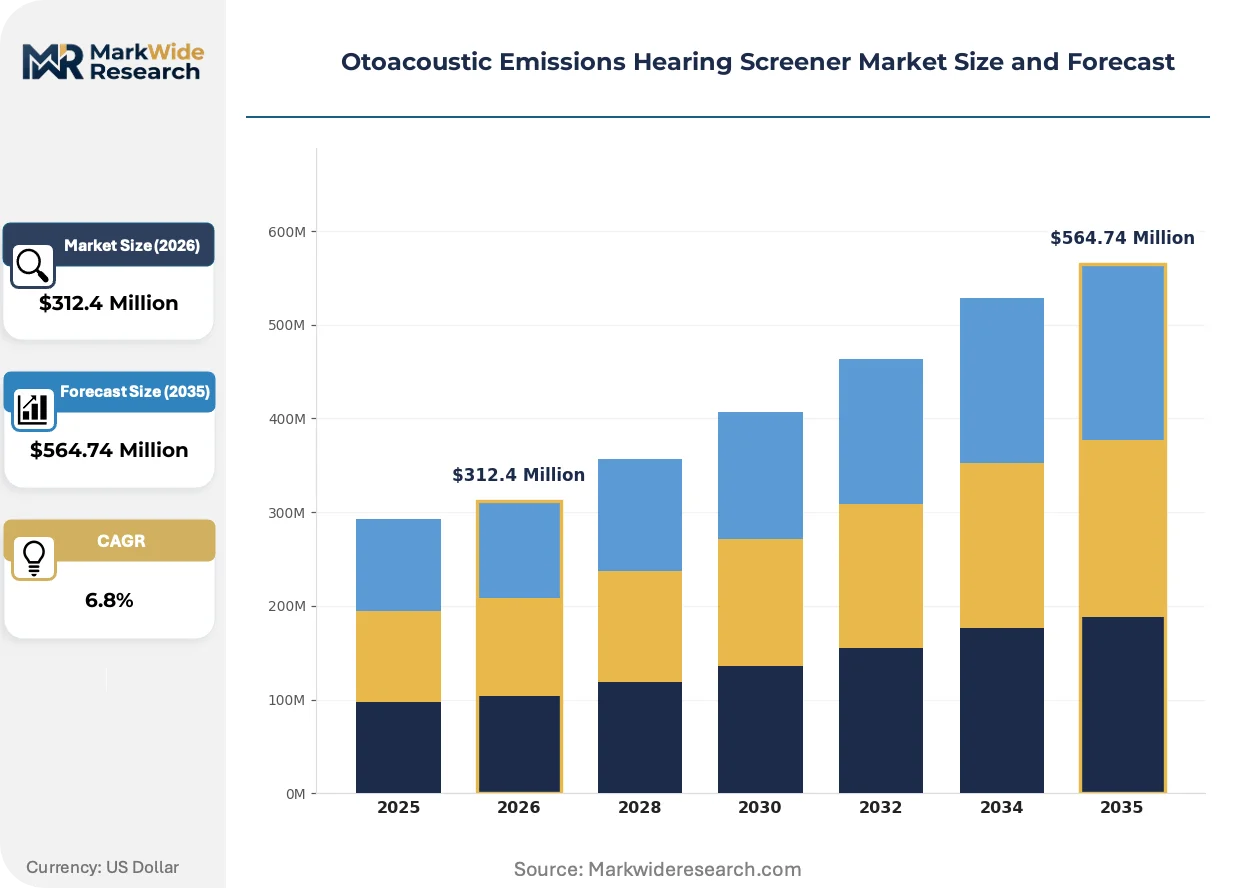
Market Dynamics
Universal newborn hearing screening mandates are compressing replacement cycles and forcing manufacturers to redesign hardware for seamless electronic health record integration, fundamentally altering how procurement committees evaluate total cost of ownership.
Growth Catalysts
- State-level EHDI mandates:Early Hearing Detection and Intervention programs in the United States create guaranteed procurement pipelines for hospital networks and birthing centers, locking in replacement demand regardless of budget cycles.
- Silicon MEMS microphone adoption:Wafer-scale fabrication of acoustic sensors is reducing per-unit material costs while improving frequency response consistency across production batches.
- Pediatric audiology specialization:Hospital departments are consolidating hearing screening into dedicated neonatal care workflows, expanding equipment utilization rates and justifying capital expenditure approvals.
Market Restraints
- IEC 60601-1-10 electromagnetic compliance:Updated standards for medical electrical equipment are extending testing timelines and increasing certification expenditures for manufacturers targeting hospital procurement.
- Transducer supply concentration:Precision acoustic sensor fabrication remains concentrated among a limited set of specialized semiconductor foundries, creating input bottleneck risks.
- Behavioral audiometry substitution:Conventional pure-tone testing retains reimbursement advantages for populations capable of voluntary response, limiting addressable market expansion in adult segments.
Strategic Opportunities
- Occupational health screening expansion:Manufacturing and aviation sectors in Germany are adopting portable otoacoustic emissions platforms for regulatory compliance hearing conservation programs.
- School-based deployment:District-level pediatric screening programs in Japan represent an underpenetrated channel where battery-optimized handheld designs reduce total cost of ownership.
- FDA AI guidance alignment:Machine-learning-enabled otoacoustic emissions classification algorithms may unlock de novo regulatory pathways distinct from traditional predicate-device routes, creating first-mover advantages.
Industry Challenges
- Calibration technician scarcity:Clinical-grade systems require specialized personnel for probe assembly verification and acoustic coupler validation, constraining field service scalability.
- Legacy EHR integration complexity:Hospital information systems built on disparate HL7 standards demand customized middleware development, extending implementation timelines and inflating professional services costs.
- Patent thickets in signal processing:Noise-rejection algorithms and stimulus artifact suppression techniques are encumbered by overlapping intellectual property claims, complicating product development freedom-to-operate analyses.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Otoacoustic Emissions Hearing Screener Market Trends and Innovations
Hardware architectures are fragmenting into specialized configurations optimized for distinct care settings, while regulatory frameworks accelerate the incorporation of automated diagnostic algorithms into clinical workflows.
Silicon-based microelectromechanical systems are modularizing otoacoustic emissions screener hardware platforms. These sensors replace ceramic transducers in next-generation devices, enabling manufacturers to source components through standard semiconductor supply chains rather than specialized acoustic component vendors. Pediatric audiology departments in hospital networks are adopting these redesigned systems most aggressively, as procurement committees prioritize equipment standardization across distributed care sites.
FDA premarket notification pathways for artificial-intelligence-enabled diagnostic algorithms are tightening performance thresholds for device clearance. Updated guidance documents require expanded clinical validation datasets and algorithm transparency documentation, extending development timelines for manufacturers pursuing 510(k) submissions. Distortion product otoacoustic emissions equipment faces the most significant compliance burden, as these systems represent the dominant configuration in hospital procurement and thus attract heightened regulatory scrutiny.
Academic medical centers and regional hospital networks are consolidating hearing screening equipment purchasing into centralized procurement functions, displacing department-level decision-making. Group purchasing organizations and shared service alliances are capturing negotiating leverage through volume aggregation, compressing price realization for manufacturers. This concentration is most visible in the United States, where state-level early hearing detection mandates create predictable replacement demand that procurement coalitions exploit in multi-year contract negotiations.
Otoacoustic Emissions Hearing Screener Market Segmentation
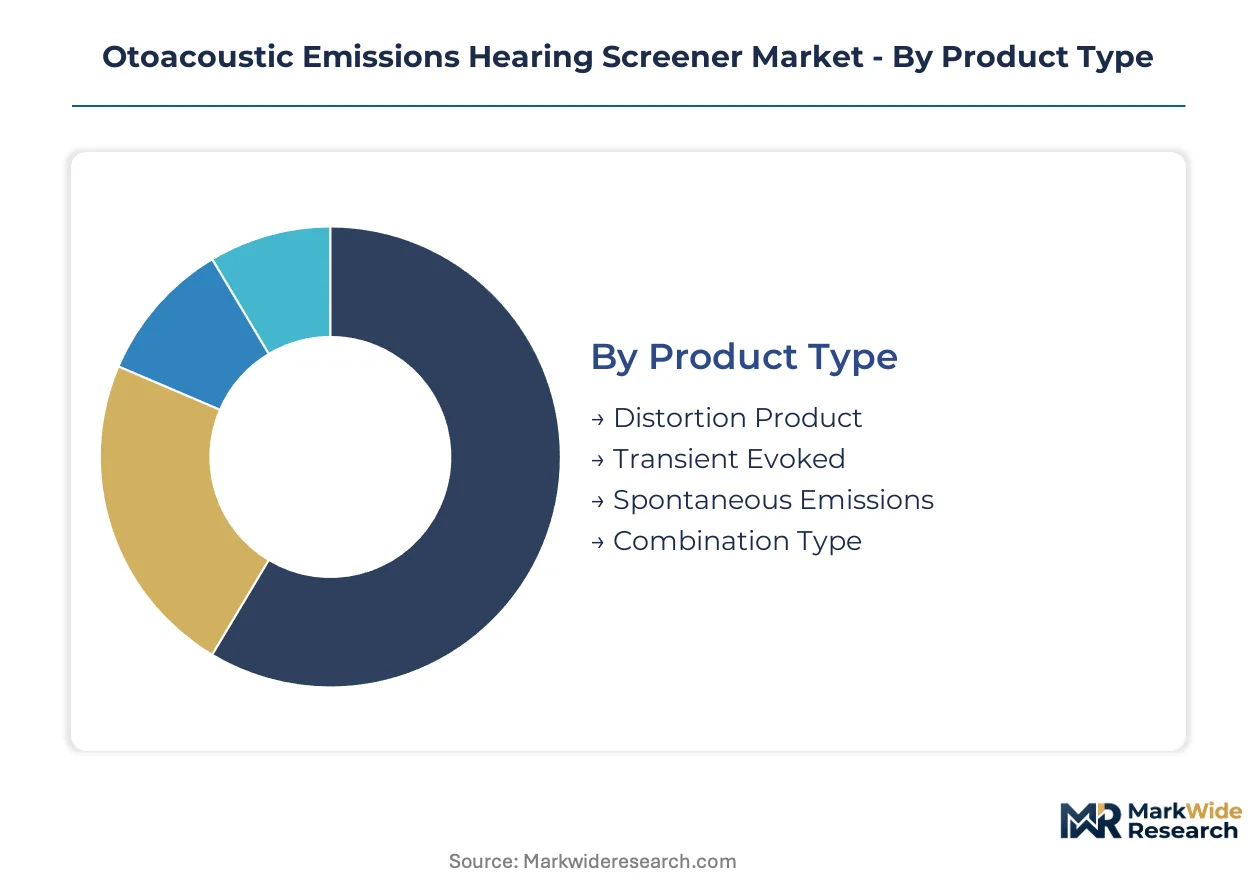
Hardware configurations and deployment settings fragment the otoacoustic emissions hearing screener market into distinct procurement channels. Each segment carries unique technical specifications, regulatory burdens, and total cost of ownership calculations that reshape manufacturer competitive positioning.
Product Type:
Clinical validation depth and reimbursement alignment separate buyers across emission detection methodologies.
- Distortion Product:Two-tone stimulus protocols generate measurable intermodulation distortion at specific frequency ratios, enabling precise cochlear mapping across the standard audiometric range. Hospital networks in the United States prioritize these systems for universal newborn hearing screening programs due to established FDA 510(k) predicate pathways and Medicaid reimbursement codes.
- Transient Evoked:Broadband click stimuli provoke outer hair cell responses detectable within 20 milliseconds of stimulus onset, supporting rapid pass-refer decisions in high-throughput environments. School districts and occupational health programs in Germany are expanding procurement of these platforms for regulatory compliance hearing conservation.
- Spontaneous Emissions:Passive acoustic monitoring without external stimulus application serves research validation and quality assurance functions.
- Combination Type:Modular architectures integrate multiple emission protocols within single hardware platforms.
Distortion product equipment leads volumes today; transient evoked systems are gaining share fastest.
Application:
Regulatory mandate intensity and screening frequency determine addressable market depth across patient populations.
- Newborn Screening:State-level Early Hearing Detection and Intervention mandates in the United States create guaranteed replacement demand regardless of hospital budget cycles, with birthing centers requiring equipment validation every 24-36 months.
- Occupational Health:Manufacturing and aviation sectors in Germany face regulatory hearing conservation requirements under national occupational safety frameworks, driving portable platform adoption for periodic workforce assessment.
- School Screening:District-level pediatric programs in Japan represent emerging demand channels where battery-optimized designs reduce total cost of ownership.
- Geriatric Screening:Long-term care facilities and primary care networks deploy simplified protocols for age-related hearing loss detection.
- Military Readiness:Defense medical commands require ruggedized field-deployable systems for pre-deployment baseline assessment.
Newborn screening dominates revenue today; occupational health is climbing fastest.
End User:
Technical sophistication requirements and capital expenditure approval thresholds differentiate institutional buyers.
- ENT Clinics:Otolaryngology practices integrate otoacoustic emissions screening into comprehensive diagnostic workflows, requiring HL7-compatible electronic health record connectivity and specialized probe calibration infrastructure.
- Audiology Centers:Dedicated hearing healthcare facilities prioritize multi-protocol flexibility and automated reporting functions to maximize patient throughput.
- Research Institutes:Academic medical centers demand extended frequency range capabilities and raw data export functions for protocol development.
- Speech Therapy Clinics:Rehabilitation-focused practices emphasize simplified operation and pediatric-appropriate interface design.
Audiology centers lead procurement volume today; ENT clinics are expanding fastest.
Deployment Mode:
Mobility requirements and power infrastructure availability reshape hardware architecture decisions.
- Portable Devices:Battery-operated platforms with integrated probe assemblies enable screening outside traditional clinical environments, with procurement concentrated in school districts and occupational health programs.
- Stationary Units:Mains-powered systems with dedicated acoustic isolation deliver maximum signal-to-noise ratios for research-grade validation.
- Mobile Screening Vans:Vehicle-integrated configurations serve rural healthcare access programs and military field operations.
- Handheld Screeners:Smartphone-connected probe systems reduce per-unit hardware costs for large-scale public health initiatives.
- Remote Monitoring:Telehealth-integrated platforms enable specialist oversight of screening operations at distributed sites.
Stationary units anchor hospital procurement today; handheld screeners are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric audiology departments in hospital networks across the United States anchor procurement volume for otoacoustic emissions hearing screener equipment, with state-level universal newborn hearing screening mandates creating predictable replacement demand that manufacturers prioritize in regional distribution strategies.
United States
State-level Early Hearing Detection and Intervention programs guarantee equipment procurement from birthing centers regardless of budget cycles, with FDA 510(k) clearance requirements shaping device development timelines for manufacturers seeking market access. The Joint Commission's ambulatory care accreditation criteria determine institutional purchasing priorities. Texas and California hospital networks concentrate replacement demand through centralized procurement functions.
Germany
Manufacturing and aviation sectors adopt portable otoacoustic emissions platforms for regulatory compliance hearing conservation programs under national occupational safety frameworks. IEC 60601-1-10 electromagnetic compatibility standards extend testing timelines for manufacturers targeting hospital procurement. The Bavaria industrial corridor drives occupational health screening expansion among precision manufacturing employers.
Japan
District-level pediatric screening programs represent underpenetrated channels where battery-optimized handheld designs reduce total cost of ownership for school-based deployment. METI standards influence device certification requirements for medical electrical equipment. The Kanto region around Tokyo concentrates audiology center procurement volume through consolidated healthcare purchasing alliances.
United Kingdom
NHS England newborn hearing screening program mandates create institutional procurement pipelines for hospital trusts, with HL7-compatible electronic health record connectivity requirements reshaping hardware architecture decisions. MHRA regulations align with updated MDR performance thresholds for device clearance. The Greater London hospital network anchors replacement cycle compression through standardized equipment specifications.
China
Provincial maternal and child health hospitals expand universal newborn hearing screening coverage under national health reform initiatives, with NMPA medical device registration requirements extending market entry timelines for foreign manufacturers. The Yangtze River Delta region concentrates pediatric audiology department formation in Shanghai and Jiangsu province hospital networks.
Otoacoustic Emissions Hearing Screener Market Competitive Landscape
Global majors compete with regional champions across calibration infrastructure and pediatric specialization dimensions, with market structure consolidating around established clinical-grade system providers and emerging portable platform specialists. Three strategic archetypes dominate: precision calibration heritage players, neonatal care ecosystem integrators, and semiconductor-enabled handheld innovators. Competitive moves concentrate on strategic partnerships for EHR integration middleware and geographic expansion through dedicated pediatric audiology distribution channels.
Within the precision calibration tier, Grason-Stadler and MAICO Diagnostics exemplify archetypes built on long-standing measurement infrastructure and dedicated pediatric specialization respectively. Natus occupies a position as a neonatal care ecosystem integrator extending screening workflows. These three entities anchor competitive positioning across North American and European procurement channels where hospital network consolidation favors established clinical validation histories.
| Leading Market Players |
|---|
| Grason-Stadler |
| MAICO Diagnostics |
| Natus |
| RION |
| E3 Diagnostics |
| Interacoustics |
| Baxter |
| Neurosoft |
| Otodynamics |
| Others |
Pricing and Supply Chain Analysis
Clinical-grade FDA 510(k) cleared systems versus handheld screening platforms diverge sharply in component sourcing and pricing power, with the former drawing from specialized acoustic sensor foundries and the latter leveraging standard semiconductor supply chains. This bifurcation concentrates margin capture among calibration-heritage manufacturers while compressing prices in the portable tier where MEMS microphone commoditization accelerates.
Pricing Analysis
Silicon MEMS microphone costs pass through directly to handheld screener price points, while clinical-grade systems maintain premium positioning through proprietary probe calibration infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hospital systems from CE-marked clinic units and unregulated screening accessories. Pricing pressure stems from group purchasing organization volume aggregation in United States hospital networks. Birthing centers and school districts exhibit highest price sensitivity; research institutes and military medical commands demonstrate lowest.
Supply Chain Analysis
Direct-to-hospital channels handle clinical-grade system demand while distributor networks serve clinic and school procurement. Precision acoustic sensor fabrication concentrates in Germany, Japan, and the United States. MEMS microphone supply draws from Taiwan and South Korea semiconductor foundries; probe assembly components source from Switzerland and the United States. Single-source vulnerability in specialized transducer supply creates bottleneck exposure. Distribution runs through dedicated medical device distributors with audiology specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on MEMS microphone cost-down curves and the shift toward premium-tier AI-enabled diagnostic algorithms that command higher price realization.
For Market Incumbents: Deepen vertical integration into probe calibration infrastructure to defend against semiconductor-enabled entrants. Acquire specialized acoustic sensor fabrication capacity in Germany or Switzerland to secure input supply. Invest in FDA de novo pathway preparation for machine-learning classification algorithms before predicate-device routes saturate. For New Entrants and Emerging Players: Launch via direct-to-school district distribution models in Japan where battery-optimized designs face minimal incumbent saturation. Target occupational health programs in Germany's manufacturing corridor with portable transient evoked platforms. Pursue CE marking pathways as faster market entry before FDA 510(k) submission. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration technician scarcity constrains field service scalability for mid-tier manufacturers. Five-to-ten year viability favors entities with established pediatric audiology distribution and AI algorithm development capabilities. Monitor FDA guidance publication timing on machine-learning diagnostic algorithms as acquisition timing signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Pathway Preparation | AI-enabled otoacoustic emissions classification algorithms unlock premium pricing distinct from predicate-device competition. |
| MEMS Microphone Supply Agreement | Long-term foundry contracts in Taiwan secure component cost advantages for portable platform scaling. |
| Hospital System Partnership | Integrated EHR connectivity with Texas and California networks locks in replacement cycle revenue visibility. |
| Occupational Health Channel Expansion | German manufacturing sector regulatory compliance mandates create predictable procurement pipeline outside clinical settings. |
| Calibration Infrastructure Acquisition | Specialized probe assembly verification capabilities defend margin position against semiconductor-commoditized entrants. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and China, with primary inputs from each market cluster. The approach combines interviews with pediatric audiologists, hospital procurement managers, biomedical engineers, and GPO contracts specialists with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and IEC standards documentation. Bottom-up equipment unit analysis and top-down healthcare expenditure triangulation anchor volume estimation.
Rate-of-change decomposition separates newborn screening mandate expansion, MEMS cost curves, and regulatory pathway evolution as independent forecast drivers across the projection horizon. Segmentation dimensions modeled include emission detection methodology, deployment mode, end-user technical sophistication, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to mandate implementation timelines and equipment replacement cycle data. Industry-specific inputs incorporate state-level EHDI program budget allocations and semiconductor foundry capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA AI guidance delays or transducer supply disruptions. Projections reflect assumptions regarding mandate expansion continuity, MEMS microphone yield improvements, and reimbursement code stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.