
 Temporary Cardiac Pacing Wires and Leads Market | 2026-2036
Temporary Cardiac Pacing Wires and Leads Market Size, Share, and Industry Trends Forecast 2026-2036
Temporary Cardiac Pacing Wires and Leads Market Analytics
Modular pacing wire kits that bundle electrodes with introducer tools and monitoring adapters is rebalancing hospital procurement toward single-source contracts. Medtronic leverages its integrated cardiovascular portfolio to sustain catheter lab loyalty across North American health systems. Merit Medical Systems Inc. anchors its position through specialized access device manufacturing that complements pacing wire deployment. B. Braun SE competes in European surgical centers with differentiated sterile packaging configurations that reduce operating room setup time.
Temporary cardiac pacing wires and leads are conductive electrodes, typically fabricated from stainless steel or platinum-iridium alloys with silicone or polyurethane insulation, designed to deliver electrical impulses to the myocardium during transient rhythm disturbances following surgery or acute cardiac events. Epicardial leads dominate surgical applications due to direct myocardial attachment capability, while endocardial leads are gaining traction in electrophysiology labs seeking minimally invasive transvenous access. Bipolar pacing wires command premium positioning in postoperative care settings where electromagnetic interference rejection proves clinically critical, and unipolar configurations occupy cost-sensitive emergency medicine deployments where rapid deployment supersedes signal fidelity requirements.
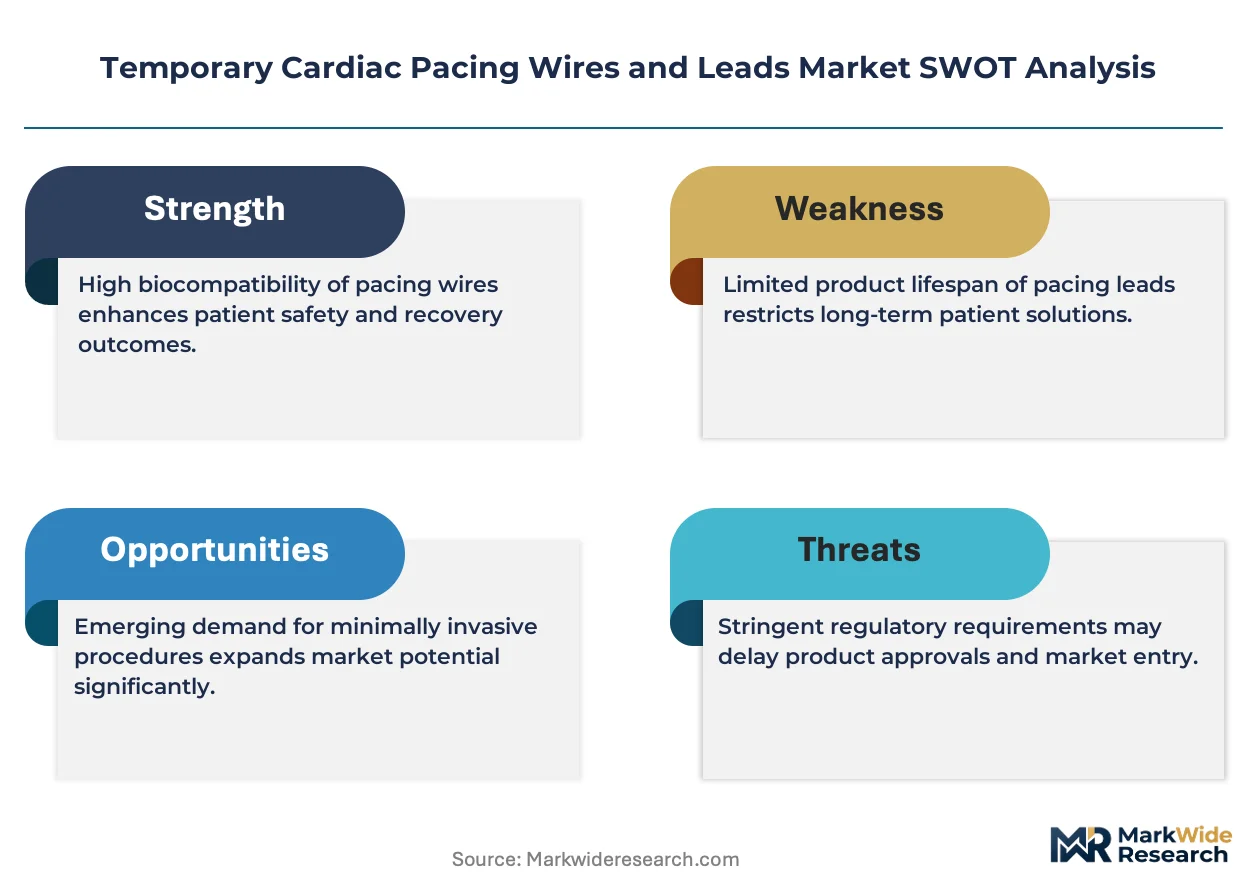
FDA 510(k) clearance pathways and EU MDR Class III device regulations govern temporary pacing wire biocompatibility, electrical safety, and sterilization validation, with ISO 10993 material testing standards increasingly shaping supplier qualification timelines. The EU AI Act and FDA Software as a Medical Device frameworks are beginning to influence smart pacing systems that integrate automated rhythm detection algorithms. Stakeholders must monitor how evolving digital health regulations will reshape temporary pacing wire classification and reimbursement pathways.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while demanding bundled sterile kits that integrate pacing wires with introducers and monitoring adapters, forcing manufacturers to reconfigure product architectures around single-source contract economics.
Growth Catalysts
- EU MDR Class III certification:Tighter biocompatibility validation for silicone insulation is accelerating supplier qualification timelines and locking in incumbent relationships with established testing documentation.
- Electrophysiology lab expansion:Minimally invasive transvenous access protocols are displacing open-chest procedures in postoperative cardiac recovery, expanding addressable procedure volumes.
- Japan's aging surgical population:Complex cardiac surgery volumes in Tokyo and Osaka medical centers are sustaining demand for epicardial lead configurations with direct myocardial attachment capability.
Market Restraints
- Platinum-iridium alloy cost volatility:Precious metal input fluctuations compress gross margins on premium bipolar configurations without corresponding pricing elasticity in tender-based hospital procurement.
- Supply concentration in German polymer processors:Specialized medical-grade polyurethane insulation depends on a narrow base of certified compounders, creating single-source vulnerability.
- ISO 10993 testing backlog:Extended biocompatibility validation timelines delay new product introductions by 18-24 months, freezing competitive repositioning.
Strategic Opportunities
- Underpenetrated Indian cardiac centers:Tier-2 and Tier-3 hospital infrastructure expansion under CDSCO medical device rules creates first-mover positioning for standardized unipolar emergency configurations.
- Smart pacing algorithm integration:Convergence of temporary pacing hardware with automated rhythm detection software is automating postoperative monitoring workflows and creating recurring revenue attachments.
- Direct-to-hospital digital procurement:Specialized cardiovascular distributors in Germany are piloting consignment inventory models that reduce operating room stockout risk and accelerate replenishment cycles.
Industry Challenges
- Electrophysiologist training pipeline:Specialized transvenous lead placement skills require fellowship-level credentialing that outpaces graduating specialist supply in United States academic medical centers.
- Legacy sterilization validation:Ethylene oxide process documentation gaps in older manufacturing facilities force costly facility requalification under revised FDA environmental compliance mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temporary Cardiac Pacing Wires and Leads Market |
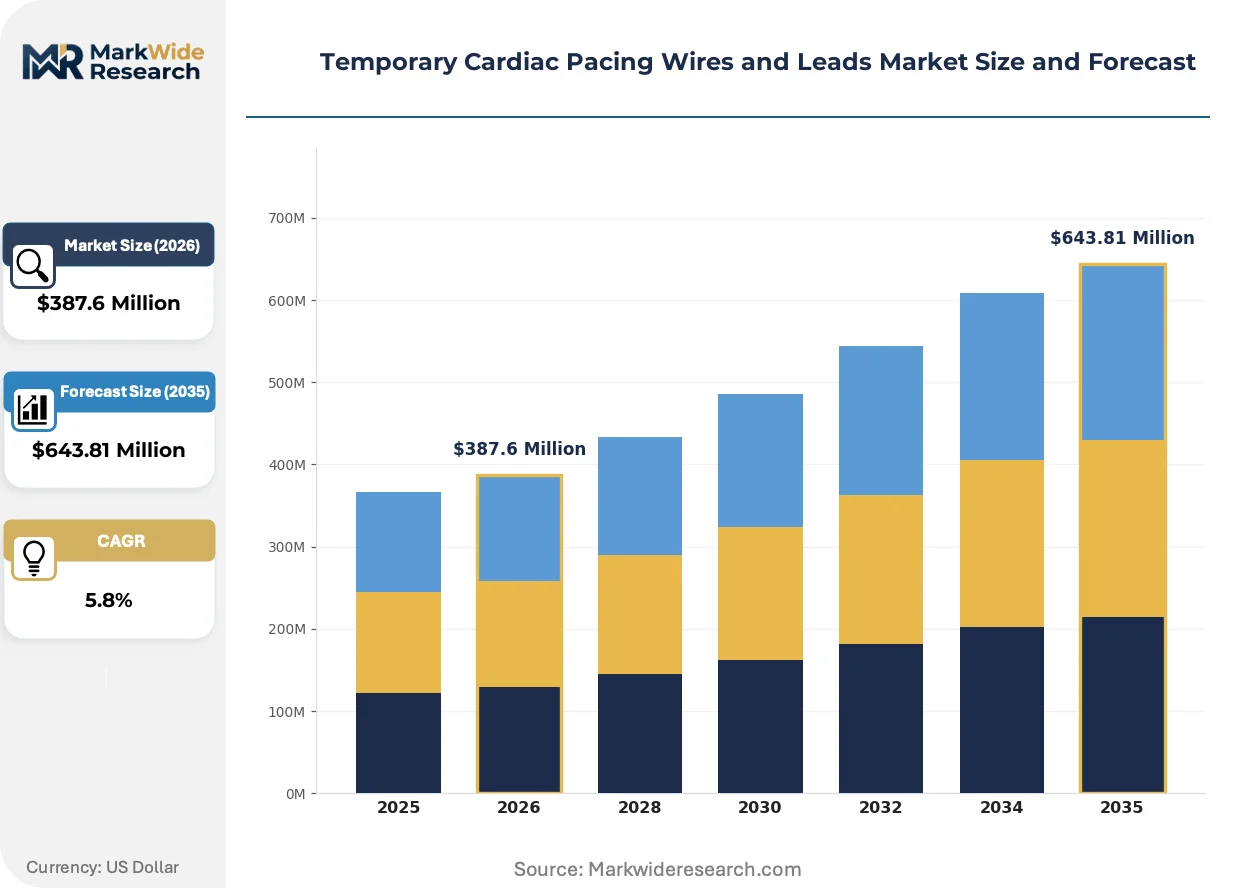
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epicardial Leads, Endocardial Leads, Bipolar Pacing Wires, Unipolar Pacing Wires Application: Cardiac Surgery, Emergency Medicine, Electrophysiology, Postoperative Care End User: Hospitals, Cardiac Clinics, Surgical Centers, Research Institutions Material: Silicone, Polyurethane, Stainless Steel, Plastic, Others |
| Companies Covered | Medtronic, Merit Medical Systems Inc., BD, B. Braun SE, Abbott, Edwards Lifesciences Corporation, Teleflex Incorporated, Oscor Inc., OSYPKA MEDICAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temporary Cardiac Pacing Wires and Leads Market Evolving Landscape
Digital health integration is redefining temporary pacing from passive conductive hardware to active monitoring nodes, with algorithm-enabled devices capturing real estate in postoperative telemetry workflows previously served by standalone monitors.
Automated rhythm detection embedded in temporary pacing leads is automating threshold surveillance and capture verification that previously required manual electrophysiologist interpretation. Academic medical centers in the United States are piloting these systems in cardiac surgery recovery units to reduce nursing workload and accelerate weaning protocols. The technology is automating clinical decision support that historically depended on intermittent manual checks, compressing the window between rhythm deterioration and intervention.
EU MDR biocompatibility surveillance requirements are extending post-market clinical follow-up obligations to temporary pacing wire manufacturers, mandating systematic collection of adverse event data across implantation sites. German and French notified bodies are enforcing stricter vigilance reporting timelines than predecessor directives, elevating documentation costs for multi-national suppliers. Class III device reclassification is forcing smaller manufacturers to consolidate regulatory affairs functions or exit European markets entirely.
Hospital value analysis committees are consolidating temporary pacing wire purchasing into cardiovascular service line bundles that span catheters, introducers, and monitoring accessories. United States integrated delivery networks are displacing specialty distributor relationships with direct manufacturer contracts that include consignment inventory and usage analytics. This concentration is most visible in Midwestern health systems where cardiac surgery volume justifies dedicated supply chain personnel negotiating multi-year sole-source agreements.
Temporary Cardiac Pacing Wires and Leads Market Segmentation
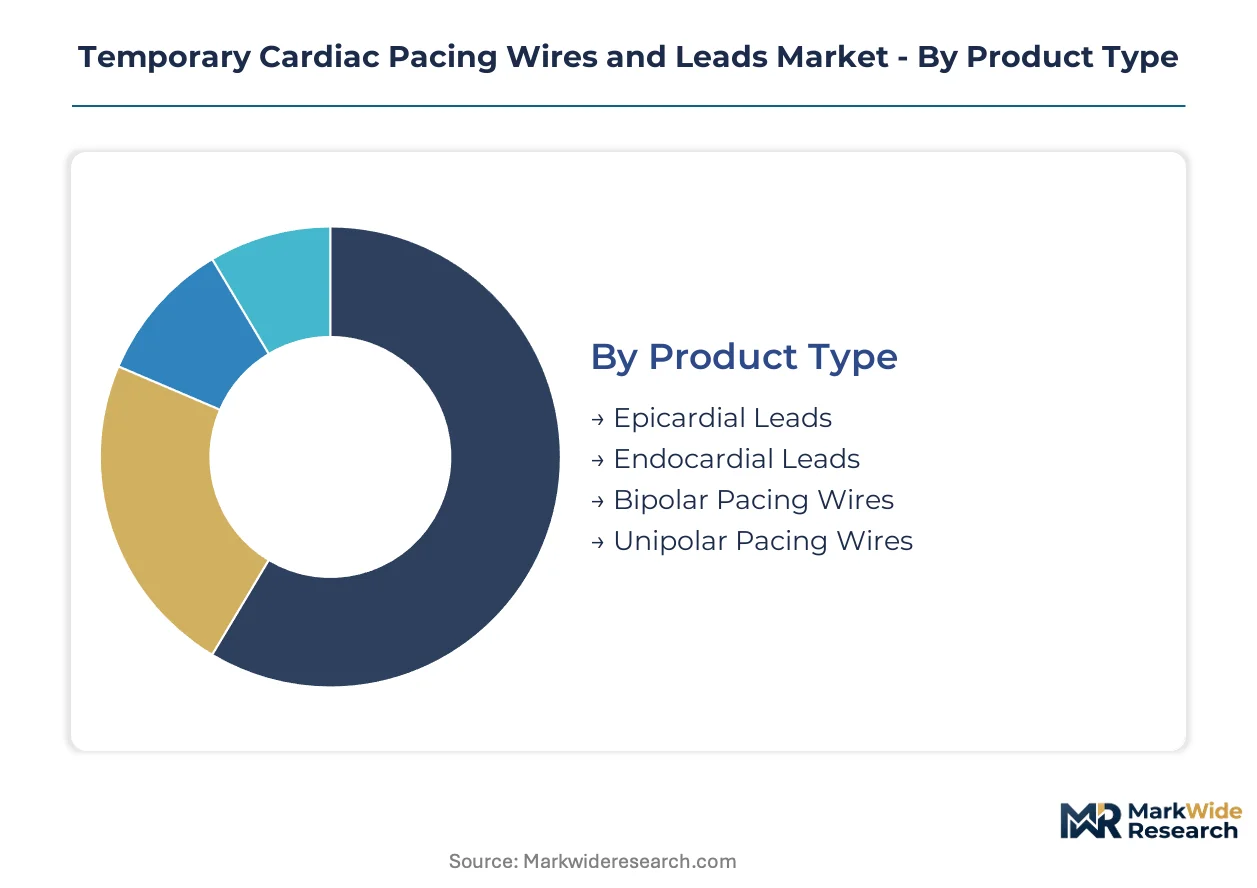
Segmentation in temporary cardiac pacing wires and leads reveals how regulatory pathways, material science investments, and procedural site economics fragment procurement behavior across hospital systems and specialized cardiac centers.
Product Type:
FDA 510(k) clearance timelines stretch longest for active-electrode configurations requiring biocompatibility validation under ISO 10993-5 and ISO 10993-10, while passive conductive designs face abbreviated review cycles.
- Epicardial Leads:Direct myocardial attachment electrodes fabricated from platinum-iridium alloys with silicone insulation, designed for sternotomy access during open-heart procedures. Demand concentrates in Tokyo and Osaka medical centers where aging surgical populations sustain complex coronary artery bypass volumes, though EU MDR Class III recertification costs are compressing supplier margins on legacy product lines.
- Endocardial Leads:Transvenous access electrodes delivered through femoral or jugular introducers, gaining share in electrophysiology labs pursuing minimally invasive alternatives to surgical placement. German catheterization centers in Munich and Heidelberg are expanding transvenous protocols for postoperative bradyarrhythmia management, displacing epicardial dependence in hemodynamically stable patients.
- Bipolar Pacing Wires:Dual-electrode configurations with electromagnetic interference rejection, commanding premium positioning in postoperative telemetry settings where signal fidelity determines weaning decisions.
- Unipolar Pacing Wires:Single-electrode emergency configurations optimized for rapid deployment, occupying cost-sensitive procurement tiers in emergency medicine and developing market hospital systems.
Epicardial leads sit at the top of the volume ranking, with endocardial leads climbing the fastest as transvenous protocols displace surgical placement in stable postoperative populations.
Application:
Reimbursement intensity varies sharply across settings, with cardiac surgery commanding bundled payment premiums and emergency medicine operating under flat-fee diagnostic-related group constraints that favor disposable cost minimization.
- Cardiac Surgery:Intraoperative and immediate postoperative pacing following valve replacement, coronary bypass, or congenital repair procedures. United States academic medical centers in Boston and Cleveland maintain highest utilization density, driven by surgical volume concentration and integrated perfusionist-electrophysiologist staffing models.
- Emergency Medicine:Transcutaneous bridge pacing in hemodynamically unstable bradyarrhythmia or high-grade AV block pending definitive therapy. Indian tier-2 hospital expansion under CDSCO medical device rules is creating volume concentration for standardized unipolar emergency kits, though price elasticity limits margin capture.
- Electrophysiology:Diagnostic and therapeutic pacing during catheter ablation or electrophysiological study procedures.
- Postoperative Care:Extended temporary pacing in cardiac surgery recovery units requiring rhythm stabilization before permanent pacemaker decision or weaning.
Cardiac surgery generates the highest absolute revenue per procedure, while electrophysiology applications are gaining share fastest as lab infrastructure expands into community hospital settings.
End User:
Procurement authority concentrates differently across facility types, with hospitals maintaining value analysis committees for bundled cardiovascular contracts and surgical centers delegating purchasing to physician preference item systems.
- Hospitals:Integrated delivery networks in the United States Midwest negotiate multi-year sole-source agreements spanning pacing wires, introducers, and monitoring accessories, with consignment inventory reducing operating room stockout risk.
- Cardiac Clinics:Specialized outpatient facilities focused on electrophysiology diagnostics and minor interventions, purchasing through specialty distributors rather than direct manufacturer relationships.
- Surgical Centers:Ambulatory settings with limited cardiac surgery volume, prioritizing disposable cost minimization over technology differentiation.
- Research Institutions:Academic medical centers conducting device evaluation and training, generating limited commercial volume but influencing downstream procurement standards through fellowship training pipelines.
Hospitals dominate procurement volume, with cardiac clinics expanding their share fastest as electrophysiology services decentralize from tertiary centers.
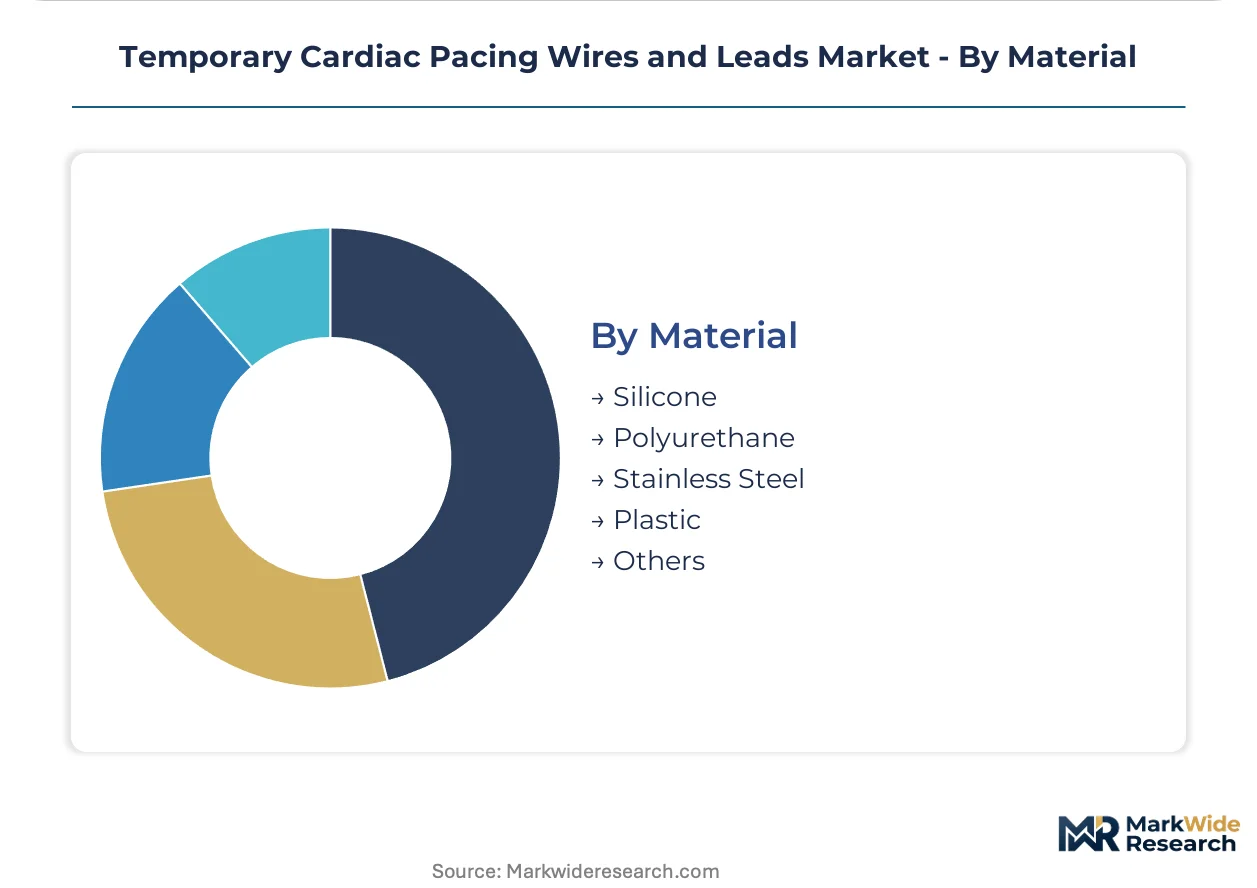
Material:
Supply concentration in German polymer processors creates single-source vulnerability for medical-grade polyurethane, while silicone insulation depends on established Asian compounders with FDA master file documentation.
- Silicone:Platinum-cured elastomer insulation with established biocompatibility profiles under ISO 10993, dominating epicardial and long-dwell temporary pacing applications where flexibility and tissue compatibility outweigh material cost.
- Polyurethane:High-tensile thermoplastic insulation enabling thinner wall construction for transvenous delivery, concentrated in specialized German compounders with EU MDR notified body certification.
- Stainless Steel:Conductive core material for unipolar and bipolar electrodes, subject to nickel release testing under REACH Annex XVII restrictions.
- Plastic:Handle and connector housing components, sourced from medical-grade ABS and polycarbonate suppliers with established sterilization validation.
- Others:Emerging coatings and surface treatments including heparin bonding and antimicrobial silver ion impregnation.
Silicone leads material volume, with polyurethane gaining fastest as transvenous lead designs proliferate in electrophysiology applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Temporary cardiac pacing wire manufacturing originated in German surgical instrument workshops during the 1960s, with Munich and Heidelberg medical centers pioneering epicardial lead techniques that spread to North American and Japanese cardiac surgery programs.
United States
Boston and Cleveland academic medical centers sustain the highest utilization density through integrated perfusionist-electrophysiologist staffing models. FDA 510(k) clearance pathways govern biocompatibility validation under ISO 10993, with Class III device reclassification extending review timelines. Midwestern integrated delivery networks negotiate multi-year sole-source agreements that displace specialty distributor relationships.
Germany
Munich and Heidelberg catheterization centers are expanding transvenous protocols for postoperative bradyarrhythmia management. EU MDR Class III certification mandates stricter vigilance reporting timelines than predecessor directives, elevating documentation costs. Bavarian and Baden-Württemberg surgical centers drive demand for differentiated sterile packaging configurations that reduce operating room setup time.
Japan
Tokyo and Osaka medical centers sustain complex coronary artery bypass volumes that concentrate demand for epicardial lead configurations. PMDA biocompatibility standards align with ISO 10993 material testing requirements, locking in incumbent supplier relationships. The aging surgical population in Kanto and Kansai regions sustains procedure volumes that exceed per-capita rates in Western markets.
India
Tier-2 and Tier-3 hospital infrastructure expansion under CDSCO medical device rules creates volume concentration for standardized unipolar emergency kits. Maharashtra and Gujarat cardiac centers are piloting direct-to-hospital digital procurement models that reduce stockout risk. Price elasticity in tender-based purchasing limits margin capture on premium configurations.
Temporary Cardiac Pacing Wires and Leads Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification depth and sterile kit integration capabilities. The vendor base clusters around three strategic archetypes: diversified cardiovascular conglomerates with catheter lab loyalty programs, specialized access device manufacturers with complementary deployment tools, and regional surgical instrument suppliers with differentiated packaging configurations. Dominant competitive moves include portfolio bundling that spans pacing wires with introducers and monitoring adapters, and backward integration into medical-grade polymer compounding to secure insulation supply.
Within the diversified cardiovascular tier, Medtronic anchors catheter lab loyalty across North American health systems through integrated portfolio positioning. Merit Medical Systems Inc. exemplifies the specialized access device archetype, occupying a position where introducer manufacturing complements pacing wire deployment workflows. B. Braun SE represents the European surgical center specialist, sitting within a competitive set defined by sterile packaging differentiation and operating room efficiency optimization.
| Leading Market Players |
|---|
| Medtronic |
| Merit Medical Systems Inc. |
| BD |
| B. Braun SE |
| Abbott |
| Edwards Lifesciences Corporation |
| Teleflex Incorporated |
| Oscor Inc. |
| OSYPKA MEDICAL |
| Others |
Value Network & Pricing Analysis
Hospital procurement consolidation across United States integrated delivery networks is forcing manufacturers to absorb sterilization validation costs and reconfigure kit architectures around single-source contract economics, compressing margins on legacy product lines while rewarding suppliers with captive polymer compounding capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates temporary cardiac pacing wire procurement, with bipolar configurations commanding premiums based on FDA 510(k) clearance depth and electromagnetic interference rejection performance. Price differentiation hinges on ISO 10993 biocompatibility certification tier and sterile kit bundling with introducers and monitoring adapters. Cost compression in emergency medicine unipolar segments is intensifying because Indian tier-2 hospital tender processes prioritize disposable cost minimization over signal fidelity. Academic medical centers in Boston and Cleveland exhibit lowest price sensitivity, while Maharashtra and Gujarat cardiac centers in India demonstrate highest elasticity.
Supply Chain Analysis
Specialized cardiovascular distributors in Germany pilot consignment inventory models that reduce operating room stockout risk and accelerate replenishment cycles. Geographic supply concentration centers on German polymer processors for medical-grade polyurethane insulation, Japanese platinum-iridium alloy fabricators, and Asian silicone compounders with FDA master file documentation. Raw material dependencies rest on platinum-group metals for electrode cores, platinum-cured silicone for insulation, and medical-grade thermoplastic polyurethane for transvenous delivery systems. Single-source vulnerability in Bavarian polymer compounding creates exposure to EU MDR notified body certification delays. Distribution runs through direct manufacturer contracts with United States health systems and specialty distributors serving European catheterization centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story where EU MDR Class III recertification costs and ISO 10993 testing backlogs are filtering marginal suppliers, concentrating procurement authority with incumbents possessing established biocompatibility documentation and sterile kit integration capabilities.
For Market Incumbents: Anticipate electrophysiology lab expansion displacing open-chest epicardial placement in stable postoperative populations, threatening surgical wire volume concentration. Defensive priorities center on backward integration into medical-grade polymer compounding to secure insulation supply against German processor concentration risk, and software companion development for automated rhythm detection algorithms that create recurring revenue attachments and hospital system lock-in.
For New Entrants and Emerging Players: The gap between premium bipolar configurations and economy unipolar emergency kits offers white-space positioning for mid-tier standardized endocardial leads with transvenous delivery optimization. Target Indian tier-2 and tier-3 hospital infrastructure expansion under CDSCO medical device rules, where price elasticity limits incumbent margin capture but volume concentration rewards lean manufacturing. Go-to-market execution should emphasize direct-to-hospital digital procurement pilots that bypass legacy distributor markups.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized access device manufacturers possessing introducer manufacturing capabilities that complement pacing wire deployment workflows. Long-term viability favors suppliers with dual FDA and EU MDR certification depth across the projection horizon. Acquisition screening should prioritize firms with captive silicone compounding or heparin-bonding surface treatment IP. The signal to monitor is PMDA biocompatibility standard harmonization with ISO 10993, which would accelerate Japanese market entry for qualified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class III Recertification Investment | Locks in incumbent positioning against smaller manufacturers facing documentation cost barriers in German and French notified body jurisdictions. |
| Automated Rhythm Detection Software Development | Captures postoperative telemetry workflow real estate previously served by standalone monitors in United States academic medical centers. |
| Consignment Inventory Model Deployment | Reduces operating room stockout risk for Bavarian surgical centers while accelerating replenishment cycles through direct manufacturer relationships. |
| Medical-Grade Polyurethane Backward Integration | Secures insulation supply against single-source vulnerability in specialized German compounders with EU MDR notified body certification. |
| CDSCO Registration Pathway Execution | Enables first-mover positioning in Maharashtra and Gujarat tier-2 hospital expansion under India's tightened medical device rules. |
Research Methodology
Direct dialogue with cardiac surgeons, electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers grounded the qualitative assessment, cross-referenced against FDA 510(k) clearance databases, EU MDR notified body certification records, hospital procurement contract filings, and CMS Medicare reimbursement schedules. Secondary validation drew from ISO 10993 material testing documentation, PMDA biocompatibility submission data, and CDSCO medical device registration records. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Segment-level outputs across the modeling period reflect product type, application setting, end-user facility category, and insulation material chemistry, with CAGRs derived from surgical volume projections, electrophysiology lab expansion trajectories, and regulatory pathway timeline assumptions. Forecast inputs incorporated aging demographic surgical demand curves, EU MDR recertification cost pass-through elasticity, and smart pacing algorithm adoption curves in postoperative telemetry workflows.
The model assumes a particular technology adoption path; alternative pathways for transvenous endocardial lead displacement of epicardial surgical placement would alter the outlook. Forecasts reflect base-case assumptions regarding ISO 10993 testing backlog resolution and platinum-group metal price stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Needles Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Global Scleral Lens Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Power Smart Bed Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Global Prosthetics Market
Medical Devices
Colposcopes Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
United States Insulin Pumps Market