
 Difficile Infections (Clostridium Difficile Associated Disease) Market | 2026-2036
Difficile Infections (Clostridium Difficile Associated Disease) Market Size, Share, and Industry Trends Forecast 2026-2036
Difficile Infections (Clostridium Difficile Associated Disease) Market Outlook
The FDA's Breakthrough Therapy designation pathway for microbiome-based treatments is hardening quality benchmarks across the Clostridioides difficile therapeutic landscape. Merck & Co., Inc. leverages its established hospital formulary relationships to sustain antibiotic distribution dominance. Seres Therapeutics, Inc. anchors the emerging live biotherapeutic segment through advanced microbiome engineering capabilities. Pfizer Inc. competes across both prevention and treatment modalities with diversified pipeline investments.
Clostridioides difficile associated disease constitutes a toxin-mediated gastrointestinal infection triggered by anaerobic, spore-forming bacteria following antimicrobial disruption of colonic flora, with recurrence rates exceeding twenty percent after standard vancomycin therapy. The condition primarily threatens immunocompromised hospitalized patients and drives substantial morbidity in long-term care settings. Antibiotics retain the largest revenue share within product type segmentation, though vaccines and live biotherapeutics represent the fastest-expanding margin pools as prevention strategies gain clinical traction. Oral delivery mode dominates hospital dispensing protocols, while intravenous formulations occupy critical care applications where absorption reliability is paramount.
FDA oversight through its Center for Biologics Evaluation and Research shapes live biotherapeutic approval timelines, while EMA's ATMP classification framework governs European market access for microbiome products. The Centers for Medicare & Medicaid Services reimbursement policies directly influence hospital procurement decisions for recurrent infection protocols. Stakeholders must monitor evolving FDA guidance on microbiome product characterization standards and prepare for potential CMS bundled payment reforms targeting readmission reduction.
Market Dynamics
FDA's Breakthrough Therapy designation pathway for microbiome-based treatments is compressing approval timelines while simultaneously elevating manufacturing quality benchmarks across the live biotherapeutic segment. Hospital procurement committees now weigh recurrence prevention economics against upfront antibiotic costs.
Growth Catalysts
- CMS bundled payment reforms:Medicare's hospital readmission reduction programs create direct financial incentives for tertiary care centers to adopt recurrence-prevention protocols. Long-term care facilities face parallel pressure from value-based purchasing metrics.
- Microbiome characterization advances:Next-generation sequencing platforms enable precise donor strain matching in fecal microbiota transplantation, improving standardization for investigational live biotherapeutic products.
- Immunocompromised patient volume:Expanding oncology and transplant patient populations in tertiary hospitals sustain demand for targeted prophylactic interventions against toxin-mediated gastrointestinal infection.
Market Restraints
- Live biotherapeutic manufacturing complexity:Anaerobic culture requirements and spore-forming bacterial stability constraints limit contract manufacturing organization capacity for microbiome products.
- Vancomycin generic erosion:Commodity pricing of first-line oral antibiotics compresses revenue pools in the established treatment segment and deters incremental R&D investment.
- EMA ATMP classification uncertainty:European regulators' evolving stance on genetically modified organism thresholds for engineered bacterial consortia extends pre-submission consultation timelines.
Strategic Opportunities
- Long-term care facility penetration:Skilled nursing facilities in the United States remain underpenetrated for standardized infection control protocols, creating whitespace for preventive therapeutic adoption.
- Oral-to-IV formulation expansion:Critical care applications currently dependent on intravenous delivery present development targets for absorption-enhanced oral alternatives with comparable bioavailability.
- FDA microbiome guidance finalization:Pending characterization standards from the Center for Biologics Evaluation and Research will clarify quality control thresholds, reducing regulatory risk capital for pipeline candidates.
Industry Challenges
- Clinical microbiology workforce scarcity:Specialized anaerobic bacteriology expertise required for C. difficile diagnostics and surveillance strains hospital laboratory staffing capacity.
- Cold chain integrity maintenance:Live biotherapeutic products require continuous refrigerated distribution from manufacturing through administration, complicating pharmacy inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Difficile Infections (Clostridium Difficile Associated Disease) Market |
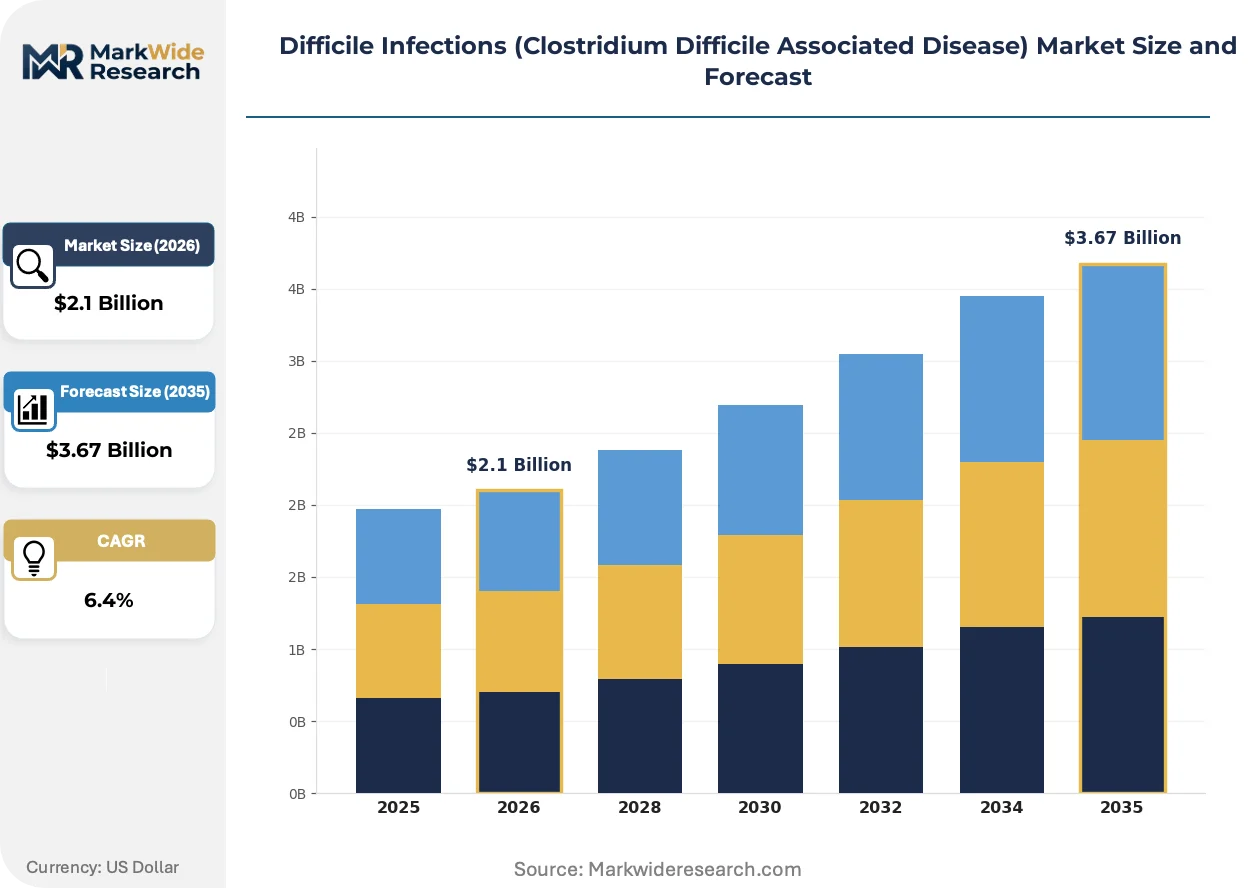
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Probiotics, Vaccines, Diagnostics Delivery Mode: Oral, Intravenous, Topical, Intramuscular End User: Hospitals, Outpatient Clinics, Long-term Care Facilities, Home Healthcare Application: Infection Treatment, Infection Prevention, Diagnostic Testing, Research |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., Sanofi S.A., AstraZeneca, Ferring Pharmaceuticals, Summit Therapeutics, Seres Therapeutics, Inc., Vedanta Biosciences, Astellas Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Difficile Infections (Clostridium Difficile Associated Disease) Market Strategic Shifts
Microbiome engineering platforms are actively displacing conventional small-molecule development paradigms, with synthetic biology approaches enabling rationally designed bacterial consortia. The competitive landscape separates along modality lines: established antibiotics, emerging live biotherapeutics, and prophylactic vaccines.
Recombinant strain engineering is electrifying the live biotherapeutic pipeline, with synthetic biology tools enabling precise deletion of virulence factors and insertion of therapeutic payload genes. Academic medical centers with established microbiome research programs are accelerating early-phase trials. This capability convergence is compressing traditional pharmaceutical development timelines and enabling platform approaches across multiple infectious indications.
EMA's Advanced Therapy Medicinal Products classification framework is creating differentiated market access pathways for microbiome products in Europe, with centralized procedures replacing national competent authority variations. Manufacturers must navigate divergent genetically modified organism thresholds across member states. The Netherlands and Denmark have emerged as early adoption clusters for fecal microbiota transplantation standardization.
Hospital pharmacy committees are consolidating formulary decisions through centralized procurement for antimicrobial stewardship programs, displacing individual prescriber discretion. Integrated delivery networks in the United States are negotiating multi-year contracts spanning prevention and treatment modalities. This concentration is most visible in tertiary academic medical centers with dedicated infectious disease pharmacists.
Difficile Infections (Clostridium Difficile Associated Disease) Market Segmentation
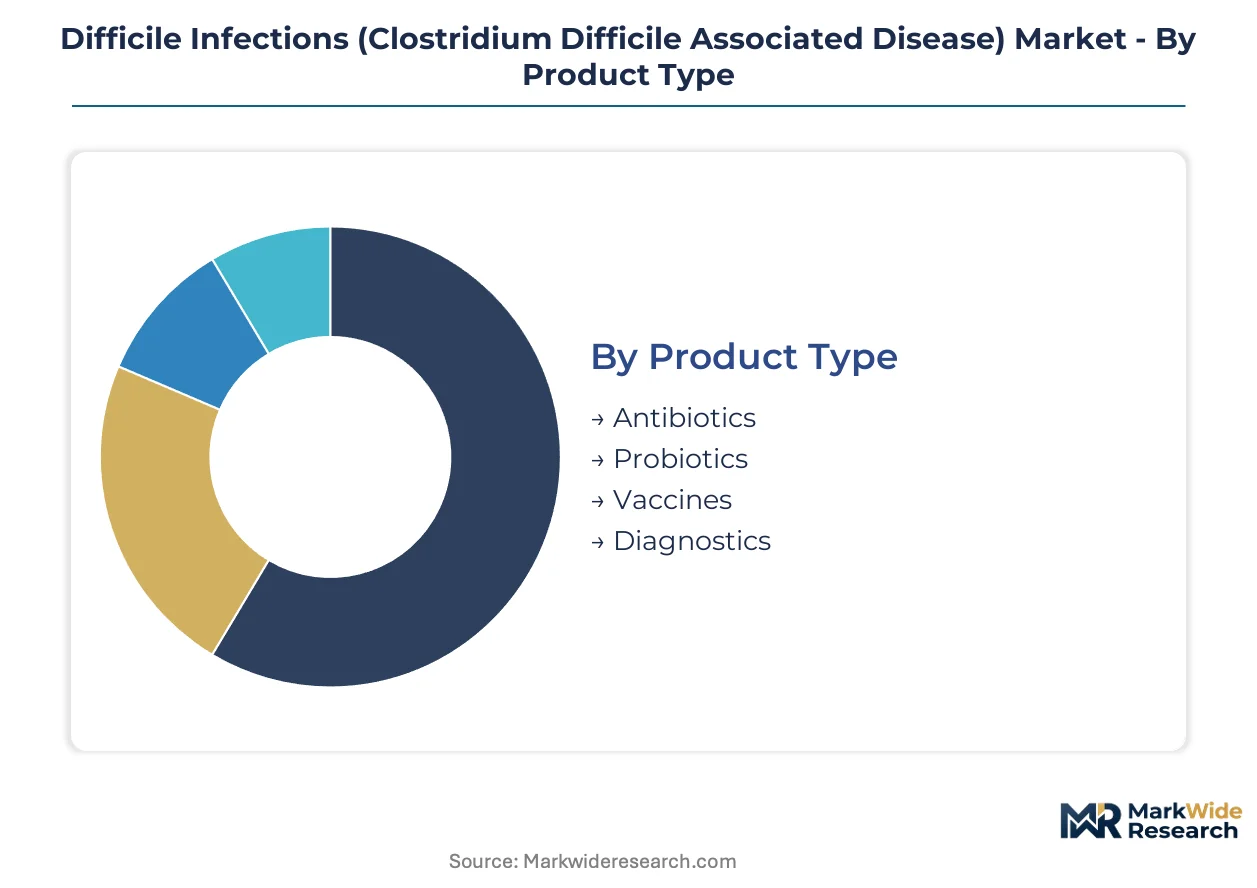
Segmentation in the C. difficile market determines regulatory pathway complexity and procurement economics. Hospital pharmacy committees evaluate product categories through distinct reimbursement and approval lenses, while delivery mode selection drives manufacturing investment priorities.
Product Type:
FDA's Center for Biologics Evaluation and Research governs live biotherapeutics and vaccines through distinct quality benchmarks, while the Center for Drug Evaluation and Research oversees small-molecule antibiotics under abbreviated approval pathways.
- Antibiotics:Oral vancomycin and fidaxomicin formulations dominate hospital formularies through established anaerobic bacteriology protocols. Tertiary care centers in the United States drive volume through antimicrobial stewardship programs that prioritize recurrence-resistant agents.
- Vaccines:Toxoid-based and recombinant subunit candidates target toxin-mediated pathogenesis prevention in immunocompromised populations. Long-term care facilities represent concentrated demand as Medicare bundled payment reforms create prophylactic intervention incentives.
- Probiotics:Live biotherapeutic products require anaerobic culture manufacturing capacity and continuous cold chain integrity from production through administration.
- Diagnostics:Nucleic acid amplification tests and enzyme immunoassays enable rapid toxin detection in hospital laboratory settings.
Antibiotics sit at the top of the volume ranking, with vaccines climbing the fastest as prevention strategies displace reactive treatment protocols.
Delivery Mode:
Route of administration determines bioavailability requirements and manufacturing complexity tiers, with oral formulations commanding premium margins against intravenous alternatives.
- Oral:Colonic-targeted delivery systems with enteric coatings protect acid-labile payloads through gastric transit. Hospital dispensing protocols favor oral administration for ambulatory and step-down unit patients.
- Intravenous:Critical care applications demand absorption reliability where gastrointestinal motility is compromised. Intensive care units in academic medical centers sustain demand for IV formulations.
- Topical:Limited applicability in gastrointestinal infection management restricts development investment.
- Intramuscular:Vaccine administration routes align with standard immunization protocols in outpatient and long-term care settings.
Oral delivery commands the highest volume position, with intravenous alternatives expanding most quickly in critical care segments.
End User:
Procurement concentration varies sharply across institutional settings, with integrated delivery networks consolidating purchasing power in tertiary hospital systems.
- Hospitals:Tertiary academic medical centers with dedicated infectious disease pharmacists anchor formulary decision-making. Antimicrobial stewardship committees centralize procurement across prevention and treatment modalities.
- Long-term Care Facilities:Skilled nursing facilities in the United States remain underpenetrated for standardized infection control protocols. CMS value-based purchasing metrics create adoption pressure for recurrence-prevention therapeutics.
- Outpatient Clinics:Community-based gastroenterology practices manage initial infection episodes with oral antibiotic regimens.
- Home Healthcare:Oral formulation suitability enables post-discharge continuation of therapy in residential settings.
Hospitals sit at the top of the volume ranking, with long-term care facilities gaining share fastest as bundled payment reforms extend beyond acute care.
Application:
Clinical utility separates mature treatment markets from emerging prevention and diagnostic segments with differentiated margin profiles.
- Infection Treatment:Standard-of-care antibiotic protocols address active toxin-mediated colitis with established reimbursement codes. Recurrence rates exceeding twenty percent after vancomycin therapy sustain demand for next-generation agents.
- Infection Prevention:Prophylactic vaccines and live biotherapeutics target high-risk immunocompromised cohorts before initial infection. Oncology and transplant patient populations in tertiary hospitals drive targeted intervention protocols.
- Diagnostic Testing:Rapid molecular detection platforms enable same-day treatment initiation in hospital laboratories.
- Research:Academic medical centers with established microbiome research programs accelerate early-phase trials for engineered bacterial consortia.
Infection treatment maintains the volume leadership position, with infection prevention representing the steepest expansion trajectory as prevention economics reshape procurement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern C. difficile therapeutic industry traces its commercial roots to the United States, where vancomycin first achieved regulatory approval for pseudomembranous colitis in the 1980s and hospital-based antimicrobial stewardship programs subsequently institutionalized infection control protocols.
United States
Tertiary academic medical centers and long-term care facilities drive therapeutic demand through Medicare's hospital readmission reduction programs. The FDA's Center for Biologics Evaluation and Research governs live biotherapeutic approvals through Breakthrough Therapy designation pathways. Boston and San Francisco anchor microbiome engineering clusters where academic medical centers accelerate early-phase trials.
Germany
Integrated delivery networks consolidate formulary decisions across prevention and treatment modalities in tertiary hospital systems. The EMA's Advanced Therapy Medicinal Products classification framework governs European market access for microbiome products through centralized procedures. Berlin and Heidelberg host established microbiome research programs that standardize fecal microbiota transplantation protocols.
United Kingdom
Immunocompromised oncology and transplant patient populations in National Health Service trusts sustain demand for targeted prophylactic interventions. The Medicines and Healthcare products Regulatory Agency aligns with EMA centralized procedures for microbiome product characterization standards. London's academic medical centers compress traditional pharmaceutical development timelines through synthetic biology platform approaches.
Japan
Hospital pharmacy committees in tertiary care centers prioritize recurrence-resistant agents through antimicrobial stewardship programs. The Pharmaceuticals and Medical Devices Agency oversees quality benchmarks for anaerobic culture manufacturing of live biotherapeutic products. Tokyo and Osaka metropolitan areas concentrate infectious disease pharmacist expertise for formulary decision-making.
Netherlands
Skilled nursing facilities face adoption pressure from value-based purchasing metrics targeting infection control standardization. The country's national pharmaceutical regulator navigates EMA ATMP classification alongside divergent genetically modified organism thresholds across member states. Amsterdam and Utrecht emerged as early adoption clusters for fecal microbiota transplantation standardization.
Difficile Infections (Clostridium Difficile Associated Disease) Market Competitive Environment
Capital-heavy producers with integrated manufacturing infrastructure compete with asset-light developers reliant on contract manufacturing organizations for anaerobic culture capacity. The market structure separates along modality lines, with established antibiotic franchises, emerging live biotherapeutic platforms, and prophylactic vaccine pipelines occupying distinct competitive tiers. Three archetypes dominate: diversified pharmaceutical conglomerates leveraging hospital formulary relationships, microbiome engineering specialists advancing synthetic biology platforms, and mid-cap developers targeting recurrence-prevention protocols. Competitive dynamics center on strategic partnerships for manufacturing scale and portfolio diversification across prevention and treatment modalities.
Within the diversified pharmaceutical tier, Merck & Co., Inc. and Pfizer Inc. exemplify incumbents with established hospital distribution networks. Seres Therapeutics, Inc. occupies a position among microbiome engineering specialists advancing live biotherapeutic platforms. These three entities represent the competitive spectrum from antibiotic dominance through emerging bacterial consortium therapies.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| Sanofi S.A. |
| AstraZeneca |
| Ferring Pharmaceuticals |
| Summit Therapeutics |
| Seres Therapeutics, Inc. |
| Vedanta Biosciences |
| Astellas Pharma |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States concentrate procurement power for C. difficile therapeutics, enabling value-based contracting that ties pricing to readmission reduction outcomes. This buyer consolidation shifts pricing power toward hospital systems with antimicrobial stewardship committees that negotiate multi-year formulary agreements spanning prevention and treatment modalities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates recurrence-resistant antibiotics from generic vancomycin and emerging live biotherapeutics. Price differentiation centers on clinical outcome guarantees and cold chain reliability certification for microbiome products. Pricing pressure stems from vancomycin generic erosion that compresses revenue pools in the established treatment segment. Long-term care facilities exhibit highest price sensitivity due to CMS reimbursement constraints, while tertiary academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Domestic-content mandates for pharmaceutical manufacturing in the United States and European Union are reshaping sourcing patterns for anaerobic culture capacity and spore-forming bacterial strains. Supply concentrates in the United States, Germany, and the Netherlands for live biotherapeutic production, with contract manufacturing organization capacity limiting scale-up. Raw material dependencies include donor microbiota screening platforms, anaerobic fermentation media, and enteric coating polymers for oral formulations. Single-source vulnerability in specialized anaerobic bacteriology expertise strains hospital laboratory staffing. Distribution runs through hospital pharmacy central procurement with cold chain integrity requirements from manufacturing through administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in C. difficile therapeutics rests on microbiome product premiumization and manufacturing cost compression through anaerobic culture platform standardization.
For Market Incumbents: Deepen hospital formulary relationships through integrated prevention-treatment portfolio bundling that anchors antimicrobial stewardship committee decisions. Expand in-house anaerobic manufacturing capacity to reduce contract manufacturing organization dependency and capture live biotherapeutic margin pools. Counter microbiome engineering specialists by accelerating FDA Breakthrough Therapy pathway submissions for recurrence-prevention protocols. For New Entrants and Emerging Players: Synthetic biology-enabled rationally designed bacterial consortia offer a technology-first wedge against established antibiotic franchises. Target skilled nursing facilities in the United States where standardized infection control protocols remain underpenetrated and CMS value-based purchasing metrics create adoption pressure. Pursue hospital system pilot programs that demonstrate readmission reduction economics to secure formulary inclusion. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with hospital distribution networks are the most active acquirers in this space, seeking microbiome platform capabilities to complement antibiotic franchises. Acquisition target archetypes include mid-cap live biotherapeutic developers with FDA Breakthrough Therapy designation and established anaerobic manufacturing partnerships. Watch for FDA microbiome guidance finalization as the signal indicating reduced regulatory risk capital and accelerated approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates FDA Breakthrough Therapy designation for microbiome-based recurrence prevention. |
| Manufacturing Scale-Up | Expands anaerobic culture capacity to meet cold chain distribution requirements for live biotherapeutics. |
| Regulatory Approval Pathway | Clarifies EMA ATMP classification for engineered bacterial consortia in European markets. |
| Hospital System Partnership | Secures antimicrobial stewardship committee formulary inclusion through integrated delivery networks. |
| Pipeline Diversification | Spans prevention vaccines, live biotherapeutics, and next-generation antibiotics across treatment modalities. |
Study Parameters
Multiple input streams — primary interviews with infectious disease pharmacists and formulary directors, regulatory filing analysis, and hospital procurement database review — were reconciled to construct market estimates. Drug development executives at microbiome engineering specialists, antimicrobial stewardship committee chairs at tertiary academic medical centers, and payer access specialists at integrated delivery networks provided qualitative validation. Secondary sources included FDA Center for Biologics Evaluation and Research filings, EMA Advanced Therapy Medicinal Products submissions, ClinicalTrials.gov protocols, and CMS Medicare reimbursement data. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation cross-validated segment-level outputs.
Historical recurrence rate trends and expert panel input on microbiome product adoption curves were cross-referenced against antimicrobial stewardship program expansion patterns. Segmentation dimensions modeled encompassed product type, delivery mode, end user institution, and application across treatment and prevention. CAGRs were derived from regression analysis of patient volume drivers and pricing trajectory assumptions. Forecast inputs included immunocompromised patient population growth, FDA guidance timeline expectations, and CMS bundled payment reform implementation pace.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA microbiome characterization standard finalization and EMA genetically modified organism threshold harmonization. Forecasts reflect documented assumptions regarding hospital formulary consolidation speed and live biotherapeutic manufacturing scale-up feasibility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Brucellosis Market
Infectious Disease
Actinomycosis Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Direct-Acting Antiviral Medicines Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Measles Market
Infectious Disease
Virology Market
Infectious Disease
Efavirenz Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Tuberculous Meningitis Treatment Market