
 South America Kidney Cancer Therapeutics and Diagnostics Market | 2026-2036
South America Kidney Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Kidney Cancer Therapeutics and Diagnostics Market Analytics
Hospital procurement consortiums across South America is tilting toward centralized tendering for renal oncology portfolios. Bristol Myers Squibb leverages its immuno-oncology franchise to anchor relationships with major public hospital networks. Bayer competes through sustained investment in targeted therapy access programs that navigate reimbursement complexity. Novartis International differentiates via diagnostic-treatment bundling with imaging and biomarker partnerships.
Kidney cancer therapeutics and diagnostics encompasses systemic treatment modalities and companion detection technologies for renal cell carcinoma and related malignancies, spanning small-molecule inhibitors, monoclonal antibodies, radiation protocols, and molecular profiling assays that guide therapy selection based on tumor mutational status and patient stratification. The primary purpose is to extend progression-free survival while minimizing nephrotoxicity through precision-matched interventions. Targeted therapy commands the largest revenue share given established reimbursement for tyrosine kinase inhibitors across major South American markets. Liquid biopsy represents the fastest-expanding technology segment as blood-based monitoring reduces dependence on repeat tissue sampling in fragmented healthcare systems. Hospitals remain the dominant end-user channel, though homecare providers are gaining traction for oral agent administration.
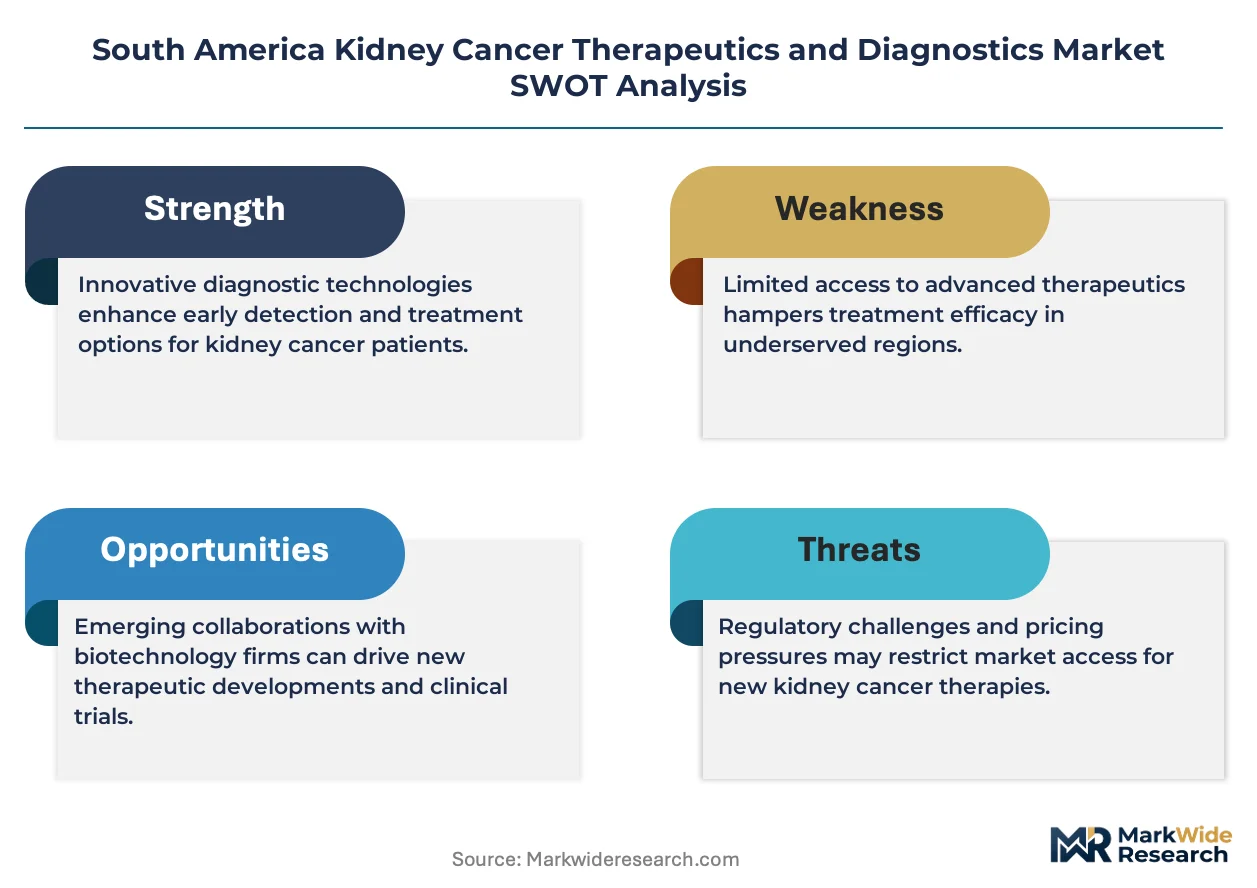
ANVISA in Brazil and INVIMA in Colombia enforce pharmacovigilance and import licensing requirements that shape market entry timelines for novel therapeutics, while Argentina's national oncology program establishes price reference mechanisms affecting commercial strategy. These frameworks compel manufacturers to localize clinical data generation and adapt labeling to regional comparator standards. Stakeholders must monitor evolving biosimilar pathways and diagnostic reimbursement carve-outs as public budgets face pressure from expanding immunotherapy indications.
Market Dynamics
Centralized hospital procurement consortiums across Brazil and Argentina are consolidating purchasing power for renal oncology portfolios, compressing vendor margins while favoring suppliers with integrated diagnostic-therapeutic bundles and established tender navigation capabilities.
Growth Catalysts
- ANVISA Fast-Track Pathway:Brazil's accelerated approval mechanism for oncology biologics reduces time-to-market for novel agents, incentivizing manufacturers to prioritize regulatory submissions in South America.
- Liquid Biopsy Adoption:Blood-based tumor monitoring technologies eliminate repeat tissue sampling burdens in fragmented healthcare systems, expanding addressable patient populations beyond major metropolitan centers.
- Private Insurance Clustering:São Paulo-Rio de Janeiro corridor concentration of specialist referral networks and premium health coverage creates concentrated demand pools for precision-matched interventions.
Market Restraints
- Import Licensing Friction:INVIMA in Colombia and ANVISA pharmacovigilance requirements extend market entry timelines for novel therapeutics, delaying revenue realization.
- Reimbursement Complexity:Argentina's national oncology program price reference mechanisms compress commercial margins and complicate pricing architecture across the Southern Cone.
- Biomarker Testing Gaps:Limited molecular diagnostic infrastructure outside tertiary hospital networks restricts patient stratification for targeted therapy selection.
Strategic Opportunities
- Homecare Oral Administration:Expansion of oral tyrosine kinase inhibitor delivery through specialized homecare providers addresses hospital capacity constraints and patient convenience preferences.
- Diagnostic-Treatment Bundling:Imaging and biomarker partnerships enable integrated value propositions that differentiate vendors in centralized tendering environments.
- Colombian Market Development:Underpenetrated oncology infrastructure outside Bogotá-Medellín corridor presents first-mover advantages for localized clinical data generation and labeling adaptation.
Industry Challenges
- Molecular Pathology Talent Scarcity:Shortage of trained personnel for next-generation sequencing interpretation and biomarker reporting limits diagnostic throughput expansion.
- Biosimilar Pathway Uncertainty:Evolving regulatory frameworks for biologic substitutes create portfolio planning complexity and intellectual property exposure for originator manufacturers.
- Legacy System Integration:Hospital information system fragmentation complicates real-world data capture for post-market surveillance and health technology assessment submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Kidney Cancer Therapeutics and Diagnostics Market |
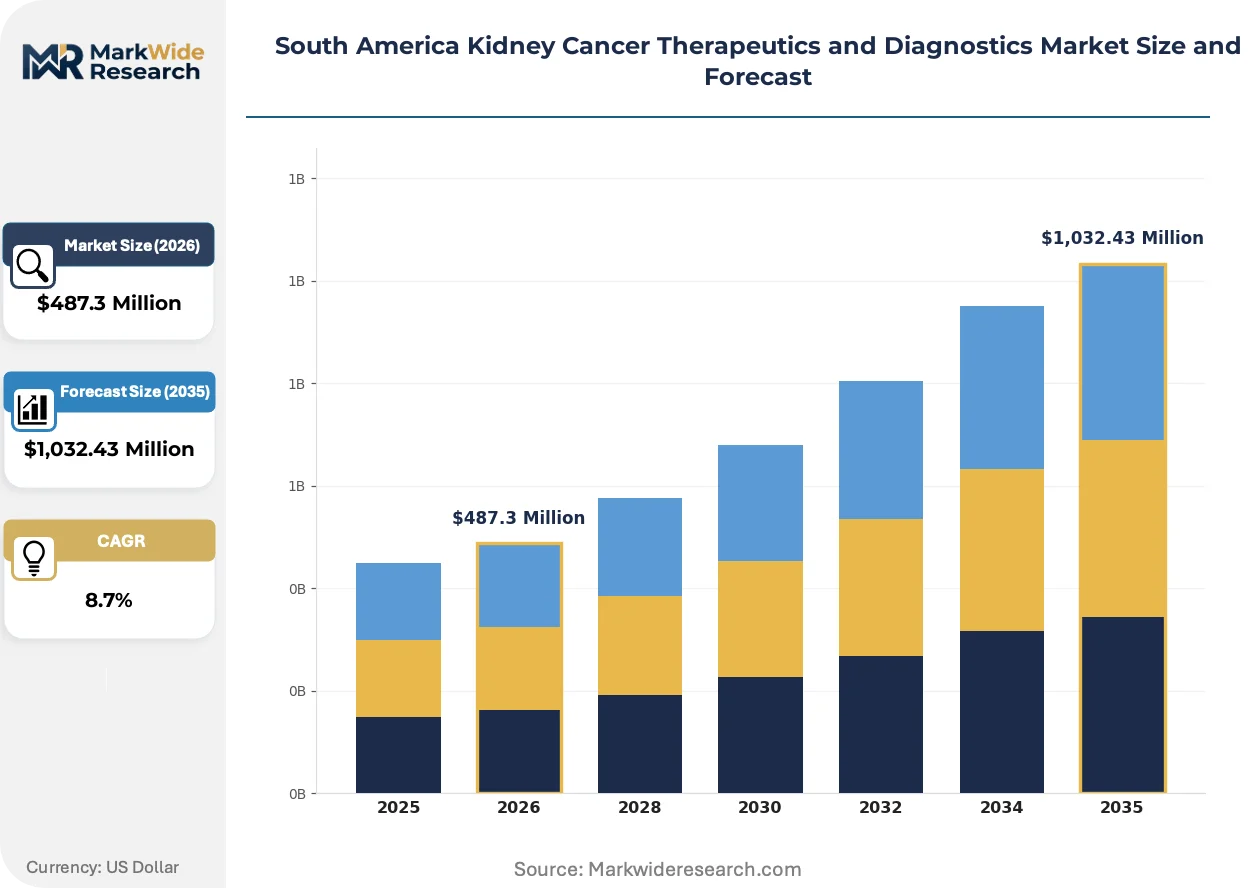
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy End User: Hospitals, Clinics, Research Laboratories, Homecare Providers Technology: Biomarkers, Imaging Techniques, Genomic Sequencing, Liquid Biopsy Delivery Mode: Intravenous, Oral, Injectable, Topical |
| Companies Covered | Eisai, Bayer, Bristol Myers Squibb, Amgen, Pfizer, Novartis International, F. Hoffmann-La Roche, Abbott Laboratories, Exelixis, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Kidney Cancer Therapeutics and Diagnostics Market Evolving Landscape
Precision medicine architectures are restructuring competitive advantage in renal oncology, with diagnostic-therapeutic convergence, regulatory pathway innovation, and care delivery decentralization emerging as dominant forces reshaping stakeholder positioning across the Southern Cone.
Next-generation sequencing panels for renal cell carcinoma molecular profiling are virtualizing tissue-based diagnostic workflows, enabling comprehensive mutational analysis from minimal sample inputs. Tertiary oncology departments in Brazil and Argentina are adopting these platforms at accelerated cadences to support clinical trial enrollment and off-label access programs. This virtualization is compressing the interval between diagnosis and therapy initiation while reducing pathology laboratory infrastructure requirements.
ANVISA's updated pharmacovigilance framework for oncology biologics mandates enhanced post-market surveillance and risk management plans for novel immunotherapeutic agents. The regulation compels manufacturers to establish localized safety databases and regional investigator networks for signal detection. Brazil's public hospital procurement channels are most affected, with tender documentation now requiring demonstrated compliance infrastructure as a technical qualification criterion.
Hospital consortium tendering for renal oncology portfolios is consolidating previously fragmented purchasing across state and municipal health systems. Major public networks in São Paulo and Buenos Aires are displacing single-hospital contracting with multi-institutional agreements that demand volume commitments and outcome reporting. This concentration is most visible in Brazil's Sistema Único de Saúde, where regional health secretariats are aggregating demand to negotiate preferential access terms for checkpoint inhibitors and targeted therapies.
South America Kidney Cancer Therapeutics and Diagnostics Market Segmentation
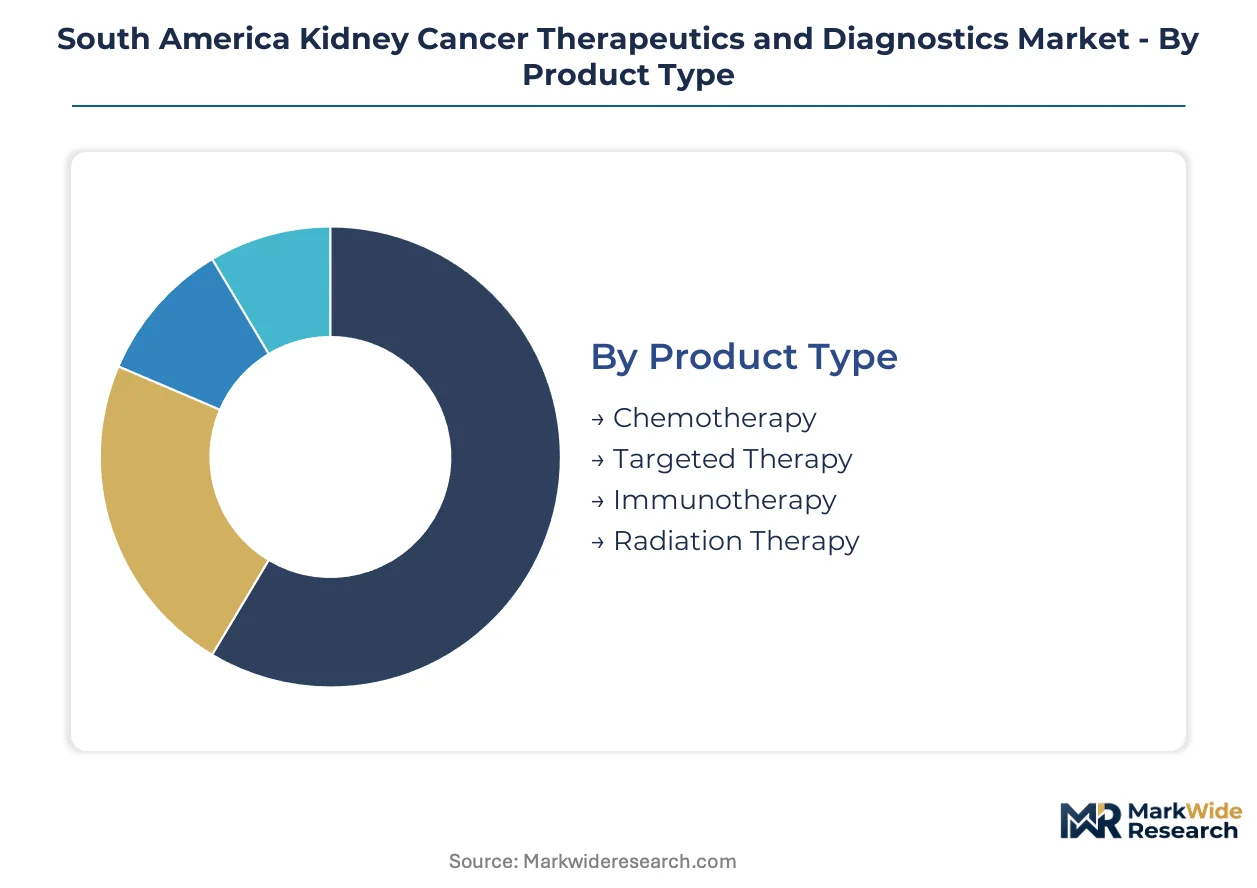
Renal oncology portfolios in South America fragment across therapeutic modalities, diagnostic technologies, and care delivery settings. Each dimension shapes procurement patterns, reimbursement pathways, and vendor competitive positioning differently across Brazil, Argentina, and Colombia.
Product Type:
Cost tier stratification separates established small-molecule regimens from premium biologic interventions, with reimbursement depth varying by public versus private channel access.
- Targeted Therapy:Tyrosine kinase inhibitors and mTOR inhibitors constitute the revenue foundation, with sunitinib and pazopanib securing preferential formulary placement through ANVISA's consolidated purchasing agreements. São Paulo's tertiary hospital networks concentrate demand for these oral agents.
- Immunotherapy:Checkpoint inhibitors command premium positioning within Brazil's Sistema Único de Saúde regional tendering, though access remains gated by biomarker eligibility criteria and cold-chain distribution capabilities. Buenos Aires private oncology centers drive adoption velocity.
- Chemotherapy:Cytotoxic regimens retain utility in sarcomatoid variant cases and combination protocols, particularly where targeted therapy resistance emerges.
- Radiation Therapy:Stereotactic ablative applications expand in metastatic oligoprogressive disease, limited by linear accelerator density outside metropolitan corridors.
Targeted therapy holds installed capacity. Immunotherapy is rotating up the share rankings.
End User:
Customer type determines procurement scale, clinical decision-making authority, and patient volume throughput for renal oncology interventions.
- Hospitals:Tertiary oncology departments anchor systemic therapy administration, molecular diagnostic processing, and multidisciplinary tumor board coordination. Brazil's public hospital consortiums aggregate purchasing power across state health secretariats.
- Homecare Providers:Specialized infusion networks and oral therapy management services address hospital capacity constraints and patient convenience preferences, expanding most quickly in São Paulo-Rio de Janeiro corridor.
- Clinics:Private oncology day centers handle stable patient monitoring and adverse event management, particularly in Argentina's prepaid medicine sector.
- Research Laboratories:Academic medical centers and contract research organizations execute biomarker validation and clinical trial enrollment, concentrated in Bogotá and Santiago.
Hospitals dominate transaction volume. Homecare providers are gaining share fastest.
Technology:
Maturity gradients separate established imaging modalities from emerging molecular profiling platforms, with infrastructure investment requirements shaping geographic penetration.
- Liquid Biopsy:Circulating tumor DNA analysis eliminates repeat tissue sampling burdens, enabling real-time resistance monitoring in fragmented healthcare systems. Colombian regional hospitals are adopting platforms to bypass pathology infrastructure gaps.
- Genomic Sequencing:Next-generation sequencing panels for renal cell carcinoma molecular profiling compress diagnostic-to-treatment intervals, though interpreter scarcity limits throughput expansion outside major metropolitan centers.
- Biomarkers:PD-L1 immunohistochemistry and VEGF pathway markers guide therapy selection, with assay standardization challenges across laboratory networks.
- Imaging Techniques:Contrast-enhanced CT and MRI remain staging workhorses, with PET-CT limited by cyclotron availability and reimbursement carve-outs.
Imaging techniques hold installed capacity. Liquid biopsy is climbing the fastest.
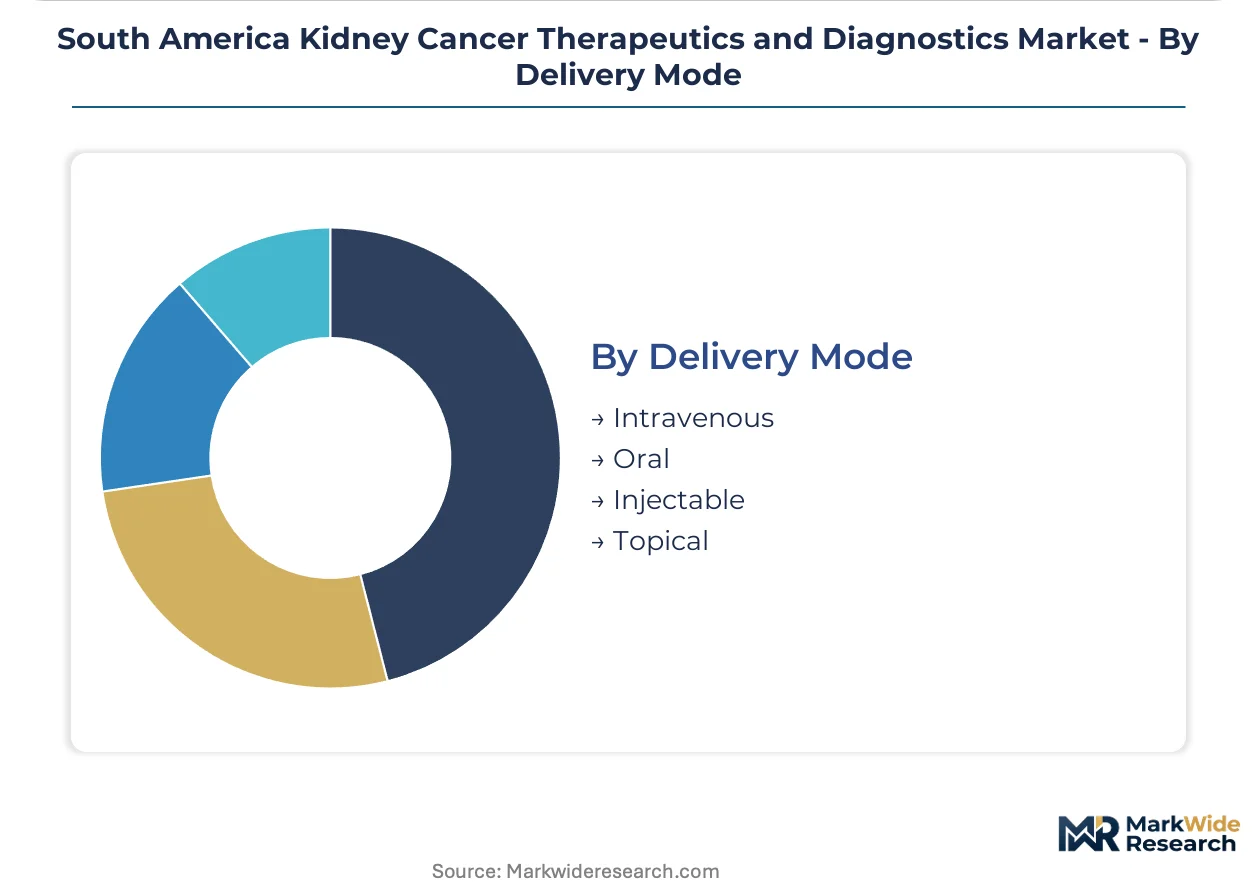
Delivery Mode:
Supply concentration patterns differentiate infusion-dependent biologics from self-administered oral agents, with logistics complexity determining channel economics.
- Oral:Tyrosine kinase inhibitor tablets enable decentralized administration through retail pharmacy networks and homecare programs, reducing hospital day-ward burden. Argentina's national oncology program references prices aggressively for this category.
- Intravenous:Checkpoint inhibitors and monoclonal antibodies require infusion center infrastructure, cold-chain integrity, and trained nursing staff, concentrating utilization in tertiary hospital networks.
- Injectable:Subcutaneous formulations of supportive care agents and selected biologics bridge convenience and clinical oversight requirements.
- Topical:Limited applicability in renal oncology, restricted to palliative skin lesion management in advanced disease presentations.
Intravenous delivery holds installed capacity. Oral administration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's fast-track oncology pathway and Argentina's national oncology program price mechanisms are redistributing procurement authority toward consolidated hospital networks across the Southern Cone. Brazil's São Paulo-Rio de Janeiro corridor concentrates private insurance-funded demand, while Colombia's regional hospitals bypass infrastructure gaps through novel diagnostic platforms.
Brazil
São Paulo's tertiary oncology departments drive demand for tyrosine kinase inhibitors and checkpoint inhibitors through consolidated Sistema Único de Saúde regional tendering. ANVISA mandates enhanced pharmacovigilance infrastructure as a technical qualification for public procurement participation. The São Paulo-Rio de Janeiro corridor clusters specialist referral networks where private insurance penetration enables premium therapeutic access.
Argentina
Buenos Aires private oncology centers anchor immunotherapy adoption velocity for renal cell carcinoma indications. The national oncology program establishes aggressive price reference mechanisms that compress commercial margins for oral agents. Metropolitan Buenos Aires concentrates prepaid medicine sector demand, with day centers handling stable patient monitoring and adverse event management.
Colombia
Regional hospitals outside Bogotá-Medellín adopt liquid biopsy platforms to circumvent pathology infrastructure limitations. INVIMA enforces import licensing and pharmacovigilance requirements that extend market entry timelines for novel biologics. The Bogotá-Medellín corridor anchors clinical trial enrollment and academic medical center biomarker validation capacity.
Chile
Santiago's academic medical centers concentrate next-generation sequencing interpretation and molecular diagnostic throughput for patient stratification. The country's national pharmaceutical regulator maintains alignment with ANVISA pharmacovigilance standards for regional consistency. The Santiago metropolitan region hosts contract research organization activity supporting renal oncology clinical development.
South America Kidney Cancer Therapeutics and Diagnostics Market Competitive Landscape
On the supply side, the industry is consolidating around integrated diagnostic-therapeutic bundling capabilities that satisfy centralized hospital procurement requirements. Three archetypes dominate: multinational biopharmaceuticals with immuno-oncology franchises, targeted therapy specialists with access program infrastructure, and diagnostic-platform vendors with biomarker partnerships. Competitive moves concentrate on diagnostic-treatment bundling and localized clinical data generation for regulatory compliance.
Among multinational biopharmaceuticals, Bristol Myers Squibb, Bayer, and Novartis International occupy positions that exemplify divergent strategic responses to procurement consolidation. Bristol Myers Squibb anchors relationships with major public hospital networks through its immuno-oncology portfolio. Bayer represents the targeted therapy access program archetype, navigating reimbursement complexity through sustained investment in patient support infrastructure. Novartis International sits within the diagnostic-treatment bundling tier, differentiating via imaging and biomarker partnerships that create integrated value propositions for tender environments.
| Leading Market Players |
|---|
| Eisai |
| Bayer |
| Bristol Myers Squibb |
| Amgen |
| Pfizer |
| Novartis International |
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| Exelixis |
| Others |
Value Network & Pricing Analysis
Undercapacity in Brazil's cold-chain distribution networks for oncology biologics concentrates pricing power among suppliers with proven ANVISA pharmacovigilance infrastructure, while Argentina's national oncology program price reference mechanisms compress margins for oral agents across the Southern Cone. This utilization asymmetry rewards integrated diagnostic-therapeutic bundling and penalizes standalone therapeutic vendors in consolidated tender environments.
Pricing Analysis
Volume-discount tiering structures dominate Brazil's Sistema Único de Saúde regional tendering, with multi-institutional agreements aggregating demand across state health secretariats to extract preferential access terms. Price differentiation rests on biomarker eligibility criteria and cold-chain certification levels, with checkpoint inhibitors commanding premium positioning against oral tyrosine kinase inhibitors. Cost compression in Argentina's oral agent category intensifies because national reference pricing anchors reimbursement to regional comparator markets. Public hospital consortiums exhibit highest price sensitivity, while São Paulo-Rio de Janeiro private insurance channels absorb premium therapeutic access with limited elasticity.
Supply Chain Analysis
Tariff exposure between Argentina and Brazil dominates supply chain risk planning for renal oncology portfolios, with import licensing friction at INVIMA and ANVISA extending inventory lead times for novel biologics. Manufacturing concentration centers on Switzerland, Germany, and the United States for active pharmaceutical ingredients, with formulation finishing distributed across regional licensed facilities. Raw material dependencies span recombinant protein production cell lines, monoclonal antibody purification resins, and diagnostic assay reagents. Single-source vulnerability in next-generation sequencing platform supply constrains diagnostic throughput expansion. Distribution runs through hospital consortium procurement channels with consolidated warehousing, displacing direct-to-hospital logistics for systemic therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's fast-track oncology pathway represents a regulatory inflection accelerating patient access velocity, positioning the market for high-growth disruption as molecular diagnostic capabilities expand beyond tertiary hospital networks. Precision-matched therapeutic selection is reshaping competitive advantage toward integrated diagnostic-therapeutic bundling.
For Market Incumbents: Entrench diagnostic-treatment bundling relationships with São Paulo and Buenos Aires public hospital networks before biosimilar pathway clarity emerges. Deepen vertical integration into liquid biopsy platform partnerships to anchor tender navigation capabilities. Prioritize ANVISA pharmacovigilance infrastructure investment as a technical qualification barrier against emerging entrants lacking localized safety databases. For New Entrants and Emerging Players: Build out Colombian regional hospital penetration outside the Bogotá-Medellín corridor, where pathology infrastructure gaps create addressable white space for blood-based monitoring technologies. Target homecare oral administration channels in Brazil's São Paulo-Rio de Janeiro corridor, where hospital capacity constraints favor decentralized delivery models. Pursue diagnostic-platform licensing agreements as the primary go-to-market angle to bypass established therapeutic vendor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic-platform vendors with biomarker partnerships and hospital system exclusive agreements. Long-term viability over the projection horizon favors archetypes with demonstrated ANVISA compliance infrastructure and regional investigator networks for signal detection. Monitor biosimilar pathway regulatory clarity as the critical inflection indicator for originator manufacturer portfolio repricing risk.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Treatment Bundling | Integrated value propositions satisfy consolidated hospital procurement technical qualification criteria in Brazil's Sistema Único de Saúde. |
| ANVISA Fast-Track Submission | Accelerated approval mechanisms reduce time-to-market for novel immunotherapeutic agents in renal cell carcinoma indications. |
| Liquid Biopsy Platform Partnership | Blood-based tumor monitoring bypasses pathology infrastructure gaps in Colombia's regional hospital networks. |
| Homecare Oral Administration Expansion | Specialized infusion networks address hospital capacity constraints in São Paulo-Rio de Janeiro corridor demand clusters. |
| Localized Clinical Data Generation | Regional comparator standards adaptation supports INVIMA import licensing and Argentina national oncology program price negotiations. |
Research Methodology
Initial hypotheses were tested against primary input from oncology drug development executives, ANVISA regulatory affairs leads, hospital procurement managers at Sistema Único de Saúde regional secretariats, and payer access specialists across Brazil, Argentina, and Colombia, then refined through secondary validation against ANVISA consolidated purchasing agreement documentation, INVIMA pharmacovigilance filings, Argentina national oncology program price reference databases, and clinical trial enrollment records from academic medical centers in Santiago and Bogotá. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Demand-supply-balance framing structured the analytical framework across the analysis window, with treatment line, administration route, biomarker eligibility status, and regional regulatory cluster dimensions modeled separately. CAGRs were derived from epidemiological incidence projections, therapy penetration curves, and pricing trajectory assumptions for targeted therapy and immunotherapy modalities. Forecast inputs incorporated ANVISA approval velocity, biosimilar pathway evolution uncertainty, and molecular diagnostic infrastructure expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive diagnostic-platform acquisition moves by multinational biopharmaceuticals or unexpected ANVISA regulatory tightening would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Blastomycosis Treatment Market