
 China Soy Beverages Market | 2026-2036
China Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
China Soy Beverages Market Outlook
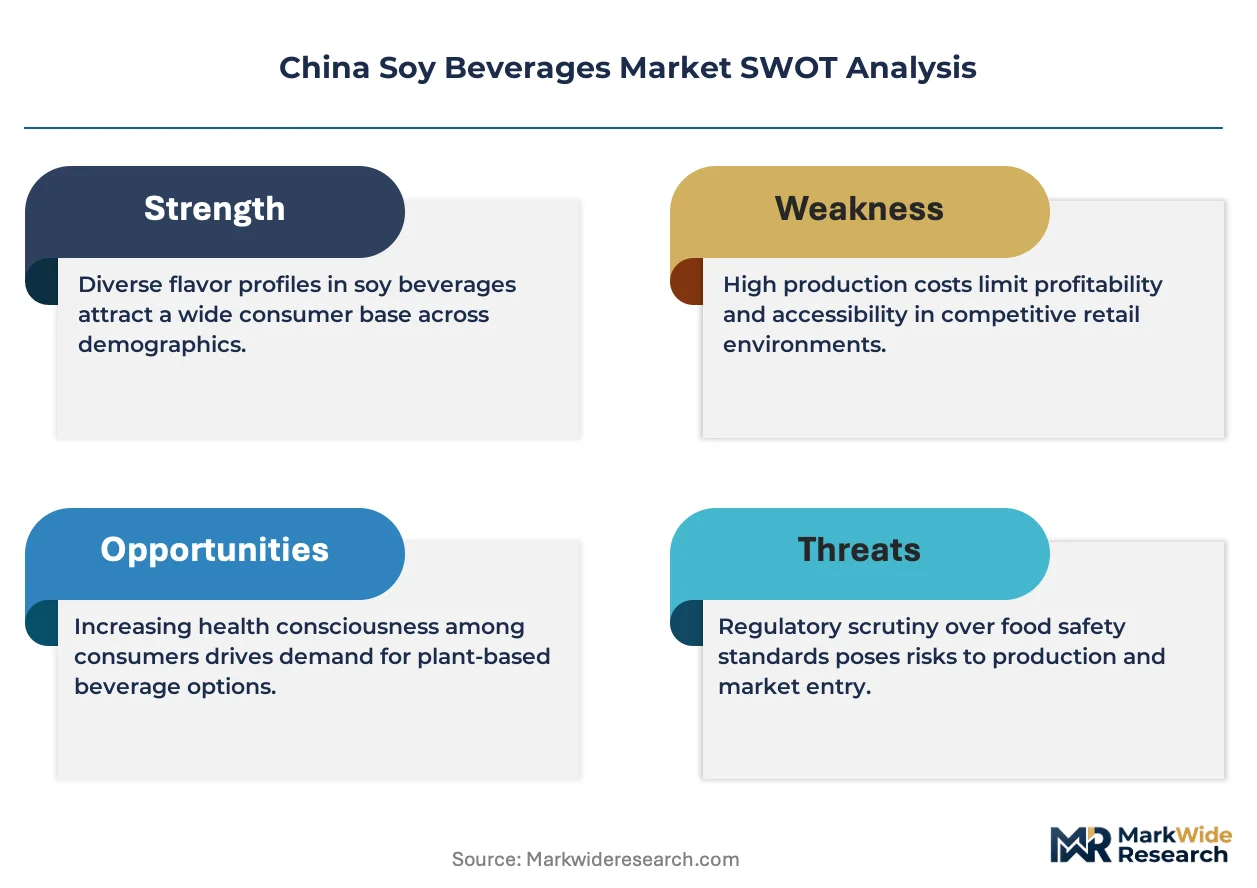
GB standards on plant-based protein labeling is pivoting the cost-of-entry calculus for new entrants, forcing reformulation investments before factory approval. Dali Foods leverages its Fujian manufacturing base to sustain cost advantages across flavored soy milk lines. Vitasoy International Holdings Ltd anchors premium positioning through Hong Kong-originated brand equity that still dominates southern Chinese retail. Danone SA competes via specialized probiotic soy yogurt formats that navigate China's dairy-alternative regulatory gray zones.
Soy beverages comprise aqueous extracts of whole soybeans or soy protein isolates, typically containing 2.5–4.0% protein by weight, processed through soaking, grinding, heat treatment, and homogenization to deliver functional nutrition and lactose-free hydration. Plain soy milk occupies the mature volume base, though margin pools concentrate in soy yogurt where probiotic positioning commands shelf-price premiums. Flavored soy milk segments are accelerating fastest as younger consumers in Chengdu and Hangzhou shift from carbonated soft drinks toward protein-fortified refreshments. Tetra Pak packaging dominates ambient distribution, while bottled formats capture refrigerated convenience-store turnover in high-traffic urban corridors.
SAMR enforces GB 7718 nutrition labeling and GB 28050 health claims standards that constrain how manufacturers position protein content and functional benefits. The National Health Commission's dietary guidelines for Chinese residents explicitly elevate soy consumption, indirectly steering institutional procurement in school and workplace canteen channels. Stakeholders must monitor whether MEE extends carbon-accounting requirements to agricultural processing, as soybean crushing and beverage sterilization carry embedded energy costs that could reshape plant location decisions.
Market Dynamics
GB standards on plant-based protein labeling is forcing manufacturers to reconfigure formulation pipelines before factory approval, compressing the cost-of-entry calculus for new entrants and accelerating consolidation among mid-tier processors.
Growth Catalysts
- Protein-fortification protocols:Health-conscious consumers in Shanghai and Beijing are expanding purchases of protein-fortified soy drinks, creating volume pull-through in premium retail channels.
- National Health Commission guidelines:Updated dietary guidelines for Chinese residents explicitly elevate soy consumption, indirectly steering institutional procurement in school and workplace canteen channels.
- Dual carbon targets:MEE's carbon-accounting trajectory for agricultural processing is incentivizing energy-efficient sterilization retrofits that reduce embedded emissions in soybean crushing operations.
Market Restraints
- Input cost volatility:Soybean crushing margins fluctuate with international commodity futures, squeezing processors when oilseed prices spike without corresponding beverage price elasticity.
- Regulatory friction:SAMR's GB 28050 health claims standards constrain how manufacturers position protein content and functional benefits, limiting marketing differentiation.
- Substitution threat:Oat and almond milk alternatives are capturing refrigerated convenience-store shelf space in tier-one cities, fragmenting plant-based beverage loyalty.
Strategic Opportunities
- Underpenetrated western provinces:Chengdu and Hangzhou are accelerating flavored soy milk adoption as younger consumers shift from carbonated soft drinks toward protein-fortified refreshments.
- Probiotic positioning:Soy yogurt formats navigate China's dairy-alternative regulatory gray zones, commanding shelf-price premiums through functional gut-health claims.
- Tetra Pak ambient distribution:Aseptic packaging technology is unifying extended shelf-life logistics with rural penetration, opening lower-tier city distribution without cold-chain infrastructure.
Industry Challenges
- Reformulation capex intensity:Cleaner ingredient decks required by GB 7718 nutrition labeling rules demand pre-approval capital outlays that strain mid-tier manufacturers.
- Certification timeline compression:SAMR factory approval protocols for modified protein extraction processes are extending time-to-market for novel soy isolate formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Soy Beverages Market |
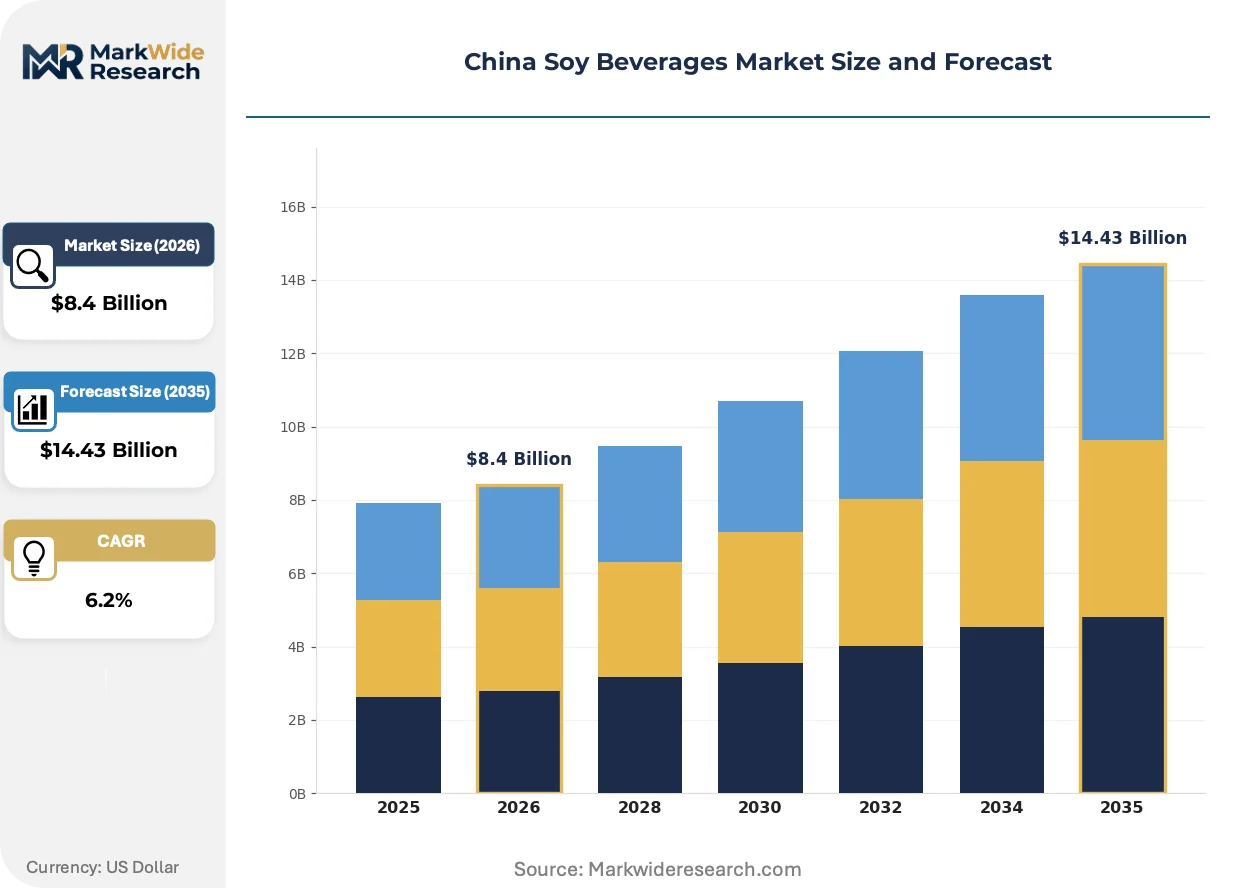
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Soy Milk, Flavored Soy Milk, Soy Protein Drink, Soy Yogurt Packaging Type: Tetra Pak, Bottled, Can, Carton Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores Target Consumer: Health-Conscious Consumers, Vegetarians, Vegans, Lactose-Intolerant Individuals |
| Companies Covered | Vitasoy International Holdings Ltd, Dali Foods, Danone SA, Kikkoman Pearl Soy Milk, The Hain Celestial Group, Guangxi Liudianban Bean Products Co., Ltd., Organic Valley, VinaSoy, Alpro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Soy Beverages Market Strategic Shifts
Aseptic processing and probiotic fortification are actively reshaping competitive positioning in China's soy beverage sector, compressing the gap between ambient distribution reach and refrigerated premium positioning.
Membrane filtration technology is unifying protein concentration efficiency with flavor profile stability in soy milk processing. Tier-one manufacturers are adopting ceramic microfiltration systems at scale, replacing traditional heat-precipitation methods. This convergence is enabling higher protein retention without the beany off-notes that previously limited consumer acceptance in premium segments.
SAMR's enforcement of GB 7718 nutrition labeling standards is constraining front-of-pack protein claims and forcing reformulation transparency. Manufacturers must now substantiate functional benefit assertions through clinical dossiers or remove them entirely. The flavored soy milk segment is responding with simplified ingredient decks that emphasize recognizable components over technical isolates.
Younger consumers in Chengdu and Hangzhou are displacing carbonated soft drink purchases with protein-fortified soy refreshments, rotating demand toward functional hydration. Convenience-store chains are expanding refrigerated bottled formats in high-traffic urban corridors, capturing impulse turnover that ambient Tetra Pak cannot access. This channel bifurcation is most visible in tier-one city retail, where premium positioning now requires dual-format availability.
China Soy Beverages Market Segmentation
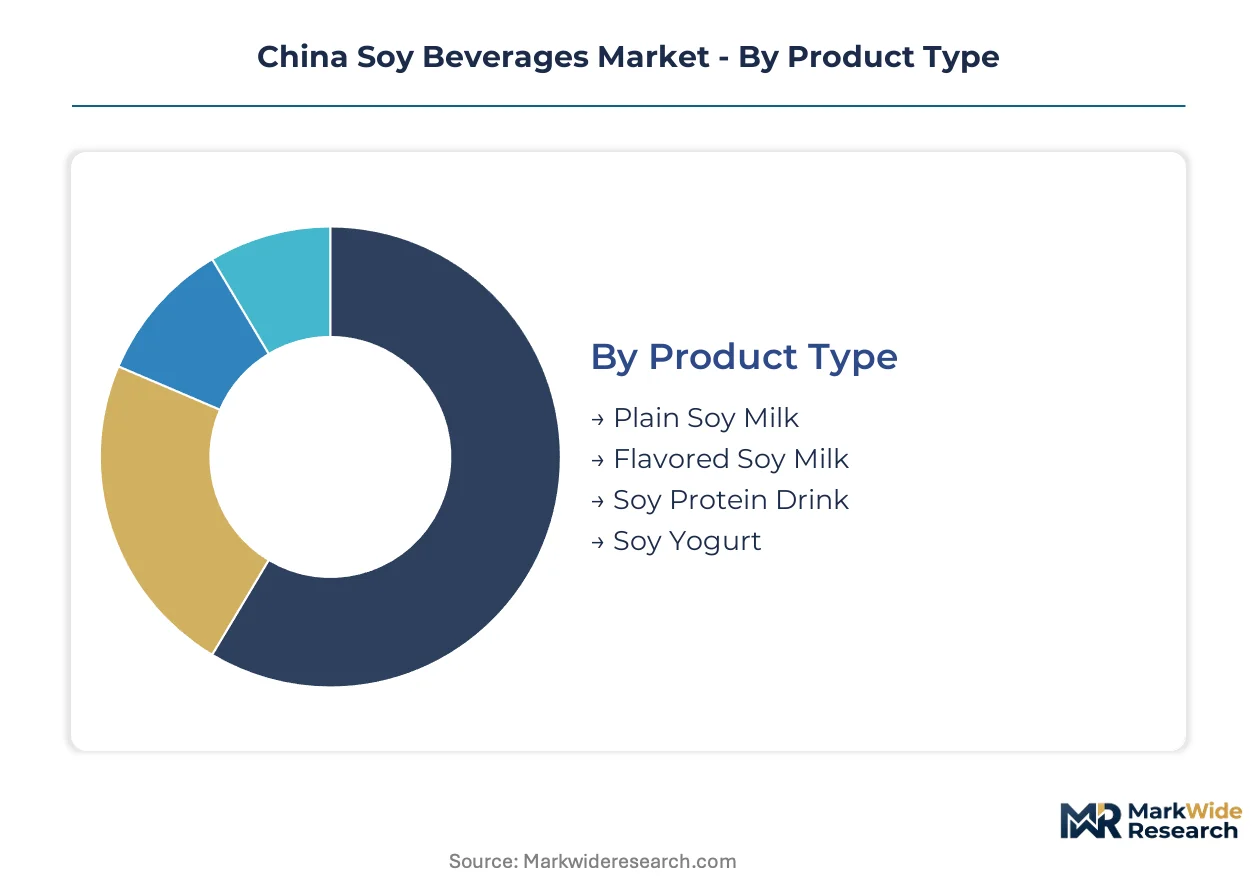
China's soy beverage market fragments across four distinct category axes that determine pricing power, channel access, and regulatory exposure. Each segmentation layer reveals divergent margin structures and growth velocities that manufacturers must navigate simultaneously.
Product Type:
Consumer protein-intensity requirements and functional benefit expectations separate buyers across this dimension.
- Plain Soy Milk:Aqueous soybean extract containing 2.5–3.5% protein by weight, processed through soaking, grinding, and heat treatment without flavor additives. Volume concentrates in institutional procurement channels across Shanghai and Beijing school canteens, driven by National Health Commission dietary guidelines elevating baseline soy consumption.
- Soy Yogurt:Fermented soy-based formulations with probiotic cultures that navigate China's dairy-alternative regulatory gray zones. Demand clusters in tier-one city supermarkets where functional gut-health claims command shelf-price premiums from health-conscious urban professionals.
- Flavored Soy Milk:Protein-fortified variants with fruit, chocolate, or grain additions targeting younger consumers in Chengdu and Hangzhou shifting from carbonated soft drinks.
- Soy Protein Drink:Isolated soy protein concentrates above 4.0% by weight, positioned for athletic and clinical nutrition applications.
Plain soy milk leads volumes today; soy yogurt is gaining share fastest.
Packaging Type:
Cold-chain infrastructure availability and shelf-life requirements dictate format selection across China's urban-rural divide.
- Tetra Pak:Aseptic laminated carton systems enabling 6–12 month ambient shelf stability without refrigeration. Dominates western province distribution where cold-chain infrastructure remains underdeveloped, unifying extended logistics reach with rural penetration.
- Bottled:PET and glass formats capturing refrigerated convenience-store turnover in high-traffic urban corridors of Beijing, Shanghai, and Shenzhen. Premium positioning requires dual-format availability in tier-one retail.
- Can:Metal packaging for single-serve consumption occasions and outdoor vending channels.
- Carton:Non-aseptic gable-top formats for short-shelf-life refrigerated distribution.
Tetra Pak dominates rural distribution; bottled formats are climbing the fastest in tier-one cities.
Distribution Channel:
Consumer purchase urgency and information-seeking behavior separate channel preferences across demographic cohorts.
- Supermarkets:Primary venue for planned category purchases and family-stock-up occasions, anchoring premium soy yogurt and flavored variant visibility through dedicated shelf space in Shanghai and Beijing.
- Online Retail:E-commerce platforms capturing subscription-based repeat purchases and bulk procurement for health-conscious consumers seeking detailed ingredient transparency.
- Convenience Stores:Impulse-driven refrigerated bottled format turnover in high-traffic urban corridors.
- Health Stores:Specialized retail channels for clinical nutrition and protein-fortified positioning.
Supermarkets anchor volume today; online retail shows steepest expansion trajectory.
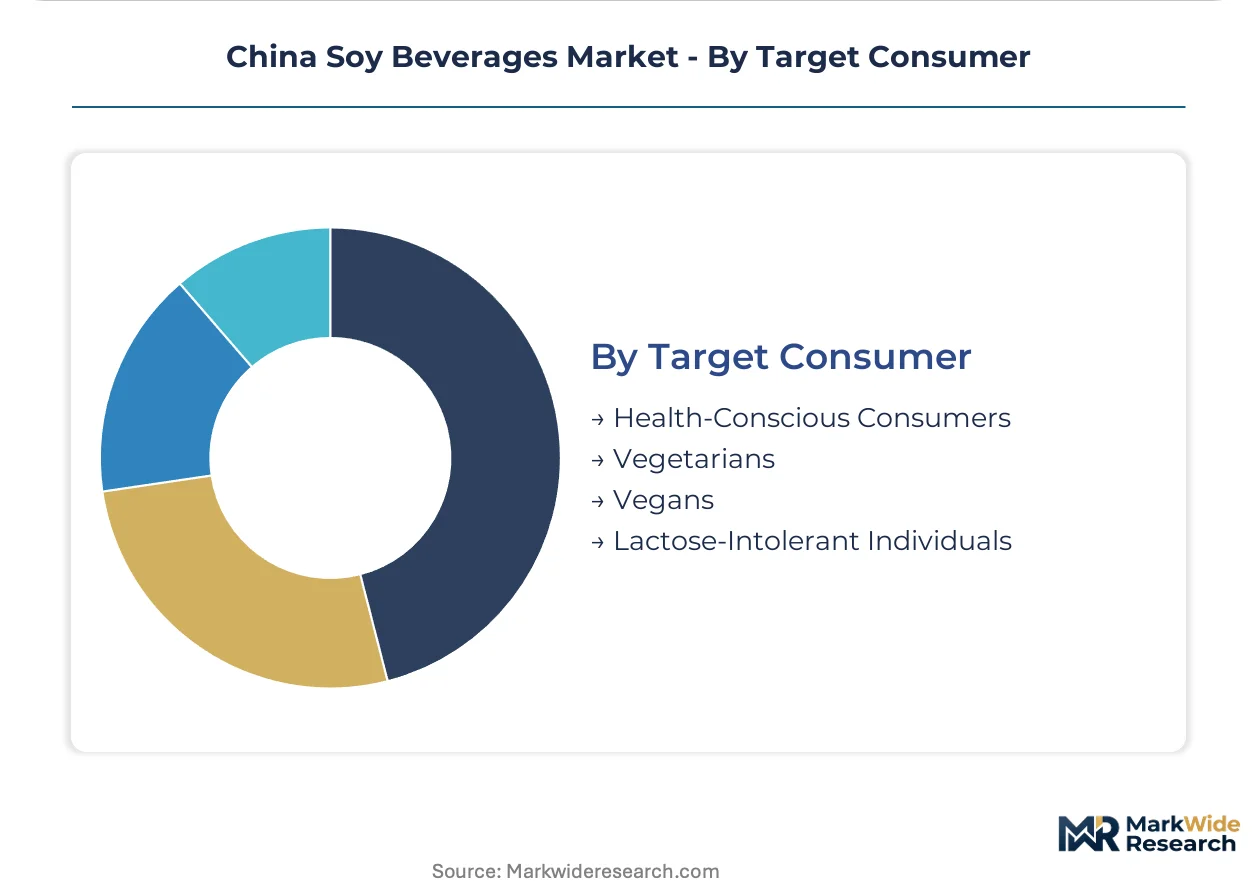
Target Consumer:
Dietary restriction severity and health motivation intensity define distinct buyer personas with divergent price elasticity.
- Health-Conscious Consumers:Protein-seeking urban professionals without strict dietary exclusions, driving flavored soy milk acceleration in Chengdu and Hangzhou as carbonated drink displacement accelerates.
- Lactose-Intolerant Individuals:Medically motivated buyers requiring dairy alternatives, concentrated in southern Chinese provinces with higher diagnosed prevalence rates.
- Vegetarians:Ethically motivated consumers seeking complete protein sources within plant-based dietary frameworks.
- Vegans:Strictest dietary cohort demanding certified animal-product-free supply chains and ingredient verification.
Health-conscious consumers lead volumes today; lactose-intolerant individuals are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soy beverage industrialization traces to early twentieth-century East Asian fermentation traditions, with commercial scaling accelerating through post-war Japan and subsequently China's reform-era food processing expansion. Contemporary production geography reflects this lineage, concentrating in coastal manufacturing belts with soybean crushing infrastructure and cold-chain logistics maturity.
Shanghai
Protein-fortified soy drink demand from health-conscious professionals drives premium retail channel expansion across Pudong and Puxi supermarket networks. SAMR's GB 28050 enforcement constrains front-of-pack health claims, forcing manufacturers toward substantiated clinical dossiers. The Yangshan port corridor anchors imported soybean intake for crushing facilities supplying beverage processors.
Beijing
Institutional procurement through school and workplace canteens concentrates volume under National Health Commission dietary guidelines elevating baseline soy consumption. GB 7718 nutrition labeling mandates cleaner ingredient deck transparency from processors seeking factory approval. The Daxing logistics cluster supports Tetra Pak ambient distribution reaching northern provincial markets.
Guangdong Province
Hong Kong-originated brand equity sustains premium positioning across Pearl River Delta retail, with probiotic soy yogurt formats commanding shelf-price premiums. Dual carbon targets from MEE incentivize energy-efficient sterilization retrofits at Dongguan and Shenzhen processing plants. The Nansha free trade zone facilitates soybean import duty optimization for crushing operations.
Sichuan-Chongqing
Younger consumers in Chengdu accelerate flavored soy milk adoption as carbonated soft drink displacement intensifies. Provincial health bureau procurement guidelines mirror national soy elevation directives in institutional feeding programs. Chongqing's Jiangjin district hosts emerging beverage processing capacity targeting western China distribution without cold-chain dependency.
Zhejiang Province
Hangzhou's tech-sector workforce drives protein-fortified refreshment demand through convenience-store refrigerated bottled formats. SAMR factory approval timelines for modified protein extraction processes extend time-to-market for novel formulations. The Ningbo-Zhoushan port complex ranks among China's largest soybean import gateways, securing crush margin advantages for regional processors.
China Soy Beverages Market Competitive Environment
The competitive structure tilts toward diversified food conglomerates with crushing-to-beverage integration capabilities. Mid-tier processors face consolidation pressure from GB standards compliance costs, while premium positioning requires Hong Kong or European brand equity anchoring. Three archetypes dominate: integrated soybean crushers with beverage diversification, Hong Kong-originated brand licensors leveraging southern China retail relationships, and multinational dairy-alternative specialists navigating regulatory gray zones. Capacity expansion and strategic partnerships represent the dominant competitive moves, with reformulation investments preceding factory approval protocols.
Within the Hong Kong-originated premium tier, Vitasoy International Holdings Ltd exemplifies brand equity translation across southern Chinese retail channels. Among diversified Chinese food conglomerates, Dali Foods occupies a position representing integrated manufacturing base cost advantages. Danone SA sits within the multinational specialist archetype, navigating China's dairy-alternative regulatory frameworks through probiotic format expertise. These three anchors illustrate the geographic and strategic segmentation binding competitive positioning to regulatory navigation capability.
| Leading Market Players |
|---|
| Vitasoy International Holdings Ltd |
| Dali Foods |
| Danone SA |
| Kikkoman Pearl Soy Milk |
| The Hain Celestial Group |
| Guangxi Liudianban Bean Products Co., Ltd. |
| Organic Valley |
| VinaSoy |
| Alpro |
| Others |
Value Chain & Pricing Dynamics
Dalian Commodity Exchange soybean futures pricing cascades through China's soy beverage value chain, compressing crush margins at processing plants and forcing tiered pricing stratification across premium probiotic formats, standard flavored variants, and economy plain milk lines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates China's soy beverage market, with probiotic soy yogurt commanding shelf premiums through functional positioning while plain soy milk competes on volume scale. Price differentiation hinges on protein concentration certification and cold-chain delivery infrastructure, with refrigerated bottled formats carrying 15-25% premiums over ambient Tetra Pak equivalents. Pricing pressure stems from international oilseed volatility transmitting directly into crush margin compression, squeezing mid-tier processors unable to pass through input costs. Institutional buyers in Beijing school canteens exhibit highest price sensitivity, while health-conscious professionals in Shanghai absorb premium tier markups with minimal elasticity.
Supply Chain Analysis
Soybean supply rests on crushing capacity concentrated in Brazil, Argentina, and the United States, with Chinese processors drawing from Ningbo-Zhoushan and Yangshan port corridors to feed Dongguan and Jiangjin beverage plants. Raw material dependencies center on imported GMO and non-GMO soybean grades, aseptic packaging laminates from Tetra Pak suppliers, and probiotic culture strains from European biotechnology specialists. Single-source vulnerability in aseptic carton supply creates bottleneck exposure for ambient distribution expansion. Distribution runs through supermarket chains anchoring planned purchases, convenience stores capturing impulse refrigerated turnover, and e-commerce platforms handling subscription-based bulk procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's soy beverage market offers margin expansion through membrane filtration technology adoption reducing heat-treatment energy costs and probiotic format premiums capturing health-motivated buyer willingness-to-pay.
For Market Incumbents: To counter oat and almond milk substitution threats in tier-one convenience stores, Dali Foods and Vitasoy should deepen backward integration into Fujian and Pearl River Delta crushing assets while accelerating GB 28050-compliant clinical dossier investments to defend functional claim positioning against regulatory tightening. For New Entrants and Emerging Players: Rural health-conscious consumers in Sichuan-Chongqing and western provinces represent the most penetrable buyer archetype, with flavored soy milk displacement of carbonated soft drinks creating white-space opportunity through Tetra Pak ambient distribution partnerships bypassing cold-chain infrastructure gaps. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier processors face GB standards compliance cost burdens exceeding capital access, positioning integrated crushers with beverage diversification as viable acquisition targets. Watch MEE carbon-accounting extension to agricultural processing as the signal indicating plant location advantage shifts and stranded asset risk concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Microfiltration Scale-Up | Membrane filtration retrofits enable higher protein retention without beany off-notes in premium segments. |
| Probiotic Clinical Dossier Investment | GB 28050 compliance substantiates gut-health claims commanding supermarket shelf-price premiums. |
| Western Province Distribution Partnership | Tetra Pak ambient logistics unlock Chengdu and Chongqing penetration without cold-chain dependency. |
| Energy-Efficient Sterilization Retrofit | Dual carbon target alignment reduces embedded emissions exposure at Dongguan processing plants. |
| Direct E-Commerce Subscription Launch | Online platforms capture bulk procurement from ingredient-transparency-seeking health-conscious consumers. |
Study Parameters
Coverage spans Shanghai, Beijing, Guangdong, Sichuan-Chongqing, and Zhejiang, with primary inputs from each region combining interviews with beverage plant managers, supermarket category buyers, SAMR regulatory affairs specialists, and soybean procurement leads at crushing facilities. Secondary validation draws from GB standards documentation, National Health Commission dietary guideline releases, MEE environmental policy circulars, and customs import data through Ningbo-Zhoushan and Yangshan port authorities. Bottom-up volume modeling triangulates against top-down value estimates from retail audit channels.
Rate-of-change decomposition across the analysis window segments growth by product type, packaging format, distribution channel, and target consumer archetype, with CAGRs derived from historical trajectory analysis and elasticity-adjusted demand projections. Forecast inputs incorporate membrane filtration adoption curves, probiotic format penetration rates, and GB standards enforcement timelines affecting factory approval protocols.
Underlying measurement precision varies by segment; plain soy milk institutional procurement carries tighter precision than emerging probiotic yogurt adoption. Forecasts reflect documented assumptions on regulatory enforcement intensity and commodity price transmission mechanisms. Policy shifts in MEE carbon-accounting scope and SAMR health claims interpretation warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Japan Kombucha Market
Beverages
Apple Juice Concentrate Market
Beverages
Sparkling Bottled Water Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Foaming Creamer Market
Beverages
Packaged Coconut Water Market
Beverages
Peanut Oil Market
Beverages
NFC JUICE Market
Beverages
Drinking Water Market
Beverages
GCC Fruit Juice Market
Beverages
Kvass Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Crystal Boba Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Gluten Free Beverages Market
Beverages
Blenders Market