
 Asia-Pacific Spring Water Market | 2026-2036
Asia-Pacific Spring Water Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Spring Water Market Insights
Corporate catering and hospitality procurement is expanding across the Asia-Pacific spring water sector as institutional buyers consolidate beverage contracts under single-source agreements. Nongfu Spring Co., Ltd. leverages its deep well network across Zhejiang and Hubei provinces to anchor supply security for national foodservice chains. Tata Consumer Products Limited competes through Himalayan source exclusivity that commands premium positioning in Indian hotels and airlines. Hangzhou Wahaha Group sustains manufacturing scale across dozens of bottling lines that service mass-market convenience channels.
Asia-Pacific spring water refers to naturally sourced groundwater emerging from subsurface geological formations with total dissolved solids typically below 500 ppm, requiring minimal treatment beyond filtration and UV sterilization before bottling. The product serves as a premium hydration alternative in commercial foodservice, residential consumption, and institutional catering where taste profiles and mineral composition influence repeat purchase. Natural spring water in PET and glass bottles dominates volume throughput across supermarket and convenience store channels, while sparkling variants capture accelerating interest in upscale restaurant and hotel minibar placements. Flavored spring water segments remain nascent in most Asia-Pacific markets but attract R&D investment as younger consumers in South Korea and Japan seek low-sugar alternatives.
Australia's TGA enforces strict therapeutic claims oversight for mineral water labeling, while China's NMPA and SAMR coordinate national food safety standards that mandate source traceability and periodic geological survey recertification for spring water extraction permits. Japan's Ministry of Health, Labour and Welfare maintains positive-list systems for allowable mineral additives that constrain product innovation timelines. Stakeholders must monitor evolving packaging regulations in Indonesia and Thailand that target single-use plastic reduction without compromising shelf stability in tropical distribution environments.
Market Dynamics
China's NMPA and SAMR coordinate stricter mineral-content labeling standards that force reformulation across extraction sites, while Australia's TGA therapeutic claims oversight compels geological recertification cycles that extend permit timelines.
Growth Catalysts
- Institutional procurement consolidation:Hotels and corporate campuses across Southeast Asia consolidate beverage contracts under single-source agreements that favor established spring water suppliers with certified extraction permits.
- China's SAMR traceability mandates:National food safety standards requiring source traceability and periodic geological survey recertification create competitive moats for operators with compliant well networks.
- Sparkling variant adoption:Upscale restaurant and hotel minibar placements accelerate demand for carbonated spring water variants that command price premiums over still formats in metropolitan foodservice channels.
Market Restraints
- PET resin input volatility:Crude oil-linked packaging material costs fluctuate with energy markets, compressing margin stability for volume producers dependent on single-use plastic formats.
- Extraction permit concentration:China's coastal megacities and India's urban corridors face limited licensed spring sites, creating supply bottlenecks as demand concentrates in these corridors.
- Japan's positive-list constraints:The Ministry of Health, Labour and Welfare's additive approval system extends product innovation timelines for mineral-enhanced variants seeking market entry.
Strategic Opportunities
- Flavored spring water white space:South Korea and Japan present underpenetrated demand for low-sugar flavored variants as younger consumers seek alternatives to conventional sweetened beverages.
- Glass bottle channel expansion:Premium hotel and airline segments create distribution openings for glass-packaged spring water that satisfies sustainability procurement criteria.
- Indonesia and Thailand packaging regulation tailwinds:Evolving single-use plastic reduction frameworks incentivize investment in alternative materials and refill infrastructure without compromising tropical shelf stability.
Industry Challenges
- Geological survey certification timelines:China's NMPA-mandated recertification cycles for extraction permits require sustained regulatory affairs capacity and documentation systems.
- Tropical distribution shelf stability:High-humidity supply chains in Southeast Asia demand packaging engineering expertise to prevent degradation during extended warehouse and transport exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Spring Water Market |
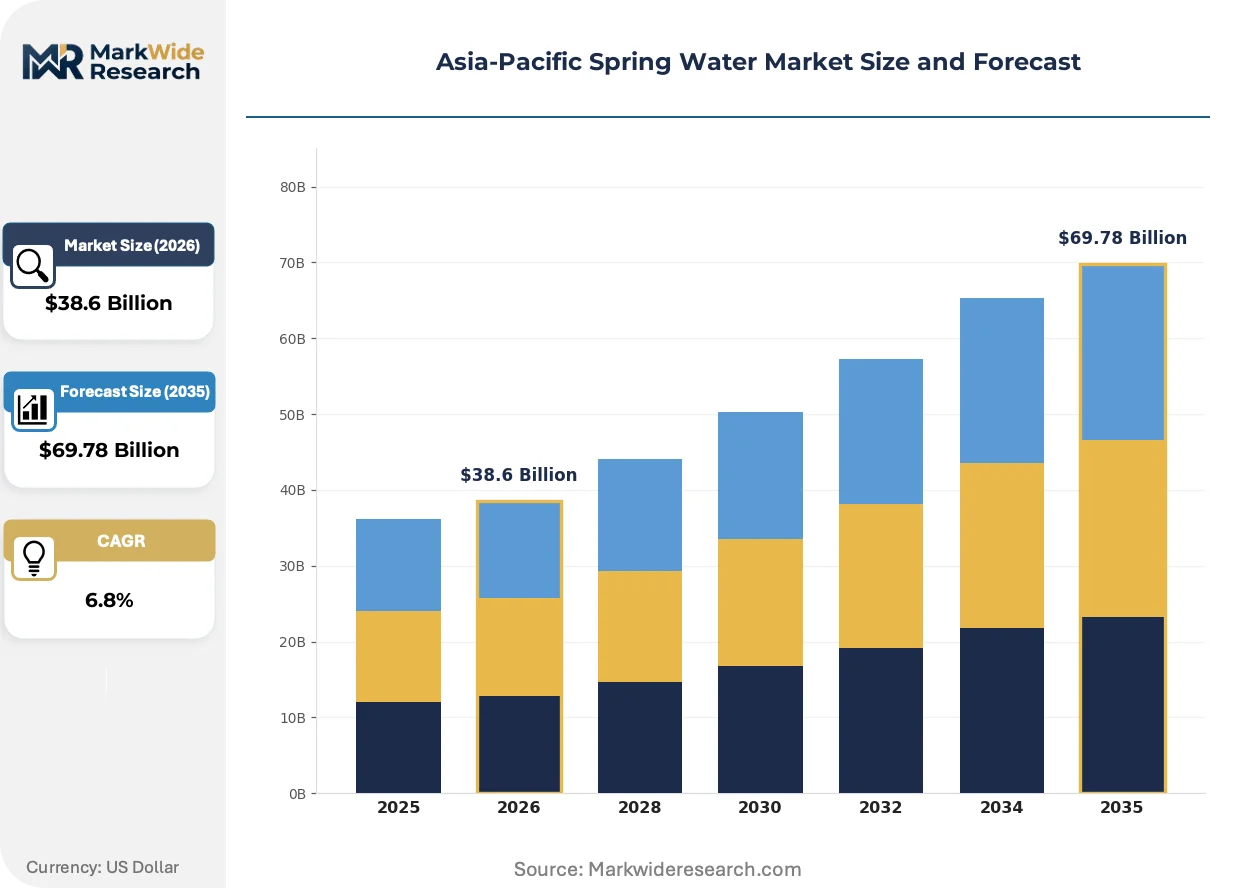
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Spring, Sparkling, Mineral, Flavored Packaging Type: Bottles, Cans, Pouches, Cartons Distribution Channel: Supermarkets, Convenience Stores, Online, Hotels End User: Households, Restaurants, Events, Corporate |
| Companies Covered | Hangzhou Wahaha Group, Asahi Group Holdings Ltd., Nongfu Spring Co., Ltd., Kirin Holdings Co., Ltd., Tibet Water Resources Ltd., Tata Consumer Products Limited, Bisleri International, Vitasoy International, Suntory Beverage & Food Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Spring Water Market Trends and Innovations
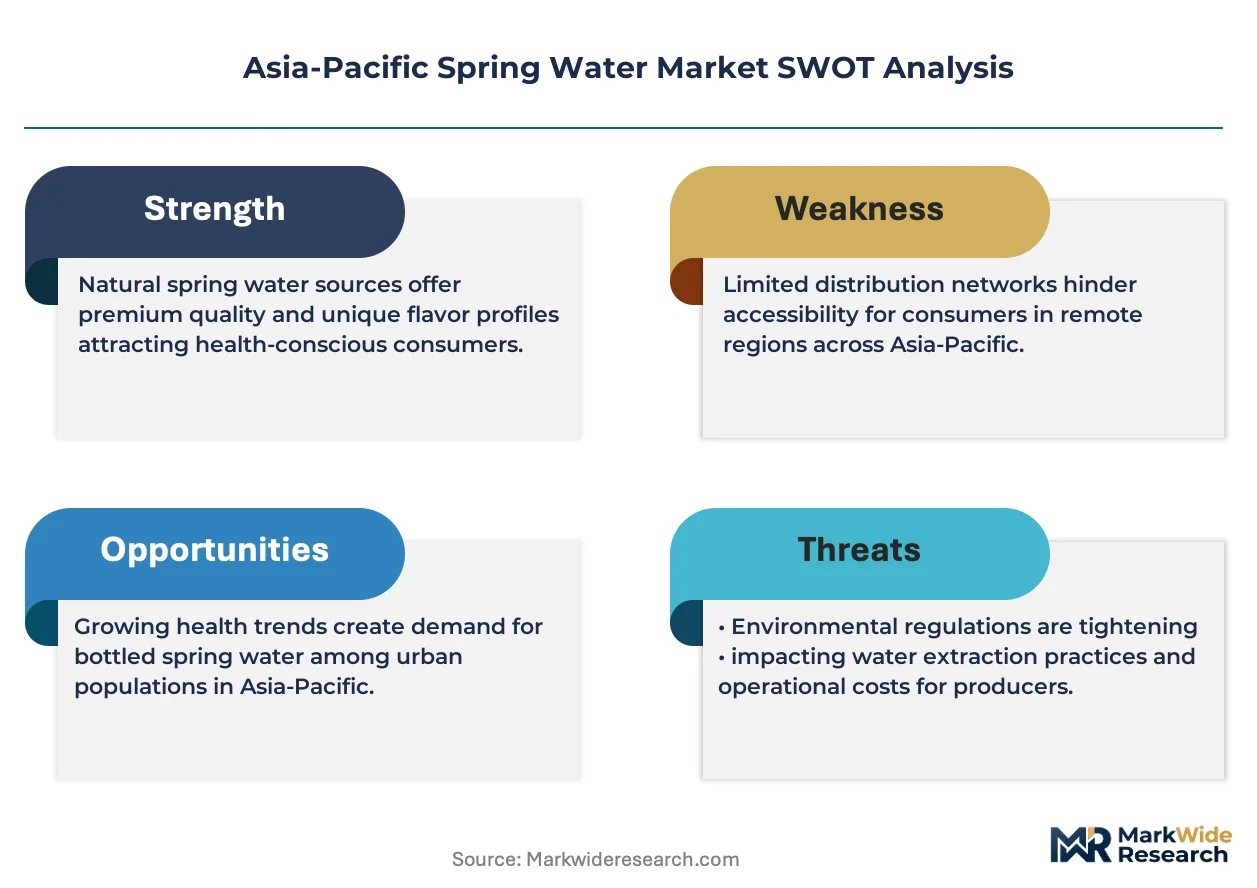
Asia-Pacific spring water markets confront simultaneous pressure from packaging material transitions, regulatory disclosure intensification, and procurement model restructuring that favors consolidated institutional buyers over fragmented retail channels.
Aseptic cold-filling technology is electrifying production economics across China's Zhejiang and Hubei bottling corridors. National foodservice chains adopt these systems to extend shelf life without thermal degradation of mineral profiles. The technology compresses capital recovery timelines for operators serving high-throughput convenience channels.
Australia's TGA therapeutic claims framework now requires evidentiary substantiation for mineral water health positioning statements. Bottlers must commission clinical or compositional studies to support labeling claims, extending product development cycles. Premium positioning strategies in Australian and New Zealand markets absorb compliance costs through price architecture adjustments.
Corporate catering contracts increasingly specify source-certified spring water with documented geological provenance. India's airline and hotel sectors displace unbranded bulk supplies with single-origin Himalayan products that satisfy procurement audit requirements. This specification tightening concentrates supplier relationships around operators with exclusive extraction rights.
Asia-Pacific Spring Water Market Segmentation
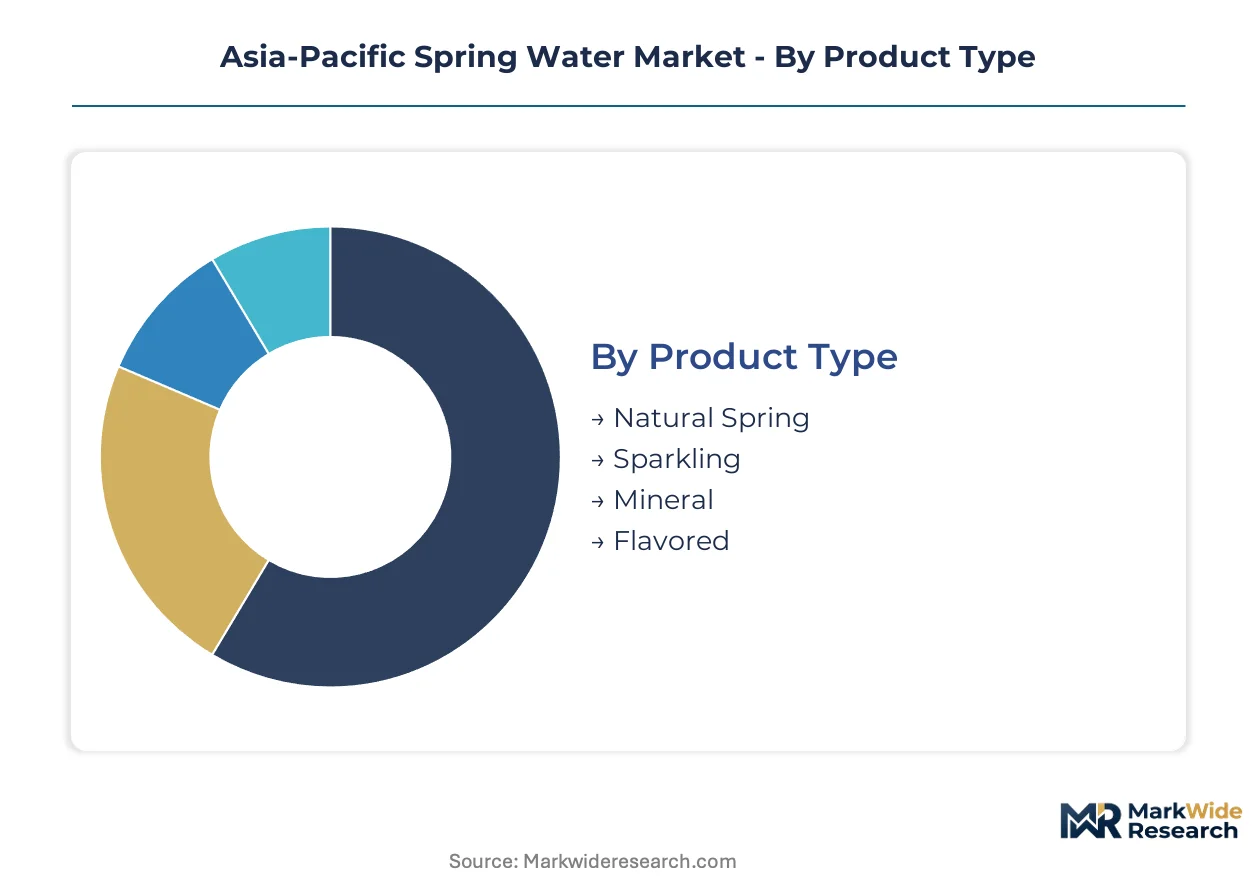
Asia-Pacific spring water segmentation reflects divergent buyer priorities across institutional procurement, retail convenience, and premium hospitality channels. Product formulation and packaging format decisions track closely to end-use specifications and distribution shelf-life requirements.
Product Type:
Buyers select product categories based on mineral composition specifications and carbonation preferences that align with consumption occasion and price tolerance.
- Natural Spring:Groundwater sourced from subsurface geological formations with total dissolved solids below 500 ppm requires only filtration and UV sterilization. Demand concentrates in China's coastal megacities where SAMR traceability mandates favor certified extraction sites with documented geological provenance.
- Sparkling:Carbonated variants command placement in upscale restaurant and hotel minibar channels across Southeast Asia. Thailand's hospitality procurement consolidation drives volume for premium sparkling formats that differentiate beverage programs.
- Mineral:Enhanced mineral content waters target therapeutic positioning under Australia's TGA oversight, requiring evidentiary substantiation for health claims.
- Flavored:Low-sugar variants attract R&D investment in South Korea and Japan as younger consumers seek alternatives to conventional sweetened beverages.
Volume sits with Natural Spring; growth tilts toward Sparkling.
Packaging Type:
Format selection hinges on shelf stability demands in tropical supply chains and sustainability procurement criteria in premium channels.
- Bottles:PET and glass formats dominate throughput across supermarket and convenience store networks. Indonesia and Thailand's evolving single-use plastic reduction frameworks incentivize alternative material investment without compromising distribution integrity.
- Cans:Aluminum formats gain traction in foodservice and event channels where portability and rapid chilling properties matter. Australia's corporate catering contracts increasingly specify recyclable can formats for outdoor hospitality applications.
- Pouches:Flexible packaging serves institutional bulk supply and airline catering where weight reduction drives logistics economics.
- Cartons:Paper-based formats capture interest in Japan's retail channels where shelf aesthetics and environmental positioning influence repeat purchase.
Bottles anchor current throughput; cans are climbing the fastest.
Distribution Channel:
Channel strategy reflects the tension between consolidated institutional contracts and fragmented retail replenishment economics.
- Supermarkets:High-volume replenishment of multi-pack PET formats serves residential stock-up behavior in India's urban corridors. Modern trade expansion across Southeast Asia concentrates procurement power with chains that demand certified source documentation.
- Convenience Stores:Chilled single-serve placement dominates impulse consumption in China's Zhejiang and Hubei provinces where Nongfu Spring maintains deep well network coverage.
- Online:Direct-to-subscription models emerge in South Korea and Japan for premium glass-bottle formats that justify delivery economics through higher per-unit value.
- Hotels:Minibar and banquet specifications tighten around single-source agreements with documented geological provenance, displacing unbranded bulk supplies across India and Southeast Asia.
Supermarkets hold volume concentration; hotels show the steepest expansion trajectory.
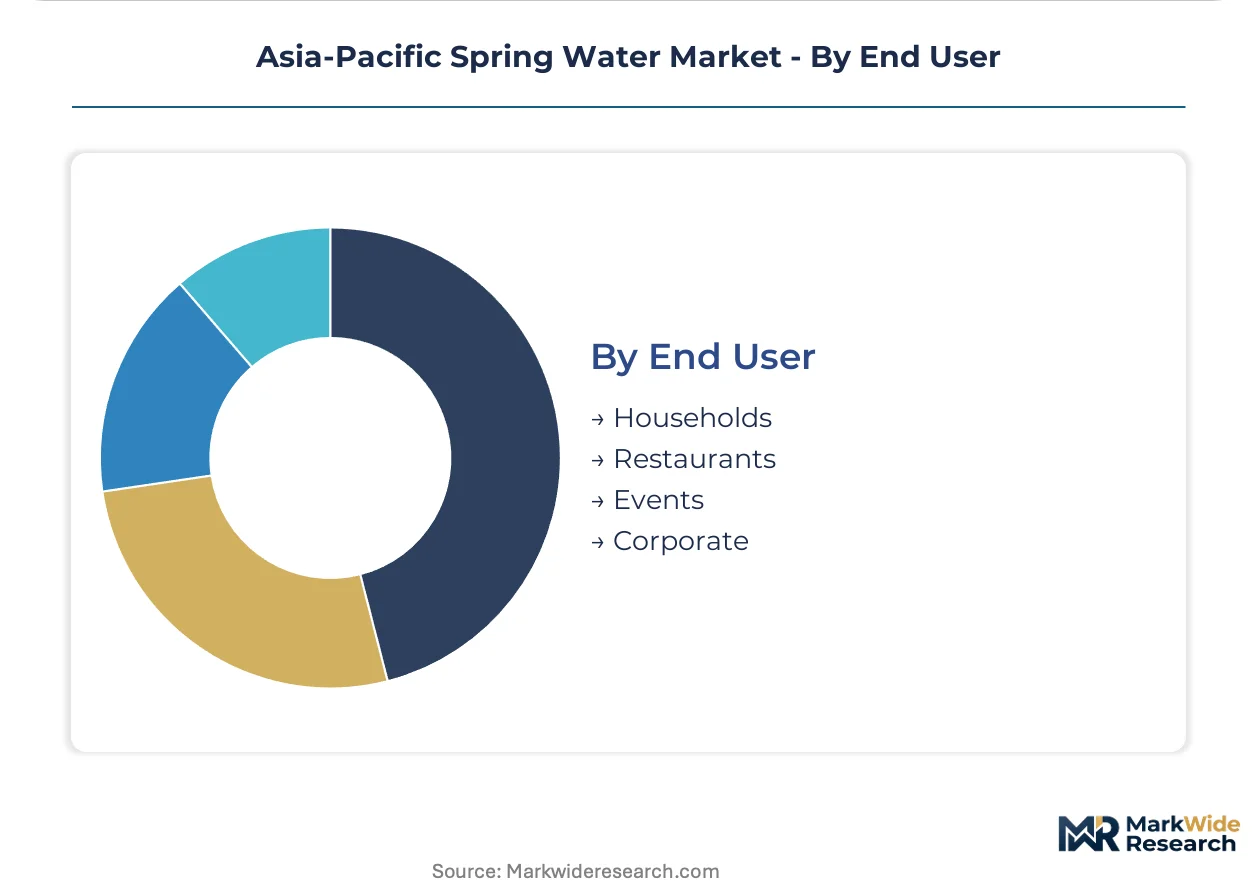
End User:
User category segmentation tracks procurement centralization trends and specification stringency in institutional versus residential demand.
- Households:Residential consumption clusters in China's coastal megacities and India's urban corridors where tap water quality concerns drive premium bottled water adoption.
- Restaurants:Foodservice procurement consolidates under national chain contracts that favor suppliers with compliant extraction permits and aseptic cold-filling capacity.
- Events:Temporary catering demand favors portable formats with rapid deployment logistics across Australia's outdoor hospitality sector.
- Corporate:Campus beverage contracts specify source-certified spring water with audit documentation, concentrating supplier relationships around operators with exclusive extraction rights in Himalayan and Zhejiang source regions.
Households represent the installed base; corporate procurement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's coastal megacities and India's urban corridors, where tap water quality concerns and institutional procurement consolidation drive premium spring water adoption across foodservice and residential channels.
China
Nongfu Spring leverages deep well networks across Zhejiang and Hubei provinces to supply national foodservice chains under NMPA traceability mandates. SAMR-coordinated national food safety standards require source traceability and periodic geological survey recertification for extraction permits. Shanghai and Guangzhou hospitality sectors specify single-source agreements with documented geological provenance for minibar and banquet placements.
India
Tata Consumer Products commands premium positioning through Himalayan source exclusivity in airline and hotel procurement channels. FSSAI labeling regulations enforce mineral-content disclosure standards that reshape product formulation and marketing claims. Mumbai and Delhi-NCR urban corridors face limited licensed spring sites, creating supply bottlenecks as residential demand accelerates.
Japan
Sparkling variant adoption accelerates in upscale Tokyo and Osaka restaurant channels where carbonated spring water commands price premiums. The Ministry of Health, Labour and Welfare maintains positive-list systems for allowable mineral additives that constrain product innovation timelines. Kanto region bottlers absorb compliance costs through price architecture adjustments for therapeutic positioning statements.
Australia
TGA therapeutic claims oversight requires evidentiary substantiation for mineral water health positioning, extending product development cycles. Sydney and Melbourne corporate catering contracts increasingly specify recyclable aluminum formats for outdoor hospitality applications. Bottlers commission clinical or compositional studies to support labeling claims, concentrating supplier relationships around compliant operators.
South Korea
Low-sugar flavored spring water segments attract R&D investment as younger consumers in Seoul seek alternatives to conventional sweetened beverages. MFDS food additive regulations govern permissible flavoring compounds and mineral enhancement protocols. Direct-to-subscription models emerge for premium glass-bottle formats that justify delivery economics through higher per-unit value.
Asia-Pacific Spring Water Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue flavored variants and sustainable packaging formats. The market exhibits moderate consolidation around operators with certified extraction permits and national distribution networks. Three archetypes dominate: scale-driven mass-market suppliers, source-exclusive premium-positioned specialists, and diversified beverage conglomerates with spring water portfolios. Competitive moves center on extraction permit acquisitions and aseptic cold-filling capacity expansion.
Among Chinese producers, Nongfu Spring Co., Ltd. and Hangzhou Wahaha Group exemplify scale-driven archetypes with extensive bottling infrastructure. Tata Consumer Products Limited represents the source-exclusive specialist model through Himalayan provenance positioning. Asahi Group Holdings Ltd. and Kirin Holdings Co., Ltd. sit within diversified beverage conglomerates leveraging cross-category distribution synergies.
| Leading Market Players |
|---|
| Hangzhou Wahaha Group |
| Asahi Group Holdings Ltd. |
| Nongfu Spring Co., Ltd. |
| Kirin Holdings Co., Ltd. |
| Tibet Water Resources Ltd. |
| Tata Consumer Products Limited |
| Bisleri International |
| Vitasoy International |
| Suntory Beverage & Food Ltd. |
| Others |
Pricing and Supply Chain Analysis
Corporate procurement consolidation across Southeast Asian hospitality chains forces supply response through certified extraction permit acquisition, compressing margin structures for uncertified operators while elevating price premiums for compliant source holders.
Pricing Analysis
Volume throughput concentrates in mass-market PET formats where Nongfu Spring and Hangzhou Wahaha compete on manufacturing scale, while margin capture shifts toward glass-packaged premium tiers serving airline and hotel procurement. Price differentiation hinges on geological provenance certification and SAMR traceability compliance, with Himalayan-sourced products commanding substantial premiums over Zhejiang corridor alternatives. Pricing pressure stems from crude oil-linked PET resin volatility that erodes stability for volume-dependent producers. Household segments in India's urban corridors exhibit highest price sensitivity, whereas corporate catering contracts in Australia and Japan absorb premiums for documented source credentials.
Supply Chain Analysis
Return flows for refillable glass formats gain traction in South Korea's subscription channels and Japan's retail networks, reducing per-use packaging intensity. Extraction concentrates in China's Zhejiang and Hubei provinces, India's Himalayan catchment, and Australia's protected aquifer zones. Raw material dependencies center on PET resin, aluminum can sheet, and glass cullet supply. Single-source vulnerability pervades the sector where exclusive extraction rights lock out competitors from premium source regions. Distribution runs through consolidated foodservice procurement networks that displace fragmented retail replenishment in high-value hospitality channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited licensed spring sites across China's coastal megacities and India's urban corridors constrain capacity expansion, propping pricing power for incumbent permit holders while intensifying acquisition premiums for extraction assets.
For Market Incumbents: To counter regulatory recertification burdens from China's NMPA-mandated geological survey cycles, deepen documentation systems and regulatory affairs capacity while securing backward integration into captive well networks across Zhejiang and Hubei to defend supply security for national foodservice contracts. For New Entrants and Emerging Players: Launch via direct-to-subscription models in South Korea and Japan where premium glass-bottle economics justify delivery infrastructure investment, targeting the underpenetrated low-sugar flavored spring water segment that attracts R&D focus from younger consumer cohorts seeking alternatives to conventional sweetened beverages. For Investors and Strategic Acquirers: The window for entry favors operators with exclusive Himalayan or Zhejiang extraction rights and compliant permit documentation. Long-term viability rests on geological asset scarcity rather than manufacturing scale. Monitor Indonesia and Thailand packaging regulation implementation as inflection indicator for alternative material investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Extraction Permit Acquisition | Secures competitive moats under China's SAMR traceability mandates that favor documented geological provenance. |
| Aseptic Cold-Filling Capacity Expansion | Compresses capital recovery timelines for operators serving high-throughput convenience channels in Zhejiang corridor. |
| Glass Bottle Channel Expansion | Captures premium hotel and airline procurement criteria that specify sustainability-compliant packaging formats. |
| Flavored Variant R&D Investment | Addresses nascent demand in South Korea and Japan where younger consumers seek low-sugar hydration alternatives. |
| Alternative Packaging Material Transition | Aligns with Indonesia and Thailand single-use plastic reduction frameworks without compromising tropical shelf stability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction site operators, hospitality procurement directors, regulatory affairs specialists, and foodservice chain beverage managers. NMPA extraction permit databases, SAMR food safety standards documentation, TGA therapeutic claims registers, and FSSAI labeling compliance records provided validation layers. Bottom-up volume modeling triangulated against top-down category spend estimates across the analysis window.
Granularity extended to product type, packaging format, distribution channel, and end-user segments, with additional modeling of mineral composition tiers and carbonation variants. CAGRs derived through regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated PET resin price indices, extraction permit approval timelines, and hospitality procurement consolidation rates.
The model assumes a particular technology adoption path; alternative pathways for aseptic cold-filling or refillable infrastructure would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency and tropical distribution shelf stability. Practitioners should monitor NMPA recertification cycle durations and Indonesia packaging regulation implementation pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Vegetable Juice Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
China Orange Juice Market
Beverages
Indonesia Bottled Water Market
Beverages
Nitro-Infused Beverages Market
Beverages
Apple Juice Market
Beverages
Botanical Infused Beverages Market
Beverages
India Cafes & Bars Market
Beverages
Premium Water Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
United States and Australia Coconut Water Market
Beverages
Middle East Energy Drinks Market
Beverages
North America Fruit Juice Market
Beverages
Electrolyte Mixes Market
Beverages
Japan Kombucha Market
Beverages
Chocolate Powdered Drinks Market