
 Beverages Market | 2026-2036
Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Beverages Market Analysis
Subscription-based replenishment and software-driven personalization is expanding how beverage companies monetize recurring consumer relationships. The Coca-Cola Company leverages its direct-to-consumer platform infrastructure to sustain repeat purchase rhythms across multiple markets. PepsiCo anchors its growth through granular retail analytics that control shelf positioning and inventory turns. Nestlé competes in premium coffee systems through specialized pod formats and machine lock-in economics.
Beverages comprise drinkable liquid formulations processed for human consumption, spanning carbonated soft drinks, natural juices, packaged water, fermented alcohols, and functional blends distinguished by pH levels, sugar content, alcohol by volume, and thermal processing methods. Their primary purpose is hydration, nutrition, stimulation, or social ritual across consumer and commercial contexts. Alcoholic beverages and bottled water represent the most entrenched margin pools, while soft drinks face structural pressure from sugar reduction mandates. Online retailers and convenience stores are capturing the fastest-growing volume flows as households shift replenishment toward smaller basket sizes and immediate consumption occasions.
The FDA governs ingredient safety and nutrition labeling in the United States, while the EU Green Deal and F-Gas Regulation constrain refrigeration-dependent distribution footprints across Europe. China's SAMR enforces national food safety standards that dictate additive permissions and packaging claims for domestic and imported products. Stakeholders must monitor how fragmented compliance obligations across FDA, EFSA, and SAMR jurisdictions will fragment product portfolios and raise localization costs.
Market Dynamics
Sugar taxation frameworks and front-of-pack labeling mandates are forcing beverage manufacturers to reformulate entire product portfolios, compressing R&D cycles and redrawing competitive boundaries between legacy soft drink portfolios and emergent functional alternatives.
Growth Catalysts
- China's SAMR food safety standards:Domestic premium spirits and bottled water brands leverage national certification requirements to build consumer loyalty against imports, concentrating demand within local supply chains.
- Functional ingredient innovation:Adaptogens, probiotics, and nootropic compounds are migrating from supplements into mainstream beverage formats, creating new consumption occasions beyond traditional hydration.
- Convenience store channel expansion:Smaller basket sizes and immediate consumption patterns are shifting volume flows toward proximity retail formats in urban clusters across Japan, South Korea, and Singapore.
Market Restraints
- Sugar input cost volatility:Weather disruptions in Brazilian cane regions and Indian beet harvests are transmitting price instability through sweetened beverage cost structures.
- Refrigeration-dependent distribution:The EU F-Gas Regulation is constraining cold-chain footprints, raising compliance costs for chilled ready-to-drink coffee and probiotic formats across European markets.
- Aluminum can supply concentration:Three North American and European smelters control the majority of beverage-grade sheet supply, creating vulnerability to energy price shocks.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer platforms with machine lock-in economics, exemplified by pod-based coffee systems, are capturing recurring revenue streams.
- India's PLI scheme for food processing:Government incentives for manufacturing scale are attracting contract bottling investment to serve South Asian demand growth.
- AI-driven flavor personalization:Machine learning algorithms analyzing individual microbiome data are enabling customized functional beverage formulations at industrial scale.
Industry Challenges
- Reformulation talent scarcity:Food scientists capable of balancing taste profiles with sugar reduction targets and clean-label requirements command premium compensation.
- Legacy ERP integration:Real-time traceability mandates from FDA and SAMR are forcing costly upgrades to decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverages Market |
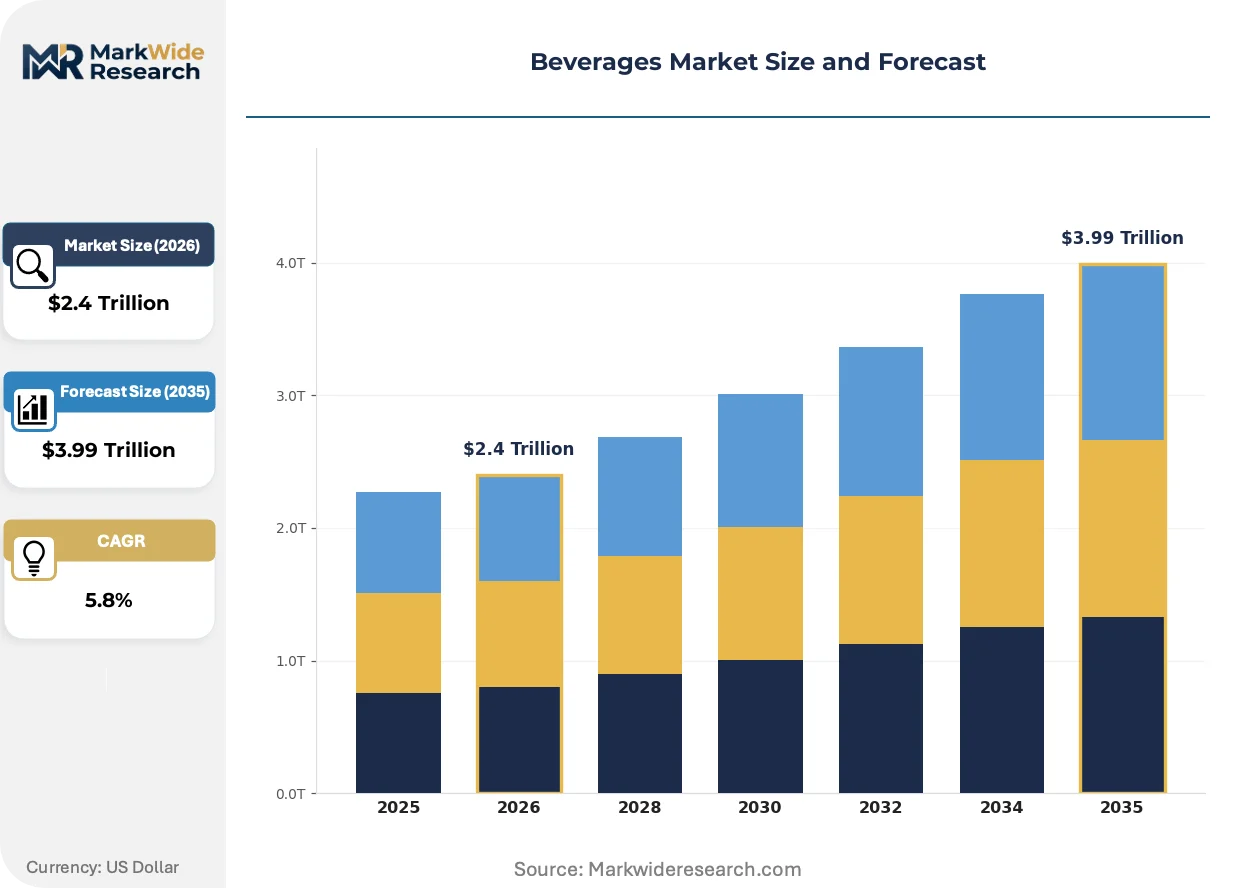
| Market Size in 2026 | $2.4 Trillion |
| Market Size in 2035 | $3.99 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Drinks, Juices, Bottled Water, Alcoholic Beverages Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Restaurants End User: Households, Commercial Establishments, Educational Institutions, Healthcare Facilities Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Fomento Económico Mexicano (FEMSA), Nestlé, The Coca-Cola Company, Nongfu Spring, Diageo, Kweichow Moutai, Anheuser-Busch InBev, Red Bull, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverages Market Emerging Trajectories
Formulation science and digital distribution infrastructure are converging to fragment mass-market monoliths into personalized, health-positioned portfolios. Three developments are compressing traditional category boundaries.
Aseptic processing technology with extended shelf-life capabilities is modularizing production economics for small-batch functional beverages. Regional craft producers in Germany, Australia, and Mexico are adopting these systems to launch probiotic and plant-based lines without capital-intensive hot-fill infrastructure. The technology is modularizing how manufacturing scale maps to geographic coverage, enabling distributed production networks that bypass centralized bottling economics.
The EU Green Deal's carbon border adjustments are reshaping ingredient sourcing decisions for multinational beverage portfolios. Scope 3 emissions reporting requirements are pressuring suppliers of fruit concentrates, natural flavors, and agricultural sweeteners to document cultivation footprints. European formulation teams are accelerating reformulation timelines to substitute high-carbon-import inputs with regional alternatives, particularly affecting tropical juice blends and cane-derived sweeteners.
Household replenishment patterns are fragmenting toward smaller, more frequent purchases through quick-commerce platforms. Urban consumers in São Paulo, Jakarta, and Lagos are substituting weekly supermarket stock-ups with 15-minute delivery of single-serve formats. This channel rotation is compressing packaging specifications toward convenience-oriented sizes and chilling requirements that strain last-mile logistics economics.
Beverages Market Segmentation
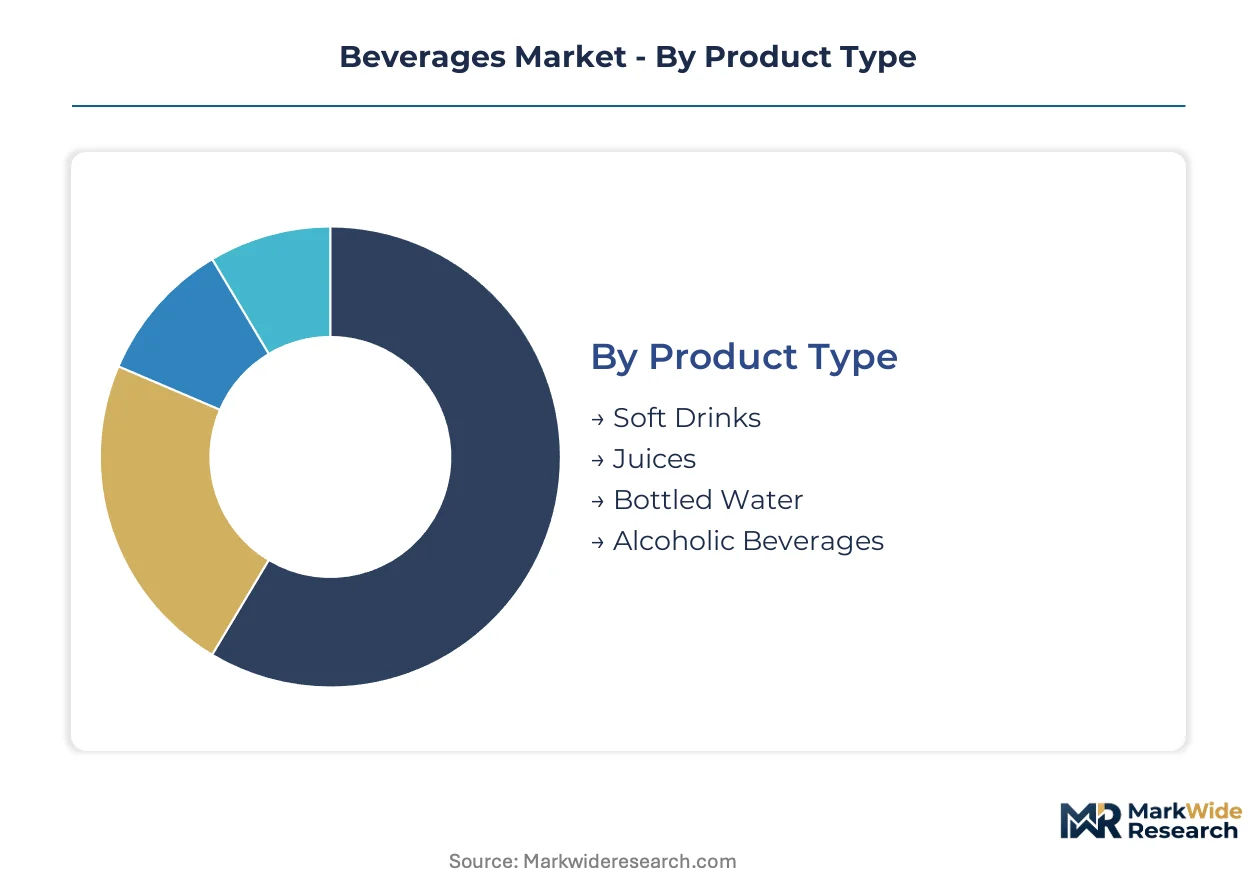
Beverage segmentation reveals how formulation requirements, certification burdens, and channel economics fragment addressable markets. Distinct regulatory pathways for alcohol versus non-alcohol products create portfolio complexity that shapes manufacturing footprints and margin structures.
Product Type:
FDA and SAMR impose divergent additive permissions and labeling mandates across these categories, fragmenting R&D priorities and localization costs for multinational portfolios.
- Soft Drinks:Carbonated formulations face sugar taxation frameworks in Brazil, Mexico, and South Africa that mandate reformulation timelines. Manufacturers balance taste profiles with clean-label requirements while navigating front-of-pack warning labels in Chile and Israel.
- Alcoholic Beverages:Fermented and distilled products carry ABV-based excise structures and age-verification mandates that constrain direct-to-consumer distribution. China's SAMR national standards for premium spirits create certification advantages for domestic producers against imports.
- Juices:Concentrate and not-from-concentrate variants fall under juice content labeling rules in California and EU member states.
- Bottled Water:Natural, purified, and fortified segments face mineral content disclosure requirements and single-use packaging levies.
Bottled Water sits at the top of the volume ranking, with Alcoholic Beverages climbing the fastest.
Distribution Channel:
Channel selection determines refrigeration dependencies, last-mile economics, and the applicability of EU F-Gas Regulation compliance costs.
- Convenience Stores:Proximity retail formats in Tokyo, Seoul, and Singapore capture immediate consumption occasions with chilled single-serve inventory. Smaller basket sizes and 24-hour operations compress replenishment cycles and strain cold-chain logistics.
- Online Retailers:Quick-commerce platforms in São Paulo, Jakarta, and Lagos deliver 15-minute fulfillment for functional beverages and premium formats. Subscription replenishment models with machine lock-in economics capture recurring revenue in coffee systems.
- Supermarkets:Large-format retail maintains volume concentration for multi-pack water and bulk soft drink purchases.
- Restaurants:Foodservice channels carry fountain equipment requirements and post-mix syrup logistics.
Supermarkets retain the highest absolute volume, with Online Retailers expanding most quickly.
End User:
End-user segmentation maps to distinct procurement patterns and specification standards across institutional buyers.
- Households:Individual consumers drive demand for wellness-positioned functional beverages with adaptogen and probiotic ingredients. Health-conscious buyers in Germany, Australia, and Japan prioritize clean-label claims and sugar reduction.
- Commercial Establishments:Hotels, cafes, and offices specify equipment-compatible formats and volume pricing structures.
- Healthcare Facilities:Hospitals and clinics require therapeutic nutrition beverages with documented clinical efficacy.
- Educational Institutions:Schools face sugar restriction policies and vending machine bans in California, France, and England.
Households command the largest consumption base, with Healthcare Facilities gaining share fastest.
Price Tier:
Margin structures stratify across input quality, certification grade, and brand positioning rather than pure volume scale.
- Premium:Single-origin coffee, aged spirits, and functional blends with patented ingredient complexes target affluent urban clusters. Three-tier pricing separates certified organic from conventional from private-label equivalents.
- Mid-Range:Mainstream juice and bottled water brands compete on distribution depth and promotional frequency.
- Budget:Value-positioned soft drinks and bulk water formats sacrifice margin for shelf presence.
- Discount:Private-label and close-out inventory serves price-sensitive segments with minimal marketing support.
Premium captures the highest margin per liter, with Mid-Range maintaining the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest volume base while the United States generates the highest per-capita premium beverage spend, creating divergent competitive imperatives across these two anchor markets.
United States
Household demand for functional beverages with adaptogen and probiotic ingredients drives category expansion in urban coastal clusters. The FDA enforces strict nutrition labeling and ingredient safety protocols that elevate compliance costs for reformulation cycles. Greater Los Angeles and New York Metro concentrate quick-commerce fulfillment infrastructure for 15-minute delivery of chilled single-serve formats.
China
Domestic premium spirits and bottled water brands leverage deep distribution networks to capture health-conscious household spending. SAMR national food safety standards create certification barriers that favor local producers against import competition. The Yangtze River Delta manufacturing corridor hosts concentrated aseptic processing facilities serving probiotic and plant-based beverage launches.
Germany
Clean-label requirements and sugar reduction mandates reshape formulation priorities for carbonated and juice segments. The EU F-Gas Regulation constrains refrigeration-dependent distribution footprints, raising last-mile costs for chilled ready-to-drink products. Bavaria's food technology clusters pioneer extended shelf-life processing systems for small-batch functional producers.
Brazil
Sugar taxation frameworks in São Paulo and Rio de Janeiro accelerate reformulation timelines for sweetened soft drink portfolios. ANVISA governs additive permissions and front-of-pack labeling claims that fragment product localization strategies. The Southeast industrial corridor concentrates contract bottling investment attracted by government incentives for food processing scale.
India
Rising middle-class consumption of packaged water and mid-range juices drives volume growth in Maharashtra and Gujarat. The PLI scheme for food processing attracts manufacturing investment to serve South Asian demand expansion. The Delhi-NCR logistics hub enables rapid distribution of ambient-stable formats to tier-two urban centers.
Beverages Market Vendor Landscape
Top-tier vendors anchor premium and mass-market portfolios simultaneously, while mid-scale regional specialists occupy niche functional and craft segments. The vendor base stratifies across multinational conglomerates with integrated supply chains, national champions leveraging regulatory familiarity, and agile insurgents betting on microbiome personalization and subscription lock-in economics. Two dominant competitive moves define current positioning: direct-to-consumer platform buildouts with recurring revenue mechanics, and granular retail analytics controlling shelf positioning and inventory velocity.
Among diversified multinational conglomerates, The Coca-Cola Company, PepsiCo, and Nestlé exemplify distinct strategic archetypes. The Coca-Cola Company occupies a position centered on direct-to-consumer infrastructure and repeat purchase rhythm management across multiple markets. PepsiCo sits within a retail analytics-driven tier, leveraging granular data to control shelf positioning and inventory turns. Nestlé anchors the premium coffee systems segment through specialized pod formats and machine lock-in economics that capture recurring revenue streams.
| Leading Market Players |
|---|
| Fomento Económico Mexicano (FEMSA) |
| Nestlé |
| The Coca-Cola Company |
| Nongfu Spring |
| Diageo |
| Kweichow Moutai |
| Anheuser-Busch InBev |
| Red Bull |
| PepsiCo |
| Others |
Supply Flow & Price Mechanics
Aluminum sheet input costs transmit directly from three dominant North American and European smelters through beverage-grade packaging tiers, concentrating margin pressure on mid-range carbonated and ready-to-drink formats while premium spirits and functional blends absorb volatility through brand premium mechanics.
Pricing Analysis
Capacity additions in India's Maharashtra and Gujarat food processing corridors are reshaping price floors for ambient-stable juice and bottled water formats across South Asian markets. Three-tier pricing structure across premium, standard, and economy levels separates certified organic functional beverages from conventional fortified variants from private-label equivalents. Pricing pressure stems from sugar input volatility in Brazilian cane regions, compressing margins on sweetened soft drink portfolios. Budget-tier buyers exhibit highest price sensitivity, while premium functional beverage consumers demonstrate inelastic demand for adaptogen and probiotic formulations.
Supply Chain Analysis
Direct-to-retailer channels handle hyperscale replenishment for supermarket and convenience store networks, while quick-commerce platforms manage fragmented last-mile delivery for single-serve chilled formats. Manufacturing concentrates in China, Germany, and Brazil, with aseptic processing facilities clustering in the Yangtze River Delta and Bavarian food technology corridors. Raw material dependencies include Brazilian cane sugar, Indian beet sugar, and beverage-grade aluminum sheet. Single-source vulnerability in aluminum smelter concentration creates exposure to energy price shocks. Distribution runs through centralized bottling economics for mass-market portfolios and distributed micro-brewery networks for craft functional producers.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Beverages Market functions as a stable compounder anchored by recurring household consumption patterns for hydration and wellness-positioned formats, with regulatory tailwinds on sugar reduction creating persistent reformulation demand.
For Market Incumbents: Hedge against sugar taxation acceleration by accelerating clean-label R&D investment and securing aseptic processing capacity in India and Southeast Asia. Lock in aluminum supply contracts with European smelters before F-Gas Regulation compliance costs transmit downstream. Build direct-to-consumer platform infrastructure with machine lock-in economics to capture recurring revenue streams insulated from retail price competition.
For New Entrants and Emerging Players: Capture white-space in microbiome-personalized functional beverages by deploying AI-driven flavor algorithms at industrial scale. Target underpenetrated quick-commerce channels in São Paulo, Jakarta, and Lagos with 15-minute delivery infrastructure for chilled single-serve formats. Lead with subscription replenishment models that establish habit formation before incumbent platform buildouts mature.
For Investors and Strategic Acquirers: Roll-up economics work for regional craft functional beverage producers because aseptic processing technology modularizes production economics and enables distributed manufacturing networks without centralized bottling capital. Long-term viability centers on portfolio brands capable of spanning premium spirits, functional wellness, and clean-label hydration. Watch SAMR certification timeline acceleration as the inflection signal for import displacement by domestic Chinese producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | The Coca-Cola Company's infrastructure sustains repeat purchase rhythms across multiple markets through subscription mechanics. |
| Aseptic Processing Capacity Expansion | Bavarian technology clusters enable small-batch probiotic and plant-based launches without hot-fill infrastructure. |
| AI-Driven Flavor Personalization | Machine learning algorithms analyzing microbiome data enable customized functional formulations at industrial scale. |
| Aluminum Supply Contract Restructuring | Three dominant smelters create vulnerability to energy price shocks requiring long-term offtake security. |
| Clean-Label Reformulation Investment | FDA and SAMR traceability mandates force costly ERP upgrades that favor scaled incumbents over legacy mid-tier producers. |
Methodological Framework
Coverage spans the United States, China, Germany, Brazil, and India, with primary inputs from each market combining interviews with beverage brand managers, retail category buyers, food technology R&D directors, and supply chain planners with secondary validation. Primary fieldwork drew from FDA filings, SAMR food safety standards, EU F-Gas Regulation compliance disclosures, and Nielsen retail audit data. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Rate-of-change decomposition anchored volume and value outputs across the projection horizon, with CAGRs derived from segment-level growth trajectories. Segmentation dimensions modeled include product type, distribution channel, end user, and price tier, with regulatory cluster and refrigeration dependency as industry-specific overlay variables. Forecast inputs incorporated sugar commodity futures curves, aluminum smelter capacity utilization, and quick-commerce penetration rates by urban cluster.
Underlying measurement precision varies by segment; premium functional beverages and subscription-platform revenue streams carry tighter precision than fragmented craft producer estimates. Forecasts reflect documented assumptions on regulatory timeline acceleration and commodity price normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Root Beer Market
Beverages
Fusion Beverages Market
Beverages
Beverage Multipacks Market
Beverages
North America Juices Market
Beverages
Kvass Market
Beverages
Global Soda Maker Market
Beverages
Low Fat Drinks Market
Beverages
Milk Tea Powder Market
Beverages
US and Canada Premium Bottled Water Market
Beverages
Double Valve Moka Pots Market
Beverages
Gluten Free Beverages Market
Beverages
Vegetable Juice Market
Beverages
Probiotic Beverage Market
Beverages
Juice Concentrates Market
Beverages
Japan Kombucha Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market