
 Carbonated Beverages Market | 2026-2036
Carbonated Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Carbonated Beverages Market Intelligence
A long-standing preference for traditional cola among older consumer cohorts is unwinding as younger demographics drive consumption of flavored seltzers and functional beverages. This shift creates opportunities for both incumbents and challengers. The Coca-Cola Company leverages its extensive global distribution to introduce new product variants across categories. PepsiCo competes by investing heavily in marketing for its low-sugar alternatives, while Keurig Dr Pepper sustains a strong position in specific flavor segments like root beer.
Carbonated beverages are liquids into which carbon dioxide gas has been dissolved under pressure, creating effervescence. This process typically involves a carbonator that infuses filtered water with CO2 before flavorings, sweeteners, and other ingredients are added. While cola products from the product type segment represent a mature, high-volume category, the tonic water and ginger ale segments show significant growth. This expansion is driven by their use as premium mixers in foodservice outlets and through online retailers.
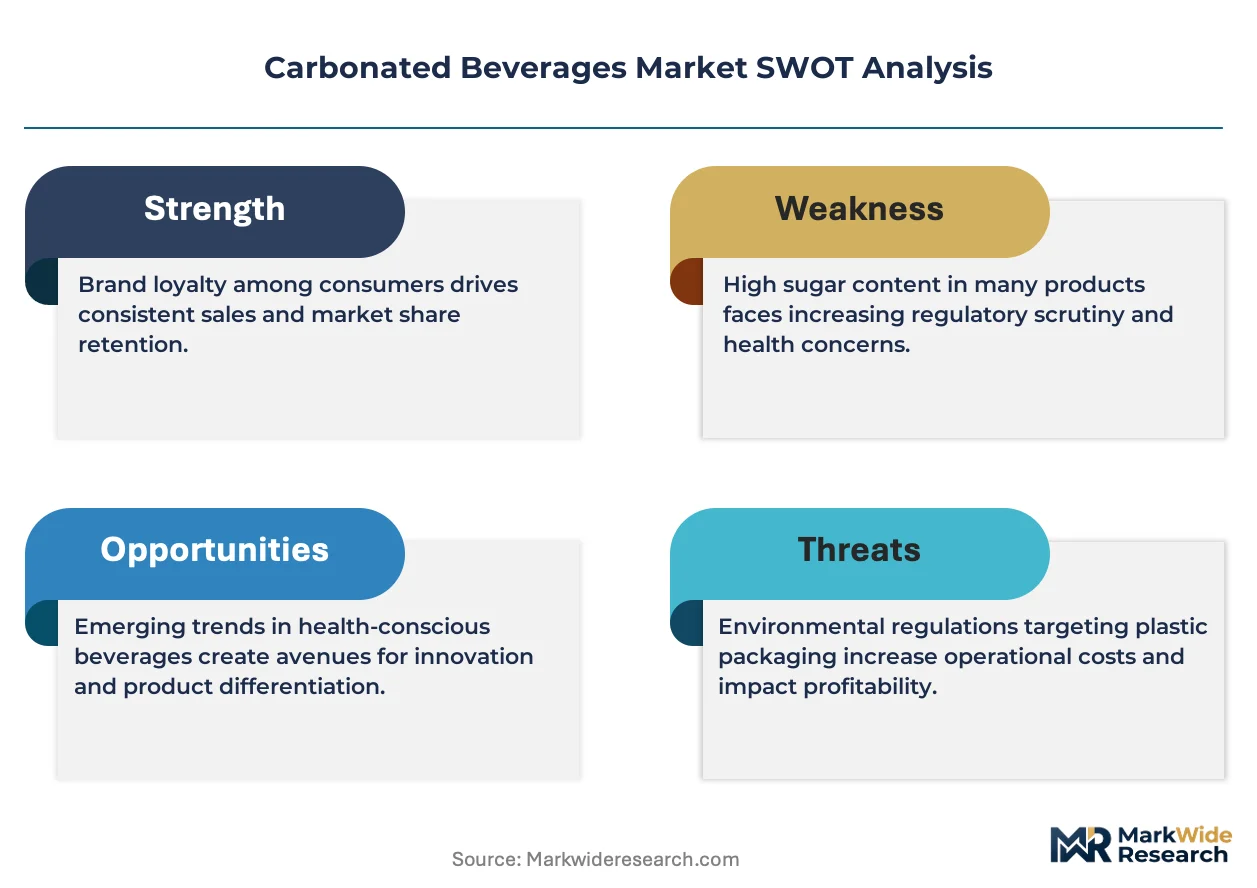
The U.S. Food and Drug Administration (FDA) enforces strict labeling rules for sugar content and nutritional information, impacting marketing claims. In parallel, European Food Safety Authority (EFSA) opinions guide regulations on additives and new ingredients across the EU. National policies, such as sugar taxes in Mexico or plastic packaging levies in the UK, further shape market access. Future profitability for producers depends on navigating these divergent regulatory pressures while aligning product portfolios with consumer health preferences.
Market Dynamics
The primary structural force is the global regulatory and consumer campaign against high-sugar content, compelling widespread product reformulation. This pressure, exemplified by national sugar taxes, directly challenges the industry's traditional volume-driven model based on sweetened colas.
Growth Catalysts
- Emerging Market Urbanization:Rising disposable incomes and urbanization in Southeast Asian countries, particularly Vietnam and Indonesia, are expanding the consumer base for packaged beverages.
- Online Retail Expansion:The growth of e-commerce and online grocery platforms provides new routes to market, enabling brands to reach consumers directly and offer greater product variety.
- Premium Mixer Demand:The foodservice sector's focus on premium cocktails is elevating demand for sophisticated carbonated mixers like tonic water and ginger ale, creating a high-margin segment.
Market Restraints
- Punitive Sugar Taxation:Fiscal policies like the UK's Soft Drinks Industry Levy and Mexico's excise tax directly increase consumer prices and reduce margins for high-sugar beverage formulations.
- Input Material Volatility:Price fluctuations and supply availability for key inputs, such as carbon dioxide and aluminum for cans, create production cost instability and supply chain risks.
- Threat of Substitution:Health-conscious consumers are increasingly opting for non-carbonated alternatives, including functional waters, ready-to-drink teas, and tap water enhancers, eroding the core market.
Strategic Opportunities
- Advanced Sweetener Formulation:Developing novel, natural-origin sweeteners and flavor modulators offers a path to create low-calorie beverages that do not compromise on taste profiles demanded by consumers.
- Functional Beverage Integration:Infusing carbonated drinks with functional ingredients such as vitamins, probiotics, or adaptogens allows brands to enter the lucrative health and wellness market segment.
- Direct-to-Consumer Models:Launching subscription-based services for niche and craft carbonated beverages enables brands to build direct customer relationships and bypass competitive retail shelf space.
Industry Challenges
- Packaging Material Transition:Managing the complex and capital-intensive shift in packaging mix from glass to aluminum and recycled plastics is complicated by inconsistent recycling infrastructure and new levies.
- Regulatory Compliance Burden:Adhering to a patchwork of international food safety and labeling standards, from FDA rules to EFSA opinions, increases operational complexity and costs for global distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbonated Beverages Market |
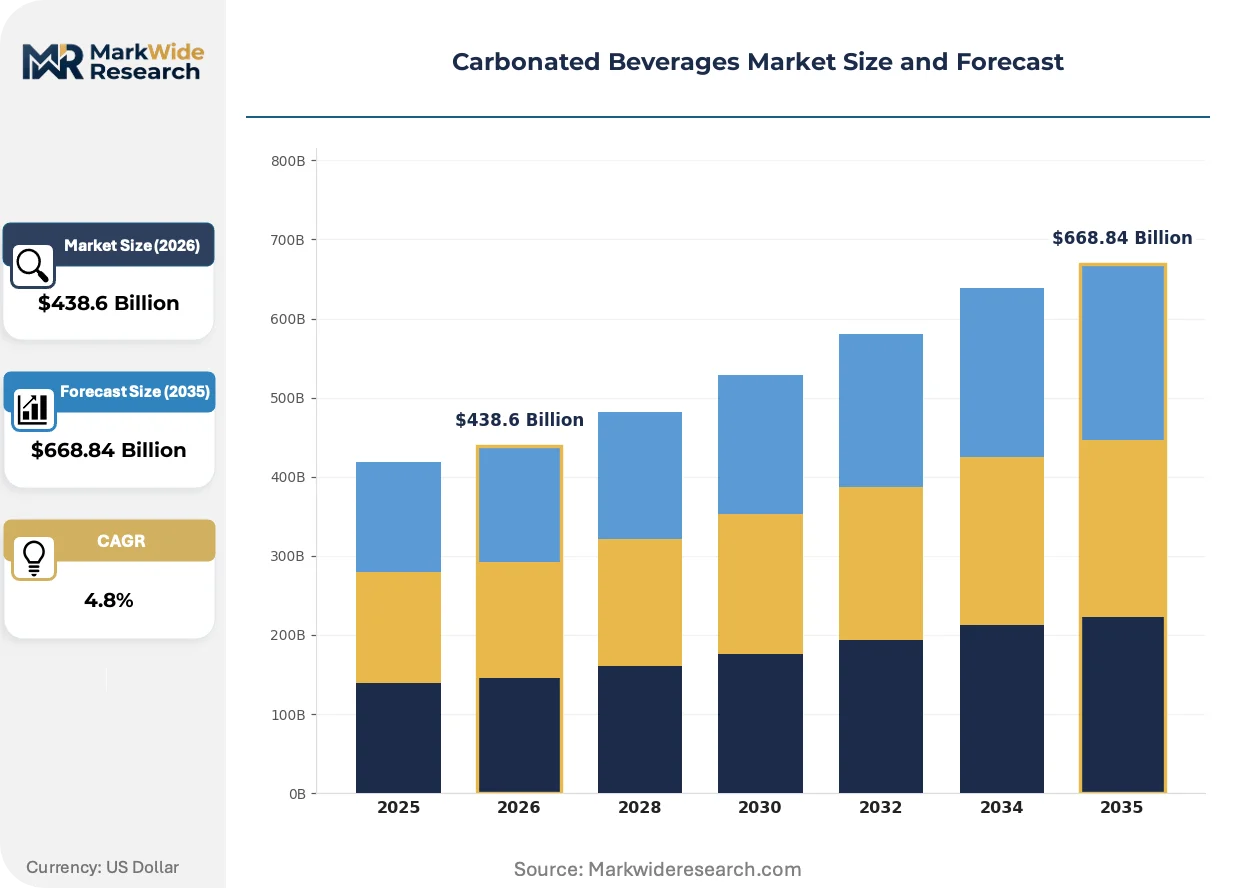
| Market Size in 2026 | $438.6 Billion |
| Market Size in 2035 | $668.84 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cola, Lemon-Lime, Root Beer, Ginger Ale, Orange, Tonic Water Packaging Type: Can, Bottle, Carton, Keg, PET, Glass Bottle Distribution Channel: Supermarkets, Convenience Stores, Vending Machines, Online Retailers, Foodservice Outlets, Wholesalers Customer Type: Restaurants, Cafes, Cinemas, Event Venues, Offices, Educational Institutions |
| Companies Covered | Suntory Beverage & Food, Asahi Group Holdings, The Coca-Cola Company, Monster Beverage, National Beverage Corp., PepsiCo, Refresco Group, Danone, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbonated Beverages Market Strategic Shifts & Innovations
Product formulation is undergoing a fundamental reinvention, driven by a convergence of data science and material innovation. This shift moves the industry beyond simple sugar reduction toward creating beverages with targeted functional outcomes and novel sensory experiences.
AI-powered flavor development platforms analyze vast datasets on consumer preferences and ingredient interactions to predict successful new combinations. R&D departments in the beverage industry are adopting this technology to shorten innovation cycles significantly. This data-centric approach is decomposing the traditional, trial-and-error process of flavor creation, enabling hyper-targeted product launches.
Extended Producer Responsibility (EPR) regulations are becoming standard across the European Union and in several key US states. These policies mandate that producers fund the collection and recycling of their packaging, internalizing environmental costs. Consequently, the plastic bottle and aluminum can segments face immense pressure to increase recycled content and design for circularity.
Consumer purchasing decisions are pivoting from brand allegiance toward ingredient transparency and functional benefits. This change disrupts the traditional cola category, as smaller brands offering products with nootropics or probiotics gain share through online retail. The shift is most visible within health-conscious urban demographics in North America and Europe.
Carbonated Beverages Market Segmentation
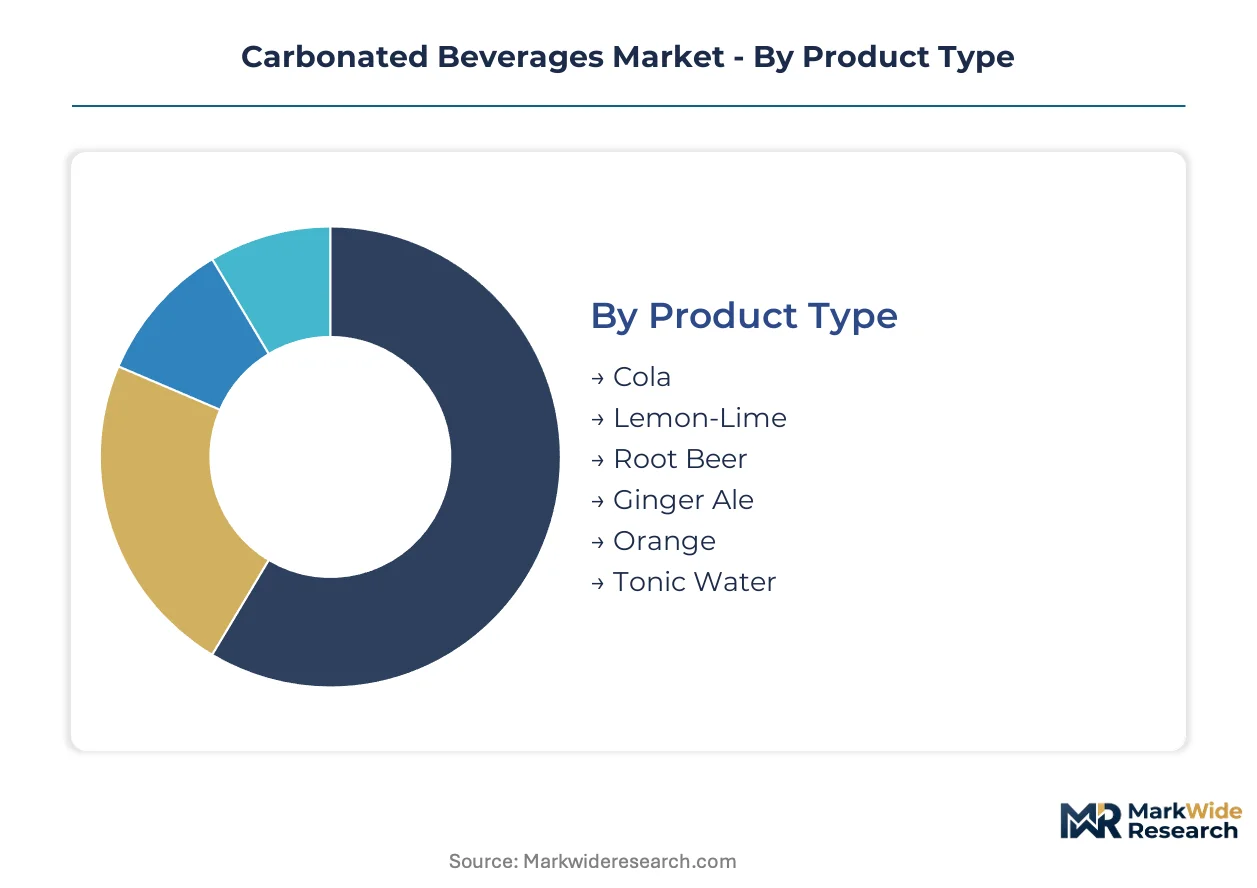
Segmentation provides a granular view of the Carbonated Beverages Market, highlighting distinct consumer preferences and operational dynamics. Understanding these divisions helps stakeholders identify precise growth opportunities and allocate resources effectively across diverse product offerings and distribution networks.
Product Type:
Margin pools within the product type category reflect consumer preference for premiumization and functional attributes.
- Cola:This product type represents carbonated beverages flavored with caramel color and phosphoric acid, typically offering a sweet, effervescent experience. Demand remains high in established markets like the United States, driven by long-standing brand loyalty and extensive availability.
- Tonic Water:Characterized by its bitter quinine flavor and carbonation, tonic water serves primarily as a sophisticated mixer for alcoholic beverages. Its demand is concentrating in European and North American foodservice outlets, fueled by the craft cocktail movement and premiumization trends.
- Lemon-Lime:These beverages offer a crisp, citrus flavor profile, often positioned as a refreshing, lighter alternative to cola.
- Root Beer:A distinct North American flavor, root beer is known for its sweet, herbal, and sassafras-like taste, maintaining a niche but loyal consumer base.
- Ginger Ale:This carbonated beverage features a prominent ginger flavor, often consumed for its perceived digestive benefits or as a mixer.
- Orange:Sweet and tangy, orange-flavored carbonated drinks appeal to a broad demographic, particularly in family-oriented consumption settings.
Cola holds significant installed capacity. Tonic Water is rotating up the share rankings.
Packaging Type:
The cost tier of packaging significantly influences both production expenses and consumer price points.
- Can:Aluminum cans provide excellent recyclability and a high surface area for branding, offering portability and protection from light. Demand for cans is accelerating globally due to increasing consumer environmental consciousness and convenience in grab-and-go formats.
- PET:Polyethylene terephthalate (PET) bottles are lightweight, shatter-resistant, and cost-effective, making them dominant for high-volume beverage sales. Their prevalence is particularly strong in emerging markets across Southeast Asia, where affordability and transport efficiency are critical.
- Bottle:This general category encompasses various bottle materials and sizes, providing versatility for different product types and consumption occasions.
- Carton:Cartons are less common for carbonated beverages but offer an alternative for specific niche products or multi-packs.
- Keg:Kegs are primarily used in the foodservice sector for dispensing carbonated beverages in high-volume environments like bars and restaurants.
- Glass Bottle:Glass bottles convey a premium image and preserve flavor integrity, often chosen for craft beverages or specific heritage brands.
PET bottles continue to dominate volume, while aluminum cans are expanding most quickly due to sustainability trends.
Distribution Channel:
Customer type dictates the optimal distribution channel, with convenience and accessibility driving purchasing decisions.
- Supermarkets:These large retail stores serve as a primary channel for household bulk purchases, offering a wide assortment of brands and sizes.
- Online Retailers:E-commerce platforms and online grocery services provide significant convenience for consumers, enabling direct-to-door delivery and access to niche products. This channel is gaining share fastest in urban centers across North America and Europe.
- Convenience Stores:Positioned for impulse purchases and immediate consumption, convenience stores offer quick access to single-serve carbonated beverages.
- Vending Machines:Automated vending solutions provide 24/7 access to beverages in high-traffic locations like offices, transport hubs, and public spaces.
- Foodservice Outlets:Restaurants, cafes, and bars rely on this channel for bulk syrups and bottled products, catering to on-premise consumption.
- Wholesalers:Wholesalers act as intermediaries, supplying smaller retailers, institutions, and foodservice businesses with large quantities of carbonated beverages.
Supermarkets remain a foundational channel, but online retailers are gaining share fastest.
Customer Type:
The application of carbonated beverages varies widely across customer types, influencing product selection and volume.
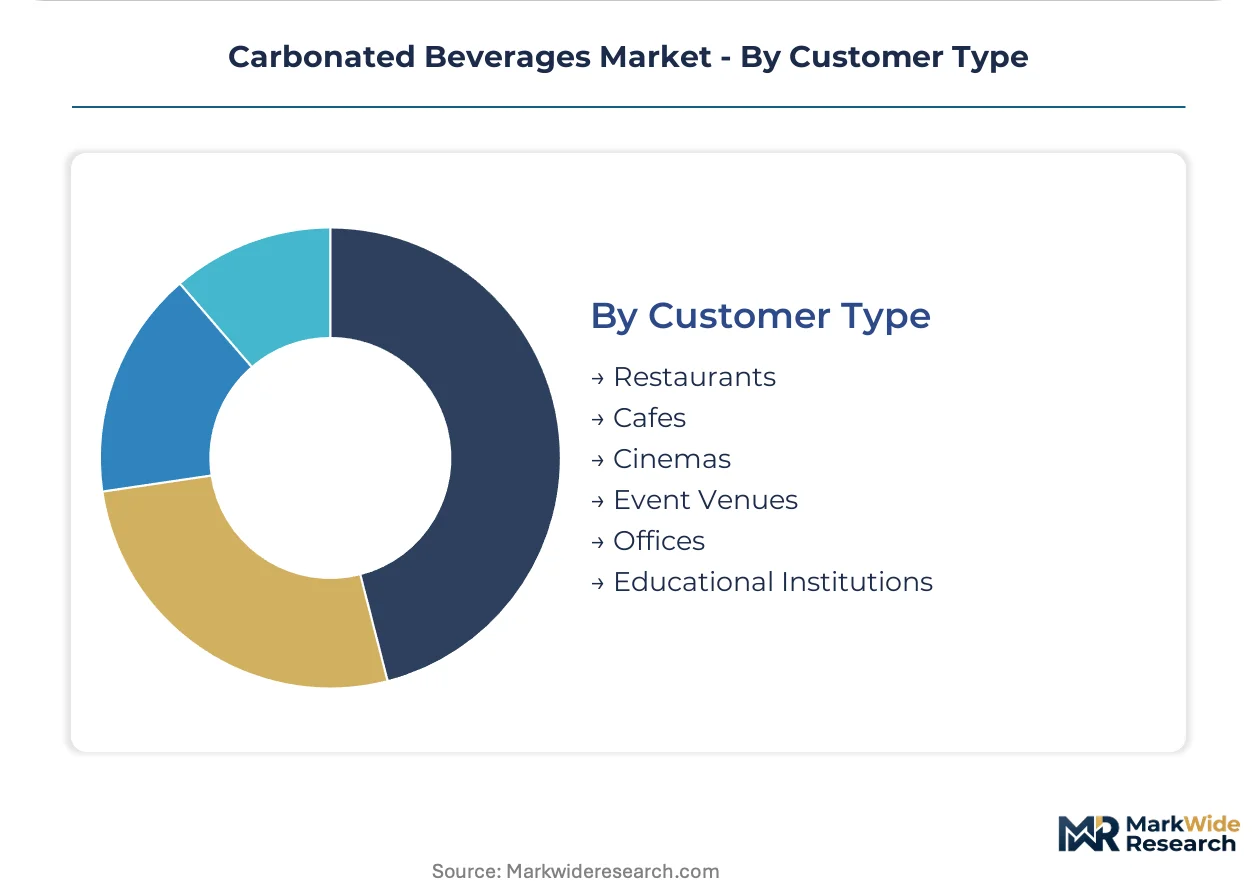
- Restaurants:These establishments purchase carbonated beverages for on-premise consumption, often in fountain drink formats or bottled options to complement meals.
- Cafes:Cafes typically offer a smaller selection of carbonated beverages, often focusing on premium mixers or unique flavor profiles to complement their coffee and tea offerings.
- Cinemas:Movie theaters drive high-volume sales of carbonated beverages, primarily through fountain drinks and large-sized single-serve options, capitalizing on impulse purchases.
- Event Venues:Sports arenas, concert halls, and convention centers represent a significant customer type, generating substantial sales during large gatherings and public events.
- Offices:Workplaces provide beverages for employees and guests, often utilizing vending machines or bulk deliveries for breakroom amenities.
- Educational Institutions:Schools and universities purchase carbonated beverages for cafeterias, vending machines, and campus stores, catering to student and faculty demand.
Restaurants represent a stable demand base, while event venues show the steepest expansion trajectory for impulse purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of carbonated beverages from established production hubs to emerging consumption markets shapes regional dynamics. Manufacturers in countries like the United States export advanced product formulations to diverse global markets. This trade supports growth in areas with rising disposable incomes and evolving consumer preferences.
United States
Demand for flavored seltzers and functional beverages drives consumption among younger demographics. The U.S. Food and Drug Administration (FDA) enforces strict labeling rules for sugar content and nutritional information. Major beverage companies in Atlanta, Georgia, continually introduce new product variants and innovative packaging solutions to capture market share.
United Kingdom
Consumer health preferences and the shift towards lower-calorie options influence product development. The UK's Soft Drinks Industry Levy directly increases consumer prices for high-sugar formulations, compelling reformulation. London's vibrant foodservice sector fuels demand for premium tonic water and ginger ale as sophisticated mixers.
Mexico
The carbonated beverages market experiences significant reformulation due to public health initiatives and consumer awareness. Mexico's excise tax on sugar-sweetened beverages compels widespread product diversification towards low-sugar alternatives. Major bottling plants near Mexico City adapt production lines to meet changing regulatory and consumer demands effectively.
Vietnam
Rising disposable incomes and rapid urbanization expand the consumer base for packaged carbonated drinks across various segments. Government initiatives supporting foreign investment facilitate market entry for international beverage brands and local producers. Ho Chi Minh City's expanding retail infrastructure and e-commerce platforms provide new routes to market for diverse product offerings.
Indonesia
Urbanization trends and a young population contribute to robust demand for refreshing carbonated options and functional beverages. The Indonesian Food and Drug Authority (BPOM) regulates food and beverage safety and labeling standards for market access. Jakarta's dense urban centers and growing middle class represent a significant consumption cluster for diverse beverage categories and new brands.
Carbonated Beverages Market Key Industry Players
Listed leaders compete with private specialists across product innovation and market penetration. The carbonated beverages market exhibits a tiered structure, with global conglomerates alongside regional players and niche craft producers. Strategic archetypes include volume-driven giants that leverage extensive distribution, health-focused innovators targeting functional benefits, and premium mixer specialists serving the foodservice sector. Portfolio diversification into non-carbonated categories and geographic expansion into emerging markets remain dominant competitive moves for securing long-term growth trajectories.
At the scale-driven end, The Coca-Cola Company and PepsiCo exemplify global beverage conglomerates with vast product portfolios. These entities anchor the traditional cola segment while also expanding into new categories like flavored seltzers and functional drinks. Keurig Dr Pepper, a US-based entity, occupies a position as a significant player within specific flavor segments, such as root beer, and maintains a strong regional presence. These companies collectively navigate complex regulatory environments and evolving consumer preferences for health and wellness. Their strategies involve continuous product reformulation and targeted marketing efforts to sustain market leadership.
| Leading Market Players |
|---|
| Suntory Beverage & Food |
| Asahi Group Holdings |
| The Coca-Cola Company |
| Monster Beverage |
| National Beverage Corp. |
| PepsiCo |
| Refresco Group |
| Danone |
| Keurig Dr Pepper |
| Others |
Cost & Logistics Intelligence
Long-term supply contracts for key ingredients like CO2 and sweeteners lock in both supply access and price visibility for major beverage producers. This stability is crucial amidst fluctuating raw material costs impacting the carbonated beverages market.
Pricing Analysis
The pricing gap between traditional high-sugar colas and newer low-calorie functional beverages is widening due to consumer health preferences. Transactional per-unit pricing dominates across most carbonated beverage categories, particularly in supermarkets. Brand premium and geographic delivery costs are significant price differentiation drivers. Pricing softness for traditional products stems from intense competition and widespread product reformulation. Value-conscious consumers in emerging markets exhibit the highest price sensitivity, while premium mixer users in foodservice outlets show less.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume carbonated beverage production, though strategic stockpiles of critical inputs like CO2 are increasing due to supply disruptions. Geographic supply concentration for key raw materials includes aluminum from China and sweeteners from Brazil. The industry draws from global sources for flavorings and PET resins. Commodity price volatility for aluminum and CO2 represents a structural supply chain risk. Distribution runs primarily through established retail networks, supported by expanding online retailer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbonated beverages market presents an early-cycle expansion story, driven by the accelerating penetration of health-conscious functional variants into new consumer demographics. This shift creates significant opportunities for strategic repositioning.
For Market Incumbents: Fortify core brand equity in established segments while aggressively diversifying product portfolios into functional beverages. Coca-Cola and PepsiCo must counter the threat of substitution from non-carbonated alternatives by investing in advanced sweetener formulation. Channel control through direct-to-consumer models offers a named lever against competitive retail shelf space.
For New Entrants and Emerging Players: Certification fast-tracks for natural-origin sweeteners and organic ingredients provide a clear entry point for new beverage brands. Target the premium mixer segment within European foodservice outlets, which remains penetrable by craft ginger ale and tonic water producers. A go-to-market angle focused on ingredient transparency and targeted functional benefits resonates strongly with health-conscious urban demographics.
For Investors and Strategic Acquirers: Capital is best deployed toward agile, health-focused innovators with strong intellectual property in novel sweetener technologies or functional ingredients. The long-term viability of the market (5-10 year window) favors companies that can navigate evolving regulatory landscapes. An acquisition target archetype includes mid-sized producers with established online retail presence. The signal to watch is sustained growth in online sales for niche functional carbonated beverages.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Formulation Reinvention | AI-powered flavor development shortens innovation cycles, enabling hyper-targeted product launches for new consumer preferences. |
| Direct-to-Consumer Launch | Subscription-based models build direct customer relationships and bypass competitive retail shelf space for craft beverages. |
| Advanced Sweetener Development | Novel natural-origin sweeteners create low-calorie options without taste compromise, addressing sugar tax concerns. |
| Packaging Circularity Investment | Increased recycled content and design for circularity meet EPR regulations and consumer environmental consciousness. |
| Functional Ingredient Integration | Infusing carbonated drinks with adaptogens or probiotics captures health and wellness market share in North America. |
Research Approach
A standing panel of beverage R&D directors, supply chain managers, retail category buyers, and regulatory affairs specialists provided ongoing calibration. Primary interviews with industry stakeholders combined with secondary validation from customs and trade data, national food safety authority reports, and company investor presentations informed the analysis. This approach ensured robust bottom-up and top-down triangulation for market sizing.
Outputs were validated against external benchmarks and peer-reviewed studies to ensure consistency across the analysis window. The analytical framework modeled segmentation dimensions including product type, packaging type, distribution channel, and customer type. Carbon dioxide and sweetener pricing volatility were key industry-specific forecast inputs. Compound Annual Growth Rates (CAGRs) were derived from historical performance trends and projected market dynamics.
Decision-makers should treat outputs as directional under current regulatory and consumer preference assumptions; material deviation warrants model refresh. Forecasts reflect a baseline scenario, acknowledging risks from new sugar taxes or packaging levies. Practitioners should keep alternative scenarios live as global economic conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Water Flavor Market
Beverages
South East Asia Bottled Water Market
Beverages
China Orange Juice Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Sparkling Water Machine Market
Beverages
Ready to Drink Premixes Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Beverage Dispenser Market
Beverages
Ready to Drink Shakes Market
Beverages
China Soy Beverages Market
Beverages
Commercial Drink Mixers Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Premium Bottled Water Market
Beverages
Middle East Energy Drinks Market
Beverages
Plant Based Protein Beverages Market
Beverages
Coconut Water Market