
 Apple Juice Concentrate Market | 2026-2036
Apple Juice Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Juice Concentrate Market Analytics
Apple cider vinegar is broadening its role as a functional substitute in beverage formulations, displacing some traditional concentrate volumes in wellness-positioned drinks. Tree Top Inc. leverages its Pacific Northwest orchard network to sustain year-round supply consistency for industrial buyers. AGRANA Beteiligungs-AG anchors its position through backward integration into European fruit processing, while Döhler competes on flavor-system customization for multinational beverage clients.
Apple juice concentrate is a dehydrated liquid extract produced by evaporating water from pressed apple juice to approximately 70-72 degrees Brix soluble solids, yielding a shelf-stable ingredient that reconstitutes at ratios near six-to-one for finished beverages. The product serves primarily as a bulk sweetener, acidulant, and flavor base across food manufacturing. Clear concentrate dominates volume flows into carbonated and still beverages, while organic concentrate commands premium positioning in clean-label bakery and confectionery segments. Cloudy concentrate retains suspended solids that suit nectar-style drinks and certain sauce applications where mouthfeel carries value.
FDA nutrition labeling rules and EU F-Gas Regulation compliance requirements shape evaporative processing investments and cold-chain logistics specifications for concentrate imports. BIS standards in India and China's GB standards for fruit-derived ingredients further segment market access pathways for exporters. Stakeholders must monitor regulatory divergence on natural-claim definitions and sugar-reduction thresholds across their priority destination markets.
Market Dynamics
Beverage manufacturers are reformulating recipes to reduce cane sugar content, pulling apple juice concentrate into expanded natural sweetener roles as FDA and EU labeling standards tighten disclosure requirements for added sugars.
Growth Catalysts
- EU F-Gas Regulation:Compliance mandates for lower-emission evaporative processing are accelerating capital upgrades that improve concentrate yield efficiency and reduce thermal degradation of flavor compounds.
- China's GB standards:Domestic beverage brands are expanding procurement of apple-derived ingredients to meet national sugar-reduction guidelines in carbonated and still drink categories.
- Clean-label bakery demand:Organic concentrate volumes are climbing as European and North American confectionery manufacturers replace synthetic sweeteners with fruit-based alternatives in premium product lines.
Market Restraints
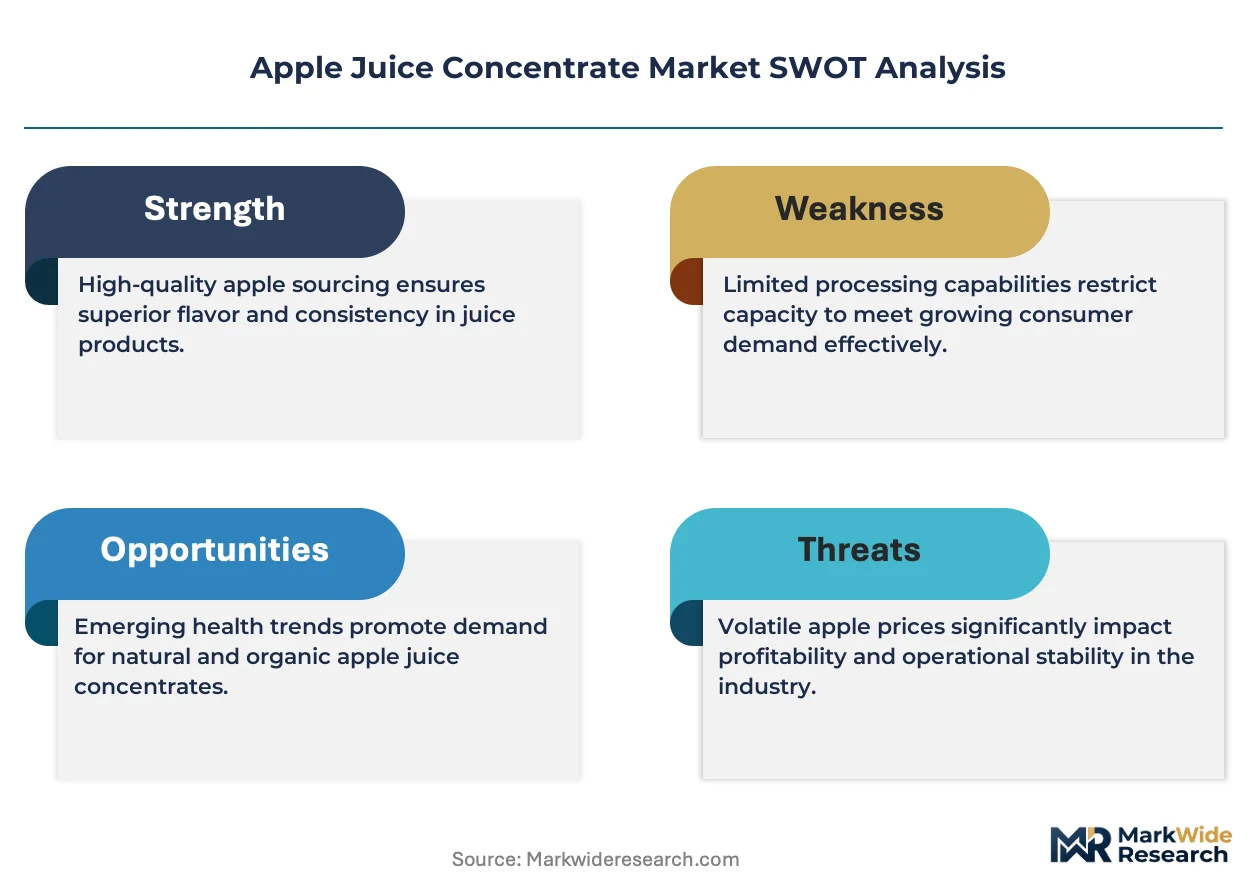
- Input cost volatility:Fresh apple prices swing with Pacific Northwest and Polish orchard weather patterns, compressing processor margins during poor harvest years.
- Supply concentration risk:Industrial-grade clear concentrate flows predominantly through Chinese and Polish processing clusters, creating single-source vulnerability for multinational beverage clients.
- Substitution threat:Apple cider vinegar is displacing concentrate volumes in wellness-positioned functional beverages where acidity and fermented flavor profiles carry marketing value.
Strategic Opportunities
- India's BIS certification pathway:Exporters establishing compliant cold-chain logistics can access underpenetrated juice and nectar markets as domestic consumption of packaged beverages expands.
- Cloudy concentrate in sauces:Suspended solids retention suits mouthfeel-driven applications in Asian cooking sauces and European prepared foods where texture differentiation commands premium placement.
- EU Green Deal alignment:Processors investing in renewable-powered evaporation and water recovery systems qualify for sustainability-linked procurement preferences from major retail private-label programs.
Industry Challenges
- Evaporator technician shortage:Specialized knowledge of multi-effect vacuum systems and Brix control instrumentation is scarce in emerging processing regions, extending commissioning timelines.
- Dual certification burden:Simultaneous FDA nutrition label compliance and EU natural-claim documentation requires parallel analytical testing protocols that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Juice Concentrate Market |
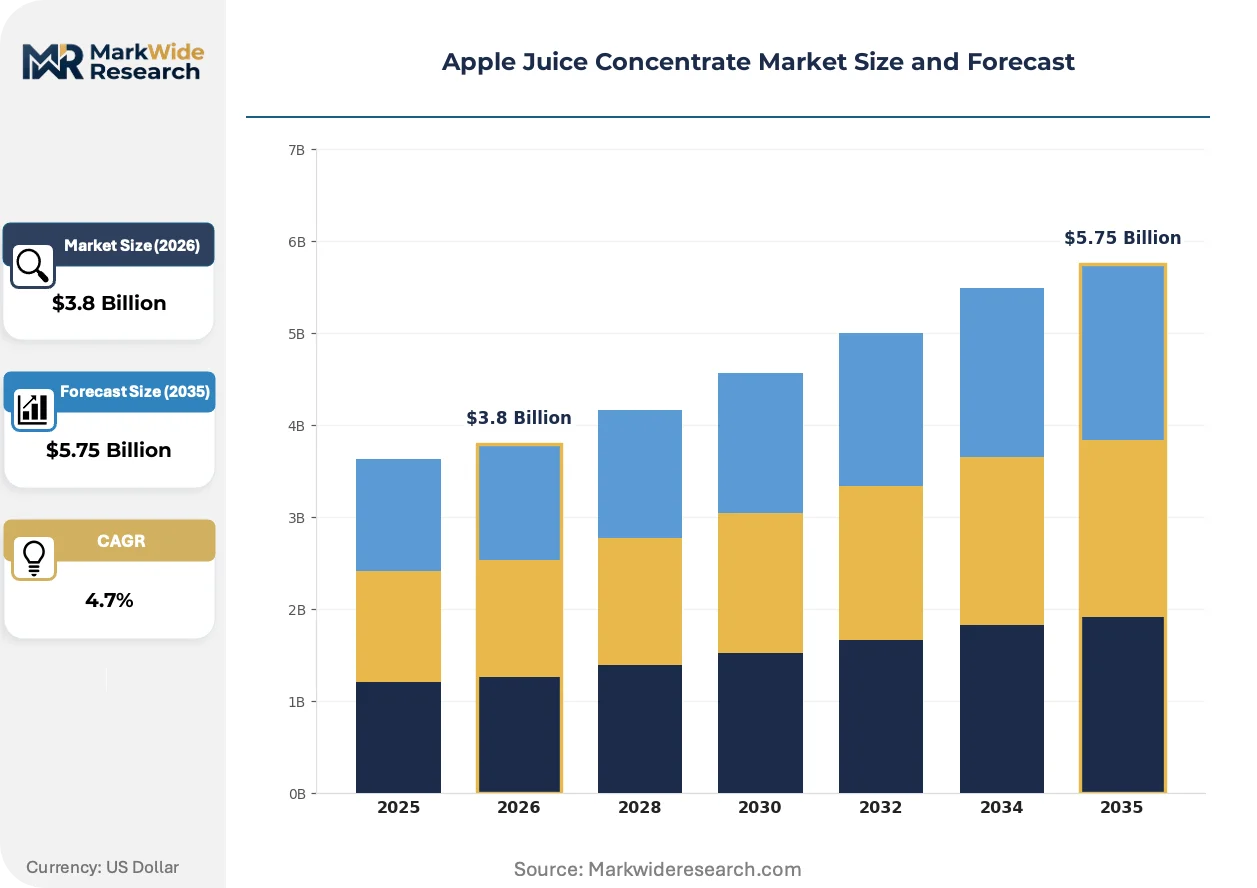
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Concentrate, Cloudy Concentrate, Organic Concentrate, Conventional Concentrate End Use: Beverages, Bakery Products, Confectionery, Sauces Packaging Type: Cartons, Drums, Pouches, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Direct Sales |
| Companies Covered | Ingredion Incorporated, Tree Top Inc., Tropicana Products, Döhler, AGRANA Beteiligungs-AG, Archer Daniels Midland Company, Hain Celestial Group, PepsiCo, Südzucker AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Juice Concentrate Market Evolving Landscape
Processing technology and procurement specifications are converging to reshape how concentrate quality is validated and how supply relationships are structured between orchard networks and industrial buyers.
Membrane filtration systems are integrating into pre-evaporation stages to remove enzymatic browning precursors and stabilize color indices across seasonal apple varietal mixes. Mid-sized processors in Washington State and northern Italy are adopting these systems to meet stringent brand-holder specifications for clear concentrate transparency. The technology is integrating quality consistency into supply contracts that previously tolerated seasonal variation, compressing acceptable specification bands and disqualifying traditional thermal-only processors.
REACH chemical safety registrations are expanding disclosure requirements for processing aids used in concentrate production, including enzymatic clarifiers and antifoam agents. European processors must now document full substance inventories to maintain market access, raising compliance costs that favor larger operators with dedicated regulatory affairs functions. Cloudy concentrate exporters to the EU are most affected, as suspended solids stabilization requires additive packages subject to enhanced scrutiny.
Long-term offtake agreements are replacing spot-market purchasing for industrial beverage clients seeking supply security amid orchard yield volatility. Major carbonated drink manufacturers in China and the United States are locking in three-to-five-year contracts with fixed-volume escalators, transferring price risk to processors in exchange for guaranteed allocation. This pattern is most visible in the Pacific Northwest, where processor investments in controlled-atmosphere storage capacity enable contract fulfillment across biennial apple crop cycles.
Apple Juice Concentrate Market Segmentation
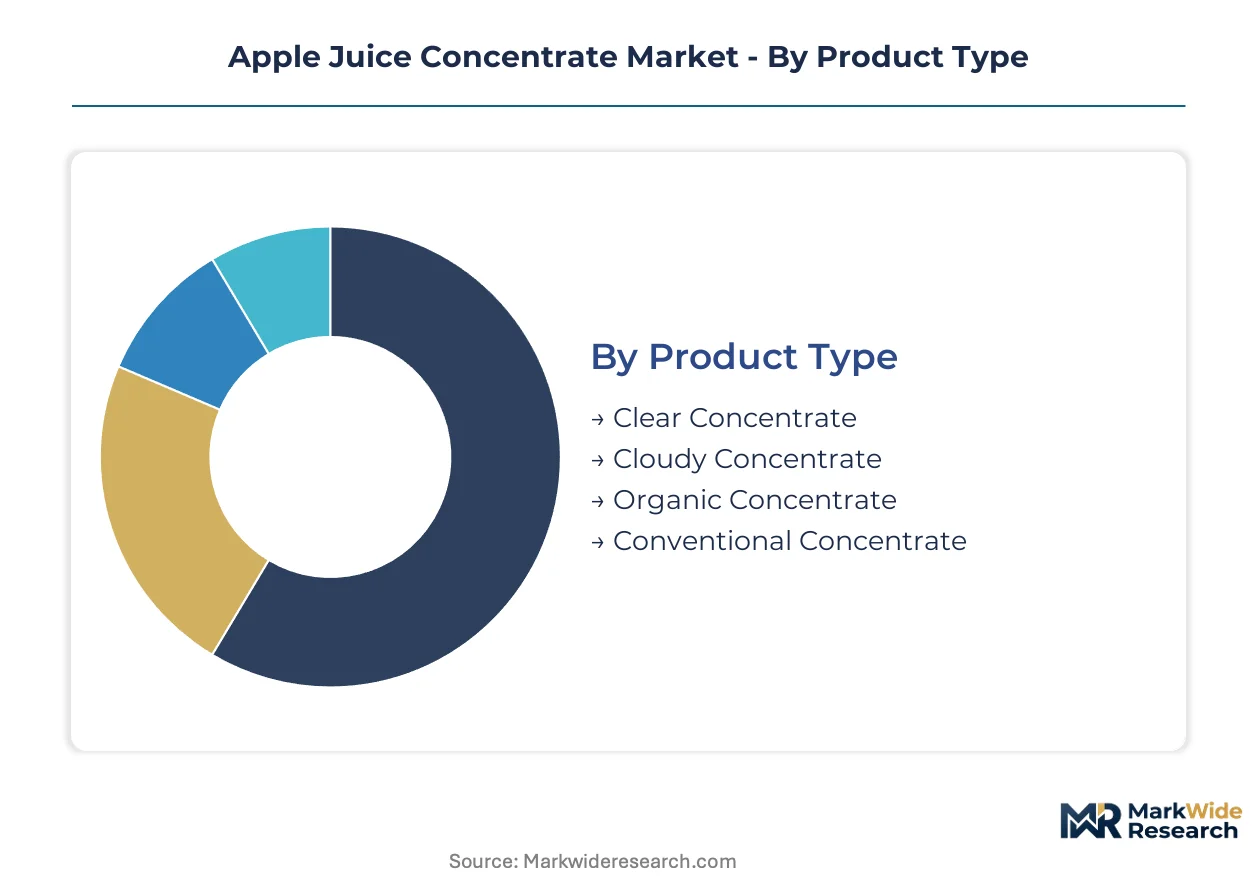
Apple juice concentrate buyers segment procurement by functional specification, application requirements, and logistics configuration. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier selection criteria across industrial and retail channels.
Product Type:
Clear concentrate buyers prioritize color stability and enzymatic clarity for transparent beverage applications, while organic concentrate purchasers absorb certification premiums for clean-label positioning.
- Clear Concentrate:Clarified to remove suspended solids and pectin, achieving transparency specifications below 50 nephelometric turbidity units. Carbonated soft drink manufacturers in China and the United States anchor procurement volumes, driven by FDA and EU labeling disclosure tightening for added sugars.
- Organic Concentrate:Sourced from orchards under third-party organic certification with full traceability documentation. European and North American confectionery manufacturers expand procurement to replace synthetic sweeteners in premium product lines, absorbing 15-25% price premiums for certification integrity.
- Cloudy Concentrate:Retains apple solids for mouthfeel in nectar-style applications.
- Conventional Concentrate:Standard grade without organic certification, serving cost-sensitive industrial formulations.
Clear concentrate leads volumes today; organic concentrate is gaining share fastest.
End Use:
Application-driven formulation requirements split procurement between high-volume beverage sweetening and specialized texture demands in prepared foods.
- Beverages:Dominant consumption channel spanning carbonated drinks, still juices, and functional wellness formulations. Reformulation campaigns across Chinese domestic brands and multinational carbonated manufacturers pull concentrate into expanded natural sweetener roles as cane sugar reduction mandates intensify.
- Sauces:Asian cooking sauces and European prepared foods leverage cloudy concentrate variants for viscosity and suspended solids that signal authenticity. Texture differentiation commands premium shelf placement in ethnic food aisles and private-label retail programs.
- Bakery Products:Humectant and browning agent functions in industrial baking.
- Confectionery:Fruit-based sweetening in premium candy and chocolate applications.
Beverage applications command the largest procurement volumes; sauces demonstrate the steepest expansion trajectory among food manufacturing segments.
Packaging Type:
Logistics economics and contamination risk tolerance determine container selection, with aseptic requirements escalating for distant supply chains.
- Drums:Steel or plastic drums with aseptic liners dominate industrial-scale procurement for beverage and sauce manufacturers. Standard 250-275 kg net weight configurations optimize palletization for ocean freight from Polish and Chinese processing clusters to European and North American destinations.
- Bulk Containers:Flexitanks and ISO tank containers serve multinational beverage clients with dedicated offtake agreements. Long-term contracts with fixed-volume escalators increasingly specify bulk delivery to controlled-atmosphere storage facilities, transferring price risk to processors.
- Cartons:Retail-oriented smaller formats for foodservice and ingredient repackaging.
- Pouches:Flexible packaging for niche artisanal and specialty food manufacturers.
Drum shipments handle the majority of industrial volumes; bulk containers are climbing fastest as contract structures consolidate procurement.
Distribution Channel:
Customer scale and technical service requirements fragment channel structures between relationship-driven direct supply and transactional wholesale intermediation.
- Wholesale Distributors:Regional intermediaries aggregate smaller food manufacturing accounts and provide technical specification matching. Polish and Pacific Northwest processors rely on distributor networks to access mid-sized European and North American bakery and confectionery clients lacking direct procurement infrastructure.
- Direct Sales:Multinational beverage manufacturers negotiate three-to-five-year offtake agreements directly with processors, locking in volume allocation and quality specifications. This channel captures the largest individual contract values and demands dedicated regulatory affairs support for dual FDA-EU certification compliance.
- Online Retail:Emerging channel for artisanal and small-batch food producers.
- Supermarkets:Limited retail ingredient sales for consumer repurchase.
Wholesale distributors move the widest customer count; direct sales channels are expanding most quickly as procurement centralizes among large beverage manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Northwest orchard networks anchor industrial concentrate flows, with Washington State processors leveraging controlled-atmosphere storage to fulfill multi-year beverage contracts. Chinese and Polish processing clusters dominate clear concentrate exports, while European organic certification premiums reshape procurement patterns across destination markets.
United States
Beverage manufacturers in California and Texas are expanding natural sweetener procurement as FDA nutrition labeling tightens added sugar disclosure requirements. The EPA oversees processing emissions compliance for evaporative facilities. Pacific Northwest processors in Washington State are investing in membrane filtration systems to meet brand-holder transparency specifications for clear concentrate.
China
Domestic beverage brands in Shanghai and Guangdong are reformulating recipes to reduce cane sugar content under national sugar-reduction guidelines. GB standards for fruit-derived ingredients segment market access pathways for exporters. Shandong Province processing clusters are scaling bulk concentrate output for carbonated drink manufacturers seeking long-term offtake security.
Poland
European confectionery manufacturers are absorbing organic certification premiums to replace synthetic sweeteners in premium product lines. EU F-Gas Regulation compliance mandates accelerate capital upgrades for lower-emission evaporative processing. Mazovia region processors are leveraging backward integration into orchard networks to sustain year-round supply consistency for industrial buyers.
Germany
REACH chemical safety registrations expand disclosure requirements for enzymatic clarifiers and antifoam agents used in concentrate production. ECHA compliance costs favor larger operators with dedicated regulatory affairs functions. Bavarian processors are deploying renewable-powered evaporation systems to qualify for EU Green Deal sustainability-linked procurement preferences.
India
Domestic consumption of packaged beverages is expanding in Maharashtra and Karnataka as foodservice channels formalize. BIS standards for fruit-derived ingredients create certification pathways for exporters establishing compliant cold-chain logistics. Gujarat-based distributors are aggregating mid-sized bakery and confectionery accounts lacking direct procurement infrastructure.
Apple Juice Concentrate Market Competitive Landscape
Global majors compete with regional champions across orchard network control and flavor-system customization. The vendor base clusters around three operational models: Pacific Northwest processors with captive apple supply, European operators with backward integration into fruit processing, and multinational ingredient houses competing on formulation services. Two competitive moves dominate: long-term offtake agreements transferring price risk to processors, and membrane filtration technology licensing reshaping quality specification bands.
Within the orchard-integrated tier, Tree Top Inc. and AGRANA Beteiligungs-AG exemplify contrasting geographic anchoring strategies. Tree Top occupies a position tied to Pacific Northwest controlled-atmosphere storage capacity, while AGRANA represents European backward integration into fruit processing. Döhler sits within the formulation-services archetype, competing on flavor-system customization for multinational beverage clients seeking regulatory compliance support across FDA and EU natural-claim documentation requirements.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Tree Top Inc. |
| Tropicana Products |
| Döhler |
| AGRANA Beteiligungs-AG |
| Archer Daniels Midland Company |
| Hain Celestial Group |
| PepsiCo |
| Südzucker AG |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between organic and conventional concentrate tiers generates parallel supply chain configurations, with organic premiums of 15-25 percent anchoring dedicated cold-chain logistics and full-traceability orchard networks while conventional grades flow through cost-optimized bulk distribution channels in China and Poland.
Pricing Analysis
Input-cost pass-through from Pacific Northwest and Polish fresh apple prices dominates processor margin dynamics, with poor harvest years compressing returns across all tiers. Three-tier pricing structure across premium organic, standard clear, and economy conventional levels reflects certification integrity and color stability specifications. Pricing pressure stems from apple cider vinegar substitution in wellness beverages, eroding volumes in the highest-margin functional segment. Multinational beverage manufacturers exhibit lowest price sensitivity due to long-term offtake contracts, while mid-sized bakery accounts remain most exposed to spot-market volatility.
Supply Chain Analysis
Fresh apple supply rests on Pacific Northwest orchards, Polish processing clusters, and Shandong Province operations, with each node exhibiting distinct harvest timing and varietal specialization. Water recovery systems, membrane filtration equipment, and aseptic packaging materials constitute critical capital dependencies. Single-source vulnerability concentrates in Chinese and Polish clear concentrate exports, creating allocation risk for multinational clients during climatic disruptions. Distribution runs through drum and bulk container configurations to controlled-atmosphere storage facilities, with direct sales channels displacing wholesale intermediation among large beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in organic certification premiums and membrane filtration yield improvements, as downstream reformulation campaigns sustain demand pull for natural sweetener alternatives.
For Market Incumbents: Anchor supply security through backward integration into controlled-atmosphere storage capacity across biennial crop cycles, while defending against apple cider vinegar substitution by expanding flavor-system customization services for wellness-positioned beverage clients. Prioritize EU F-Gas Regulation compliance investments to capture sustainability-linked procurement preferences from major retail private-label programs. For New Entrants and Emerging Players: The 15-25 percent premium gap between organic and conventional tiers opens viable entry points in India's underpenetrated juice and nectar markets, where BIS certification pathways remain sparsely contested. Target Gujarat-based distributor aggregation of mid-sized bakery accounts lacking direct procurement infrastructure, leveraging compliant cold-chain logistics as the primary go-to-market wedge. For Investors and Strategic Acquirers: Consolidation pressure builds where evaporator technician shortages extend commissioning timelines and dual certification burdens strain quality assurance bandwidth at sub-scale processors. Five-to-ten year viability favors operators with dedicated regulatory affairs functions and renewable-powered evaporation assets. Watch membrane filtration technology licensing deals as inflection signals for quality-specification band compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Networks | Pacific Northwest processors secure year-round supply consistency despite biennial crop fluctuations. |
| Membrane Filtration Technology Deployment | Washington State operators meet brand-holder transparency specifications for clear concentrate applications. |
| EU Green Deal Alignment Investment | Bavarian processors qualify for sustainability-linked procurement from retail private-label programs. |
| Long-term Offtake Agreement Structuring | Chinese beverage manufacturers lock in volume allocation while transferring price risk to processors. |
| BIS Certification Pathway Establishment | Exporters access Maharashtra and Karnataka packaged beverage expansion through compliant cold-chain logistics. |
Research Methodology
Direct dialogue with beverage formulation executives, fruit processing plant managers, cold-chain logistics operators, and confectionery procurement leads grounded qualitative insights, validated against customs trade records, FDA nutrition labeling filings, EU F-Gas Regulation compliance databases, and orchard yield statistics from Washington State and Mazovia region agricultural bureaus. Bottom-up volume estimates from individual processor capacities and top-down demand triangulation from end-use consumption patterns were cross-referenced to establish market sizing.
Segment-level value outputs across product type, end use, packaging configuration, and distribution channel dimensions were modeled through the projection horizon, with CAGRs derived from historical growth trajectory analysis and forward-looking regulatory impact assessment. Forecast inputs incorporated apple varietal mix shifts, evaporative processing yield efficiency curves, and sugar-reduction guideline implementation timelines in China and the United States.
Caveats apply where Pacific Northwest weather patterns, EU REACH disclosure requirement expansions, or apple cider vinegar substitution rates could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Dairy Based Beverages Market
Beverages
Blackstrap Molasses Market
Beverages
Aloe Vera Juice Market
Beverages
United Kingdom Energy Drink Market
Beverages
Sparkling Water Machine Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
Plant Based Protein Beverages Market
Beverages
Coconut Milk Beverages Market
Beverages
China Orange Juice Market
Beverages
Europe Probiotic Drinks Market
Beverages
Beverage Dispenser Market
Beverages
Tonic Water Market
Beverages
Beverage Cooler Market
Beverages
Fiber Fortified Beverages Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Europe Smoothies Market