
 United States Borescope Market | 2026-2036
United States Borescope Market Size, Share, and Industry Trends Forecast 2026-2036
United States Borescope Market Analytics
High-definition imaging specifications is unwinding legacy product lines across the United States borescope landscape. Olympus America Inc. leverages its optical heritage to dominate premium videoscope installations at major airline MRO facilities. Waygate Technologies anchors industrial energy contracts through captive supply of remote visual inspection systems. Gradient Lens Corporation specializes in rigid borescope configurations for precision manufacturing quality control.
A borescope is a remote visual inspection instrument consisting of an eyepiece or display, an optical or digital image relay system, and an insertion tube typically ranging from 2.8 mm to 10 mm in diameter, engineered to access confined cavities without disassembly. The device transmits real-time imagery to assess surface integrity, corrosion, or foreign object debris in turbine engines, process piping, and welded joints. Flexible videoscopes lead the product type hierarchy due to articulation range advantages in complex geometries, while wireless technology segments capture expanding share as maintenance teams prioritize mobility and data integration. Robotic borescopes represent the fastest-growing technology category, though optical systems retain entrenched positions in nuclear and aerospace certification pathways where analog redundancy matters.
FAA airworthiness directives mandate periodic borescope inspections for commercial turbine engines, creating baseline demand cycles tied to flight-hour regulations. OSHA lockout/tagout standards and EPA leak detection protocols in petrochemical facilities further shape equipment specifications and operator training requirements. Stakeholders must monitor evolving NDT certification tiers and AI-enabled defect recognition thresholds as procurement criteria shift from hardware acquisition toward integrated inspection data platforms.
Market Dynamics
High-definition imaging specifications are unwinding legacy product lines across the United States borescope landscape, forcing manufacturers to recalibrate R&D budgets toward digital sensor integration and AI-enabled defect recognition systems.
Growth Catalysts
- FAA Airworthiness Directives:Periodic borescope inspections for commercial turbine engines create baseline demand cycles tied to flight-hour regulations, locking in recurring equipment procurement from airline MRO facilities.
- OSHA Lockout/Tagout Standards:Petrochemical facilities face mandatory visual verification protocols before equipment restart, expanding industrial borescope deployment across refinery and pipeline maintenance operations.
- Texas Energy Infrastructure Cluster:Concentrated oil and gas processing capacity along the Gulf Coast sustains procurement volumes for remote visual inspection systems in high-temperature, high-pressure applications.
Market Restraints
- CMOS Sensor Supply Concentration:Dependence on Asian semiconductor foundries for image sensor components creates vulnerability to trade policy shifts and shipping disruptions.
- Nuclear Certification Pathway Rigidity:Analog optical borescopes retain entrenched positions in nuclear reactor inspection protocols where digital redundancy faces regulatory skepticism, slowing technology transition.
- Trained Operator Scarcity:FAA and OSHA both mandate certified personnel for borescope operations, constraining deployment velocity in maintenance organizations with limited NDT training budgets.
Strategic Opportunities
- Robotic Borescope Integration:Autonomous articulation and AI-guided defect detection converge to enable unmanned inspection of hazardous confined spaces in chemical processing and nuclear facilities.
- California Defense Manufacturing:Aerospace component suppliers in Southern California represent underpenetrated demand for precision rigid borescopes in quality control of turbine blade castings.
- Wireless Data Platform Migration:Maintenance teams prioritize mobility and cloud-integrated inspection records, opening white space for borescope OEMs to bundle hardware with subscription-based data management services.
Industry Challenges
- ASNT NDT Certification Timelines:Operator qualification requirements extend 12-18 months, compressing workforce scalability for inspection service providers responding to demand surges.
- Legacy System Integration Friction:Digital videoscopes must interface with existing maintenance management software used by major airlines and energy operators, complicating deployment roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Borescope Market |
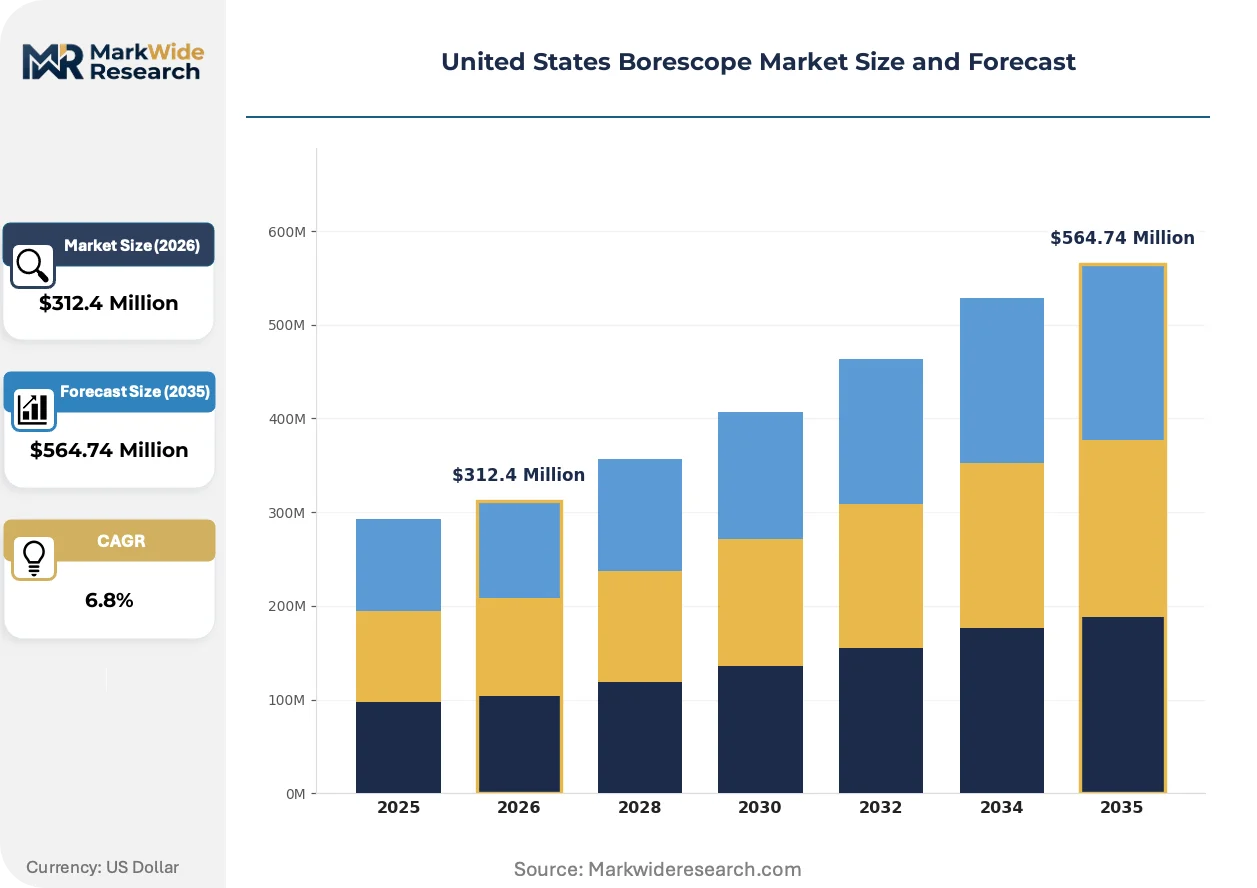
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
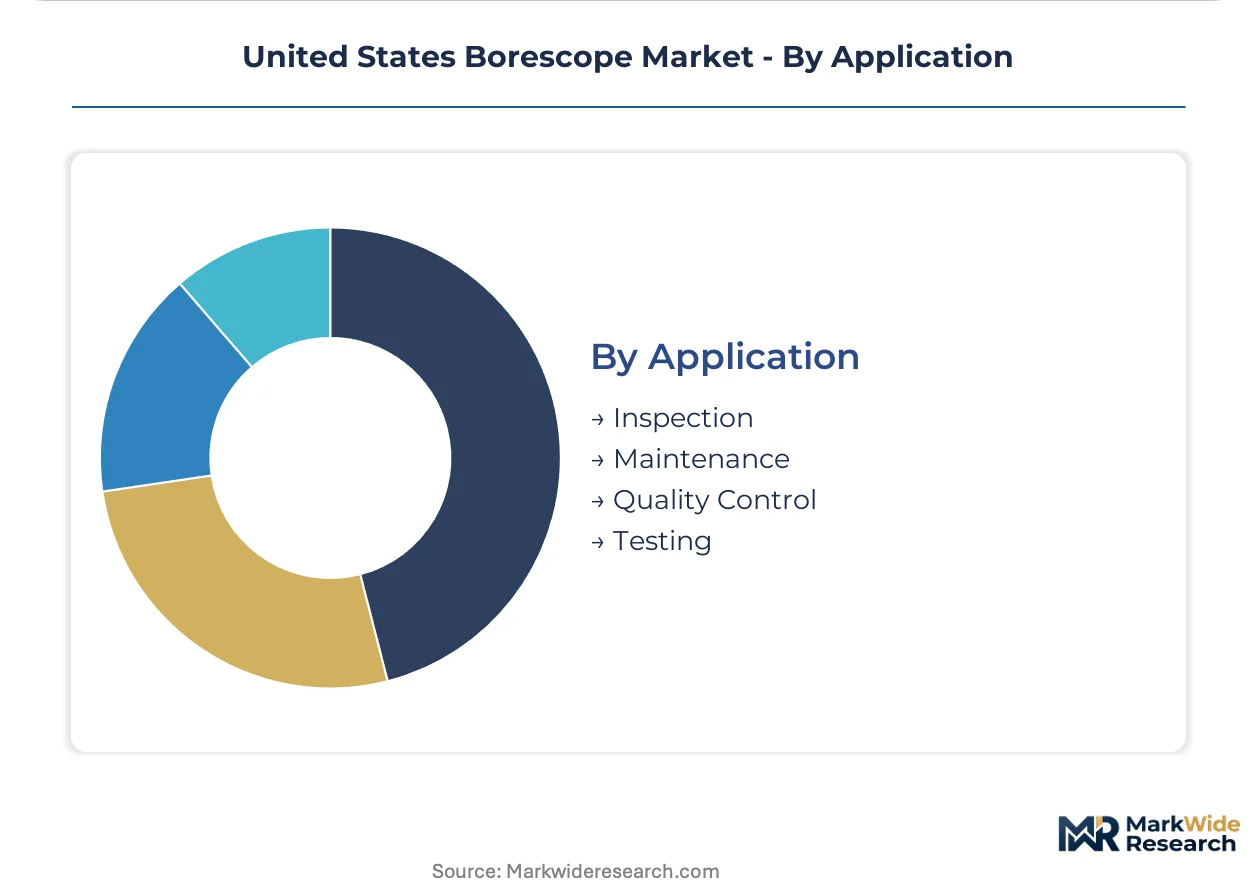
| Segmentation | Product Type: Rigid, Flexible, Videoscope, Fiberscope End User: Aerospace, Automotive, Manufacturing, Energy Technology: Optical, Digital, Wireless, Robotic Application: Inspection, Maintenance, Quality Control, Testing |
| Companies Covered | USA Borescopes, Olympus America Inc., PCE Instruments, JME Technologies, Gradient Lens Corporation, Lenox Instrument Company, ViewTech Borescopes, Waygate Technologies, GE Inspection Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Borescope Market Evolving Landscape
Three distinct vectors are actively reshaping borescope technology trajectories: sensor architecture evolution, regulatory digitization mandates, and procurement model restructuring toward integrated service platforms.
4K CMOS sensor arrays with enhanced low-light sensitivity are decomposing the traditional hierarchy between optical and digital inspection systems. Major airline MRO facilities in Texas and California are accelerating replacement cycles for analog videoscopes. This technology compression is collapsing the price-performance gap that previously protected legacy equipment categories.
FAA advisory circulars on engine condition monitoring are tightening documentation standards for visual inspection records. Operators must now archive high-resolution imagery with searchable metadata for audit trails. Commercial aviation maintenance organizations are responding by standardizing on borescope platforms with embedded GPS tagging and automated report generation.
Asset owners are unbundling after-sales service contracts from initial hardware purchases, instead procuring inspection capability through multi-year managed service agreements. Energy sector buyers in the Permian Basin and Gulf Coast refineries are driving this shift, favoring vendors who guarantee uptime and data integrity over discrete equipment transactions. This behavioral pivot is most visible among mid-size independent oil producers with limited in-house NDT departments.
United States Borescope Market Segmentation
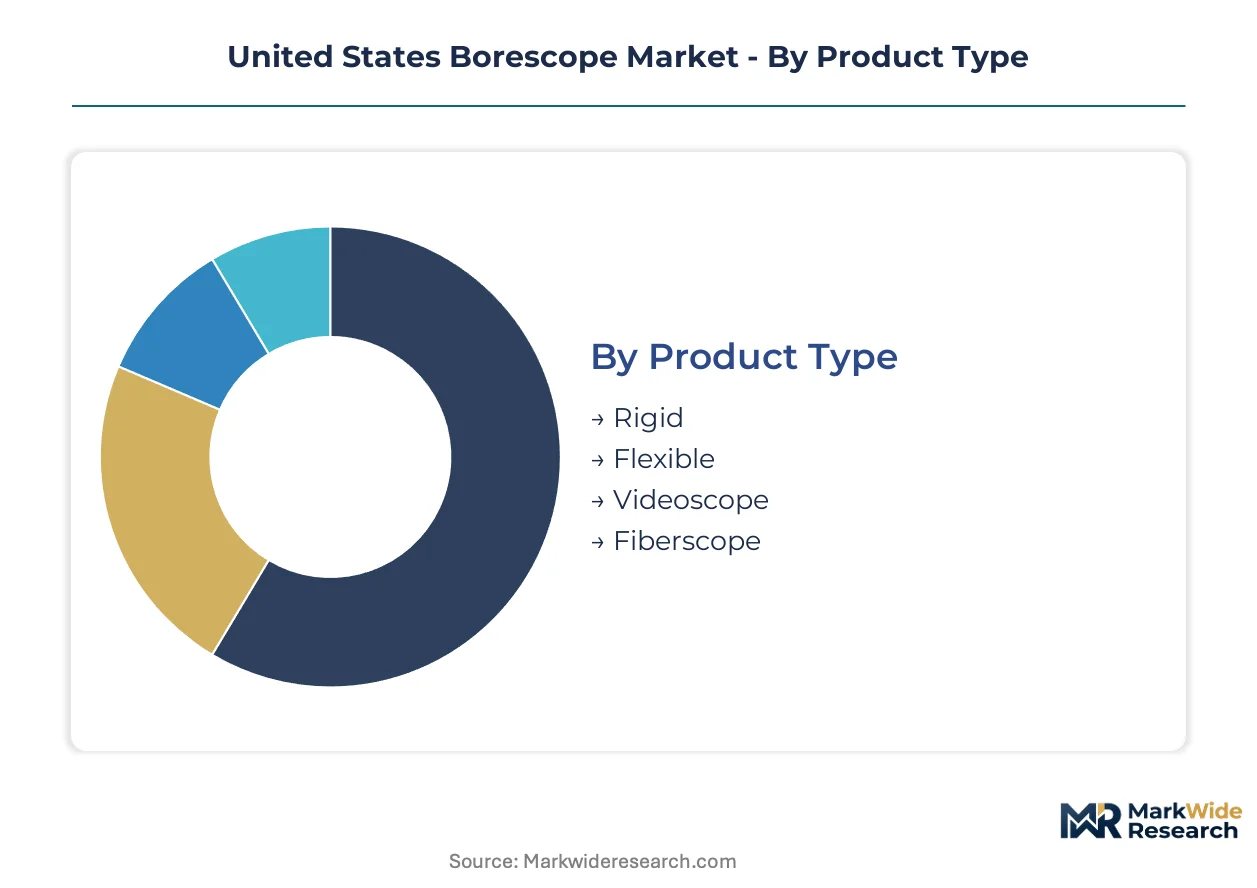
Borescope procurement patterns diverge sharply across product architectures, end-use industries, and technology tiers. FAA-mandated inspection protocols and OSHA safety verification requirements create distinct specification demands that reshape how manufacturers configure their portfolios.
Product Type:
Margin pools concentrate in articulation mechanisms and image sensor integration, where premium pricing separates inspection-grade systems from commodity visual probes.
- Videoscope:Articulating insertion tubes with integrated CMOS sensors deliver real-time high-definition imagery to external displays. Major airline MRO facilities in Texas and California prioritize these systems for turbine engine borescope inspections under FAA airworthiness directives.
- Flexible:Fiber-optic or digital image relay systems navigate complex geometries through steerable distal tips. Petrochemical facilities along the Gulf Coast deploy these for heat exchanger and pipeline inspections where rigid access proves impossible.
- Rigid:Straight-line optical borescopes with fixed eyepieces or camera adapters serve precision manufacturing quality control in Southern California aerospace component shops.
- Fiberscope:Bundled fiber-optic image transmission in sub-4mm diameters accesses extremely confined cavities in automotive fuel injection systems and small-bore hydraulic lines.
The dominant share belongs to Videoscope, while Robotic (under Technology) is closing the gap fastest through autonomous deployment in hazardous environments.
End User:
Volume concentration tracks regulatory inspection frequency, with flight-hour mandates and pressure vessel certification cycles dictating equipment refresh rates.
- Aerospace:Commercial airlines and third-party MRO providers execute periodic borescope inspections per FAA engine condition monitoring advisory circulars. High-resolution documentation requirements with searchable metadata archives drive platform standardization.
- Energy:Refinery operators and pipeline maintenance contractors deploy remote visual inspection systems for OSHA lockout/tagout verification before equipment restart. Gulf Coast processing clusters sustain concentrated procurement volumes.
- Manufacturing:Precision casting and machining operations utilize rigid borescopes for surface integrity verification in turbine blade production and welded joint assessment.
- Automotive:Engine assembly plants and aftermarket service networks employ compact flexible systems for cylinder bore examination and transmission internal inspection.
Aerospace commands the largest equipment spend, though Energy is expanding most quickly through mid-size independent oil producers adopting managed inspection services.
Technology:
Cost tier differentiation separates legacy analog certification pathways from digital platforms competing on data integration and mobility.
- Digital:CMOS sensor arrays with 4K resolution and enhanced low-light sensitivity are collapsing the price-performance gap that previously protected optical systems. Major airline facilities accelerate replacement cycles for analog videoscopes.
- Robotic:Autonomous articulation with AI-guided defect detection enables unmanned inspection of hazardous confined spaces in chemical processing and nuclear facilities. This segment shows the steepest expansion trajectory as maintenance teams prioritize operator safety.
- Optical:Pure lens-and-prism systems retain entrenched positions in nuclear reactor inspection protocols where regulatory skepticism toward digital redundancy slows technology transition.
- Wireless:Bluetooth and Wi-Fi-enabled image transmission supports cloud-integrated inspection records and mobile tablet viewing, opening white space for subscription-based data management services.
Digital platforms hold the installed base advantage, while Wireless architectures are gaining share fastest through maintenance team mobility priorities.
Application:
Customer type stratification separates scheduled compliance-driven procurement from event-triggered spot purchases.
- Inspection:Routine visual verification of internal surfaces for corrosion, cracking, or foreign object debris in turbine engines and process piping. FAA and OSHA mandates create recurring demand cycles.
- Maintenance:Condition-based intervention decisions using borescope imagery to determine component repair versus replacement. Energy sector buyers increasingly procure through uptime-guarantee service contracts rather than discrete equipment.
- Quality Control:Manufacturing process verification for casting integrity, weld penetration, and machined surface finish in aerospace component production.
- Testing:R&D and failure analysis applications in materials laboratories and product development facilities.
Inspection generates the highest procedure volume, while Maintenance is climbing fastest through outcome-based service model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German borescope manufacturers export precision optical systems to United States maintenance facilities, while domestic assembly operations in Texas and California integrate Asian-sourced CMOS sensors into finished inspection platforms.
Texas
Gulf Coast petrochemical complexes and independent oil producers drive procurement volumes for high-temperature remote visual inspection systems. OSHA lockout/tagout verification mandates require visual confirmation before equipment restart, expanding deployment across refinery turnaround operations. Houston-area energy infrastructure clusters sustain concentrated demand for videoscope rentals and managed inspection services.
California
Southern California aerospace component suppliers generate precision rigid borescope demand for turbine blade casting quality control. FAA airworthiness directives on engine condition monitoring tighten documentation standards, pushing MRO facilities toward 4K digital platforms with automated report generation. Los Angeles Basin defense manufacturing subcontractors represent underpenetrated demand for optical inspection systems.
Pacific Northwest
Boeing manufacturing and maintenance operations in Washington State anchor commercial aviation borescope procurement tied to flight-hour inspection cycles. EPA leak detection protocols in regional chemical processing facilities supplement aerospace demand with industrial applications. Seattle-Tacoma aerospace supplier networks require portable wireless systems for field deployment.
Southeast
Florida and Georgia aviation MRO hubs execute periodic turbine engine inspections per FAA mandates, generating recurring equipment refresh cycles. Growing automotive manufacturing in Tennessee and South Carolina employs flexible borescopes for cylinder bore examination and transmission internal verification. Charleston and Savannah port facilities drive marine engine inspection demand.
Midwest
Illinois and Michigan automotive assembly plants and tier-one suppliers utilize compact fiberscopes for fuel injection system quality control. Ohio-based power generation facilities deploy rigid borescopes for steam turbine maintenance under FERC reliability standards. Chicago-area industrial distribution channels aggregate procurement for nationwide maintenance service providers.
United States Borescope Market Competitive Landscape
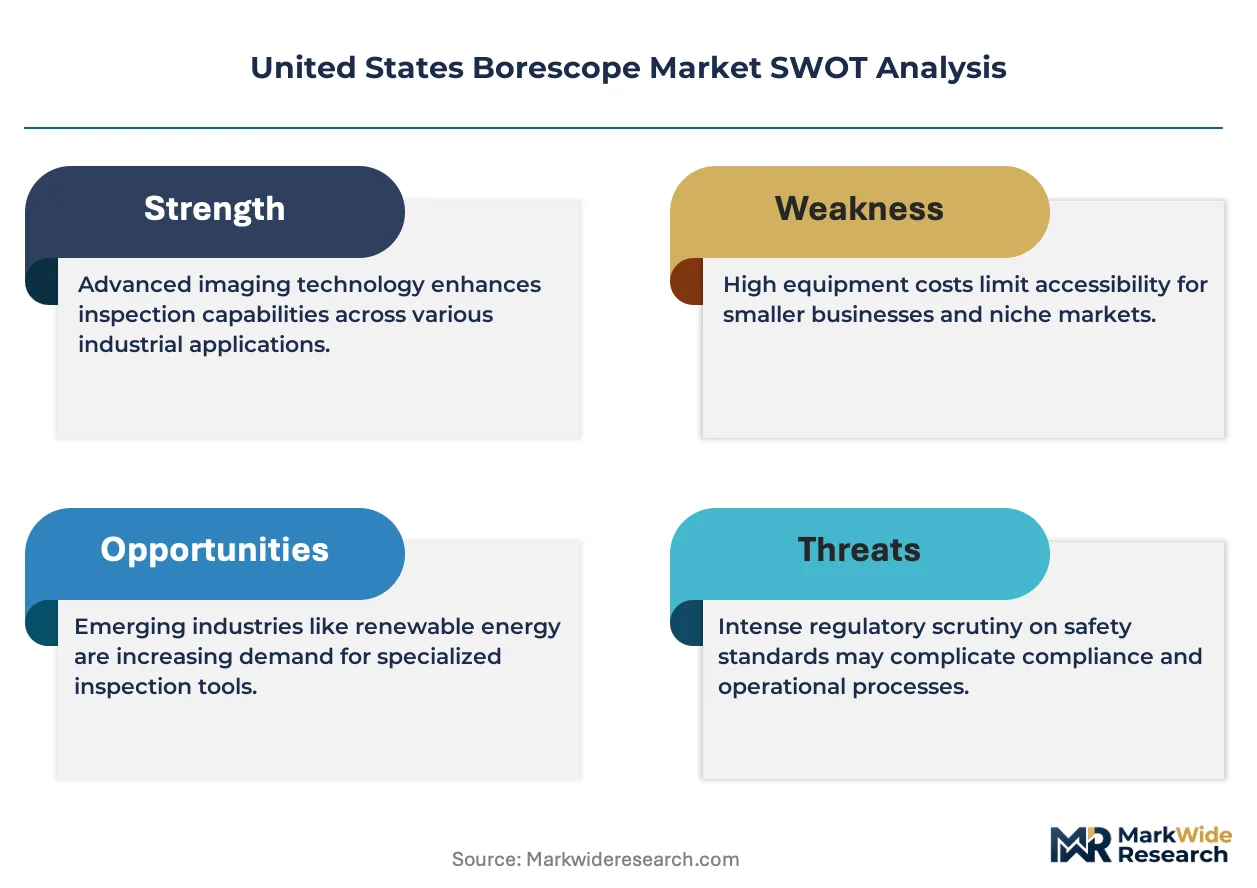
Listed leaders compete with private specialists across technology tier and certification pathway. The United States borescope landscape shows moderate consolidation at the premium videoscope tier alongside fragmentation in specialized rigid and fiberscope segments. Three strategic archetypes dominate: optical heritage multinationals leveraging brand recognition in aerospace certification channels, industrial instrumentation conglomerates bundling inspection systems with broader NDT portfolios, and regional specialists capturing price-sensitive rental and spot-purchase demand. Competitive moves concentrate on sensor technology licensing partnerships and backward integration into CMOS supply arrangements.
Among United States-based specialists, Gradient Lens Corporation and Lenox Instrument Company exemplify the precision rigid borescope archetype serving manufacturing quality control applications. Waygate Technologies anchors the industrial energy contract segment through captive supply of remote visual inspection systems. Olympus America Inc. occupies the premium videoscope position at major airline MRO facilities, representing the optical heritage multinational archetype.
| Leading Market Players |
|---|
| USA Borescopes |
| Olympus America Inc. |
| PCE Instruments |
| JME Technologies |
| Gradient Lens Corporation |
| Lenox Instrument Company |
| ViewTech Borescopes |
| Waygate Technologies |
| GE Inspection Technologies |
| Others |
Value Network & Pricing Analysis
Managed inspection service contracts lock in multi-year supply access for energy sector buyers while fixing price visibility for borescope OEMs seeking recurring revenue stability. This contractual pattern concentrates procurement leverage among Gulf Coast refinery operators and Permian Basin independents, compressing margins for hardware-only vendors.
Pricing Analysis
The 4K CMOS-to-optical pricing gap is narrowing as digital sensor costs fall and airline MRO facilities accelerate replacement cycles. Three-tier pricing structure across premium FAA-certified, standard industrial-grade, and economy rental tiers separates inspection-grade systems from commodity probes. Cost compression in the standard tier is intensifying because Asian CMOS foundries are expanding capacity. Independent oil producers show highest price sensitivity, while major airline MROs prioritize certification compliance over unit cost.
Supply Chain Analysis
Port congestion on the Los Angeles-Long Beach corridor elevates inbound logistics costs for Japanese and German optical component shipments destined for Texas and California assembly facilities. CMOS sensor supply concentrates in Taiwan, South Korea, and China, while precision optical glass draws from Germany and Japan. Single-source vulnerability in 4K sensor foundries creates exposure to trade policy shifts. Distribution runs through Houston and Los Angeles industrial distribution channels serving energy and aerospace clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States borescope market is recovering from pandemic-depressed airline maintenance cycles, with FAA flight-hour mandates now restoring baseline equipment refresh demand. Fleet expansion and engine shop visit backlogs sustain procurement momentum through the projection horizon.
For Market Incumbents: Shield premium videoscope positions by deepening backward integration into CMOS supply arrangements and securing exclusive sensor allocation contracts. Accelerate FAA certification pathway investments to block emerging entrants from aerospace MRO channels. Lock in long-term managed service agreements with Gulf Coast energy operators before price transparency erodes hardware margins.
For New Entrants and Emerging Players: FAA Part 145 repair station certification fast-tracks market entry for robotic borescope platforms targeting nuclear and chemical processing facilities. White space concentrates in Southern California defense manufacturing subcontractors and mid-size independent oil producers adopting subscription-based inspection services. Go-to-market leverage rests on bundling hardware with cloud-integrated data platforms rather than competing on equipment price.
For Investors and Strategic Acquirers: Capital is best deployed toward precision rigid borescope specialists with entrenched positions in aerospace component quality control. Long-term viability hinges on regulatory digitization mandates expanding addressable inspection procedure volume. Watch ASNT NDT certification wait times as the inflection signal—shortening queues indicate scalable workforce expansion and demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Sensor Supply Agreement | Secures image sensor allocation from Taiwan and South Korea foundries for 4K videoscope production. |
| FAA Certification Fast-Track | Accelerates airworthiness approval for robotic borescope platforms in commercial turbine engine inspection. |
| Managed Service Platform Launch | Bundles hardware with cloud-integrated inspection records for Permian Basin oil producers. |
| Defense Manufacturing Partnership | Captures precision rigid borescope demand from Southern California turbine blade casting suppliers. |
| Wireless Data Integration | Enables mobile tablet viewing and automated report generation for OSHA lockout/tagout verification. |
Research Methodology
The analysis maps videoscope, flexible, rigid, and robotic borescope sub-sectors, each validated through maintenance directors at airline MRO facilities, plant engineers at Gulf Coast refineries, NDT certification trainers, and procurement leads at defense manufacturers. Primary interviews combined with secondary validation from FAA airworthiness directive databases, OSHA enforcement records, SEC 10-K filings of listed instrumentation companies, and customs import data for optical components. Bottom-up equipment shipment estimates and top-down maintenance procedure volume analysis triangulate market sizing.
Consistency checks validated volume and value outputs against external benchmarks including airline fleet expansion projections, refinery turnaround schedules, and NDT technician certification throughput data. The analytical framework models product type, end-use industry, technology tier, and application dimensions across the projection horizon. CAGRs derive from segmented procedure frequency analysis and equipment replacement cycle assumptions. Forecast inputs incorporate flight-hour regulation compliance rates and energy sector capital expenditure patterns.
Underlying assumptions cover sustained FAA mandate enforcement, stable CMOS sensor supply from Asian foundries, and gradual nuclear regulatory acceptance of digital redundancy, with deviation risk concentrated in trade policy disruptions and NDT certification pipeline constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Production Testing Market
Test and Measurement
Diamond Tester Market
Test and Measurement
Volte Testing Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Radiation Tester Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Impedance Tester Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Permeability Testing Machine Market