
 Global Phosphor Plate Scanners Market | 2026-2036
Global Phosphor Plate Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phosphor Plate Scanners Market Foresight
Capital-intensity divergence between high-throughput manufacturers and niche software developers is reorganizing competitive tiers in phosphor plate scanners. PLANMECA OY leverages integrated imaging workflows across Nordic dental markets. DÜRR DENTAL SE anchors European distribution through direct service networks. Envista competes on aftermarket consumables tied to its installed base of photostimulable luminescence systems.
Phosphor plate scanners are electro-optical devices that read latent images stored in photostimulable phosphor plates, typically barium fluorohalide crystals doped with europium, by scanning with a helium-neon laser or solid-state diode array and converting emitted luminescence into digital signals for diagnostic display. Their primary commercial purpose is digitizing radiographic exposures without chemical processing, bridging analog capture infrastructure toward full digital radiography transition. Desktop scanners occupy the highest volume tier among product types due to universal compatibility with existing plate inventories across dental practices. Computed radiography technology leads installed base figures while digital radiography displaces new purchases in premium orthopedic clinics. Veterinary diagnostics application segments are expanding fastest as equine and small-animal practices adopt portable scanner units for field use.
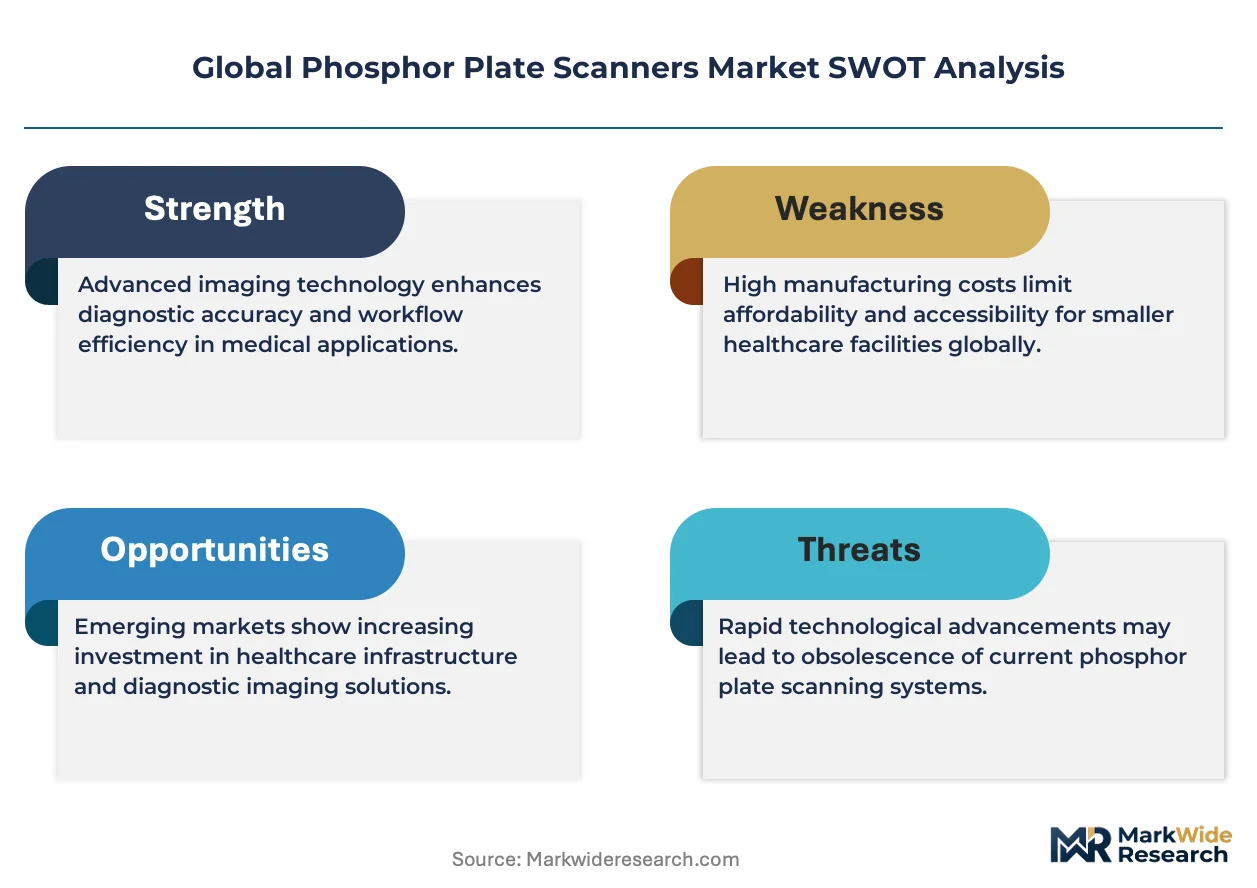
FDA 510(k) premarket notification requirements govern software-driven image enhancement algorithms in US-marketed systems, while EU MDR classification rules impose clinical evidence standards on scanner-plate combinations sold under CE marking. Japan's PMDA maintains distinct electromagnetic compatibility testing protocols that shape product variant strategies for METI-registered devices. Stakeholders must monitor convergence between laser scanning hardware specifications and AI-assisted diagnostic software modules as regulatory scopes overlap across jurisdictions.
Market Dynamics
Computed radiography infrastructure is fragmenting as digital radiography sensors compress replacement cycles and veterinary practices accelerate portable scanner adoption for field diagnostics. This structural tension between legacy fleet maintenance and full-digital transition is reallocating capital across dental, orthopedic, and animal health verticals.
Growth Catalysts
- EU MDR clinical evidence standards:Scanner-plate combinations sold under CE marking now require upgraded documentation, pulling upgrade demand from installed base renewal cycles.
- Veterinary field diagnostics:Equine and small-animal practices across Australia and Brazil are adopting portable scanner units for ambulatory care.
- Barium fluorohalide crystal refinement:Improved europium doping protocols are extending plate reusability cycles in high-throughput diagnostic centers.
Market Restraints
- Solid-state diode array supply:Concentration of laser component manufacturing in East Asian foundries creates input volatility for scanner assembly.
- Digital radiography substitution:Direct-capture sensors are displacing new phosphor plate purchases in premium orthopedic clinics.
- FDA 510(k) software validation:Tightened requirements for image enhancement algorithms extend clearance timelines for algorithm-driven systems.
Strategic Opportunities
- India diagnostic center chains:Franchise networks standardizing on multi-plate scanner configurations create volume aggregation points for equipment vendors.
- AI-assisted diagnostic software modules:Convergence between laser scanning hardware specifications and machine learning image analysis is opening new service revenue streams.
- Southeast Asia dental clinic expansion:Aging populations in Thailand, Vietnam, and Indonesia are driving computed radiography fleet growth.
Industry Challenges
- Helium-neon laser technician scarcity:Specialized maintenance expertise for legacy scanning systems is concentrating in manufacturer service networks.
- Legacy PACS integration:Scanner interoperability with hospital picture archiving systems requires custom middleware development.
- Photostimulable luminescence calibration drift:Plate sensitivity degradation monitoring demands ongoing quality assurance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phosphor Plate Scanners Market |
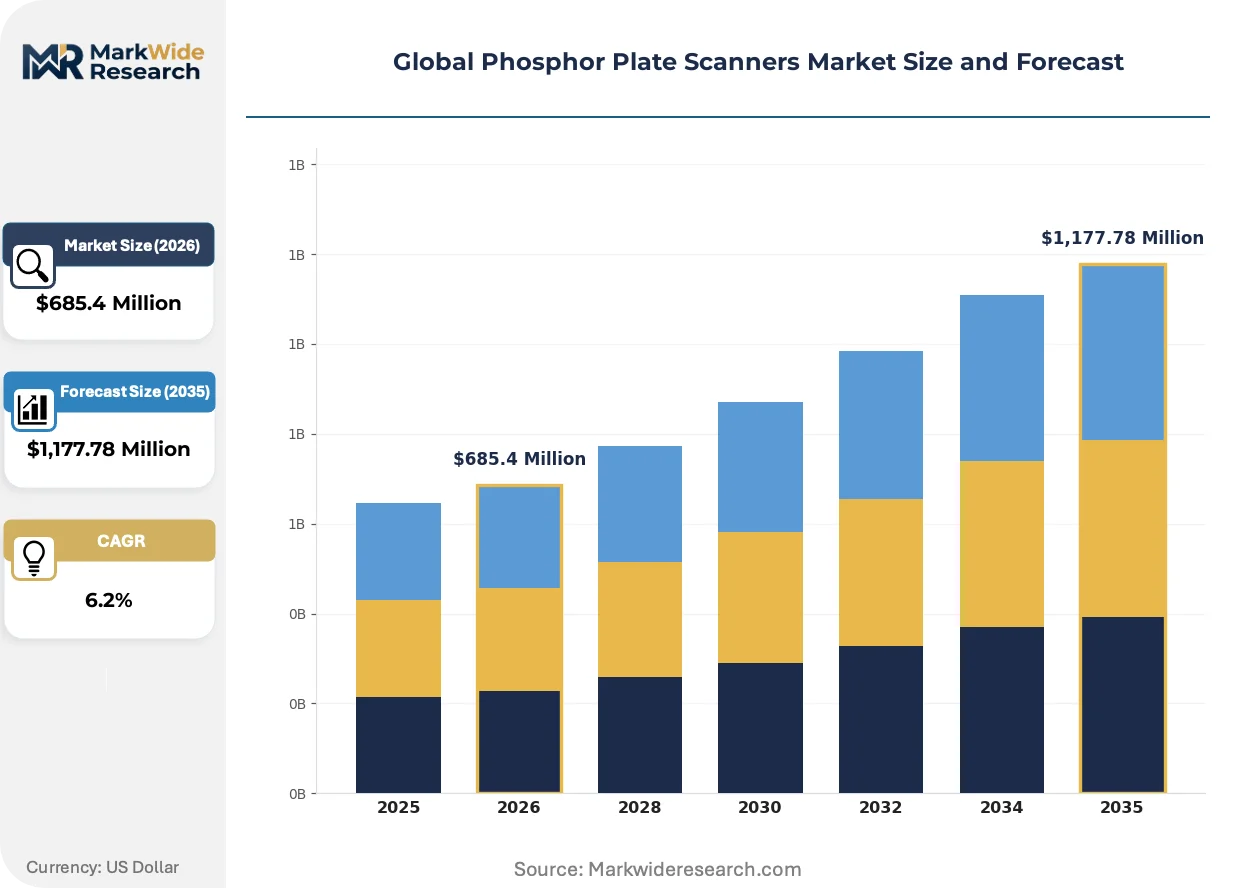
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Scanners, Portable Scanners, Multi-Plate Scanners, High-Resolution Scanners Technology: Computed Radiography, Digital Radiography, Laser Scanning, Photostimulable Luminescence Application: Dental Imaging, Veterinary Diagnostics, Bone Density Analysis, Industrial Non-Destructive Testing End User: Diagnostic Centers, Research Laboratories, Orthopedic Clinics, Quality Control Facilities |
| Companies Covered | PLANMECA OY, Owandy Radiology, ACTEON Group, Carestream Dental LLC, DÜRR DENTAL SE, Apixia Corp, Envista, Dentsply Sirona, DIGIRAY Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phosphor Plate Scanners Market Shifts & Advancements
Scanner hardware is decomposing into modular subsystems as software-defined imaging workflows gain precedence over fixed-function devices. This reconfiguration is altering how vendors monetize equipment, consumables, and diagnostic support services across dental and veterinary channels.
Solid-state diode arrays are decomposing the market position of helium-neon laser scanning architectures. Veterinary practices and mobile diagnostic units are adopting these compact, vibration-resistant modules for field-deployable units. The structural consequence is decomposing the traditional premium tier of fixed-installation scanners into price-competitive portable segments.
Japan's PMDA electromagnetic compatibility testing protocols are reshaping product variant strategies for METI-registered devices. Manufacturers must maintain separate hardware configurations for Japanese market entry, fragmenting production runs and complicating inventory management. Dental equipment distributors are responding by consolidating procurement around PMDA-prevalidated platform designs to streamline regulatory exposure.
Diagnostic center procurement is consolidating around multi-plate scanner configurations with bundled service contracts. Independent dental practices are losing purchasing leverage as chain networks aggregate volume and negotiate direct manufacturer relationships. This concentration is most visible in India's franchise-model diagnostic chains, where standardized equipment specifications are displacing individual practice autonomy in vendor selection.
Global Phosphor Plate Scanners Market Segmentation
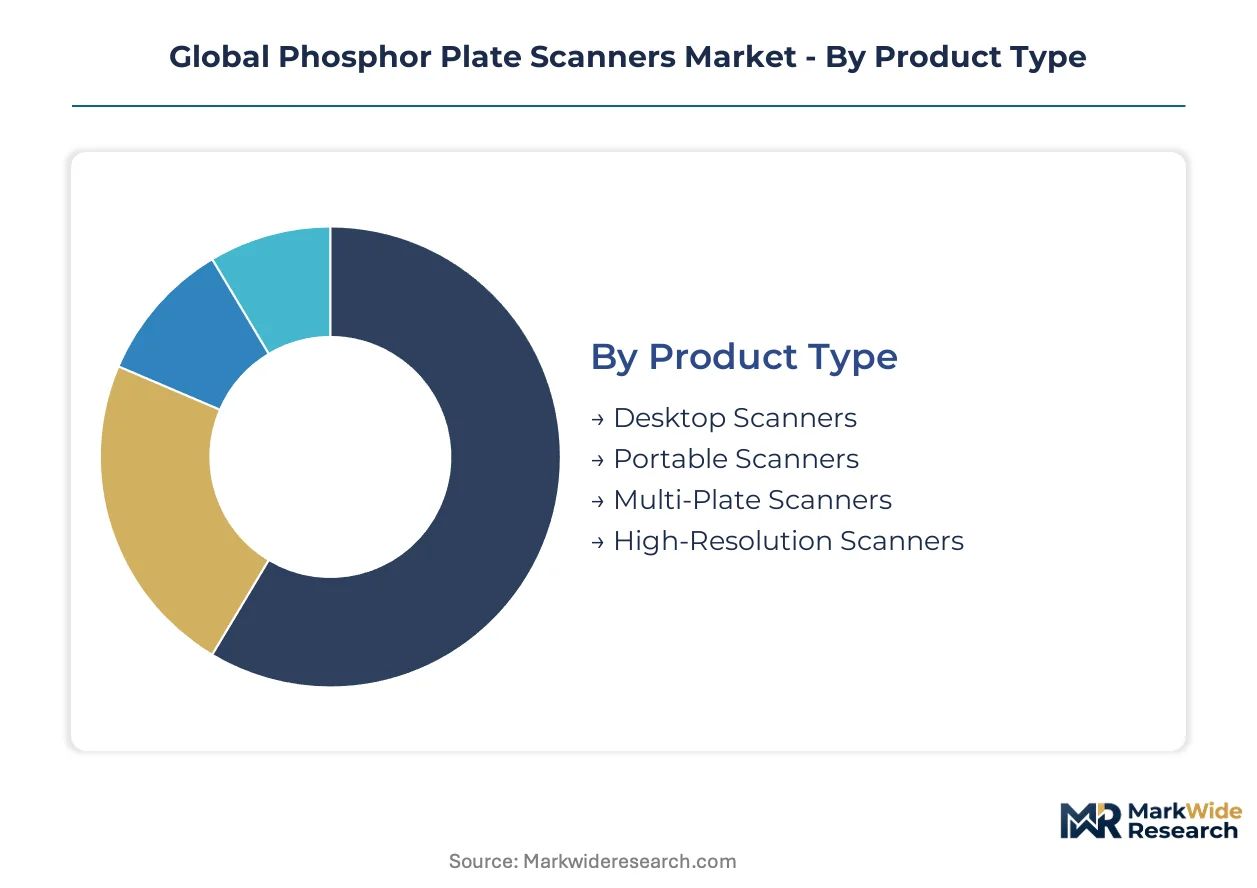
Phosphor plate scanner segmentation reveals divergent margin structures across hardware configurations and technology generations. Equipment vendors calibrate pricing and service bundling differently for each tier, with installed base characteristics determining aftermarket revenue potential.
Product Type:
Margin pools concentrate in multi-plate configurations where service contracts and consumable replenishment generate recurring revenue streams.
- Desktop Scanners:Fixed-installation units with universal plate compatibility dominate dental practice procurement in volume terms. Demand concentrates in India's franchise-model diagnostic chains where standardized equipment specifications override individual practice autonomy in vendor selection.
- Portable Scanners:Battery-powered solid-state diode array systems enable field-deployable veterinary diagnostics. Australian and Brazilian equine practices are adopting these compact, vibration-resistant modules for ambulatory care, compressing replacement cycles in mobile segments.
- Multi-Plate Scanners:High-throughput configurations with automated plate handling serve centralized diagnostic centers.
- High-Resolution Scanners:Specialized units for orthopedic and industrial applications command premium positioning.
Desktop scanners hold installed capacity. Portable scanners are rotating up the share rankings.
Technology:
Volume distribution splits between legacy fleet maintenance and full-digital transition investments across end-use verticals.
- Computed Radiography:Barium fluorohalide crystal systems with europium doping remain the dominant installed base technology. Southeast Asian dental clinics are expanding computed radiography fleets to serve aging populations in Thailand, Vietnam, and Indonesia.
- Digital Radiography:Direct-capture sensors are displacing phosphor plate purchases in premium orthopedic clinics, fragmenting replacement demand.
- Laser Scanning:Helium-neon architectures face technician scarcity constraints.
- Photostimulable Luminescence:Core image capture mechanism underlying computed radiography systems.
Computed radiography maintains installed capacity. Digital radiography is climbing the fastest.
Application:
Customer procurement patterns vary sharply between institutional healthcare settings and mobile service providers.
- Dental Imaging:Intraoral and extraoral radiography digitization represents the largest addressable application. Nordic markets demonstrate integrated imaging workflow adoption through consolidated equipment procurement.
- Veterinary Diagnostics:Equine and small-animal field diagnostics are expanding most quickly as portable scanner adoption accelerates across ambulatory practices.
- Bone Density Analysis:Osteoporosis screening applications in orthopedic settings.
- Industrial Non-Destructive Testing:Quality control applications in manufacturing inspection.
Dental imaging holds installed capacity. Veterinary diagnostics is gaining share fastest.
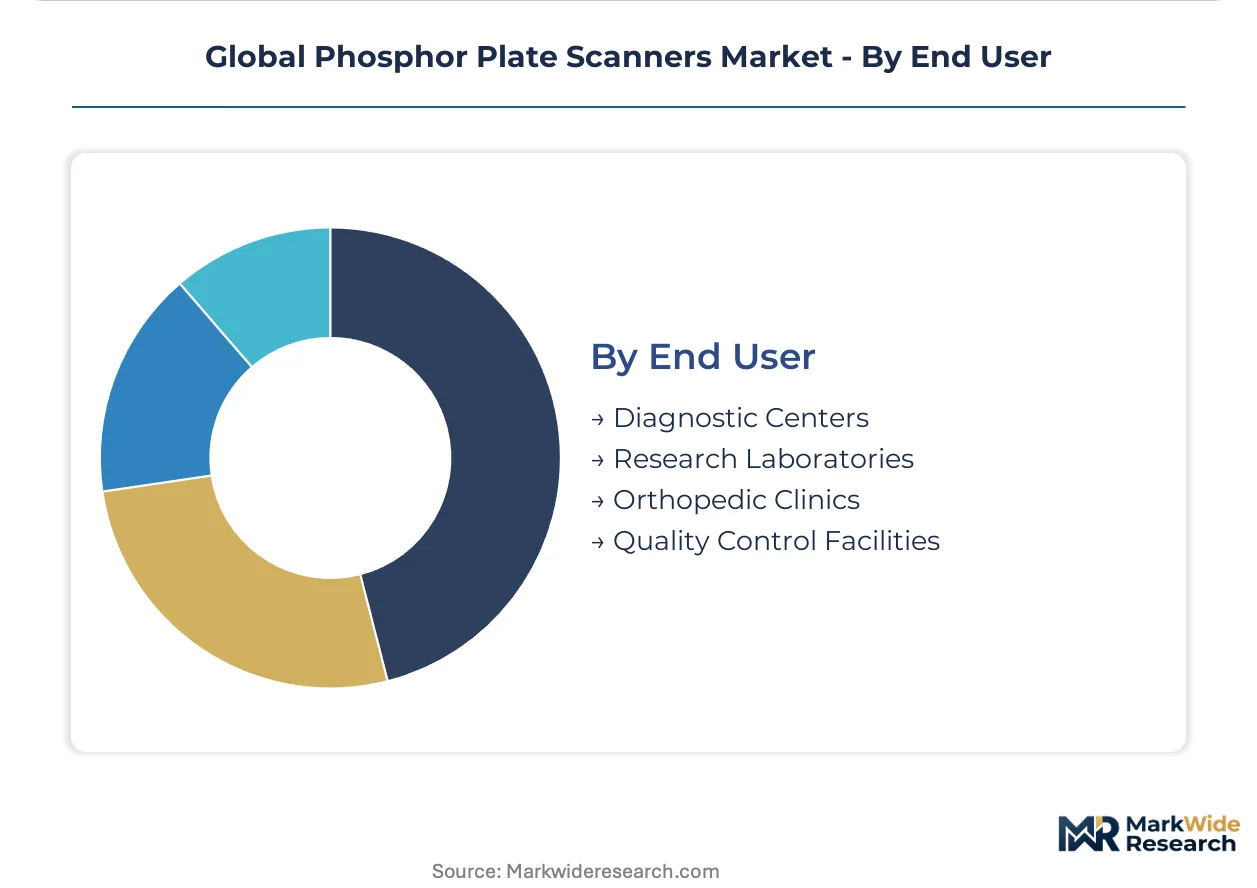
End User:
Purchasing leverage concentrates in network organizations that aggregate volume across multiple sites.
- Diagnostic Centers:High-throughput operations with multi-plate configurations and bundled service contracts. India's franchise networks standardize on specific scanner configurations, displacing individual practice autonomy.
- Orthopedic Clinics:Premium segment customers where digital radiography substitution is compressing phosphor plate demand.
- Research Laboratories:Specialized imaging requirements with customized calibration protocols.
- Quality Control Facilities:Industrial non-destructive testing applications with distinct procurement timelines.
Diagnostic centers hold installed capacity. Orthopedic clinics are rotating down the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in phosphor plate scanners tilt toward import-dependent dental markets in Southeast Asia and export-oriented manufacturing bases in East Asia and Europe. Currency volatility and divergent regulatory timelines are fragmenting procurement patterns across national borders.
United States
FDA 510(k) premarket notification requirements for image enhancement algorithms are extending clearance timelines for new scanner introductions. The agency's tightened software validation standards are pulling upgrade demand from installed base renewal cycles. California's dense cluster of dental technology distributors is consolidating procurement around prevalidated platform designs.
Germany
EU MDR clinical evidence standards on scanner-plate combinations are reshaping documentation requirements for CE-marked systems. The country's precision manufacturing base supplies solid-state diode arrays to veterinary portable scanner assemblers. Bavaria's dental equipment hub anchors European distribution through direct service networks.
Japan
METI-registered devices face distinct PMDA electromagnetic compatibility testing protocols that fragment production runs. The country's aging demographic is sustaining computed radiography fleet maintenance in suburban dental practices. Tokyo's imaging equipment distributors are consolidating around PMDA-prevalidated hardware configurations.
India
Franchise-model diagnostic center chains are standardizing on multi-plate scanner configurations, aggregating volume for direct manufacturer negotiations. CDSCO's medical device regulations are tightening import documentation for refurbished systems. Maharashtra's diagnostic hub cities are witnessing rapid equipment fleet standardization across chain networks.
Brazil
ANVISA's medical device registration pathways are lengthening approval timelines for imported scanner systems. Equine veterinary practices in São Paulo state are adopting portable solid-state diode array units for ambulatory field diagnostics. The country's diagnostic imaging distributors are pivoting toward bundled service contract models.
Global Phosphor Plate Scanners Market Competitive Landscape
Concentration sits with integrated dental equipment conglomerates that bundle scanner hardware with imaging software and consumable supply contracts. The vendor base spans Nordic workflow specialists, German precision manufacturers, and North American imaging technology holding companies. Two strategic archetypes dominate: full-stack imaging platform providers and aftermarket consumables specialists. Competitive moves center on service network densification and AI-assisted diagnostic software module integration.
Within the Nordic integrated-platform tier, PLANMECA OY exemplifies workflow-centric positioning across dental markets. German precision manufacturers anchor European distribution through direct service infrastructure, with DÜRR DENTAL SE occupying a representative position in this archetype. North American holding companies compete on installed base monetization, where Envista sits within the aftermarket consumables specialist tier.
| Leading Market Players |
|---|
| PLANMECA OY |
| Owandy Radiology |
| ACTEON Group |
| Carestream Dental LLC |
| DÜRR DENTAL SE |
| Apixia Corp |
| Envista |
| Dentsply Sirona |
| DIGIRAY Corp |
| Others |
Supply & Pricing Matrix
Capacity utilization at East Asian solid-state diode foundries directly shapes both component availability floors and scanner assembly pricing tiers, concentrating bargaining power among photonics suppliers while compressing margins for downstream equipment assemblers serving price-sensitive diagnostic chains.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across multi-plate scanner configurations, with price differentiation resting on FDA 510(k) certification tier and bundled service contract depth. Cost compression in portable segments is intensifying because solid-state diode arrays are displacing helium-neon architectures. Franchise-model diagnostic centers in India exhibit highest price sensitivity, while Nordic integrated-platform purchasers show lowest sensitivity due to workflow lock-in effects.
Supply Chain Analysis
Port congestion on Shanghai-to-Rotterdam lanes intermittently disrupts inbound laser component flows, extending lead times for European scanner assemblers. Manufacturing concentrates in China, Germany, and Japan, with raw material dependencies spanning barium fluorohalide crystals, europium doping compounds, and helium-neon laser tubes. Single-source vulnerability sits with East Asian solid-state diode foundries. Distribution runs through direct service networks in Europe and consolidated dental equipment distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized maintenance expertise for legacy helium-neon systems is thinning across independent service channels, creating asset-specific capability gaps that favor manufacturers with captive technician networks.
For Market Incumbents: Secure installed base monetization through consumable replenishment contracts and AI-assisted diagnostic software modules before digital radiography substitution accelerates in orthopedic segments. Deepen backward integration into solid-state diode sourcing to reduce East Asian foundry exposure. Prioritize PMDA-prevalidated platform designs to streamline Japanese market entry. For New Entrants and Emerging Players: Anchor in veterinary field diagnostics across Australia and Brazil, where portable solid-state scanner demand is climbing fastest and incumbent service networks remain underdeveloped. Target equine ambulatory practices with battery-powered units bundled with calibration support. Pursue direct-to-practice distribution bypassing consolidated dental equipment distributors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aftermarket consumables specialists with dense installed bases over hardware manufacturers facing digital radiography displacement. Long-term viability hinges on software-defined imaging workflow integration rather than fixed-function device sales. Monitor FDA 510(k) clearance velocity for algorithm-driven systems as inflection indicator for regulatory-complexity winners.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Diagnostic Software Development | Opens recurring revenue streams through machine learning image analysis modules integrated with laser scanning hardware. |
| PMDA Prevalidation Investment | Streamlines Japanese market entry by consolidating procurement around electromagnetic compatibility-tested platform designs. |
| Veterinary Portable Scanner Launch | Captures ambulatory care growth in Australian and Brazilian equine practices with solid-state diode array units. |
| Multi-Plate Configuration Standardization | Aggregates volume in India's franchise-model diagnostic chains through direct manufacturer negotiations. |
| Backward Integration into Diode Sourcing | Reduces supply vulnerability from East Asian foundry concentration for critical laser scanning components. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dental equipment procurement managers, veterinary practice owners, diagnostic center operations directors, and biomedical engineering technicians at hospital systems. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, PMDA electromagnetic compatibility test reports, and CDSCO import registration records. Bottom-up equipment shipment tracking and top-down imaging market sizing were triangulated to cross-verify volume estimates.
Across the analysis window, the analytical framework modeled product type, technology generation, application vertical, and end-user purchasing leverage to segment revenue and unit projections. CAGRs were derived from fitted growth curves anchored to installed base replacement cycles and technology substitution rates. Forecast inputs incorporated veterinary field diagnostics adoption curves and regulatory clearance timeline assumptions for algorithm-driven enhancement modules.
Decision-makers should treat outputs as directional under assumptions of stable FDA software validation standards and continued solid-state diode cost reduction; material deviation would warrant model refresh. Specific risk factors include accelerated digital radiography substitution in orthopedic settings and prolonged EU MDR documentation delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Cooled IR Camera Market
Imaging
Borescope Market
Imaging
Microscopic Camera Market
Imaging
Light Field Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Document Imaging Market
Imaging
Ingaas Image Sensor Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Middle East and Africa IP Camera Market
Imaging
Embedded Smart Cameras Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Global Computed Radiography Market
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Europe Machine Vision Systems Market
Imaging
Raman-Imaging System Market
Imaging
Global Cell Imagers Market