
 Gige Camera Market | 2026-2036
Gige Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Gige Camera Market Analysis
Equipment leasing and project-based financing is narrowing the capital barrier for mid-tier system integrators entering high-resolution imaging deployments. Basler AG leverages captive production of interface components to sustain margin control across European machine vision installations. Sony Corporation anchors sensor supply for multiple downstream camera assemblers through its CMOS fabrication scale. Teledyne DALSA Inc. differentiates by dominating line-scan architectures for flat-panel inspection and web monitoring.
GigE cameras transmit uncompressed image data over standard Ethernet cabling using the GigE Vision protocol, typically operating at 1 Gbps with Power over Ethernet (PoE) integration to simplify cabling infrastructure in factory environments. Their primary purpose is to feed real-time visual data into automated inspection, measurement, and robotic guidance systems without proprietary frame grabbers. Camera modules and interface cards together capture the dominant share of hardware value, while software solutions represent the fastest-expanding margin pool as vision libraries migrate to subscription licensing. Machine vision applications lead volume demand, though quality control deployments in semiconductor packaging are accelerating fastest due to defect sensitivity requirements.
FCC equipment authorization rules shape US market access for RF-emitting GigE variants, while CE marking under the EU Machinery Directive governs safety integration for European industrial deployments. Japan's METI promotes factory digitization standards that explicitly reference GigE Vision interoperability in smart manufacturing guidance. Stakeholders must monitor whether IEEE 802.3bt power standards and subsequent GigE Vision protocol revisions alter cabling topologies and competitive positioning in next-generation deployments.
Market Dynamics
The transition from proprietary Camera Link interfaces to standardized Ethernet-based GigE Vision architectures is compressing equipment refresh cycles and redistributing margin pools across the imaging supply chain. This protocol convergence is forcing incumbent frame grabber manufacturers to pivot toward software licensing models while opening procurement to commodity network infrastructure.
Growth Catalysts
- Machine vision mandates in automotive quality gates:German OEMs now require 100% inline optical inspection at welding and paint stations, mandating PoE-enabled GigE cameras to reduce cabling complexity in Stuttgart-area assembly plants.
- CE marking under EU Machinery Directive:Safety integration standards for collaborative robotics are accelerating certified camera deployments in European metal fabrication and packaging lines.
- 10 GigE Vision protocol maturation:Higher bandwidth Ethernet standards are enabling single-cable solutions for 12-megapixel inspection systems in semiconductor wafer handling, displacing multi-cable Camera Link configurations.
Market Restraints
- CMOS sensor supply concentration:Japanese and Korean foundries control advanced backside-illuminated sensor fabrication, exposing camera assemblers to allocation risk during foundry capacity constraints.
- Cabling infrastructure retrofit costs:Legacy factory floors in Midwestern US automotive plants lack Category 6A Ethernet runs, requiring expensive electrical contractor deployment for PoE++ power delivery.
- Machine learning vision library substitution:Cloud-based inference services from hyperscale providers are capturing value from edge camera hardware in low-latency-tolerant inspection applications.
Strategic Opportunities
- Underpenetrated Mexican automotive tier-one supply base:Querétaro and Guanajuato industrial corridors lack dense machine vision deployment despite accelerating EV battery module assembly investment.
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor packaging and mobile phone assembly are creating first-time demand for defect inspection systems in Noida and Sri City clusters.
- 5G private network convergence:Ultra-reliable low-latency communication is enabling wireless GigE camera arrays in warehouse robotics and automated guided vehicle guidance, eliminating tethering constraints.
Industry Challenges
- Embedded vision software engineering scarcity:Manufacturers in Nagoya and Detroit industrial corridors report 18-month hiring timelines for engineers proficient in GenICam standard implementation and real-time Linux kernel tuning.
- Multi-protocol certification complexity:Camera vendors must simultaneously validate GigE Vision 2.0, GenICam SFNC, and IEEE 1588 precision time protocol for semiconductor lithography alignment applications, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gige Camera Market |
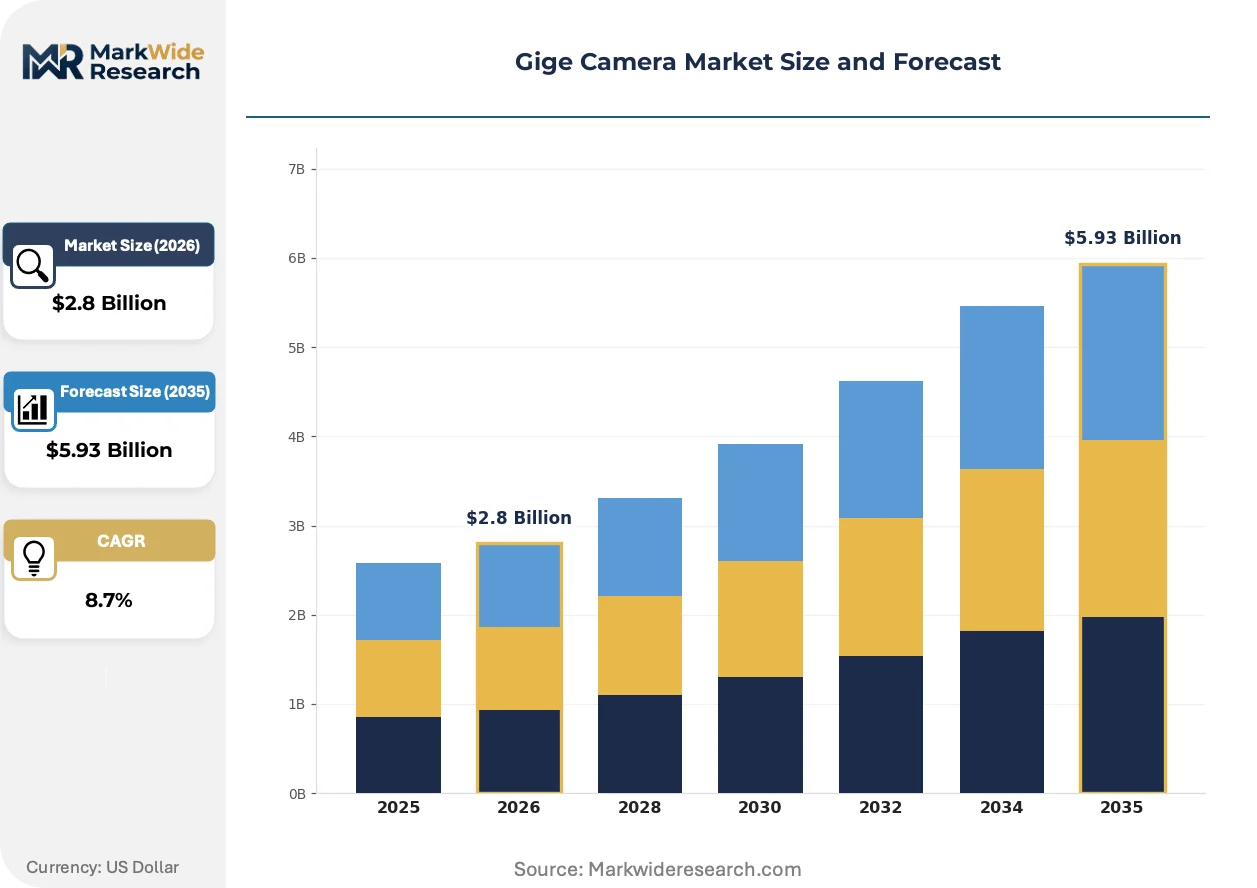
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Modules, Imaging Sensors, Software Solutions, Interface Cards Technology: Digital, Analog, Hybrid, Wireless End User: Healthcare, Automotive, Industrial Automation, Security Application: Machine Vision, Quality Control, Surveillance, Research |
| Companies Covered | Allied Vision Technologies GmbH, Basler AG, Baumer Holding AG, Teledyne DALSA Inc., JAI A/S, IMPERX Inc., Sony Corporation, Omron Corporation, Matrox Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gige Camera Market Emerging Trajectories
Silicon-level integration and protocol standardization are compressing the traditional imaging value chain, redistributing competitive advantage from hardware specialists to software-defined platform vendors. Three concurrent developments are reshaping how visual data is captured, transmitted, and monetized in industrial environments.
Embedded FPGA-based pre-processing at the sensor edge is rendering obsolete the traditional model of raw image transmission to host-based frame grabbers. Automotive battery manufacturers in German and US Midwest facilities are adopting these smart cameras to perform defect classification locally, reducing network bandwidth requirements by an order of magnitude while compressing inspection cycle times.
Japan's METI factory digitization guidelines explicitly mandate GigE Vision interoperability for smart manufacturing equipment subsidies, creating regulatory pull-through across Nagoya-area precision component suppliers. This policy alignment is accelerating replacement of proprietary vision systems in automotive stamping and machining operations, with compliance verification now required for capital equipment depreciation benefits.
System integrators in Stuttgart and Detroit corridors are consolidating vendor relationships around full-stack vision platform providers, displacing the historical practice of mixing camera, lens, lighting, and software from separate specialists. This buyer concentration is compressing margins for pure-play hardware manufacturers while expanding recurring revenue pools for integrated solution vendors with captive software licensing.
Gige Camera Market Segmentation
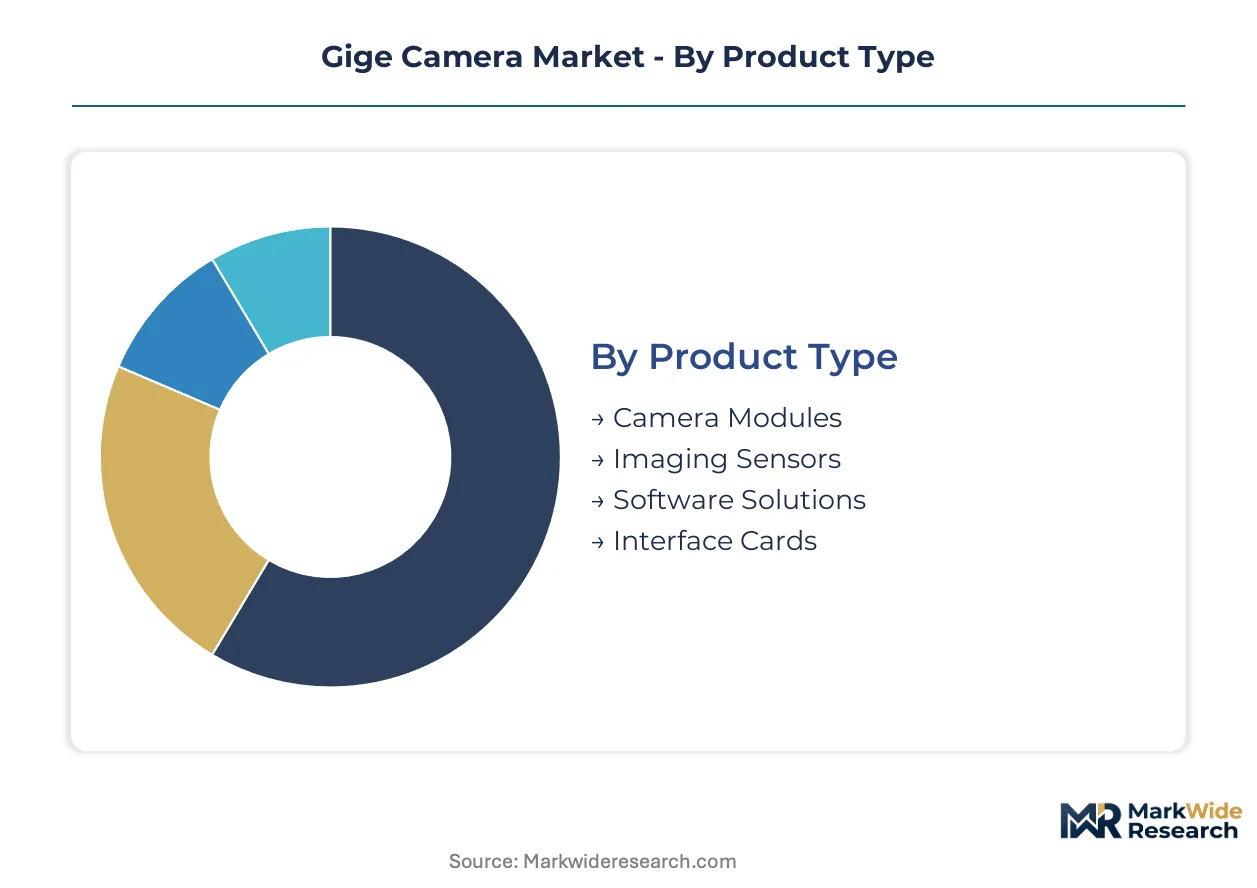
Segmentation in the GigE camera market reveals how hardware commoditization and software value capture are reshaping procurement patterns. Understanding these dimensions exposes where margin pools are concentrating and which technology transitions are compressing equipment refresh cycles across industrial automation corridors.
Product Type:
Cost tier segmentation distinguishes capital-intensive hardware components from recurring software revenue streams, exposing divergent margin architectures across the imaging value chain.
- Camera Modules:These integrated units combine CMOS sensors with GigE Vision protocol chipsets in IP65-rated housings for factory floor deployment. German automotive OEMs in Stuttgart-area welding stations are standardizing on PoE-enabled variants to eliminate separate power runs. The shift toward 12-megapixel inspection systems is narrowing replacement cycles for mid-tier assemblers.
- Imaging Sensors:Backside-illuminated CMOS architectures dominate high-sensitivity applications, with Japanese and Korean foundries controlling advanced fabrication. Supply allocation risk during foundry capacity constraints exposes camera vendors to delivery volatility. Sensor procurement now requires 26-week forward commitments from semiconductor packaging integrators.
- Software Solutions:Vision libraries with GenICam compliance and subscription licensing models are capturing expanding margin pools.
- Interface Cards:Ethernet PHY controllers and PoE power management circuits complete the hardware stack for host-side connectivity.
Camera modules command the established base. The steepest expansion runs through software solutions.
Technology:
Application requirements across bandwidth, latency tolerance, and mobility constraints determine which transmission architecture dominates specific deployment contexts.
- Digital:GigE Vision 2.0 protocol implementation over standard Ethernet cabling delivers uncompressed image streams at 1-10 Gbps with IEEE 1588 precision timing for multi-camera synchronization. Semiconductor wafer handling facilities in Japan's Nagoya corridor are migrating to 10 GigE Vision for single-cable 12-megapixel inspection, displacing legacy Camera Link multi-cable configurations.
- Analog:Coaxial-based legacy architectures persist in retrofit-constrained Midwestern US automotive plants where Category 6A Ethernet infrastructure is absent.
- Hybrid:Mixed-signal approaches bridge analog sensor front-ends with digital Ethernet backhaul for cost-sensitive quality control deployments.
- Wireless:5G private network integration enables untethered camera arrays in warehouse robotics and automated guided vehicle guidance, eliminating cabling constraints for mobile inspection platforms.
Digital architectures anchor current procurement volumes. Wireless configurations are climbing the fastest as private 5G deployments mature in logistics automation.
End User:
Customer type segmentation tracks how regulatory mandates and defect sensitivity requirements are concentrating demand across sector-specific procurement channels.
- Healthcare:FDA-regulated medical device manufacturing deploys GigE cameras for sterile packaging inspection and surgical instrument verification, with 21 CFR Part 11 compliance requirements governing image data integrity. Pharmaceutical serialization mandates are accelerating vision system procurement for track-and-trace verification lines.
- Automotive:German OEM quality gate mandates now require 100% inline optical inspection at welding and paint stations, driving PoE-enabled GigE camera standardization. EV battery module assembly in Querétaro and Guanajuato corridors is creating first-time demand among Mexican tier-one suppliers previously lacking dense machine vision deployment.
- Industrial Automation:CE marking under the EU Machinery Directive accelerates certified camera deployments in European collaborative robotics and metal fabrication lines.
- Security:Surveillance applications favor lower-resolution, higher-frame-rate configurations for motion detection and perimeter monitoring.
Automotive applications command the established base. Healthcare deployments are gaining share fastest as pharmaceutical serialization regulations tighten.
Application:
Maturity differentiation separates established inspection workflows from emerging research and development configurations with divergent performance specifications.
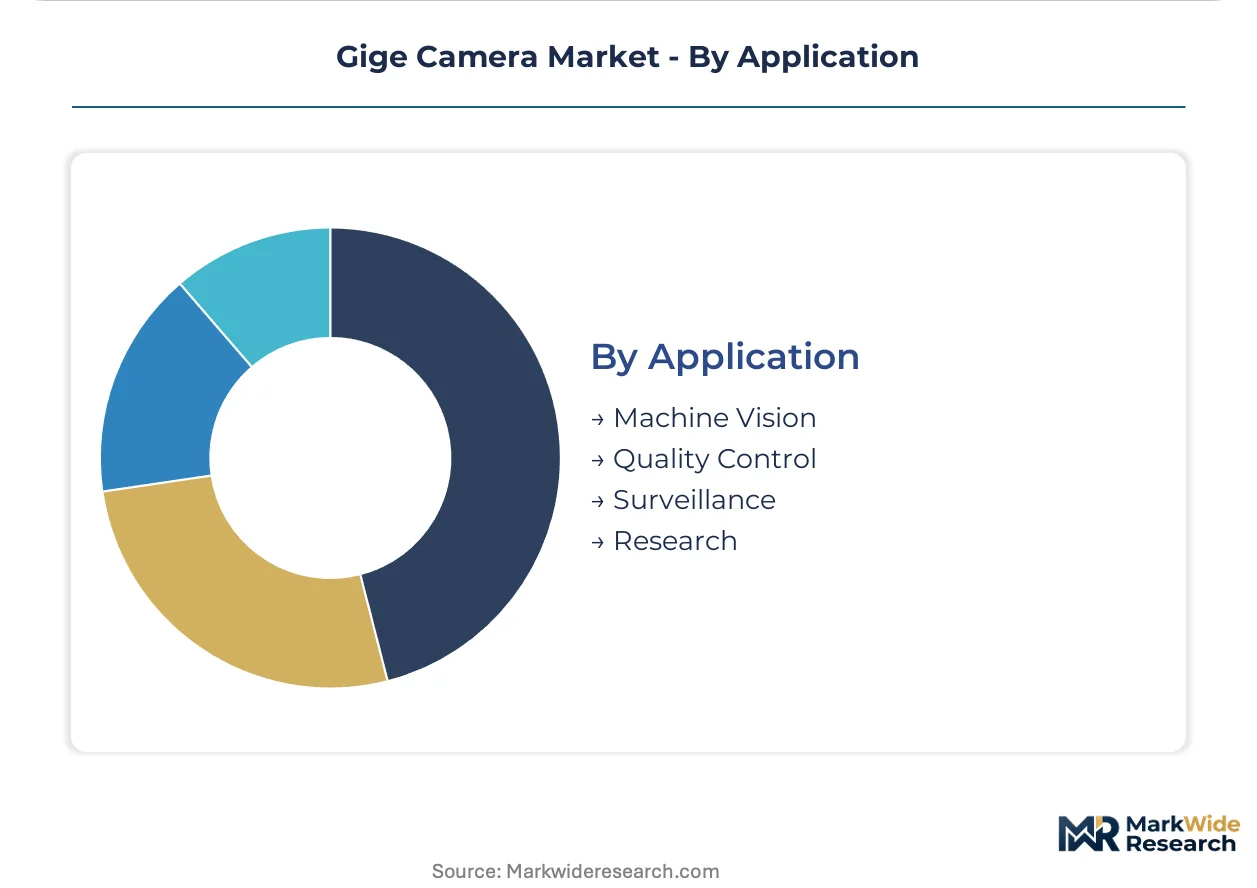
- Machine Vision:Real-time robotic guidance and automated measurement systems constitute the volume anchor, with system integrators in Stuttgart and Detroit corridors consolidating vendor relationships around full-stack platform providers. Japan's METI factory digitization guidelines explicitly mandate GigE Vision interoperability for smart manufacturing equipment subsidies, accelerating replacement of proprietary vision systems in Nagoya-area precision component suppliers.
- Quality Control:Defect detection in semiconductor packaging exhibits the steepest demand acceleration due to nanometer-scale sensitivity requirements and yield economics. Embedded FPGA-based pre-processing at the sensor edge enables local defect classification, reducing network bandwidth requirements by an order of magnitude.
- Surveillance:Continuous monitoring applications prioritize thermal tolerance and vandal resistance over resolution specifications.
- Research:Scientific imaging deployments require cooled sensors and extended dynamic range for low-light microscopy and spectroscopy applications.
Machine vision commands the established base. Quality control is climbing the fastest as semiconductor packaging defect sensitivity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy German and Japanese camera assemblers supply machine vision hardware to automotive and semiconductor packaging facilities across North America and Asia. Import dependence for advanced CMOS sensors concentrates supply risk in East Asian foundries. Regional deployment patterns track industrial automation corridors and regulatory subsidy programs.
United States
Midwestern automotive plants in Michigan and Ohio drive PoE-enabled GigE camera procurement for welding inspection lines. FCC equipment authorization rules govern RF-emitting variants entering the market. Detroit-area system integrators consolidate vendor relationships around full-stack platform providers as factory digitization accelerates.
Germany
Stuttgart-area OEMs mandate 100% inline optical inspection at paint and welding stations, compressing equipment refresh cycles. CE marking under the EU Machinery Directive governs safety integration for collaborative robotics deployments. Basler AG anchors European supply through captive production of interface components.
Japan
Nagoya precision component suppliers replace proprietary vision systems to comply with METI factory digitization guidelines. Sony Corporation controls advanced backside-illuminated CMOS fabrication, exposing camera assemblers to allocation risk. Semiconductor wafer handling facilities migrate to 10 GigE Vision for single-cable 12-megapixel inspection.
China
Yangtze River Delta electronics manufacturers deploy machine vision for mobile phone assembly and semiconductor packaging. MIIT promotes domestic GigE Vision interoperability standards for smart manufacturing equipment. Ningbo and Suzhou industrial clusters concentrate defect inspection system procurement.
India
Noida and Sri City electronics manufacturing clusters generate first-time demand under PLI scheme incentives for semiconductor packaging. BIS certification requirements shape equipment procurement specifications for mobile phone assembly lines. System integrators report 18-month hiring timelines for embedded vision software engineers.
Gige Camera Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and interface card supply. The vendor base separates into consolidated full-stack providers and fragmented hardware assemblers dependent on external sensor supply. Three archetypes dominate: captive sensor fabricators, software-defined platform vendors, and pure-play camera module manufacturers. Competitive positioning hardens through backward integration into sensor supply and strategic partnerships for 5G private network integration.
Among German-based platform providers, Basler AG exemplifies the vertically integrated archetype through in-house production of interface components. Sony Corporation anchors the sensor supply tier as a captive fabricator supplying multiple downstream assemblers. Teledyne DALSA Inc. occupies a position within the specialized line-scan segment for flat-panel inspection applications. These three represent divergent strategic postures: component control, scale fabrication, and application-specific architecture dominance.
| Leading Market Players |
|---|
| Allied Vision Technologies GmbH |
| Basler AG |
| Baumer Holding AG |
| Teledyne DALSA Inc. |
| JAI A/S |
| IMPERX Inc. |
| Sony Corporation |
| Omron Corporation |
| Matrox Imaging |
| Others |
Supply Flow & Price Mechanics
Japanese and Korean CMOS foundries anchor upstream sensor supply, concentrating pricing power with Sony Corporation and Samsung Electronics while compressing margins for downstream camera assemblers dependent on external procurement. This supply asymmetry forces pure-play hardware manufacturers toward software licensing models to escape commodity pricing traps.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade under EU Machinery Directive CE marking and volume scale serving as primary differentiation drivers. Pricing pressure stems from embedded FPGA smart cameras reducing unit volumes in high-bandwidth inspection applications. Mid-tier system integrators exhibit highest price sensitivity, while semiconductor packaging integrators accept premium tiers for defect sensitivity compliance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for GigE camera vendors sourcing Ethernet PHY controllers and PoE power management circuits. Advanced backside-illuminated CMOS sensors draw from Japanese and Korean fabrication facilities, while interface card assembly concentrates in Taiwanese and Chinese electronics manufacturing corridors. Single-source vulnerability persists for 10 GigE Vision protocol chipsets. Distribution runs through Stuttgart, Nagoya, and Detroit industrial corridor system integrators with consolidated vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward full-stack platform providers as automotive OEMs and semiconductor packaging integrators consolidate vendor relationships, fragmenting procurement access for pure-play hardware specialists.
For Market Incumbents: Insulate sensor supply through captive fabrication partnerships or long-term allocation agreements with Sony Corporation and Samsung Electronics to counter foundry capacity constraints. Deepen software licensing revenue through GenICam-compliant vision libraries with subscription terms, reducing dependence on hardware margin compression from embedded FPGA substitution. For New Entrants and Emerging Players: Mexican automotive tier-one corridors around Querétaro and Guanajuato offer underpenetrated white-space for PoE-enabled GigE camera deployment as EV battery module assembly accelerates. India's Noida and Sri City electronics manufacturing clusters under PLI scheme incentives present first-time demand for defect inspection systems. A channel partnership strategy with Detroit and Stuttgart system integrators provides fastest route to OEM quality gate specifications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed machine vision platform vendors consolidating software-defined capabilities. Long-term viability favors integrated providers with captive sensor supply or exclusive licensing arrangements across the analysis window. The signal to monitor is IEEE 802.3bt power standard adoption altering cabling topologies and vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Captive CMOS fabrication capacity insulates margin control against foundry allocation volatility. |
| Software Licensing Platform Launch | GenICam-compliant vision libraries with subscription terms capture recurring revenue from hardware commoditization. |
| 5G Private Network Partnership | Ultra-reliable low-latency communication enables wireless GigE camera arrays in warehouse robotics. |
| Geographic Manufacturing Footprint Expansion | Local assembly in Querétaro and Guanajuato corridors reduces tariff exposure for North American automotive procurement. |
| Certification Investment Pathway | CE marking under EU Machinery Directive and FDA 21 CFR Part 11 compliance unlock pharmaceutical and collaborative robotics demand. |
Methodological Framework
The analysis maps camera modules, imaging sensors, software solutions, and interface cards, each validated through plant engineers at Stuttgart and Nagoya automotive facilities, system integrators in Detroit industrial corridors, and procurement leads at semiconductor packaging operations. Primary interviews with OEM platform engineers, aftermarket service heads, and embedded vision software developers combined with secondary validation from SEC filings, customs trade data, and METI factory digitization guidelines. Bottom-up unit economics and top-down industrial automation corridor analysis provided triangulation.
Assumptions held fixed include GigE Vision 2.0 protocol dominance and PoE infrastructure penetration rates in target manufacturing corridors, while CMOS sensor supply allocation and 10 GigE Vision adoption pace were varied across sensitivity scenarios. The forecast framework models product type, technology architecture, end-user sector, and application maturity segmentation throughout the projection horizon. CAGRs derived from equipment refresh cycle compression rates and regulatory mandate implementation timelines, with semiconductor packaging defect sensitivity requirements and automotive quality gate specifications as key demand inputs.
Practitioners should monitor foundry capacity utilization reports, IEEE 802.3bt power standard ratification, and METI subsidy compliance verification for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Chemical Imaging Systems Market
Imaging
Asia Pacific IP Camera Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Cinematographic Camera Market
Imaging
Digital Movie Cameras Market
Imaging
Specific Imaging Solution Market
Imaging
Camera with Flip Screen Market
Imaging
Global Broadcast Cameras Market
Imaging
Ingaas Image Sensor Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Handheld Imager Market
Imaging
Global 3D Imaging Market
Imaging
Video Capture Card Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Global 3D Camera Market