
 360-Degree Camera Market | 2026-2036
360-Degree Camera Market Size, Share, and Industry Trends Forecast 2026-2036
360-Degree Camera Market Intelligence
Subscription-based hardware leasing is rewriting competitive entry barriers for 360-degree camera operators. Insta360 leverages direct-to-creator channel control to sustain premium pricing in the professional tier. GoPro anchors its position through backward integration into ruggedized housing design and action-oriented firmware. Samsung Electronics competes by extending semiconductor fabrication advantages into image sensor supply.
A 360-degree camera captures spherical video or still imagery through multiple lenses arranged to record overlapping fields of view, then stitches outputs into seamless equirectangular or cubic projections using onboard or cloud-based processing; typical units employ two ultra-wide fisheye lenses with 180-degree-plus coverage and resolutions from 4K to 8K per eye for immersive playback. The professional product type dominates absolute revenue as filmmaking studios and broadcasters demand color-accurate, high-bitrate output. Wireless technology segments are expanding fastest as real-time streaming to VR headsets eliminates tethering constraints. Industrial usage scenarios for virtual facility tours carry above-average margin pools due to enterprise software integration requirements.
FCC Part 15 rules govern unintentional radiators and intentional wireless emitters in the United States, while CE marking under the EU Radio Equipment Directive shapes market access across Europe; both frameworks compel manufacturers to certify 2.4 GHz and 5 GHz transmission modules before commercial distribution. Japan's MIC radio law adds a third certification layer for units sold into that market. Stakeholders must monitor whether emerging spectrum reallocations or privacy regulations governing surveillance-grade capture will force hardware redesigns or firmware restrictions.
Market Dynamics
Wireless transmission certification requirements are fragmenting go-to-market timelines as FCC Part 15, CE marking under the EU Radio Equipment Directive, and Japan's MIC radio law impose overlapping but non-harmonized testing protocols on manufacturers targeting multiple jurisdictions simultaneously.
Growth Catalysts
- Real-time VR streaming:Elimination of tethering constraints through 5 GHz and 6 GHz wireless modules is accelerating professional studio adoption for live immersive broadcasting.
- EU CSRD disclosure mandates:Virtual facility documentation requirements are pulling industrial-grade 360-degree capture into enterprise sustainability audit workflows.
- Sensor manufacturing clusters:Concentrated CMOS and BSI sensor production in China, Japan, and South Korea is compressing component lead times for final assembly operations.
Market Restraints
- Memory storage cost volatility:NAND flash and high-speed SD card pricing fluctuations directly impact bill-of-materials stability for 8K recording units.
- Lens supply concentration:Ultra-wide fisheye glass elements rely on specialized Japanese and German optical foundries with limited surge capacity.
- Smartphone spherical capture:Native 360-degree photo modes on flagship mobile devices are eroding entry-level dedicated camera demand.
Strategic Opportunities
- India industrial digitization:PLI scheme incentives for electronics manufacturing are creating localized assembly opportunities for mid-tier professional units.
- AI-driven stitching acceleration:Neural network-based image processing is converging with edge compute silicon to enable real-time spherical video generation without cloud dependency.
- Direct-to-creator platforms:Subscription hardware leasing is bypassing traditional retail distribution to capture recurring revenue from independent content producers.
Industry Challenges
- Multi-jurisdiction certification timelines:Sequential FCC, CE, and MIC radio testing extends product launch windows by 8-14 months for wireless-enabled models.
- Computational imaging talent scarcity:Shortage of firmware engineers with expertise in parallax correction and rolling shutter compensation is constraining R&D velocity.
- Legacy broadcast infrastructure integration:SDI and HDMI 2.0 compatibility requirements complicate adoption by established filmmaking studios with sunk equipment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 360-Degree Camera Market |
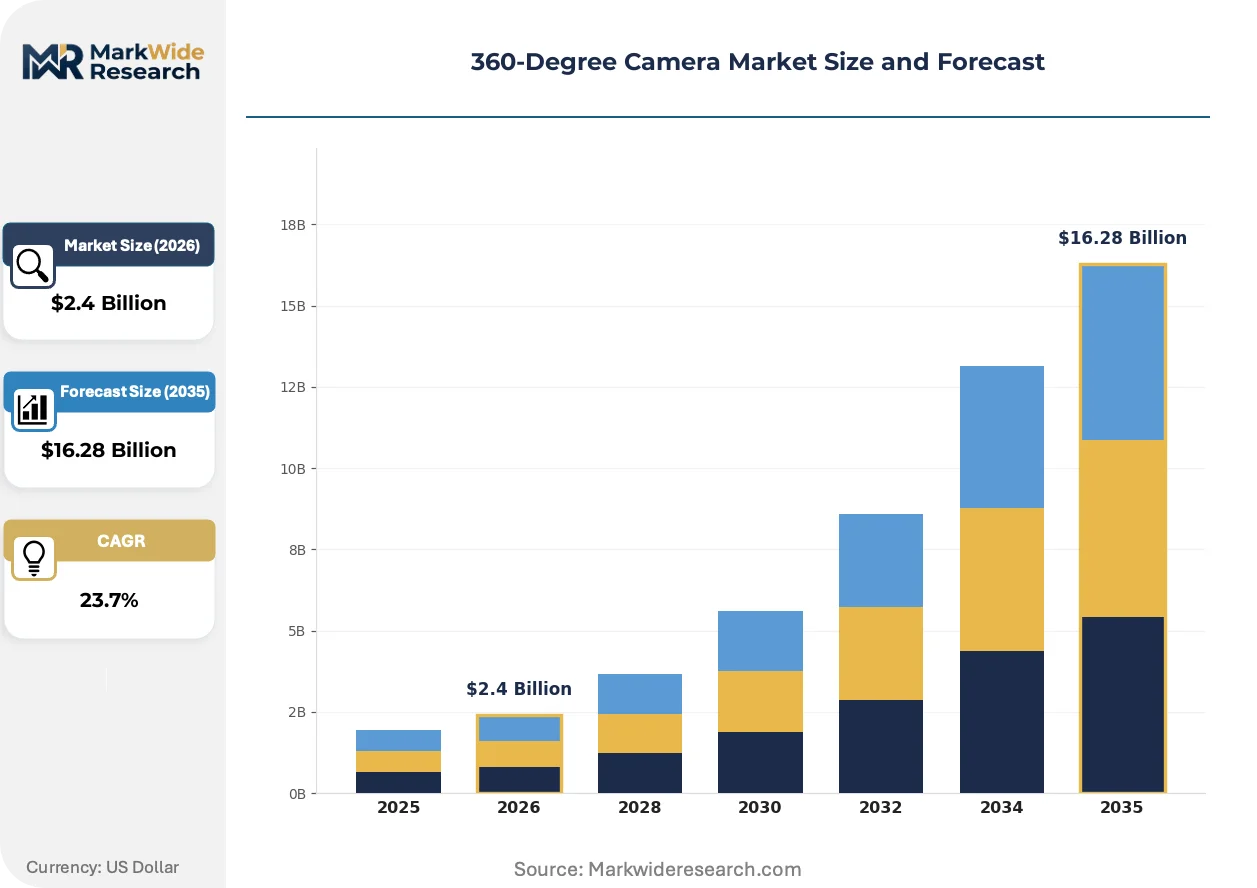
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $16.28 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer, Professional, Industrial, VR End User: Filmmakers, Content Creators, Businesses, Education Technology: Optical, Digital, Hybrid, Wireless Usage Scenario: Virtual Tours, Events, Sports, Surveillance |
| Companies Covered | GoPro, Insta360, Samsung Electronics, Ricoh, LG Electronics, Nikon Corporation, 360fly, Panasonic, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
360-Degree Camera Market Strategic Shifts & Innovations
Computational photography pipelines are displacing optical hardware complexity as the primary value driver, with software-defined image processing now determining output quality more than lens count or sensor size alone.
On-device stitching silicon is hybridizing with cloud-based neural rendering to split processing loads dynamically based on resolution targets and latency constraints. Professional studios are adopting this architecture for live VR broadcasts where edge processing handles preview streams while cloud clusters manage final 8K spherical output. The technology is compressing post-production timelines from hours to minutes for time-sensitive content workflows.
FCC Part 15 rules governing unintentional radiators are tightening emission testing protocols for 6 GHz Wi-Fi 6E modules entering the 360-degree camera supply chain. Manufacturers must now submit updated equipment authorization filings for existing product lines incorporating these transmission standards. The regulation is forcing hardware redesign cycles on units targeting the United States market, particularly affecting compact form factors with limited shielding space.
Content creators are consolidating purchases around subscription-lease bundles that combine hardware access with cloud storage and editing software. Traditional retail channels are losing share to direct manufacturer portals that capture recurring revenue and usage data. This shift is most visible in North American and Western European markets where independent filmmakers and real-estate documentation specialists dominate professional-tier demand.
360-Degree Camera Market Segmentation
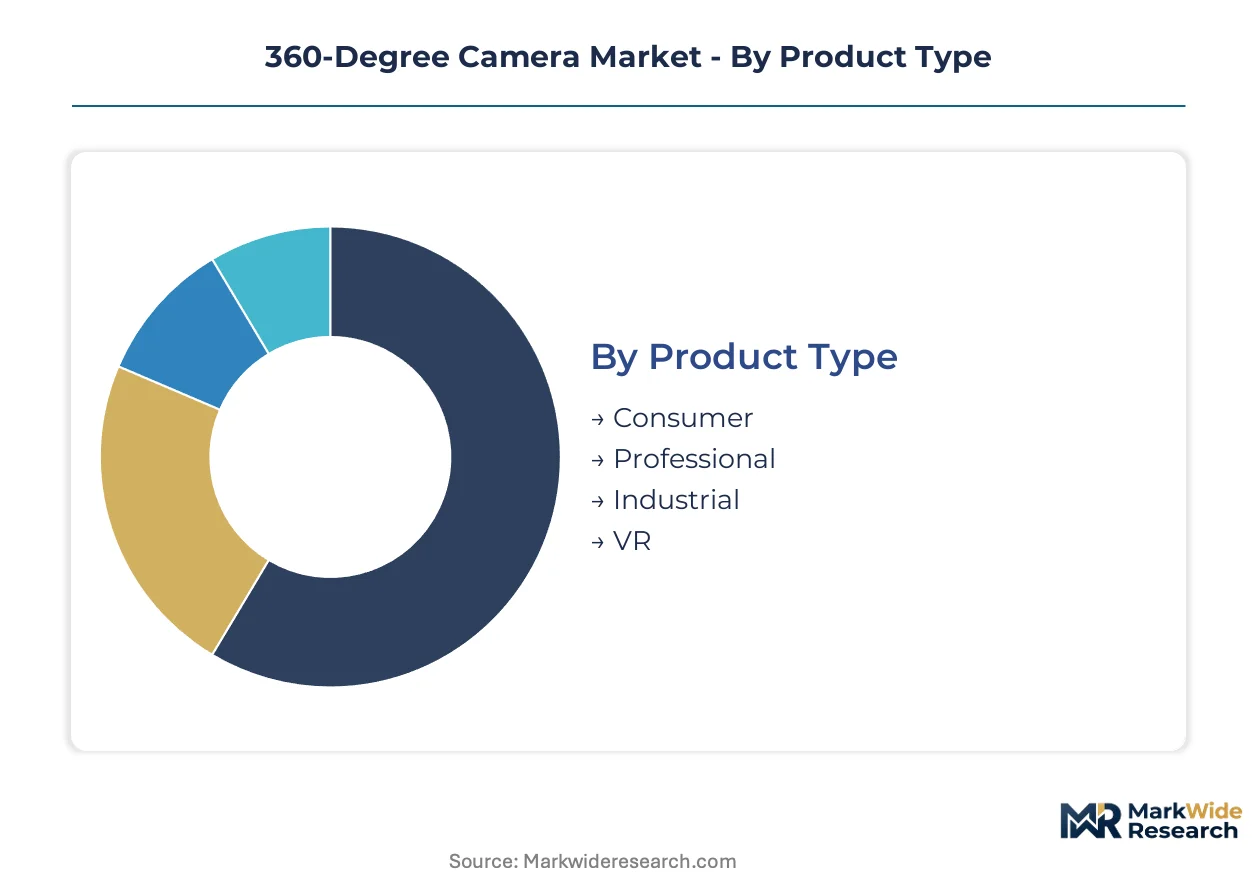
360-degree camera segmentation reveals how hardware specifications, transmission protocols, and post-processing workflows diverge across user sophistication levels. Product tiers align with distinct certification requirements and margin structures, while technology choices determine real-time capability versus archival fidelity trade-offs.
Product Type:
Mature consumer hardware competes with emerging industrial deployments as enterprise digitization accelerates facility documentation demand.
- Consumer:Compact dual-lens units with onboard equirectangular stitching target travel documentation and social media creators. FCC Part 15 certification for 2.4 GHz transmission dominates go-to-market costs for US-bound inventory.
- Professional:High-bitrate RAW capture with color-accurate output commands premium positioning among filmmaking studios and broadcasters. CE marking under the EU Radio Equipment Directive extends validation timelines for European distribution.
- Industrial:Ruggedized housings with enterprise software integration enable virtual facility tours and sustainability audit workflows.
- VR:Low-latency wireless streaming modules eliminate tethering constraints for immersive headset playback.
Professional handles the majority of throughput; VR is the fastest mover on share.
End User:
Cost tier stratification separates subscription-lease adopters from capital-intensive studio procurement patterns.
- Filmmakers:Color grading pipelines and SDI output compatibility dominate equipment selection for narrative and documentary production. Legacy broadcast infrastructure integration constraints slow hardware refresh cycles.
- Content Creators:Direct-to-manufacturer portal purchasing bypasses retail markup through subscription bundles combining hardware access with cloud storage. Independent filmmakers in North America and Western Europe concentrate demand here.
- Businesses:Enterprise procurement favors industrial-grade units with API-accessible stitching software for real estate and hospitality documentation.
- Education:Institutional budgets prioritize durable hardware with simplified post-production workflows for campus virtual tours and remote learning content.
Filmmakers anchor absolute revenue; Content Creators are expanding most quickly as leasing models democratize professional-tier access.
Technology:
Volume concentration in sensor manufacturing clusters shapes component sourcing strategies across all technology approaches.
- Optical:Ultra-wide fisheye glass elements from specialized Japanese and German foundries determine image circle coverage and edge sharpness. Limited surge capacity at these suppliers constrains rapid scaling.
- Digital:Computational photography pipelines leverage neural network-based parallax correction to reduce hardware complexity. Edge compute silicon from South Korean fabrication facilities enables real-time processing without cloud dependency.
- Hybrid:Split architectures combine optical capture with software-defined enhancement for mid-tier price positioning.
- Wireless:Wi-Fi 6E modules operating at 6 GHz face tightening FCC Part 15 emission testing protocols forcing hardware redesign cycles.
Digital commands the steepest expansion trajectory as AI-driven stitching acceleration converges with on-device silicon; Optical retains margin concentration through lens supply scarcity.
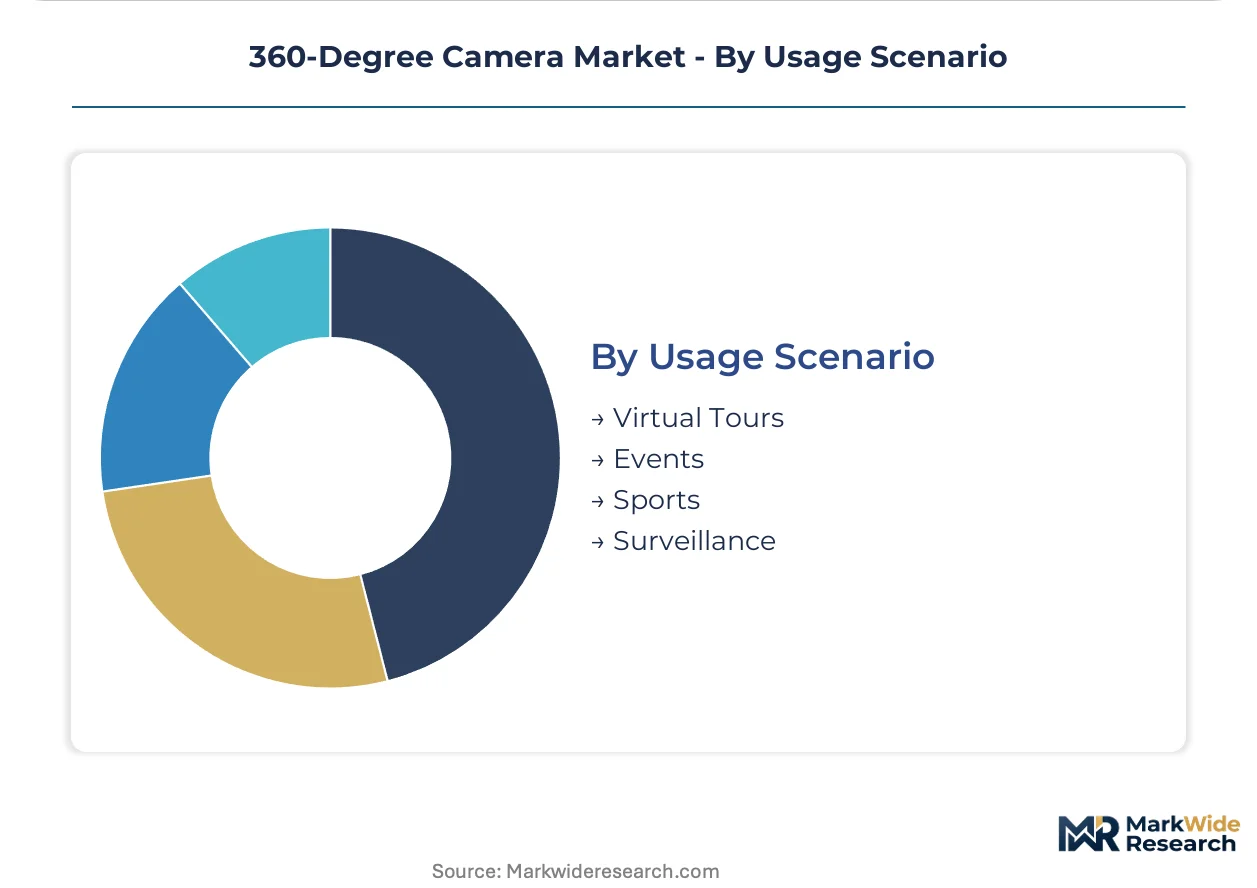
Usage Scenario:
Application differentiation separates recurring revenue SaaS integrations from one-time hardware transactions.
- Virtual Tours:Enterprise software integration requirements carry above-average margin pools for industrial-grade capture in real estate and facility management. EU CSRD disclosure mandates are pulling this segment into sustainability audit workflows.
- Events:Live streaming demand drives wireless module adoption for real-time VR broadcast without post-production delays. Professional studios prioritize this architecture for time-sensitive content workflows.
- Sports:Ruggedized housings and action-oriented firmware target high-motion capture with gyroscopic stabilization.
- Surveillance:Privacy regulations governing capture-grade recording may force firmware restrictions or hardware redesigns in multiple jurisdictions.
Virtual Tours generates the highest margin contribution per unit; Events is climbing the fastest as live immersive broadcasting eliminates tethering constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from East Asian sensor foundries dominate upstream value capture, while import demand concentrates in North American and European content production hubs. Trade balances favor manufacturing clusters in China, Japan, and South Korea against consumption centers in the United States and Germany. Wireless certification fragmentation extends delivery timelines differentially across destination markets.
United States
Filmmaking studios in Los Angeles and New York drive professional-tier procurement for immersive broadcast content. FCC Part 15 equipment authorization requirements for 2.4 GHz and 5 GHz transmission modules impose 8-14 month pre-market testing timelines. Austin and Seattle host emerging post-production facilities specializing in real-time VR stitching workflows.
China
Shenzhen and Dongguan concentrate CMOS sensor fabrication and final assembly capacity for global supply. MIIT radio transmission standards and GB certification protocols govern domestic market access for wireless-enabled units. Shanghai content creator communities are accelerating adoption of subscription-lease hardware models.
Germany
Industrial facility documentation demand from automotive and manufacturing sectors pulls ruggedized capture hardware into enterprise procurement. CE marking under the EU Radio Equipment Directive and REACH chemical compliance shape import validation requirements. Munich and Stuttgart host system integrators specializing in virtual tour SaaS platforms.
Japan
Specialized optical foundries in Hokkaido and Kyushu supply ultra-wide fisheye glass elements with limited surge capacity. MIC radio law adds certification layers for 2.4 GHz and 5 GHz modules distinct from FCC and CE protocols. Tokyo broadcasters anchor regional demand for high-bitrate RAW capture workflows.
South Korea
Edge compute silicon fabrication in Gyeonggi Province enables on-device neural network stitching without cloud dependency. Korean content creators drive wireless streaming adoption for real-time VR headset playback. Seoul-based electronics conglomerates leverage captive semiconductor supply for image sensor integration.
360-Degree Camera Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream controlling sensor and optical supply. Market structure consolidates around three to four vertically integrated electronics conglomerates with captive semiconductor fabrication, while mid-tier specialists compete through firmware differentiation and direct-to-creator distribution. Strategic archetypes span action-oriented rugged hardware designers, computational photography software platforms, and semiconductor-to-system integrators. Dominant competitive moves include backward integration into image sensor supply and subscription-based hardware leasing to capture recurring revenue.
Within the platform integrator tier, GoPro exemplifies action-oriented rugged hardware positioning through in-house housing design, while Insta360 occupies a position emphasizing direct-to-creator channel control and subscription bundling. Samsung Electronics anchors the semiconductor-to-system archetype by extending captive fabrication advantages into sensor supply. These three represent distinct competitive vectors: ruggedized physical design, software-defined distribution, and upstream component integration.
| Leading Market Players |
|---|
| GoPro |
| Insta360 |
| Samsung Electronics |
| Ricoh |
| LG Electronics |
| Nikon Corporation |
| 360fly |
| Panasonic |
| Sony |
| Others |
Cost & Logistics Intelligence
The Shanghai-Los Angeles transpacific freight corridor carries sensor modules and optical assemblies from East Asian fabrication hubs to North American content production centers, with container rate volatility directly compressing margins on professional-grade units while amplifying price spreads between FCC-certified wireless models and tethered entry-tier hardware.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads based on CE marking and FCC Part 15 certification grade plus after-sales software integration; price erosion runs through economy tiers as smartphone spherical capture substitutes erode dedicated hardware demand. Content creators leasing through direct-to-manufacturer portals show lowest price sensitivity, while education procurement faces acute budget constraints.
Supply Chain Analysis
CMOS sensors, ultra-wide fisheye glass elements, and edge compute silicon feed from concentrated manufacturing bases in China, Japan, and South Korea. Single-source vulnerability at specialized Japanese and German optical foundries constrains surge capacity for 8K-grade lens assemblies. Distribution runs through direct-to-creator portals and enterprise system integrators, bypassing traditional retail channels in North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with real-time VR streaming adoption pulling professional studios into wireless-enabled refresh cycles ahead of legacy infrastructure depreciation schedules.
For Market Incumbents: Entrench through backward integration into image sensor supply and captive edge compute silicon fabrication. Smartphone spherical capture substitutes threaten entry-tier volume; defend through certification investment in FCC Part 15 and CE marking tiers that lock out unqualified competitors from professional procurement channels. For New Entrants and Emerging Players: India industrial digitization presents the most penetrable geography, with PLI scheme incentives enabling localized assembly for mid-tier professional units. Target virtual facility documentation workflows in automotive and manufacturing sectors; bypass retail distribution through API-accessible stitching software bundled with hardware lease subscriptions. For Investors and Strategic Acquirers: Computational photography software platforms with neural network stitching IP represent the priority acquisition archetype. Long-term viability hinges on AI-driven parallax correction capabilities displacing optical hardware complexity; watch for FCC spectrum reallocations or privacy regulations forcing firmware restrictions as inflection signals requiring portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Captive CMOS fabrication in South Korea and Japan insulates margin from NAND flash volatility. |
| Direct-to-Creator Portal Launch | Subscription-lease bundles bypass retail markup and capture recurring revenue from independent filmmakers. |
| AI-Driven Stitching Acceleration | Neural network processing on edge compute silicon enables real-time spherical video without cloud dependency. |
| Multi-Jurisdiction Certification Investment | Sequential FCC, CE, and MIC radio testing creates 8-14 month barriers against unqualified competitors. |
| Enterprise Software Integration Partnership | API-accessible stitching platforms penetrate EU CSRD-driven virtual facility documentation workflows. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with 360-degree camera manufacturers, content creator platform operators, and enterprise procurement officers; and secondary validation against FCC equipment authorization filings, CE marking registries, customs trade data, and hyperscaler VR content investment disclosures. Bottom-up unit shipment modeling triangulated against top-down addressable market sizing across product type, technology, and usage scenario segments.
Forecast inputs span professional, consumer, industrial, and VR product tiers; optical, digital, hybrid, and wireless technology approaches; and virtual tours, events, sports, and surveillance usage scenarios. CAGRs derived from regression analysis of historical shipment trajectories, weighted by adoption curve positioning and substitution threat intensity from smartphone spherical capture and computational photography pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by semiconductor-to-system integrators or platform-native software entrants would shift outcomes. Cross-checking against hyperscaler VR content capex disclosures and FCC equipment authorization filing trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Computer Aided Detection Market
Imaging
X Ray Tubes Market
Imaging
APAC Image Sensors Market
Imaging
Gige Camera Market
Imaging
CCD Image Sensors Market
Imaging
Electron Microscopy Market
Imaging
Image Based Barcode Reader Market
Imaging
Global Panoramic Camera Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
TDI Camera Market
Imaging
Live Cell Imaging Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Hybrid Imaging Market
Imaging
Image Intensifier Market
Imaging
Japan Digital X-Ray Market
Imaging
Raman-Imaging System Market