
 Retro-Reflective Labels Market | 2026-2036
Retro-Reflective Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Retro-Reflective Labels Market Analytics
The gap between glass-bead and microprismatic retro-reflection technology is narrowing as coating precision improves and unit costs converge. 3M Company leverages its multi-layer optical film patents to sustain premium positioning across safety and transportation segments. Avery Dennison Corporation anchors global supply through integrated adhesive-substrate R&D facilities in North America and Europe. ORAFOL Europe GmbH specializes in microprismatic sheeting for high-performance traffic applications, competing on optical efficiency rather than volume scale.
Retro-reflective labels are pressure-sensitive constructions incorporating glass beads, microprisms, or cube-corner arrays that return incident light toward its source, typically achieving coefficients of retro-reflection measured in candela per lux per square meter. These labels enable machine-readable and human-visible identification under low-illumination conditions across supply chains, roadways, and industrial floors. Polyester substrates dominate durable outdoor applications where UV stability and dimensional integrity matter, while vinyl formulations capture cost-sensitive packaging and temporary signage. Permanent adhesives hold the largest volume share in traffic marking and industrial asset tagging, though repositionable variants are gaining traction in retail promotional cycles where shelf resets occur frequently.
The US DOT Federal Highway Administration mandates minimum retro-reflectivity levels for traffic signs under the MUTCD, while the EU CE marking framework enforces EN 12899 standards for road equipment including reflective sheeting. China's GB standards for traffic safety products, administered by SAMR, require domestic certification for reflective materials used on public infrastructure. Stakeholders must monitor how evolving photometric testing protocols and regional procurement localization rules reshape supplier qualification requirements.
Market Dynamics
Microprismatic retro-reflection technology is compressing the historical performance gap with glass-bead alternatives as coating precision advances and unit economics converge, forcing incumbents to defend optical efficiency premiums through patent-protected multi-layer film architectures.
Growth Catalysts
- US DOT MUTCD mandates:Federal Highway Administration retro-reflectivity thresholds for highway signage and vehicle markings tighten compliance requirements, forcing fleet operators and infrastructure agencies into replacement cycles.
- E-commerce fulfillment networks:Logistics operators deploy reflective tracking labels to reduce sorting errors in automated distribution centers, driving volume demand for machine-readable identification under low-illumination conditions.
- Smart logistics infrastructure procurement:China, India, and Germany concentrate public investment in connected freight systems where optical tracking reduces supply chain friction.
Market Restraints
- Raw material concentration:High-grade optical-grade polymers and specialized adhesives concentrate among Asian petrochemical suppliers, exposing converters to input cost volatility and freight disruption.
- Technical performance ceilings:Glass-bead formulations face inherent angular limitations in wide-entrance-angle applications, capping their penetration in high-performance traffic safety segments.
- Certification fragmentation:Divergent photometric testing protocols across US DOT, EU EN 12899, and China's GB standards force redundant qualification expenses for multi-regional suppliers.
Strategic Opportunities
- Underpenetrated cold-chain logistics:Pharmaceutical and fresh-food distribution networks in India and Southeast Asia lack standardized reflective tracking, creating first-mover space for temperature-tolerant label formulations.
- RFID-retroreflection convergence:Hybrid labels combining optical visibility with passive RFID encoding enable dual-mode tracking for automated warehouse systems and human verification.
- EU Green Deal procurement rules:Public infrastructure tenders increasingly weight environmental product declarations, favoring suppliers with verified recycled-content substrates and solvent-free adhesive systems.
Industry Challenges
- Photometric engineering talent scarcity:Specialized expertise in optical design and retro-reflective metrology concentrates among aging workforces in Germany and Japan, constraining R&D expansion.
- Legacy asset-tagging system integration:Industrial facilities with decades-old barcode infrastructure face capital-intensive retrofitting to capture full benefits of enhanced-visibility labels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retro-Reflective Labels Market |
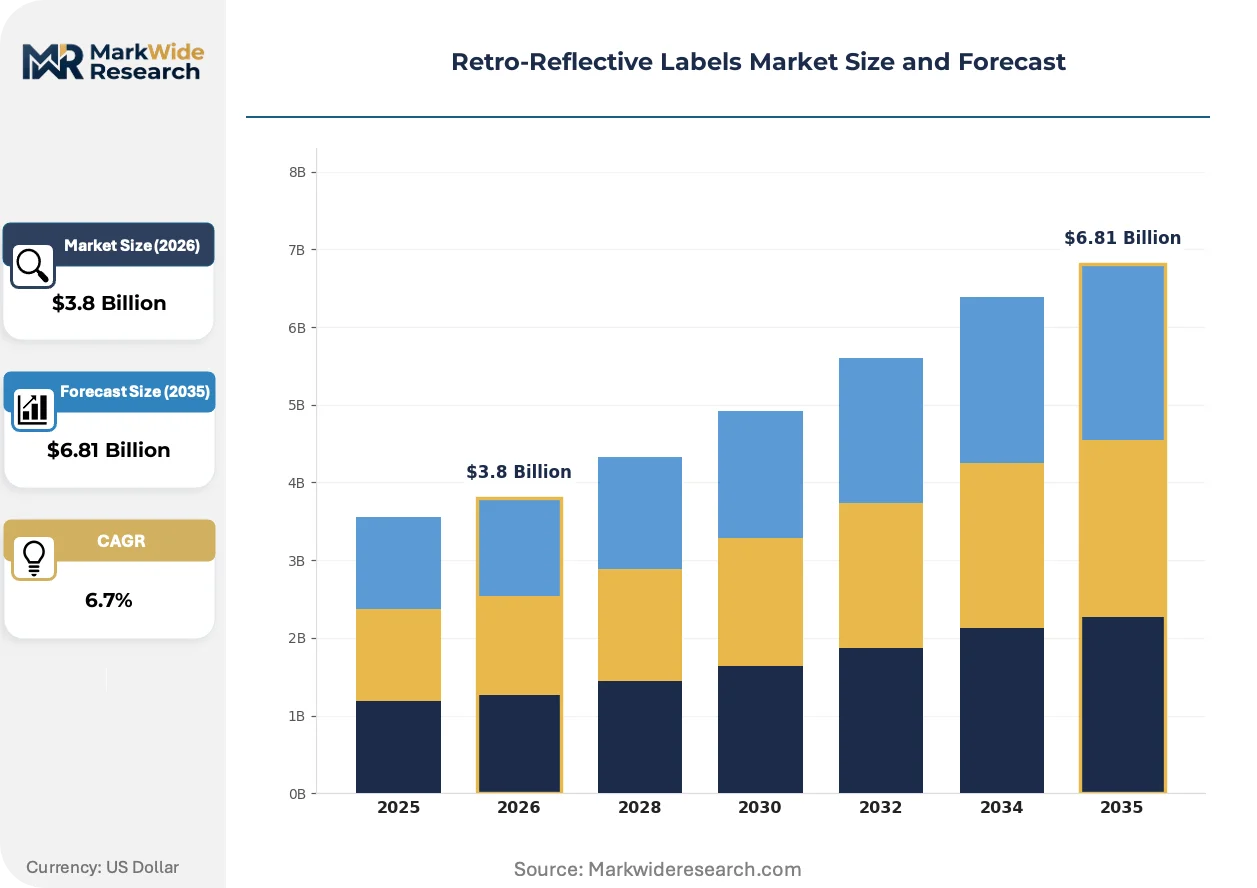
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Vinyl, Polypropylene, Paper Adhesive Type: Permanent, Removable, Repositionable, Specialty Application: Safety Signage, Traffic Markings, Packaging, Industrial Use End User: Manufacturing, Transportation, Retail, Logistics |
| Companies Covered | 3M Company, Avery Dennison Corporation, UPM Raflatac, Brady Worldwide, PPG Industries, Lintec Corporation, ORAFOL Europe GmbH, Nippon Carbide Industries, Schreiner Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retro-Reflective Labels Market Evolving Landscape
Coating and substrate technologies are converging toward multifunctional constructions that merge optical performance with digital traceability, compressing the traditional separation between passive safety materials and active identification systems.
Microprismatic sheeting is hybridizing with nanostructured surface coatings to achieve broader entrance angles and improved color stability under UV exposure. Automotive OEMs and heavy-truck manufacturers are adopting these constructions for regulatory-compliant conspicuity markings. The technology is hybridizing product tiers by enabling mid-priced formulations to approach premium optical performance, eroding historical price-performance segmentation.
China's SAMR administration is tightening enforcement of GB standards for traffic safety products, requiring domestic certification for reflective materials deployed on public infrastructure. Domestic converters face accelerated qualification timelines to maintain procurement eligibility. Municipal transportation bureaus in Shanghai and Shenzhen are prioritizing certified suppliers in smart-city infrastructure tenders.
Third-party logistics operators are consolidating label procurement through centralized fleet-management platforms, displacing fragmented purchasing by individual distribution centers. Amazon, DHL, and regional parcel networks negotiate multi-year supply agreements directly with adhesive-substrate integrators. This concentration is most visible in North American and Western European e-commerce fulfillment corridors where automation investment runs highest.
Retro-Reflective Labels Market Segmentation
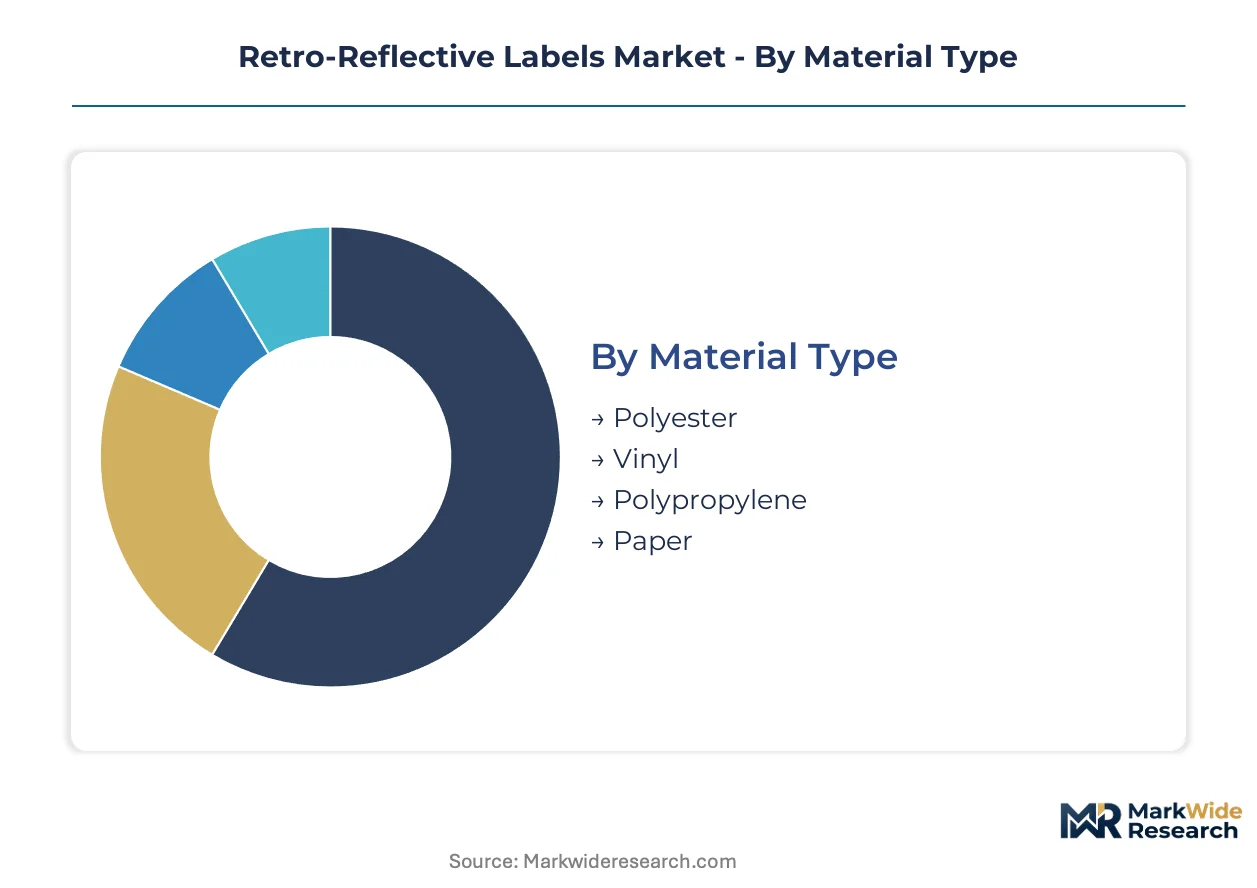
Retro-reflective label specifications diverge sharply across deployment environments, from UV-exposed highway signage to temperature-cycled pharmaceutical logistics. Material selection, adhesive chemistry, and optical performance tiers must align precisely with regulatory mandates and automated scanning infrastructure.
Material Type:
Use-case spectrum spans permanent infrastructure installations demanding decades of optical stability versus temporary promotional applications where cost minimization dominates.
- Polyester:High-tenacity film substrates deliver dimensional stability under thermal cycling and UV exposure. US DOT MUTCD-compliant highway signage and European EN 12899 traffic equipment specifications drive procurement concentration, though raw material costs track petrochemical volatility.
- Vinyl:Flexible calendered films enable conformability to curved surfaces and irregular substrates. Cost-sensitive packaging and temporary construction zone signage represent volume concentration, particularly in emerging logistics corridors where replacement frequency exceeds durability requirements.
- Polypropylene:Oriented film structures balance moisture resistance with lower density than polyester. Cold-chain pharmaceutical labeling in India and Southeast Asia favors this substrate for temperature-tolerant performance.
- Paper:Saturated paper stocks with retro-reflective coatings serve short-cycle retail promotions and indoor safety applications where environmental exposure remains minimal.
Established volume favors polyester; emerging adoption favors vinyl in cost-optimized logistics networks.
Adhesive Type:
Attachment permanence requirements segment procurement between infrastructure-grade bonding and operational flexibility needs.
- Permanent:Cross-linked acrylic and solvent-based systems achieve substrate failure before adhesive failure. Traffic marking and industrial asset tagging specifications mandate this chemistry class for regulatory compliance longevity.
- Removable:Low-tack formulations enable clean removal from painted surfaces and glass. Fleet vehicle temporary markings and retail window signage drive intermittent demand spikes.
- Repositionable:Microsphere-based adhesives permit multiple attachment cycles without residue accumulation. Automated distribution center shelf labeling and reusable container tracking represent expanding use cases.
- Specialty:Custom-engineered systems address extreme temperature ranges, chemical exposure, or low-surface-energy substrates. Cryogenic logistics and offshore oil platform applications require qualified supplier relationships.
Permanent adhesives anchor infrastructure procurement; repositionable variants climb fastest in e-commerce fulfillment automation.
Application:
Optical performance thresholds and regulatory certification requirements stratify demand across visibility-critical functions.
- Safety Signage:High-coefficient retro-reflection for emergency egress and workplace hazard communication. OSHA compliance mandates and EU workplace safety directives sustain replacement cycles.
- Traffic Markings:Pavement striping and vertical delineation demanding abrasion resistance and wet-night visibility. Federal Highway Administration minimum retro-reflectivity thresholds force systematic infrastructure upgrades.
- Packaging:Machine-readable identification for sortation automation under variable illumination. Amazon, DHL, and regional parcel networks consolidate procurement through centralized fleet platforms.
- Industrial Use:Asset tagging and process control labeling in manufacturing environments. Barcode-legacy facility retrofits and RFID-retroreflection hybrid adoption reshape specifications.
Traffic markings concentrate public infrastructure spending; packaging applications expand most quickly in automated logistics corridors.
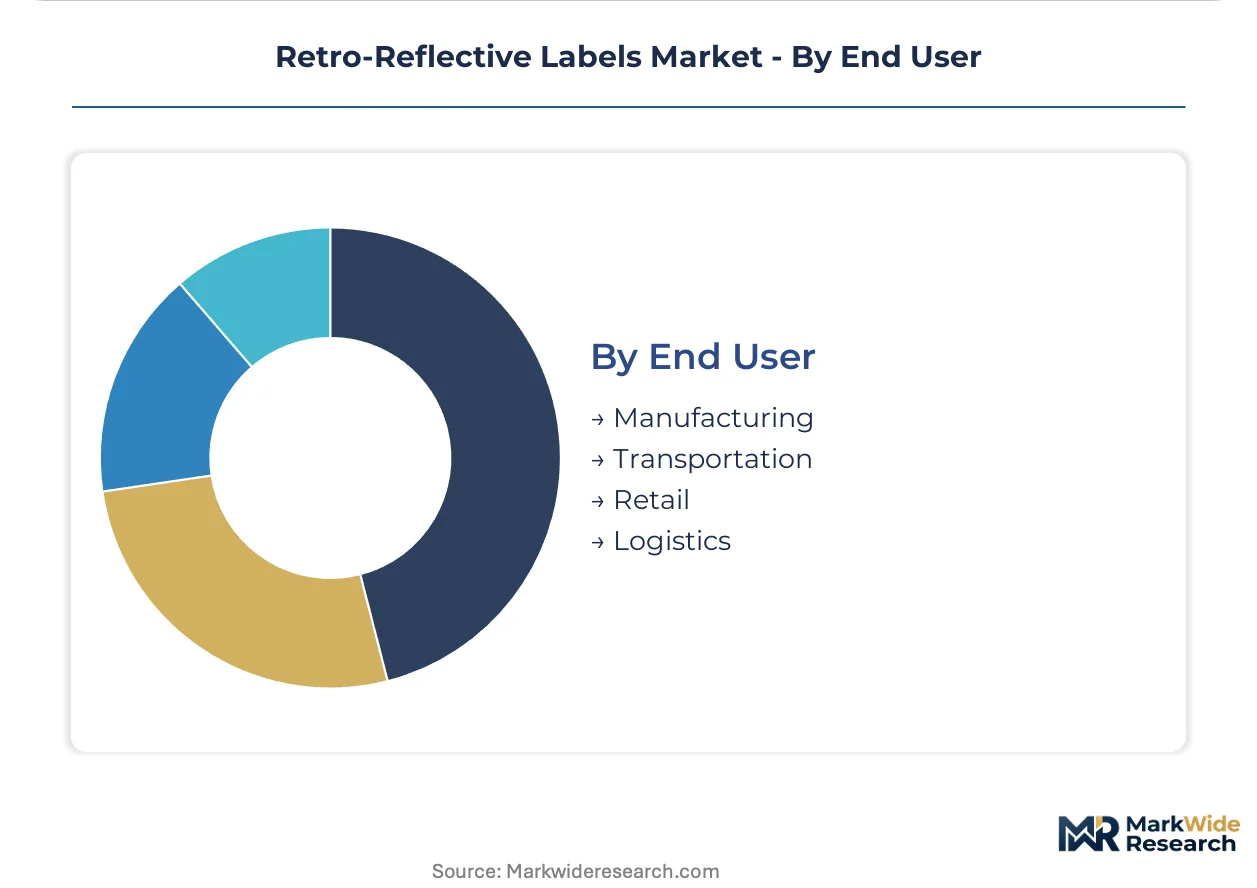
End User:
Procurement sophistication and specification authority vary dramatically across organizational types and capital allocation priorities.
- Manufacturing:Asset lifecycle tracking and lean process visualization requirements. Industrial facilities with decades-old barcode infrastructure face capital-intensive retrofit decisions.
- Transportation:Fleet compliance markings and vehicle conspicuity mandates. Heavy-truck OEMs and aftermarket retrofitters source through certified converter networks.
- Retail:Promotional cycle turnover and shelf-reset operational rhythms. Seasonal demand volatility complicates inventory planning for label converters.
- Logistics:End-to-end supply chain visibility and automated sortation accuracy. Third-party operators in China, Germany, and India prioritize smart infrastructure procurement.
Manufacturing represents mature specification discipline; logistics end users gain share fastest through e-commerce network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics operators and infrastructure agencies concentrate procurement authority across five national markets where e-commerce expansion and traffic safety mandates drive specification intensity.
United States
Fleet compliance managers and highway agencies dominate procurement through centralized platforms. The US DOT Federal Highway Administration enforces MUTCD retro-reflectivity thresholds that force systematic replacement cycles for aging signage. Distribution centers in Pennsylvania and Ohio deploy machine-readable reflective labels for automated sortation under variable warehouse illumination.
Germany
Automotive OEMs and heavy-truck manufacturers anchor demand for regulatory-compliant vehicle conspicuity markings. The EU CE marking framework enforces EN 12899 standards for road equipment including reflective sheeting specifications. Industrial clusters in Bavaria and Baden-Württemberg concentrate converter operations serving pan-European logistics networks.
China
Municipal transportation bureaus and smart-city integrators concentrate procurement for connected freight infrastructure. SAMR administration tightens GB standards enforcement for traffic safety products requiring domestic certification. Shanghai and Shenzhen prioritize certified suppliers in municipal infrastructure tenders for optical tracking systems.
India
Third-party logistics operators and cold-chain pharmaceutical distributors drive emerging demand for temperature-tolerant label formulations. BIS certification requirements shape supplier qualification for public infrastructure deployment. Industrial corridors in Maharashtra and Gujarat attract converter investments targeting underpenetrated pharmaceutical distribution networks.
Japan
Precision manufacturing facilities and export-oriented automotive suppliers sustain specification discipline for asset lifecycle tracking. METI oversees JIS standards alignment for industrial safety materials. Manufacturing clusters in Aichi Prefecture and the Kansai region maintain legacy barcode infrastructure while evaluating RFID-retroreflection hybrid adoption.
Retro-Reflective Labels Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where optical performance certification separates premium positioning from volume scale. Three archetypes dominate: multi-layer optical film patent holders defending premium positioning, integrated adhesive-substrate R&D operators anchoring global supply, and microprismatic efficiency specialists competing on photometric performance rather than manufacturing scale. Dominant competitive moves include strategic partnerships with logistics fleet operators and portfolio diversification into hybrid RFID-retroreflection constructions.
Within the patent-protected premium tier, 3M Company and Avery Dennison Corporation occupy positions sustained by multi-layer optical film architectures and integrated North American and European R&D facilities respectively. ORAFOL Europe GmbH sits within the microprismatic specialization vector where optical efficiency metrics rather than volume scale determine competitive standing. These three entities exemplify how intellectual property concentration and manufacturing integration define sustainable positioning against coating-technology convergence pressures.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| UPM Raflatac |
| Brady Worldwide |
| PPG Industries |
| Lintec Corporation |
| ORAFOL Europe GmbH |
| Nippon Carbide Industries |
| Schreiner Group |
| Others |
Value Network & Pricing Analysis
Shanghai's optical-grade polymer processing clusters concentrate microprismatic film coating capacity, feeding downstream pricing power to certified converters serving US DOT MUTCD and EU EN 12899 compliance markets. This geographic concentration of high-grade substrate production creates asymmetric leverage where petrochemical input volatility transmits rapidly to finished label quotations.
Pricing Analysis
Cost-plus contracts with petrochemical indexation dominate long-term supply agreements between Asian substrate producers and North American converters. Three-tier pricing structure across premium, standard, and economy levels separates multi-layer optical film patents from commodity glass-bead formulations, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from coating-technology convergence compressing historical performance premiums. Fleet operators and third-party logistics platforms exhibit highest price sensitivity, while traffic infrastructure agencies prioritize optical compliance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for reflective sheeting importers. High-grade optical polymers concentrate in China, South Korea, and Japan, with specialized acrylic adhesives drawing from German and US chemical producers. Single-source vulnerability persists for microprismatic masterbatch formulations. Distribution runs through certified converter networks that laminate, die-cut, and apply regulatory markings before direct shipment to fleet operators and infrastructure agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photometric engineering expertise concentrates among aging workforces in Germany and Japan, constraining R&D expansion for optical design and retro-reflective metrology. This talent scarcity amplifies acquisition premiums for specialist firms holding proprietary multi-layer film architectures.
For Market Incumbents: Harden patent-protected optical film positions through backward integration into captive coating capacity in Bavaria and Ohio industrial corridors. Accelerate certification maintenance for evolving US DOT MUTCD and SAMR GB standard protocols to defend against coating-technology convergence eroding performance premiums. Channel control through direct fleet-management platform relationships offers defensive leverage against logistics procurement consolidation. For New Entrants and Emerging Players: Cold-chain pharmaceutical distribution networks in India and Southeast Asia present underpenetrated white-space for temperature-tolerant polypropylene label formulations. Hybrid RFID-retroreflection constructions for automated warehouse systems offer technical differentiation absent from legacy barcode infrastructure retrofits. Pursue BIS certification early to qualify for municipal infrastructure tenders in Maharashtra and Gujarat industrial corridors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because infrastructure replacement cycles and fleet conspicuity mandates create non-discretionary demand insulated from cyclical downturns. Target acquisition candidates with verified solvent-free adhesive systems and recycled-content substrates aligned to EU Green Deal procurement weighting. Monitor SAMR enforcement intensity for GB standard domestic certification as signal for Chinese market access premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Polymer Production | Captive supply of high-grade substrates insulates margin compression from Asian petrochemical volatility. |
| RFID-Retroreflection Hybrid Label Development | Dual-mode tracking captures automated warehouse upgrade cycles at Amazon and DHL fulfillment networks. |
| EU Green Deal Certification Investment | Solvent-free adhesive systems and recycled-content substrates qualify for weighted public infrastructure tenders. |
| Photometric Engineering Talent Acquisition | Specialist optical design capabilities in Germany and Japan constrain competitive R&D replication. |
| Direct Fleet-Management Platform Partnerships | Centralized procurement consolidation by third-party logistics operators displaces fragmented distribution center purchasing. |
Research Methodology
The analysis maps microprismatic sheeting, glass-bead formulations, adhesive-substrate integrations, and hybrid RFID-optical constructions, each validated through converter operations managers, fleet compliance officers, and municipal procurement directors. Primary interviews with photometric engineering specialists and logistics automation engineers combined with secondary validation through US DOT FHWA MUTCD compliance databases, SAMR GB standard filings, EU CE marking registries, and customs trade data. Bottom-up volume triangulation across material type, adhesive chemistry, and application segments reconciled with top-down infrastructure spending and e-commerce fulfillment capex trajectories.
Forecasts assume continued US DOT MUTCD retro-reflectivity threshold enforcement, SAMR GB standard domestic certification tightening, and EU Green Deal procurement weighting expansion across the analysis window. Segmentation dimensions modeled include substrate material, adhesive permanence class, optical performance tier, and end-use regulatory environment. CAGRs derived from elasticity-adjusted replacement cycle analysis and logistics automation penetration curves, with specific inputs for cold-chain pharmaceutical distribution network expansion and smart-city infrastructure procurement concentration.
Practitioners should monitor SAMR enforcement timelines, EU EPD verification protocol adoption, and photometric testing standard harmonization progress for early signals of qualification cost shifts. Forecasts reflect assumptions regarding petrochemical input stability and logistics automation capex continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
GCC Labeling Market
Labels
Print Label Market
Labels
Booklet Labels Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
ESD Protective Signage Labels Market
Labels
Pre-Gummed Labels Market
Labels
Braille Labels Market
Labels
Foam Labels Market
Labels
Stretch Sleeve Labels Market
Labels
GHS Labels Market
Labels
GCC Labels and Release Liners Market
Labels
Wet Glue Labeling Machines Market
Labels
Global Waterproof Labels Market
Labels
Fiber Optic Labels Market
Labels
Global Cryogenic Label Market
Labels
Direct Thermal Linerless Labels Market