
 Emboss Coding Machine Market | 2026-2036
Emboss Coding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Emboss Coding Machine Market Foresight
The EU Green Deal is recalibrating packaging material specifications across European consumer goods, forcing converters to upgrade coding equipment for compostable substrates. BOBST leverages its rotary embossing platform to dominate high-volume folding carton lines in France and Italy. Heidelberg sustains technology leadership through integrated hot-foil and embossing modules for premium cosmetics packaging. Komori Corporation competes via precision register control systems that reduce substrate waste on short pharmaceutical runs.
An emboss coding machine mechanically raises or depresses alphanumeric characters, logos, or security patterns into paper, film, or foil substrates using engraved dies at pressures typically ranging from 500 to 3,000 psi, producing permanent tamper-evident marks without consumable inks. Industrial-grade systems lead unit shipments due to continuous-duty requirements on pharmaceutical blister lines, while handheld units represent the fastest-growing category as field-service technicians adopt portable serialization tools for warehouse and distribution environments. Hot foil technology anchors premium cosmetic and document security applications where metallic visual authentication commands price premiums, whereas thermal transfer dominates high-speed food labeling where barcode readability must survive refrigeration cycles.
EMA serialization requirements under the Falsified Medicines Directive mandate machine-readable codes on every pharmaceutical pack sold in the EU, directly expanding emboss coding deployment for tamper-evident seals. REACH compliance on die materials restricts certain alloy compositions, pushing manufacturers toward certified tool-steel alternatives. FDA track-and-trace rules for US-bound drug imports create parallel compliance obligations for European exporters. Stakeholders must monitor evolving substrate portfolios as bio-based films enter commercial scale, since die geometry and pressure profiles require recalibration for materials with divergent elastic recovery properties.
Market Dynamics
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive are forcing packaging converters to replace legacy coding equipment with emboss systems capable of unit-level tamper-evident marking at line speeds exceeding 300 units per minute.
Growth Catalysts
- EU Falsified Medicines Directive:EMA serialization rules now require machine-readable codes on every pharmaceutical pack sold in the EU, directly expanding emboss coding deployment for blister-line applications.
- Compostable substrate transition:The EU Green Deal is recalibrating material specifications across European consumer goods, forcing converters to upgrade equipment for bio-based films with divergent elastic recovery properties.
- Cosmetics premiumization:Hot-foil embossing demand concentrates in French and Italian luxury packaging clusters where metallic visual authentication commands sustained price premiums.
Market Restraints
- Certified tool-steel input costs:REACH compliance on die materials restricts certain alloy compositions, pushing manufacturers toward higher-cost certified alternatives with elongated procurement timelines.
- German supply concentration:High-precision embossing equipment production clusters disproportionately in southern Germany, creating geographic vulnerability to regional logistics disruptions.
- Thermal transfer substitution:Food labeling applications increasingly favor thermal transfer systems for high-speed barcode applications where refrigeration-cycle readability outweighs tamper-evidence requirements.
Strategic Opportunities
- Handheld serialization tools:Portable emboss coding units represent underpenetrated white space as field-service technicians adopt mobile equipment for warehouse and distribution environments.
- Rotary platform convergence:Integration of hot-foil and embossing modules into single-pass systems creates technology convergence opportunities for premium folding carton converters.
- FDA track-and-trace alignment:European exporters face parallel compliance obligations for US-bound drug imports, creating service bundling opportunities around dual-jurisdiction validation.
Industry Challenges
- Die geometry recalibration:Bio-based films entering commercial scale require pressure profile adjustments that strain existing operator skill sets and extend commissioning timelines.
- Legacy line integration:Pharmaceutical blister lines running continuous-duty cycles face capital-intensive retrofit requirements to accommodate emboss coding modules without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emboss Coding Machine Market |
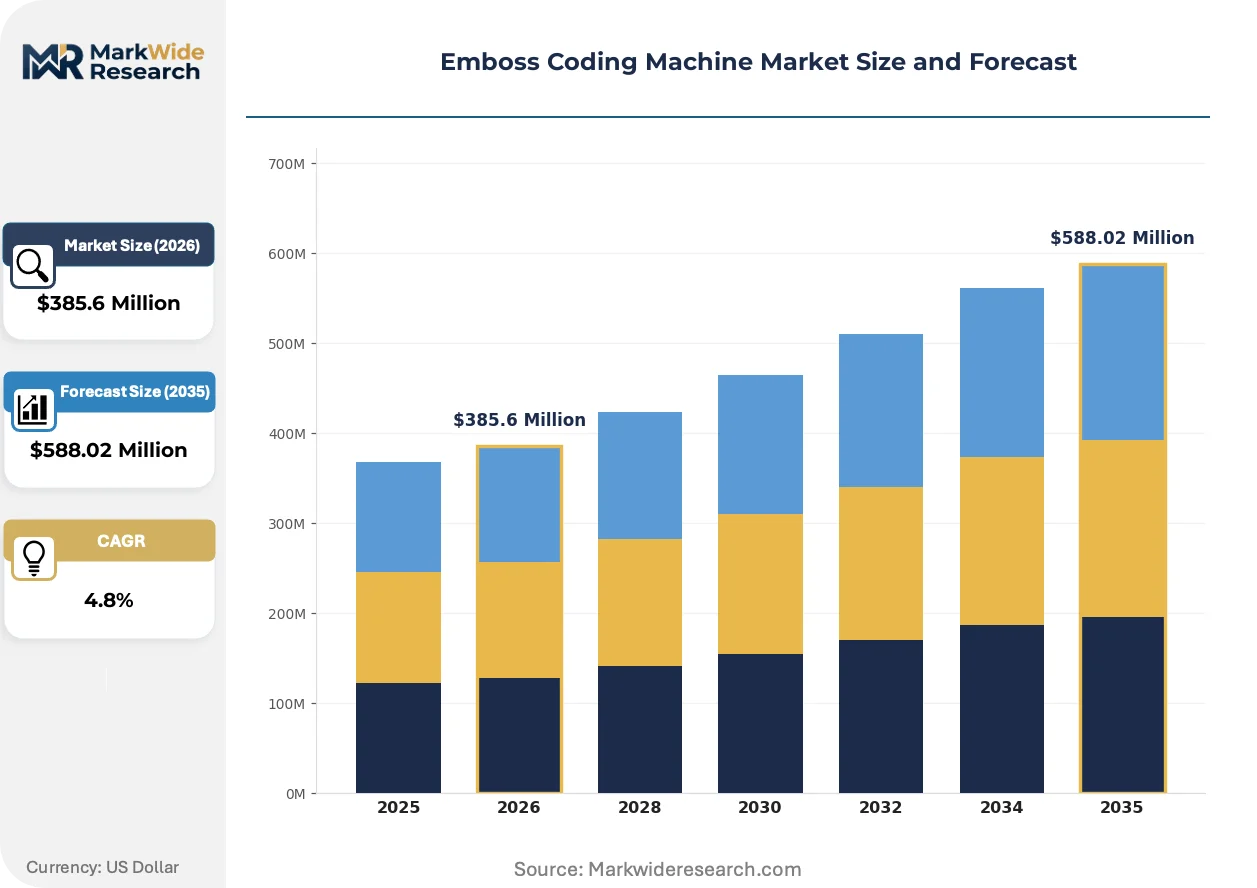
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop, Handheld, Industrial, Portable Application: Packaging, Labeling, Product Marking, Document Security Technology: Thermal Transfer, Inkjet, Laser, Hot Foil End User: Food & Beverage, Pharmaceuticals, Electronics, Cosmetics |
| Companies Covered | BOBST, Heidelberg, Komori Corporation, Gietz AG, Brandtjen and Kluge, Alliance Machine and Engraving, Pannier Corporation, Jawo Sheng Precise Machinery Works, The Bradbury Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emboss Coding Machine Market Shifts & Advancements
Equipment architecture is shifting from centralized line-integrated systems toward modular configurations that accommodate frequent substrate changes and shorter pharmaceutical production runs.
Precision register control systems are decentralizing quality assurance from centralized line operators to distributed sensor arrays that adjust die pressure in real time. Pharmaceutical contract packagers in Germany and Switzerland are adopting these systems at accelerated pace to reduce substrate waste on short serialization runs. The technology is decentralizing accountability for defect detection from post-production inspection stations to in-process monitoring nodes.
REACH restrictions on hexavalent chromium in die coatings are compressing supplier qualification timelines and forcing accelerated validation of alternative surface treatments. Industrial consequence includes extended procurement cycles for emboss tooling as converters await ECHA-compliant certification documentation. French pharmaceutical packaging lines are responding by pre-qualifying multiple tool-steel suppliers to mitigate single-source exposure.
Service contracting patterns are compressing from multi-year maintenance agreements to outcome-based performance contracts tied to line-availability metrics. Pharmaceutical OEMs in Italy and Spain are unbundling after-sales support from equipment purchases, instead procuring uptime guarantees from specialized service providers. This shift is most visible in high-volume folding carton operations where unplanned downtime carries serialization compliance penalties.
Emboss Coding Machine Market Segmentation
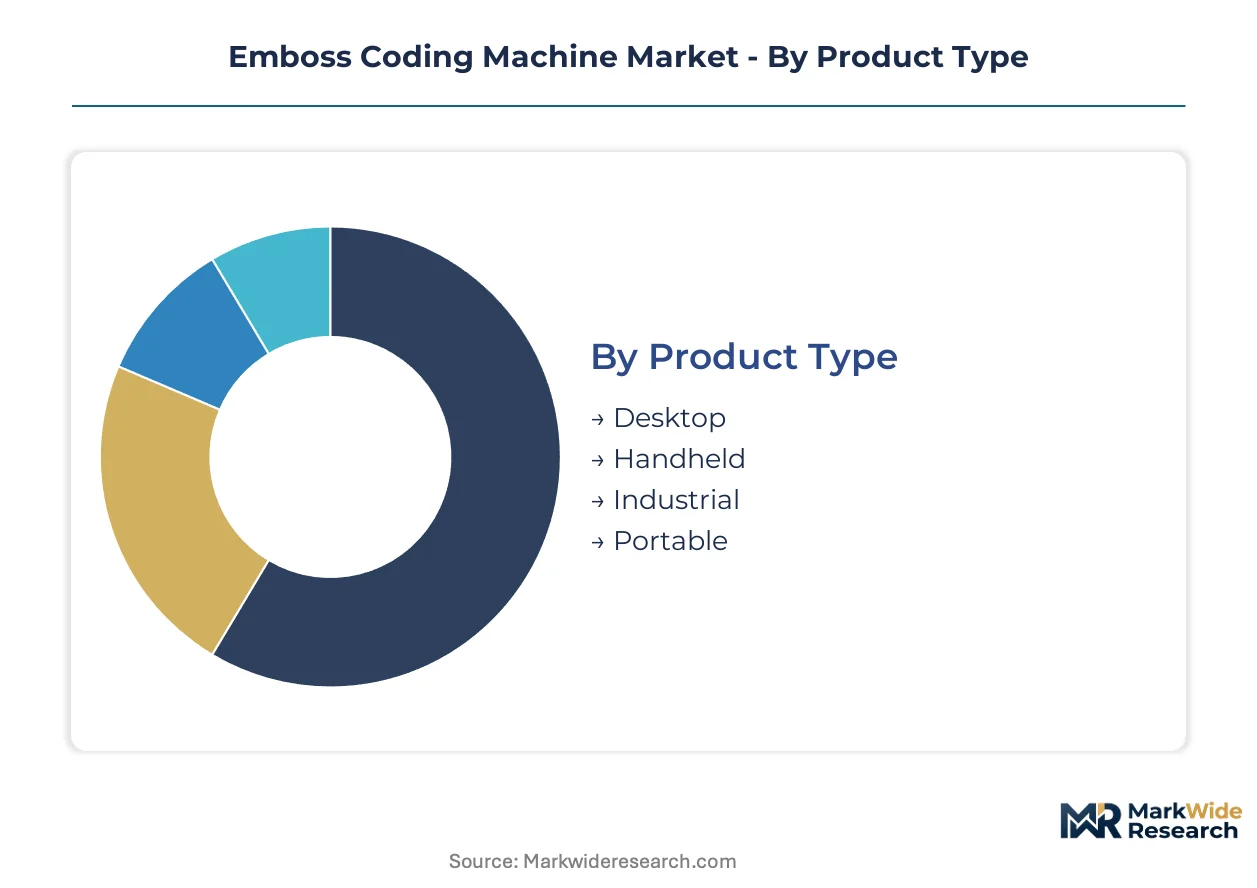
Equipment segmentation in the emboss coding machine market tracks how packaging converters prioritize capital allocation across duty cycles, substrate portfolios, and compliance mandates. Upgrade decisions hinge on line-speed requirements, serialization complexity, and the elastic recovery properties of emerging bio-based materials.
Product Type:
Replacement cycles accelerate where legacy equipment cannot accommodate compostable substrate transitions or unit-level pharmaceutical serialization at required throughput.
- Industrial:Continuous-duty systems operate at pressures from 500 to 3,000 psi on pharmaceutical blister lines exceeding 300 units per minute. Demand concentrates in Germany where BOBST and Heidelberg anchor supply for high-volume folding carton converters facing EU Falsified Medicines Directive mandates.
- Handheld:Portable units enable field-service technicians to execute warehouse and distribution serialization without line integration. French pharmaceutical contract packagers are adopting these for mobile tamper-evident marking in secondary distribution nodes.
- Desktop:Compact systems serve low-volume cosmetics prototyping and security label sampling in Italian luxury packaging clusters.
- Portable:Mid-weight configurations bridge stationary and field applications for Swiss pharmaceutical exporters requiring dual-jurisdiction validation flexibility.
Industrial systems sit at the top of the volume ranking, with Handheld climbing the fastest.
Application:
Application selection follows substrate elasticity and authentication requirements rather than generic throughput metrics.
- Packaging:Folding carton lines in France and Italy deploy rotary embossing platforms for premium cosmetics and food applications where compostable film transitions demand pressure profile recalibration.
- Labeling:Pharmaceutical serialization drives tamper-evident seal deployment on blister packs and secondary packaging across German and Spanish contract packaging operations.
- Product Marking:Direct substrate embossing serves electronics and industrial components requiring permanent identification without consumable inks.
- Document Security:Hot-foil integration dominates government and financial document authentication where metallic visual verification commands compliance premiums.
Packaging commands the largest installed base, while Labeling gains share fastest on regulatory serialization deadlines.
Technology:
Technology adoption splits between visual authentication premiums and functional readability under environmental stress.
- Hot Foil:Rotary hot-foil systems integrate metallic transfer and embossing in single-pass configurations for French and Italian luxury cosmetics packaging. REACH compliance on die coatings extends procurement timelines for certified tool-steel alternatives.
- Thermal Transfer:High-speed barcode applications in food labeling favor this technology where refrigeration-cycle readability outweighs tamper-evidence requirements, displacing emboss share in certain German dairy and meat packaging lines.
- Laser:Non-contact marking serves electronics and medical device applications requiring precision without mechanical substrate stress.
- Inkjet:Variable data printing complements emboss systems for sequential serialization on pharmaceutical lines in Switzerland and Austria.
Hot Foil retains the highest value concentration, with Thermal Transfer expanding most quickly in cost-sensitive food segments.
End User:
End-user segmentation reflects divergent compliance timelines and substrate transition maturity across European manufacturing clusters.
- Pharmaceuticals:EMA serialization rules under the EU Falsified Medicines Directive mandate machine-readable codes on every pack sold in the EU. German and Swiss contract packagers lead adoption of precision register control systems to reduce waste on short production runs.
- Cosmetics:Premiumization trends in French and Italian luxury packaging sustain demand for hot-foil embossing modules where metallic visual authentication supports price positioning.
- Food & Beverage:Compostable substrate transitions under the EU Green Deal force equipment upgrades for bio-based films with divergent elastic recovery properties in Spanish and Dutch converter operations.
- Electronics:Component traceability requirements drive compact emboss systems for circuit board and device housing identification in German industrial manufacturing zones.
Pharmaceuticals dominates capital deployment, with Food & Beverage showing the steepest expansion trajectory on sustainability-driven substrate transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering heritage established precision embossing equipment production in southern industrial zones during the post-war packaging automation wave, with BOBST and Heidelberg scaling rotary platform manufacturing from Basel and Heidelberg respectively.
Germany
Pharmaceutical blister line serialization and folding carton premiumization drive equipment procurement across Baden-Württemberg and Bavaria. EMA rules under the EU Falsified Medicines Directive mandate machine-readable codes on every pharmaceutical pack, expanding emboss coding deployment. Stuttgart and Heidelberg anchor high-precision equipment manufacturing clusters where BOBST and Heidelberg sustain technology leadership for continuous-duty pharmaceutical applications.
France
Luxury cosmetics packaging and hot-foil authentication applications concentrate demand in Île-de-France and Provence-Alpes-Côte d'Azur. REACH compliance on hexavalent chromium die coatings extends procurement timelines for certified tool-steel alternatives. Paris and Lyon-based converters pre-qualify multiple suppliers to mitigate single-source exposure while sustaining metallic visual authentication premiums.
Italy
Premium cosmetics and food labeling applications sustain rotary embossing platform demand across Lombardy and Emilia-Romagna. Compostable substrate transitions under the EU Green Deal force pressure profile recalibration for bio-based films with divergent elastic recovery properties. Milan and Bologna packaging clusters upgrade equipment portfolios to accommodate frequent substrate changes on shorter pharmaceutical production runs.
Switzerland
Pharmaceutical contract packaging and precision register control system adoption accelerate in Basel and Zurich regions. Swissmedic serialization requirements align with EMA mandates, driving dual-jurisdiction validation service demand. Basel-based packagers deploy precision register systems to reduce substrate waste on short pharmaceutical runs while maintaining compliance for EU and export markets.
Spain
Food and beverage compostable packaging transitions and pharmaceutical serialization create equipment upgrade demand across Catalonia and Madrid. Outcome-based performance contracting compresses traditional multi-year maintenance agreements into uptime-guarantee structures. Barcelona and Madrid converters unbundle after-sales support from equipment purchases, procuring line-availability guarantees from specialized service providers.
Emboss Coding Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across precision engineering and regulatory compliance capabilities. Equipment architecture differentiation separates continuous-duty pharmaceutical systems from portable field-service units. Three archetypes dominate: precision rotary platform specialists, modular handheld system developers, and integrated hot-foil convergence providers. Competitive dynamics center on M&A for substrate-handling technology and strategic partnerships for FDA dual-jurisdiction validation services.
Among Swiss and German precision engineering groups, BOBST and Heidelberg exemplify the premium-tier rotary platform archetype, while Komori Corporation occupies a position within the precision register control specialization. BOBST represents the continuous-duty pharmaceutical systems anchor, Heidelberg exemplifies integrated hot-foil and embossing module convergence, and Komori Corporation sits within the substrate waste reduction technology tier for short pharmaceutical runs.
| Leading Market Players |
|---|
| BOBST |
| Heidelberg |
| Komori Corporation |
| Gietz AG |
| Brandtjen and Kluge |
| Alliance Machine and Engraving |
| Pannier Corporation |
| Jawo Sheng Precise Machinery Works |
| The Bradbury Co. |
| Others |
Supply & Pricing Matrix
Tool-steel price indices in European metals markets cascade through emboss coding equipment manufacturing, compressing margins for certified die suppliers while amplifying pricing power for rotary platform integrators that backward-integrate into captive tooling production. REACH compliance documentation requirements extend procurement cycles, forcing converters to absorb cost premiums or shift toward outcome-based service contracts that bundle equipment and consumable pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates continuous-duty pharmaceutical systems from modular handheld units and entry-level desktop configurations. Certification grade under ECHA-compliant tool-steel standards and geographic delivery cost from southern German manufacturing clusters drive price differentiation between Swiss precision engineering and Spanish assembly operations. Cost compression in economy-tier portable units is intensifying because thermal transfer substitution in food labeling erodes emboss system value propositions. Pharmaceutical OEMs in Germany and Switzerland exhibit lowest price sensitivity due to serialization compliance penalties, while Spanish food converters face acute budget constraints on sustainability-driven equipment upgrades.
Supply Chain Analysis
Freight cost volatility on precision-engineered components from Basel and Heidelberg to Milan and Barcelona compresses converter margins and accelerates regional supplier qualification. Geographic supply concentrates in Germany, Switzerland, and Italy, with BOBST and Heidelberg anchoring rotary platform production and Komori Corporation sustaining precision register control manufacturing in Japanese facilities. Raw material dependencies center on certified tool-steel alloys, engraved die coatings, and servo-motor drive systems. Single-source vulnerability persists for REACH-compliant die surface treatments as ECHA restrictions on hexavalent chromium compress qualified supplier pools. Distribution runs through authorized dealer networks for industrial systems and direct-to-converter digital channels for handheld units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge as Swissmedic and EMA serialization alignment creates dual-jurisdiction service demand that commands premium pricing unavailable in single-market deployments, while German labor cost differentials against Spanish assembly operations enable margin capture through production footprint optimization.
For Market Incumbents: Hedge against thermal transfer substitution in food labeling by accelerating hot-foil convergence module development for premium cosmetics applications where metallic authentication sustains pricing power. Invest in backward integration into certified tool-steel die production to mitigate REACH-driven supplier qualification delays. Defensive capacity expansion in Swiss pharmaceutical packaging clusters captures dual-jurisdiction validation service demand.
For New Entrants and Emerging Players: Enter via handheld serialization tools for French and Spanish pharmaceutical contract packagers seeking mobile tamper-evident marking in secondary distribution nodes. Target underpenetrated warehouse and distribution environments where field-service technician adoption outpaces line-integrated system deployment. Pursue outcome-based performance contracting as the go-to-market angle, bundling equipment and uptime guarantees to displace traditional multi-year maintenance agreements.
For Investors and Strategic Acquirers: Consolidation pressure builds where precision register control technology fragments across mid-cap German and Swiss specialists lacking scale to serve pan-European pharmaceutical OEMs. Long-term viability favors equipment-architecture players with substrate-handling capabilities spanning compostable film transitions and legacy pharmaceutical blister lines. Acquisition target archetype: modular handheld system developers with FDA dual-jurisdiction validation infrastructure. Signal to monitor: REACH expansion into additional die coating chemistries that would further compress qualified supplier timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Die Manufacturing | Mitigates ECHA certification delays that currently extend procurement cycles for Swiss and German OEMs. |
| Dual-Jurisdiction Validation Service Launch | Captures parallel FDA and EMA compliance demand from Basel-based pharmaceutical exporters. |
| Modular Handheld Platform Development | Addresses underpenetrated warehouse serialization needs in French and Spanish distribution networks. |
| Outcome-Based Performance Contracting | Aligns with Spanish converter preference for uptime guarantees over traditional maintenance agreements. |
| Compostable Substrate Handling Upgrade | Enables Italian and Dutch converters to meet EU Green Deal packaging material specifications. |
Research Methodology
Direct dialogue with pharmaceutical packaging engineers, folding carton production managers, aftermarket service heads, and regulatory compliance officers grounded qualitative findings in operational realities across German, Swiss, French, and Italian manufacturing clusters. Secondary validation drew from EMA serialization guidance documents, ECHA REACH restriction updates, EU Green Deal implementation timelines, and SEC filings of publicly traded packaging equipment manufacturers. Bottom-up equipment shipment estimates triangulated against top-down pharmaceutical packaging line investment data.
Segmented outputs across industrial, handheld, desktop, and portable equipment types combined with pharmaceutical, cosmetics, food and beverage, and electronics end-use applications produced granular demand projections across the analysis window. Technology splits between hot foil, thermal transfer, laser, and inkjet modalities incorporated substrate elasticity parameters and regulatory authentication requirements. CAGRs derived from line-speed upgrade cycles, serialization mandate phase-in schedules, and compostable film commercialization trajectories.
Inputs from pharmaceutical OEM capital expenditure disclosures and packaging converter equipment procurement records were available through the study window; gaps in real-time bio-based film performance data introduce uncertainty bands around pressure profile recalibration assumptions. Forecasts reflect documented regulatory timelines and substrate transition commitments that remain subject to acceleration or delay. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
High Vacuum Filling Machine Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Thermal Laminating Machine Market