
 Global Bone Morphogenetic Protein Market | 2026-2036
Global Bone Morphogenetic Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Morphogenetic Protein Market Foresight
EMA MDR compliance is consolidating the European competitive landscape for recombinant human BMP suppliers. Medtronic plc leverages its deep vertical integration in collagen carrier manufacturing to sustain premium positioning across spinal fusion accounts. Stryker Corporation anchors its orthopedic trauma franchise through controlled distribution of BMP-7 formulations to hospital systems.
Bone morphogenetic proteins comprise a family of growth factors belonging to the transforming growth factor-beta superfamily, typically produced via recombinant DNA technology in mammalian cell culture systems with molecular weights ranging from approximately 30 to 38 kDa for active homodimeric forms. These signaling molecules induce osteoblastic differentiation of mesenchymal stem cells and serve as osteoinductive agents in spinal fusion, long-bone nonunion repair, and maxillofacial reconstruction. BMP-2 dominates current revenue contribution through entrenched spinal fusion adoption, while BMP-7 competes in revision settings where prior fusion attempts failed. Scaffold delivery systems attract development capital as surgeons seek alternatives to traditional collagen sponge carriers.
FDA 510(k) and PMA pathways govern US market access for recombinant BMP devices, while Japan's PMDA enforces localized clinical data requirements that extend approval timelines for foreign manufacturers. ISO 13485 quality management certification functions as a baseline predicate for supplier qualification by multinational orthopedic device firms. Stakeholders must monitor evolving carrier material biocompatibility standards and reimbursement volatility for outpatient spinal procedures.
Market Dynamics
Hospital procurement consolidation is compressing margins for recombinant BMP suppliers while simultaneously raising the technical bar for carrier system validation. Orthopedic departments now bundle bone graft substitute purchasing across spinal fusion, trauma, and maxillofacial service lines.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for next-generation collagen sponge carriers are pulling device submissions toward osteoinductive combination products.
- Japan's PMDA localized clinical data requirements:Domestic trial mandates extend foreign manufacturer timelines but create captive demand for established local partners.
- Ambulatory surgery center expansion:Outpatient spinal fusion migration in the United States is fragmenting historical hospital-centric purchasing into multi-site contracting.
Market Restraints
- Mammalian cell culture input costs:Serum and growth medium price volatility constrains recombinant protein manufacturing scale economics.
- EMA MDR biologics compliance:Evolving carrier material biocompatibility standards are extending European technical documentation timelines.
- Synthetic bone graft substitutes:Ceramic and polymer-based alternatives compete on cost in long-bone nonunion repair outside spinal fusion.
Strategic Opportunities
- Germany's hospital procurement centralization:Bundled purchasing frameworks favor suppliers with ISO 13485 certification and vertical carrier manufacturing control.
- Scaffold delivery system innovation:Hydrogel and nanofiber matrices are opening revision fusion settings where collagen sponge resorption kinetics underperform.
- India's orthopedic trauma volume expansion:Road injury reconstruction demand outpaces domestic BMP manufacturing capacity, creating import partnership windows.
Industry Challenges
- Recombinant protein purification expertise scarcity:Qualified bioprocess engineers command premium compensation in mammalian expression system operations.
- Carrier-batch sterility assurance validation:Terminal sterilization method changes trigger lengthy FDA PMA supplement reviews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Morphogenetic Protein Market |
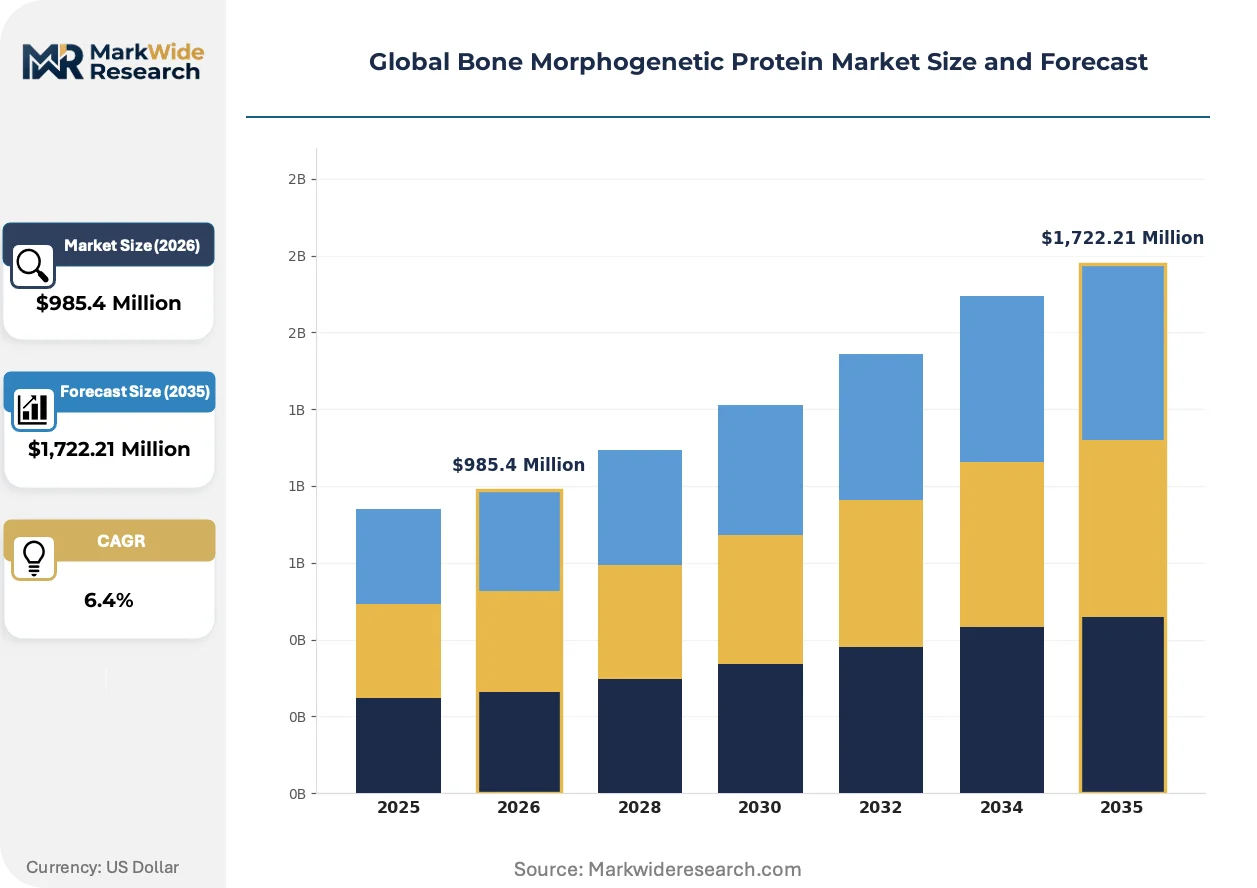
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,722.21 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BMP-2, BMP-4, BMP-7, Recombinant Human BMP Application: Spinal Fusion, Dental Bone Grafting, Orthopedic Trauma, Craniofacial Reconstruction End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutes Delivery Mode: Collagen Carriers, Synthetic Carriers, Injectable Formulations, Scaffold Delivery Systems |
| Companies Covered | Medtronic plc, Stryker Corporation, Thermo Fisher Scientific Inc., Merck KGaA, Johnson & Johnson, Bio-Techne, Zimmer Biomet Holdings, Inc., Cellumed Co., Ltd., DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Morphogenetic Protein Market Shifts & Advancements
Carrier material science is outpacing recombinant protein engineering as the primary locus of competitive differentiation. Surgeons now evaluate BMP devices through sponge handling characteristics and release kinetics rather than molecular potency alone.
Peptide-modified synthetic scaffolds are electrifying spinal fusion practice by matching osteoinductive signal duration to bone remodeling timelines. Academic medical centers in the United States are piloting these matrices in complex deformity cases where traditional collagen carriers resorb prematurely. The technology is electrifying revenue models toward premium pricing for extended-release formulations.
EU MDR Article 117 biologics requirements are forcing device manufacturers to revalidate collagen sourcing through certified Notified Body review. European orthopedic suppliers are absorbing twelve-to-eighteen-month documentation preparation cycles. Germany and France account for the majority of notified body capacity bottlenecks.
Hospital value analysis committees now dominate BMP selection decisions, displacing individual surgeon preference in the United States. Integrated delivery networks bundle bone graft purchasing across orthopedic, neurosurgical, and podiatric service lines. This concentration is most advanced in Texas and Florida health systems.
Global Bone Morphogenetic Protein Market Segmentation
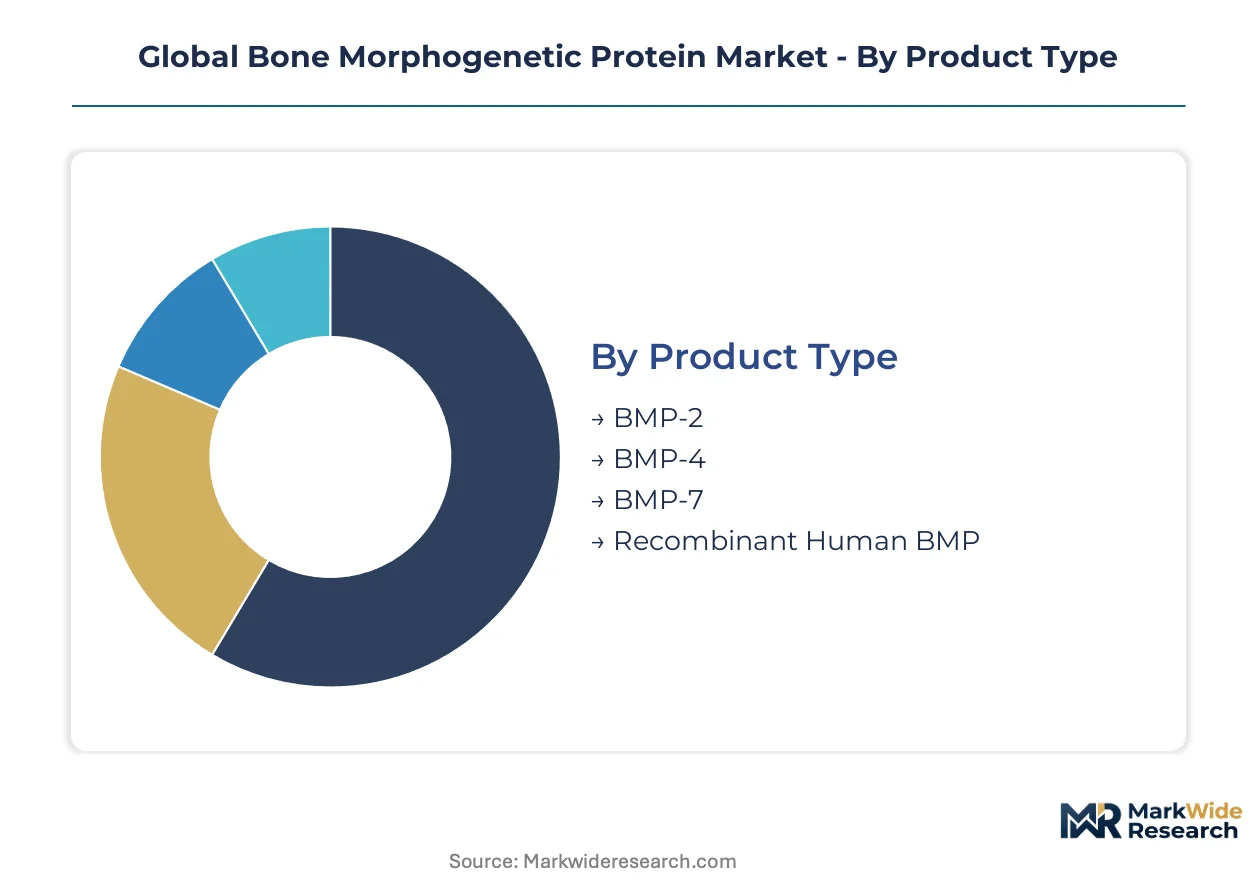
Bone morphogenetic protein purchasing fragments across molecular variants, surgical settings, and carrier technologies. Procurement committees now evaluate segments through bundled contracting frameworks that cross traditional category boundaries.
Product Type:
Standalone recombinant proteins dominate hospital formularies, while engineered variants embed into combination device systems with specialized release profiles.
- BMP-2:The 30 kDa homodimeric protein manufactured in Chinese hamster ovary cells commands the largest revenue share through entrenched spinal fusion adoption. United States hospital systems standardize on this variant for anterior lumbar interbody fusion procedures where FDA 510(k) clearance history supports reimbursement security.
- BMP-7:Also designated osteogenic protein-1, this 36 kDa signaling molecule targets revision fusion settings and long-bone nonunions where prior BMP-2 exposure failed. German orthopedic departments increasingly specify this variant for complex tibial fractures requiring alternative osteoinductive signaling.
- BMP-4:Preclinical and early clinical applications concentrate in maxillofacial reconstruction where researchers investigate dose-response relationships for mandibular continuity defects.
- Recombinant Human BMP:Engineered variants with modified glycosylation patterns or fusion tags enable extended half-life formulations for scaffold integration.
Volume placements concentrate in BMP-2; the faster expansion belongs to BMP-7.
Application:
Procedure reimbursement tiers and surgical site infection risk profiles segment demand across anatomical targets and clinical complexity levels.
- Spinal Fusion:Posterolateral lumbar and interbody fusion procedures consume the majority of recombinant BMP doses, with United States ambulatory surgery centers now qualifying for bundled payment categories that include bone graft substitutes. Medicare reimbursement volatility for multi-level fusions constrains volume growth in certain hospital referral regions.
- Orthopedic Trauma:Open tibial fractures and atrophic nonunions drive demand in trauma centers where delayed union rates justify premium biologic costs. Japan's PMDA localized clinical data requirements slow foreign manufacturer entry into this application segment.
- Dental Bone Grafting:Sinus lift and ridge augmentation procedures utilize lower doses with compressed carrier resorption timelines suited to oral healing kinetics.
- Craniofacial Reconstruction:Pediatric craniosynostosis and adult trauma reconstruction represent niche volume with specialized carrier handling requirements.
Revenue weighting tilts toward spinal fusion; trauma applications climb the fastest as surgical techniques advance.
End User:
Capital intensity and case volume thresholds determine which facility types maintain on-site biologic inventory versus consignment arrangements.
- Hospitals:Academic medical centers and community hospital systems with orthopedic service lines exceeding annual fusion volume thresholds negotiate direct purchasing agreements with recombinant protein manufacturers. Value analysis committees in Texas and Florida health systems now control selection decisions previously delegated to individual surgeons.
- Ambulatory Surgical Centers:Outpatient spinal fusion migration in the United States fragments historical hospital-centric purchasing into multi-site contracting with specialized distributor networks.
- Specialty Clinics:Oral and maxillofacial surgery practices maintain limited inventory for predictable dental grafting volumes.
- Research Institutes:Academic laboratories investigating next-generation scaffold systems drive small-volume demand for research-grade recombinant proteins.
Procurement concentration sits with hospital systems; ambulatory surgical centers expand most quickly as site-of-service shifts accelerate.
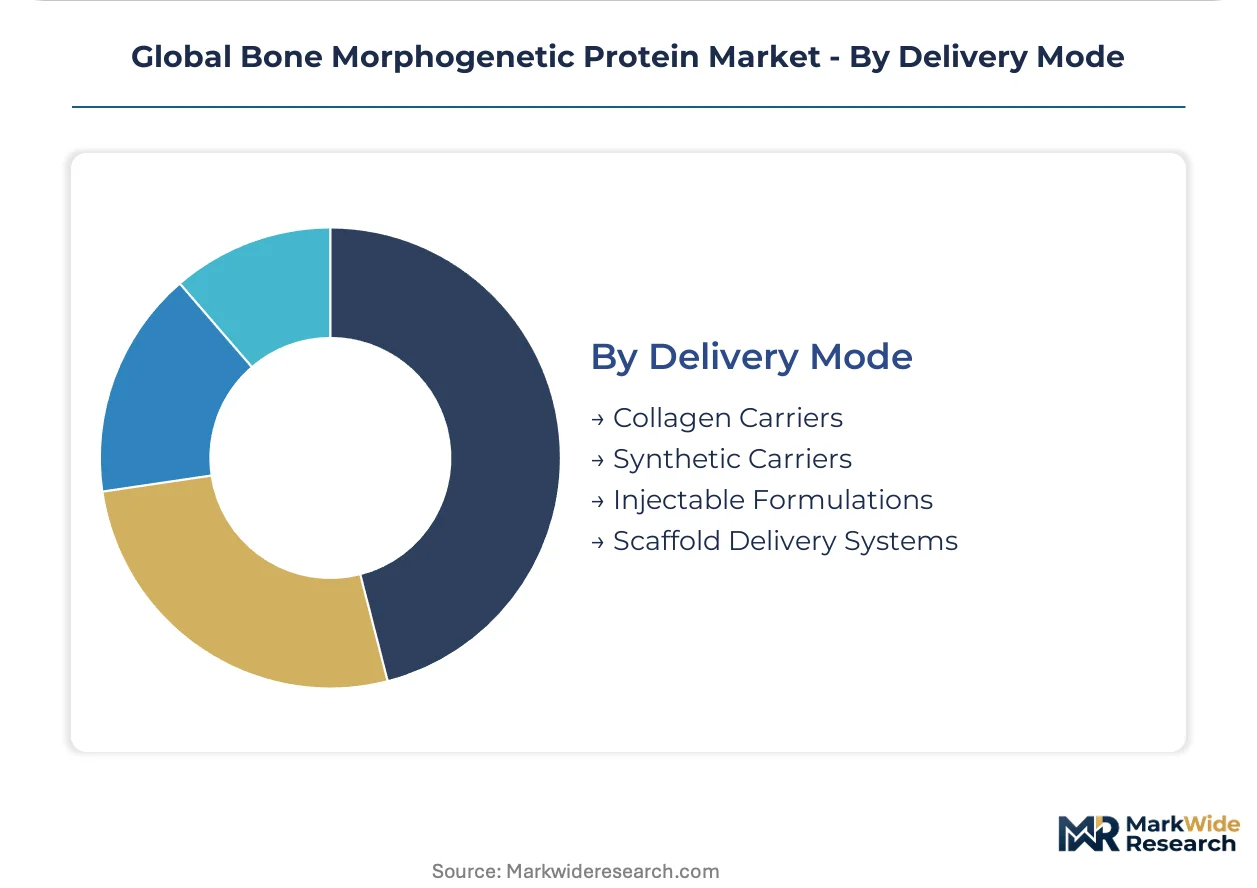
Delivery Mode:
Carrier material science now dominates competitive differentiation more than recombinant protein engineering, with handling characteristics and release kinetics determining surgeon preference.
- Collagen Carriers:Bovine type I collagen sponges remain the reference standard for spinal fusion, with Medtronic plc's deep backward integration into collagen manufacturing sustaining premium positioning. EMA MDR Article 117 requirements now force revalidation of sourcing through certified Notified Body review, extending European technical documentation timelines.
- Scaffold Delivery Systems:Hydrogel and nanofiber matrices attract development capital for revision fusion settings where traditional collagen sponge resorption kinetics underperform. Academic medical centers in the United States pilot peptide-modified synthetic scaffolds in complex deformity cases.
- Synthetic Carriers:Ceramic and polymer-based alternatives compete on cost in long-bone nonunion repair outside spinal fusion applications.
- Injectable Formulations:Minimally invasive delivery systems target vertebral compression fractures and smaller bone defects where open surgical exposure is undesirable.
Installed base concentrates in collagen carriers; scaffold delivery systems gain share fastest as material science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement of BMP-2 and BMP-7 concentrates in the United States, Germany, and Japan where aging demographics and established reimbursement frameworks for bone graft substitutes support sustained adoption. The regulatory pathways in these markets reshape how manufacturers validate carrier systems and recombinant purity benchmarks.
United States
Spinal fusion migration toward ambulatory surgery centers fragments historical hospital-centric purchasing into multi-site contracting across Texas and Florida health systems. FDA 510(k) clearance pathways accelerate device submissions for next-generation collagen sponge carriers. Value analysis committees in integrated delivery networks now dominate BMP selection decisions previously delegated to individual surgeons.
Germany
Bundled purchasing frameworks favor suppliers with ISO 13485 certification and vertical control over carrier manufacturing. EMA MDR Article 117 biologics requirements force manufacturers to revalidate collagen sourcing through certified Notified Body review. Bavaria and Baden-Württemberg host orthopedic clusters where hospital procurement centralization compresses margins for recombinant BMP suppliers.
Japan
PMDA localized clinical data requirements extend approval timelines for foreign manufacturers but create captive demand for established domestic partners. Road injury reconstruction demand outpaces domestic BMP manufacturing capacity in trauma centers across Kanto and Kansai regions. METI industrial policy supports biologics manufacturing scale-up to reduce import dependency.
India
Road injury reconstruction demand in orthopedic trauma outpaces domestic BMP manufacturing capacity, creating import partnership windows for foreign suppliers. CDSCO regulatory pathways for biologics require localized stability data that extends market entry timelines. Maharashtra and Karnataka medical device clusters concentrate distribution networks for imported recombinant proteins.
China
NMPA biologics registration regulations mandate domestic clinical trials for recombinant BMP products that extend approval timelines for multinational firms. Yangtze River Delta orthopedic centers drive demand for spinal fusion procedures as aging demographics accelerate. Local manufacturers in Jiangsu and Zhejiang provinces expand mammalian cell culture capacity to substitute imports.
Global Bone Morphogenetic Protein Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions through regulatory compliance depth. The vendor base clusters around three strategic archetypes: diversified orthopedic conglomerates with captive biologics manufacturing, pure-play recombinant protein suppliers focused on carrier innovation, and regional trauma-focused distributors. Dominant competitive moves include strategic partnerships for scaffold delivery system development and backward integration into collagen carrier production.
Within the diversified orthopedic tier, Medtronic plc and Stryker Corporation exemplify scale-driven positioning through deep backward integration into collagen manufacturing and controlled distribution to hospital systems. Zimmer Biomet Holdings, Inc. occupies a position among reconstructive surgery specialists seeking scaffold innovation partnerships. Thermo Fisher Scientific Inc. represents the life sciences tools archetype supplying research-grade recombinant proteins and bioprocessing technologies to BMP manufacturers.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Johnson & Johnson |
| Bio-Techne |
| Zimmer Biomet Holdings, Inc. |
| Cellumed Co., Ltd. |
| DePuy Synthes |
| Others |
Supply & Pricing Matrix
EMA MDR Article 117 biocompatibility mandates now gate qualified supply access and premium-tier pricing power for recombinant BMP suppliers, forcing manufacturers to absorb twelve-to-eighteen-month revalidation cycles before commanding hospital formulary placement.
Pricing Analysis
Short lead-time premiums now separate emergency procurement from scheduled surgical inventory in United States hospital systems. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and carrier material biocompatibility tier. Cost compression in standard-tier collagen carriers is intensifying because mammalian cell culture input costs face serum and growth medium price volatility. Ambulatory surgery centers exhibit the highest price sensitivity due to fragmented multi-site contracting, while academic medical centers with direct manufacturer agreements show the least.
Supply Chain Analysis
Mammalian cell culture capacity rests on United States, Germany, and Chinese bioprocessing infrastructure for serum-dependent recombinant protein production. Raw material dependencies center on fetal bovine serum, type I collagen sourcing, and specialized growth media formulations. Single-source vulnerability concentrates in bovine collagen sponge carriers subject to EMA MDR sourcing revalidation. Distribution runs through hospital GPO contracts and specialized orthopedic distributor networks serving ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone morphogenetic protein market sits in a carrier technology transition phase, with peptide-modified synthetic scaffolds displacing legacy collagen sponges in revision fusion settings.
For Market Incumbents: Lock in backward integration into collagen manufacturing to defend against hydrogel and nanofiber scaffold substitutes. Prioritize ISO 13485 certification maintenance under evolving EMA MDR requirements to preserve hospital GPO contract eligibility. Secure captive supply of bovine type I collagen before Notified Body review bottlenecks extend European sourcing timelines. For New Entrants and Emerging Players: Scaffold delivery system innovation offers the most penetrable wedge against entrenched collagen carrier incumbents. Target India's orthopedic trauma segment where road injury reconstruction demand outpaces domestic BMP manufacturing capacity. Pursue CDSCO regulatory partnerships with Maharashtra and Karnataka medical device clusters to compress import distribution timelines. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for next-generation carriers is the leading indicator that material science differentiation will consolidate competitive positioning. The five-to-ten-year viability window favors acquisition targets with vertical control over carrier manufacturing and established hospital system relationships. Watch PMDA localized clinical data requirement relaxations as the signal for Japanese market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Article 117 Compliance Program | Notified Body certification unlocks German hospital procurement centralization contracts. |
| Scaffold Delivery System R&D Partnership | Peptide-modified synthetic matrices capture revision fusion premium pricing tiers. |
| India Import Distribution Network Buildout | Maharashtra trauma centers create partnership windows for foreign BMP suppliers. |
| Collagen Carrier Backward Integration | In-house bovine type I production insulates against EMA sourcing revalidation delays. |
| Ambulatory Surgery Center Contracting Specialist | Multi-site purchasing fragmentation in Texas and Florida demands dedicated channel focus. |
Research Methodology
Document review covered FDA 510(k) filings, EMA MDR technical documentation, hospital GPO contract databases, and CDSCO biologics registration records, complemented by interviews with orthopedic surgeons, hospital value analysis committee members, biomedical engineers, and recombinant protein manufacturing executives. Secondary validation drew from CMS Medicare reimbursement data, ISO 13485 certification registries, and mammalian cell culture trade publications. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to derive market sizing.
Historical volume trends were cross-referenced against expert panel input across molecular variant, surgical application, carrier technology, and end-user facility type segmentation dimensions. CAGRs were derived through regression analysis of procurement volume trajectories and pricing elasticity patterns. Forecast inputs incorporated ambulatory surgery center site-of-service migration rates and EMA MDR compliance timeline assumptions throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA regulatory delay scenarios or mammalian cell culture input cost spikes. Forecasts reflect documented assumptions on reimbursement stability and carrier material innovation adoption curves. A small set of named triggers—FDA 510(k) pathway streamlining decisions, Notified Body capacity expansion in Germany and France, and METI biologics manufacturing subsidies—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market
Pharmaceuticals
Chronic Kidney Disease (CKD) Drugs Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Small Volume Parenteral Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market