
 Cytokine Storm Therapy Market | 2026-2036
Cytokine Storm Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Cytokine Storm Therapy Market Outlook
Outcome-based reimbursement for cytokine storm management is shifting how biopharmaceutical contracts are structured in critical care settings. Roche sustains broad immunology infrastructure spanning diagnostic-to-therapeutic integration. Amgen specializes in TNF-alpha pathway modulation with established manufacturing scale. CytoSorbents occupies extracorporeal cytokine removal as a parallel technology track to pharmacologic intervention.
Cytokine storm therapy encompasses pharmacologic and mechanical interventions designed to interrupt hyperinflammatory cascades characterized by elevated interleukin-6, TNF-alpha, and interferon-gamma levels, typically administered via intravenous infusion in monitored clinical settings to prevent multi-organ failure. Monoclonal antibodies targeting the IL-6 receptor anchor current standard-of-care protocols and command the largest existing revenue pool. Cytokine inhibitors represent the fastest-expanding product category as next-generation biologics enter Phase III programs. Combination therapies are emerging where sequential or simultaneous pathway blockade addresses refractory presentations.
The FDA, EMA, and WHO collectively shape cytokine storm therapy development through emergency use authorization frameworks, post-market pharmacovigilance requirements, and pandemic preparedness protocols that accelerate trial enrollment. These regulators enforce divergent evidentiary standards for surrogate endpoints, creating complexity for sponsors pursuing simultaneous US and European filings. Stakeholders must monitor evolving biomarker qualification pathways and adaptive licensing mechanisms that will determine which therapeutic platforms achieve sustainable market access.
Market Dynamics
The FDA's accelerated approval pathways for immunomodulatory therapies are compressing commercial timelines and reshaping how sponsors design pivotal trials for cytokine-directed interventions. This regulatory pressure is forcing parallel development tracks across pharmacologic and mechanical intervention categories.
Growth Catalysts
- Hospital ICU Expansion:Academic medical centers in the United States are expanding dedicated cytokine storm response units for sepsis and CAR-T complications. This infrastructure investment creates dedicated demand channels for IL-6 receptor antagonists and extracorporeal removal systems.
- EMA Adaptive Licensing:The European Medicines Agency's adaptive pathways framework enables conditional approval based on surrogate biomarker endpoints. Sponsors are leveraging this mechanism to advance next-generation biologics through Phase III with reduced patient exposure requirements.
- Biomarker-Guided Triage:Elevated interleukin-6 and TNF-alpha testing protocols are standardizing patient selection for intervention. Diagnostic integration is unifying therapeutic decision-making across emergency departments and oncology infusion centers.
Market Restraints
- Plasma-Derived Input Volatility:Monoclonal antibody production depends on fractionated plasma supply concentrated in United States collection networks. Harvest disruptions or viral screening protocol changes transmit directly to manufacturing cost structures.
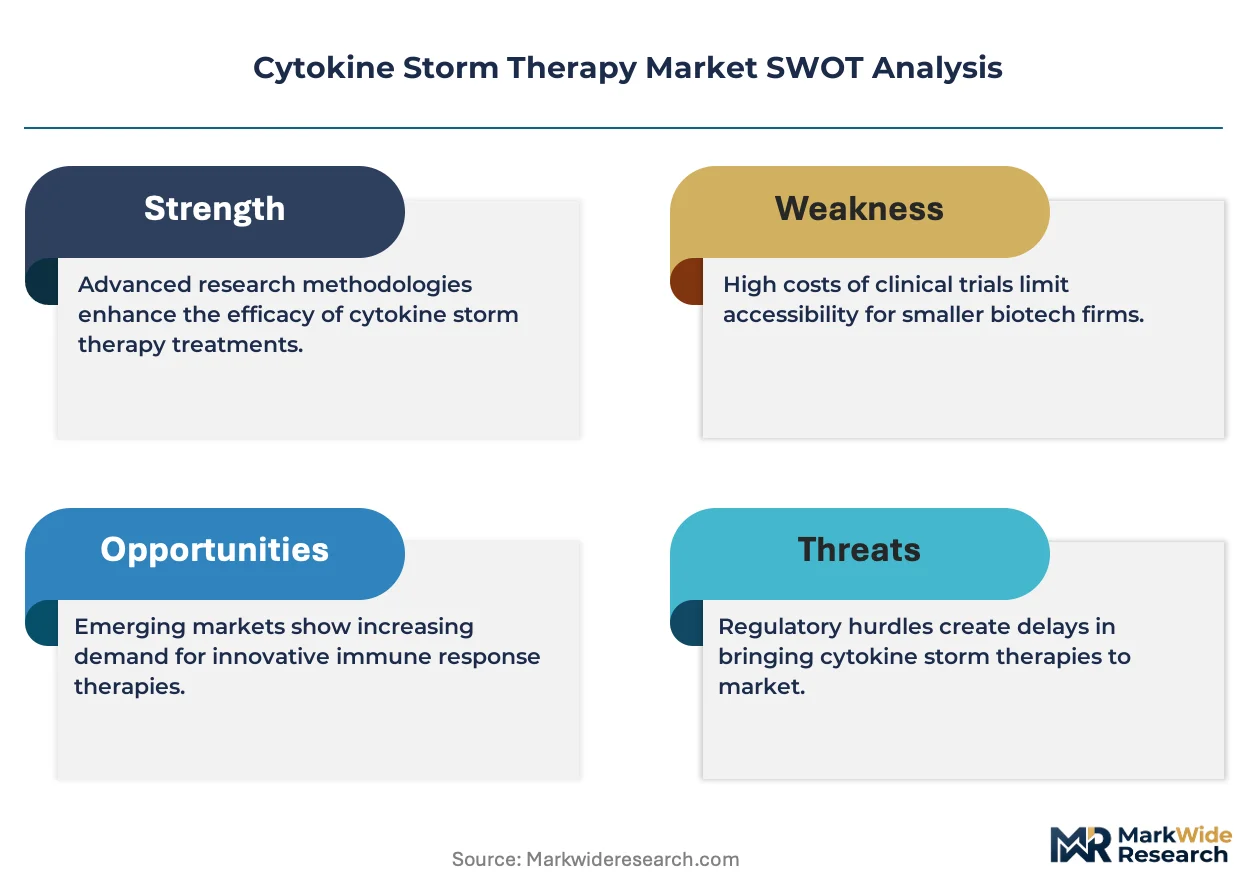
- Divergent Evidentiary Standards:The FDA and EMA enforce incompatible requirements for surrogate endpoint qualification. Sponsors pursuing simultaneous filings face duplicated trial designs or sequential regulatory submissions that extend capital lock-up periods.
- Extracorporeal Substitution Threat:CytoSorbents' cytokine adsorption technology offers non-pharmacologic intervention for refractory cases. This parallel technology track captures patients who fail first-line biologic therapy or present contraindications to monoclonal antibodies.
Strategic Opportunities
- Combination Protocol White Space:Sequential IL-6 and TNF-alpha blockade addresses refractory presentations unresponsive to single-pathway inhibition. Investigational programs are exploring simultaneous receptor antagonism in academic medical center settings.
- Outcome-Based Contracting:Payers are piloting reimbursement tied to ICU length-of-stay reduction and ventilator-free days. This shifts contract structure from per-dose pricing toward bundled critical care episode payments.
- India Manufacturing Scale:Contract development and manufacturing organizations in India offer cost-competitive biologics production under CDSCO oversight. Multinational sponsors are qualifying secondary supply sources to reduce geographic concentration risk.
Industry Challenges
- Immunology Specialist Shortage:Cytokine storm management requires intensivists with dual training in immunology and critical care. Fellowship programs are not producing sufficient specialists to staff expanding ICU protocols.
- Legacy EHR Integration Friction:Real-time cytokine level reporting requires bidirectional interfaces between laboratory information systems and medication ordering workflows. Hospital IT departments face multi-year upgrade cycles to enable closed-loop decision support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cytokine Storm Therapy Market |
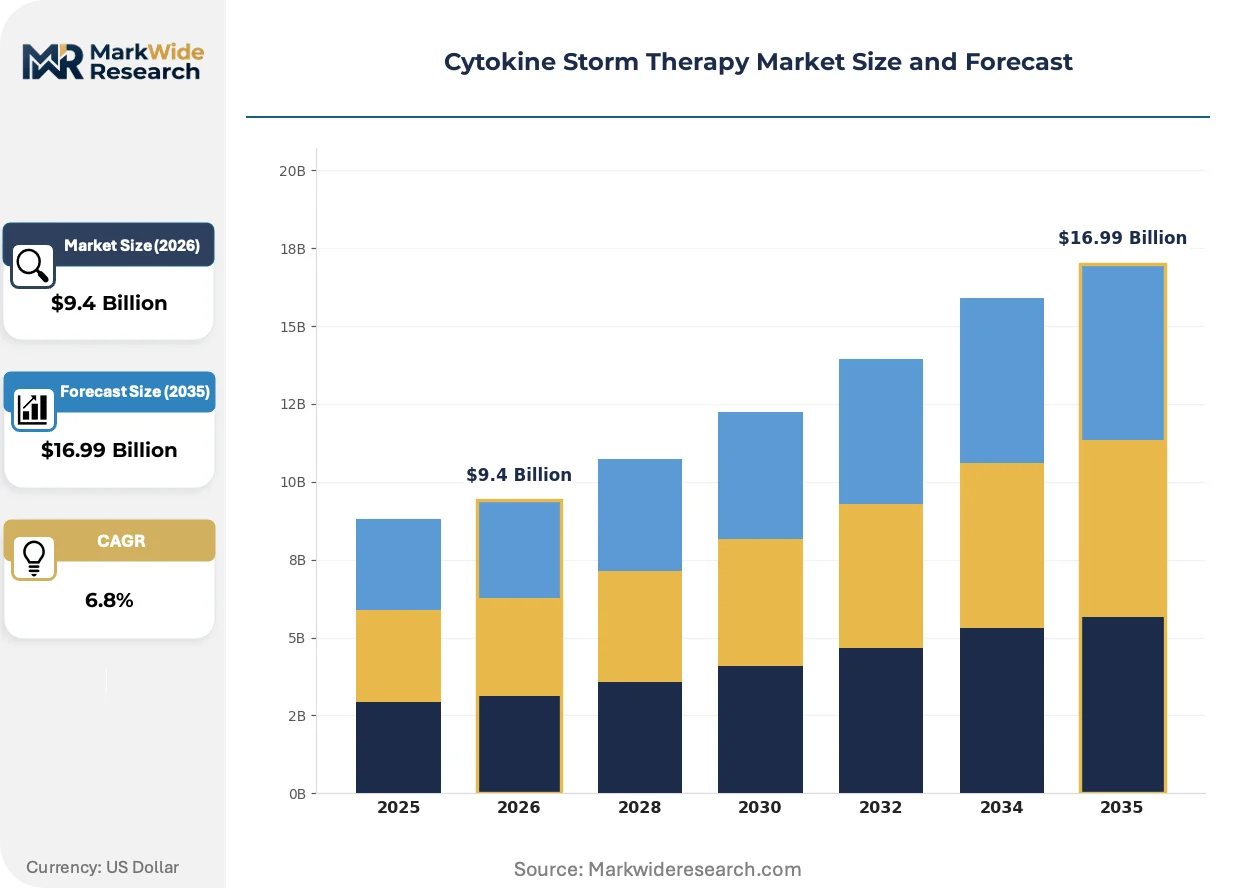
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Autoimmune Disorders, Infectious Diseases, Cancer, Genetic Conditions Product Type: Monoclonal Antibodies, Cytokine Inhibitors, Small Molecule Drugs, Combination Therapies Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Specialty Clinics, Research Labs, Homecare |
| Companies Covered | Jazz Pharmaceuticals, Swedish Orphan Biovitrum, Roche, Amgen, AbbVie, Novartis, CytoSorbents, Johnson & Johnson, Incyte Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cytokine Storm Therapy Market Strategic Shifts
Diagnostic-to-therapeutic integration is compressing the interval between biomarker elevation and intervention initiation. This convergence is reshaping competitive positioning around response speed rather than standalone efficacy claims.
Multiplex cytokine profiling platforms are unifying IL-6, TNF-alpha, and interferon-gamma quantification into single-assay workflows. Hospital laboratories in Germany and the United States are adopting these systems to replace sequential ELISA testing. This unification is compressing turnaround times from hours to minutes and enabling point-of-care triage decisions in emergency departments.
The WHO's pandemic preparedness protocols are mandating stockpiling frameworks for immunomodulatory therapies with demonstrated cytokine storm efficacy. National strategic reserves in Japan and South Korea now include IL-6 receptor antagonists alongside ventilators and antivirals. Manufacturers with pre-negotiated procurement agreements are securing multi-year offtake commitments that insulate revenue from routine demand fluctuation.
Critical care purchasing consortia are consolidating procurement authority for high-cost biologics under centralized pharmacy and therapeutics committees. Individual hospital formularies are losing autonomy as integrated delivery networks in the United States negotiate enterprise-wide contracts. This concentration is most visible in California and Texas, where multi-hospital systems command sufficient volume to extract performance-based rebates and dedicated supply allocations.
Cytokine Storm Therapy Market Segmentation
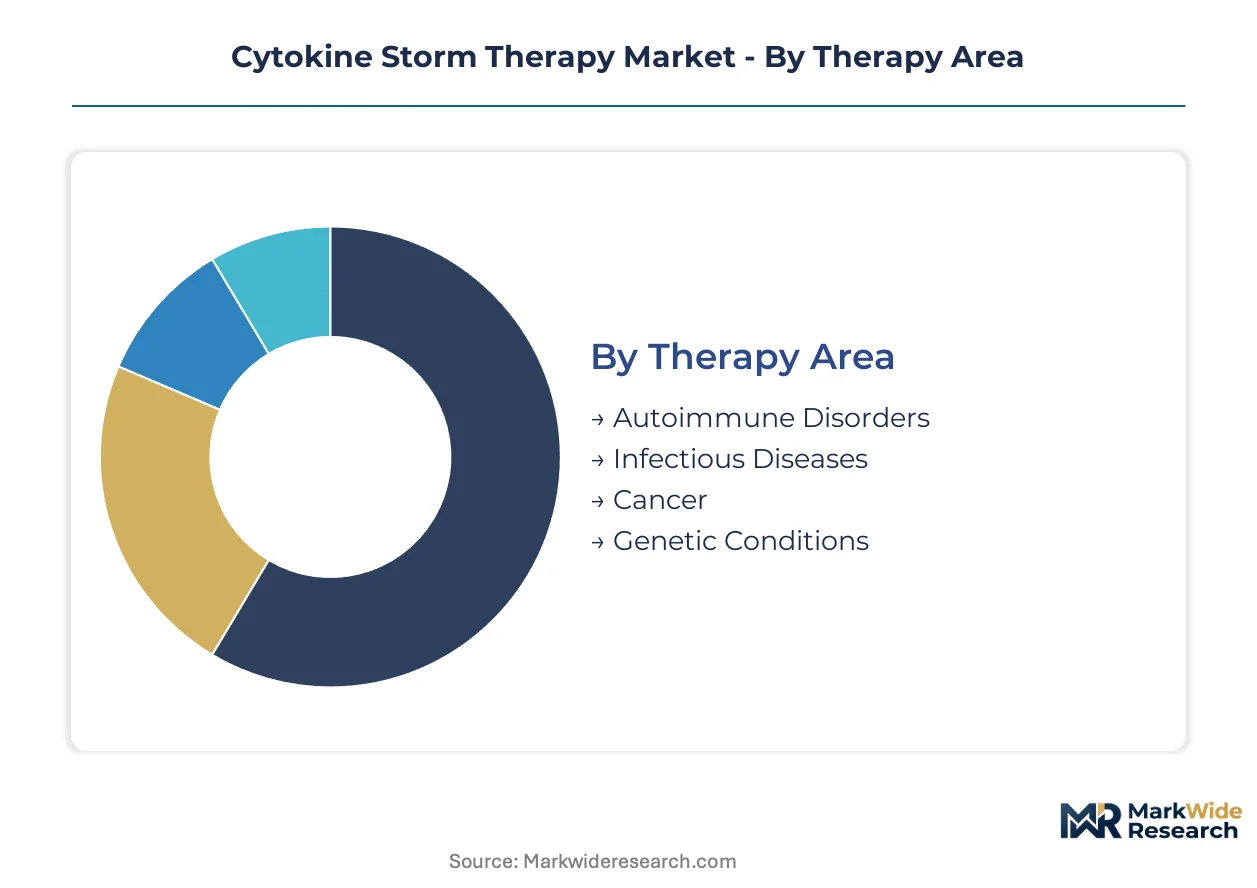
Therapeutic modality and care setting segmentation determines reimbursement pathways and manufacturing scale requirements for cytokine storm interventions. Product type and delivery mode classifications dictate regulatory submission strategies and hospital formulary placement.
Therapy Area:
Volume concentrates in infectious disease applications while premium pricing attaches to oncology protocols.
- Infectious Diseases:Sepsis and viral pneumonia drive the largest patient volumes through emergency departments and medical ICUs. United States academic medical centers anchor demand for IL-6 receptor antagonists in severe community-acquired infections.
- Cancer:CAR-T cell therapy complications and checkpoint inhibitor toxicities command the highest per-patient treatment costs. Memorial Sloan Kettering and MD Anderson anchor protocol development for cytokine release syndrome management.
- Autoimmune Disorders:Systemic lupus erythematosus and macrophage activation syndrome represent established indications with mature payer coverage frameworks.
- Genetic Conditions:Hemophagocytic lymphohistiocytosis and rare autoinflammatory diseases attract orphan drug designations and accelerated regulatory pathways.
Today's leader: Infectious Diseases. Tomorrow's challenger: Cancer.
Product Type:
Cost tier separation runs deepest between established biologics and emerging small molecule alternatives.
- Monoclonal Antibodies:Tocilizumab and siltuximab dominate current standard-of-care with validated manufacturing processes and broad payer contracts. Hospital pharmacies in Germany and Japan maintain dedicated cold chain infrastructure for these temperature-sensitive biologics.
- Cytokine Inhibitors:Next-generation biologics targeting multiple inflammatory pathways are expanding most quickly through Phase III programs. Sponsors are leveraging EMA adaptive pathways to compress development timelines.
- Small Molecule Drugs:Oral JAK inhibitors and other synthetic agents offer storage and administration advantages over biologics. Formulary committees evaluate these for step-therapy protocols.
- Combination Therapies:Sequential IL-6 and TNF-alpha blockade addresses refractory presentations unresponsive to monotherapy. Academic medical centers pilot these protocols under institutional review board oversight.
Established dominance belongs to monoclonal antibodies. Cytokine inhibitors are climbing the fastest toward commercial parity.
Delivery Mode:
Application context determines route selection, with acute care settings demanding immediate bioavailability.
- Intravenous:First-line cytokine storm management requires rapid serum concentration achievement in monitored settings. Infusion centers at Cleveland Clinic and Mayo Clinic process the highest volumes of IL-6 antagonist administrations.
- Subcutaneous:Outpatient maintenance protocols for chronic autoinflammatory conditions utilize prefilled syringe formats. Rheumatology practices in France and the United Kingdom favor this route for patient self-administration training.
- Oral:Small molecule agents enable community-based initiation and step-down therapy after acute stabilization.
- Intramuscular:Emergency department triage protocols occasionally employ this route when vascular access is compromised.
Intravenous administration commands current utilization. Subcutaneous formats are gaining share fastest in outpatient expansion.
End User:
Customer type segmentation reveals divergent procurement authority and clinical decision-making structures.
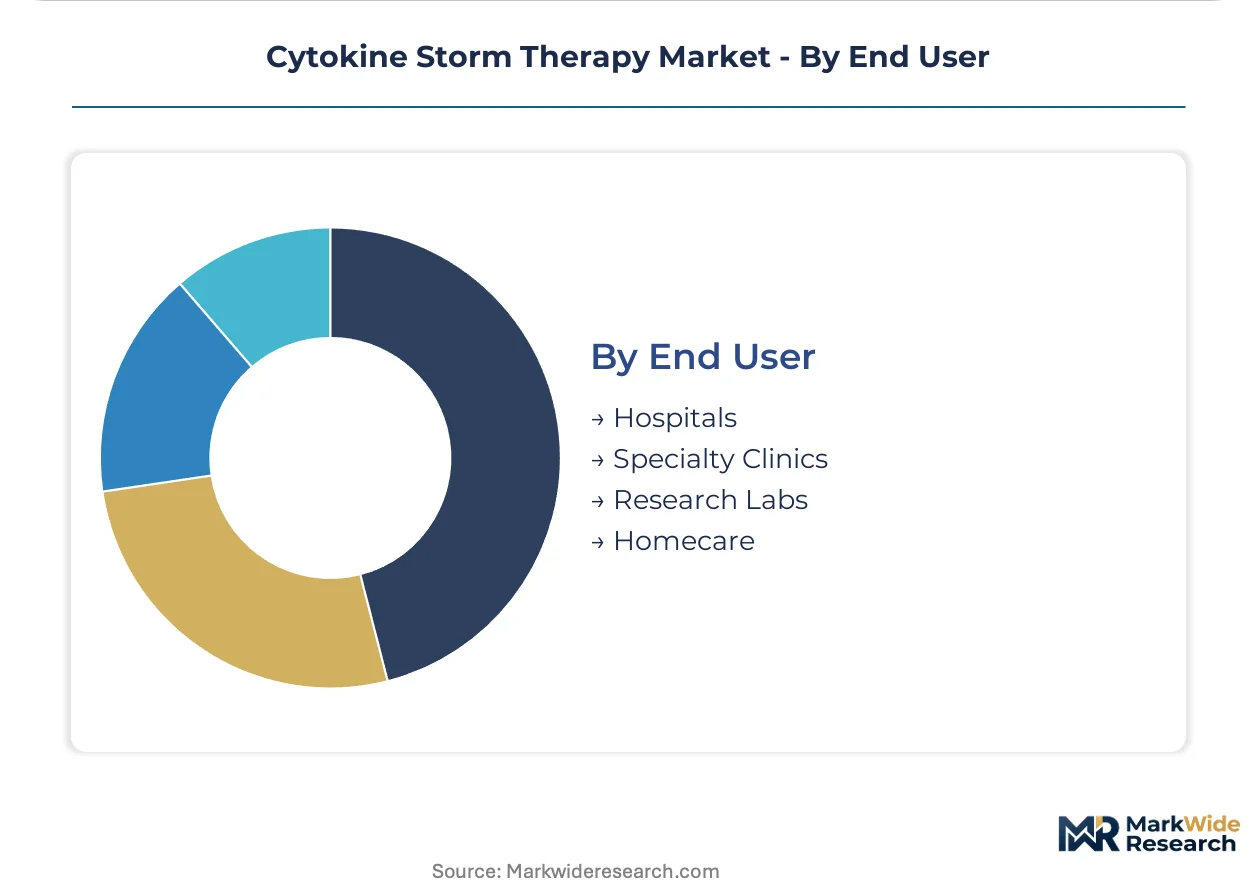
- Hospitals:Integrated delivery networks in Texas and California consolidate purchasing for high-cost biologics under centralized pharmacy committees. These institutions command performance-based rebates and dedicated supply allocations.
- Specialty Clinics:Rheumatology and oncology infusion centers manage chronic cytokine dysregulation with protocolized monitoring. United States community oncology practices are qualifying for CAR-T toxicity management certification.
- Research Labs:Academic medical centers conduct investigator-initiated trials exploring combination pathway blockade.
- Homecare:Subcutaneous administration enables selected patients to transition from inpatient to residential settings with nursing support.
Hospitals dominate procurement volume. Specialty clinics represent the steepest expansion trajectory in outpatient protocol development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in cytokine storm therapy deployment velocity, with German university hospitals standardizing IL-6 protocols faster than American community hospitals. Japan and India occupy opposite ends of the manufacturing spectrum, where Japanese precision biologics contrast with Indian contract manufacturing scale. The United Kingdom anchors European regulatory harmonization efforts through MHRA alignment post-Brexit.
United States
Academic medical centers at Cleveland Clinic and Mayo Clinic process the highest volumes of IL-6 antagonist infusions for CAR-T complications. FDA accelerated approval pathways compress commercial timelines for immunomodulatory therapies entering pivotal trials. Texas and California integrated delivery networks consolidate procurement under centralized pharmacy committees commanding performance-based rebates.
Germany
University hospitals in Berlin and Heidelberg anchor European protocol development for sepsis-directed cytokine intervention. EMA adaptive licensing enables conditional approval based on surrogate biomarker endpoints, reducing Phase III patient exposure requirements. The Eindhoven-to-Munich corridor concentrates diagnostic-to-therapeutic integration infrastructure for multiplex cytokine profiling.
Japan
Memorial Sloan Kettering and MD Anderson equivalents in Tokyo and Osaka drive premium pricing for oncology cytokine release syndrome management. METI pandemic preparedness protocols mandate national strategic reserves including IL-6 receptor antagonists alongside ventilators. The Kanto region houses PMDA-qualified manufacturing for temperature-sensitive biologics cold chain distribution.
India
CDSCO oversight of contract development and manufacturing organizations attracts multinational sponsors seeking cost-competitive biologics production. Maharashtra and Gujarat host secondary supply qualification programs reducing geographic concentration risk for plasma-derived inputs. Bangalore academic medical centers pilot combination IL-6 and TNF-alpha blockade protocols under institutional review board oversight.
United Kingdom
Rheumatology practices in London and Manchester favor subcutaneous administration formats for patient self-administration training in chronic autoinflammatory conditions. MHRA post-Brexit regulatory autonomy enables faster adaptive pathway adoption than EMA centralized procedures. The Cambridge-Oxford-London triangle concentrates investigator-initiated trials exploring sequential pathway blockade.
Cytokine Storm Therapy Market Competitive Environment
Top-tier vendors anchor biologics manufacturing and diagnostic integration, while mid-cap specialists occupy extracorporeal technology and combination protocol development. The vendor base stratifies across three archetypes: diversified pharmaceutical conglomerates with immunology infrastructure, targeted biologics manufacturers with pathway-specific expertise, and device-therapeutic hybrids offering mechanical cytokine removal. Consolidation pressures favor M&A activity around manufacturing scale and strategic partnerships bridging pharmacologic and mechanical intervention categories.
Within the diversified pharmaceutical tier, Roche and Amgen exemplify contrasting strategic positions. Roche sustains broad diagnostic-to-therapeutic integration spanning cytokine level quantification through IL-6 receptor antagonist administration. Amgen occupies TNF-alpha pathway modulation with established manufacturing scale and payer contract breadth. CytoSorbents represents the device-therapeutic hybrid archetype, anchoring extracorporeal cytokine adsorption as a parallel intervention track for refractory cases and monoclonal antibody contraindications.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals |
| Swedish Orphan Biovitrum |
| Roche |
| Amgen |
| AbbVie |
| Novartis |
| CytoSorbents |
| Johnson & Johnson |
| Incyte Corporation |
| Others |
Value Chain & Pricing Dynamics
Plasma-derived immunoglobulin inputs originating from United States collection networks flow through fractionation facilities into three-tier pricing structures across premium, standard, and economy levels. Cold chain logistics costs and viral screening protocol compliance stack onto base manufacturing expenses before hospital procurement committees negotiate performance-based rebates.
Pricing Analysis
Capacity additions in India are reshaping price floors for contract biologics manufacturing under CDSCO oversight. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved originator products from EMA-authorized biosimilars and Indian-manufactured alternatives. Pricing pressure stems from extracorporeal substitution threats as CytoSorbents captures refractory cases. Academic medical centers demonstrate lowest price sensitivity due to outcome-based contracting pilots; community hospitals face tightest budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with United States plasma collection networks that feed global monoclonal antibody production. Manufacturing draws from fractionated plasma, temperature-sensitive biologics cold chain infrastructure, and single-use bioreactor components. Tariff exposure runs through pharmaceutical ingredient classifications in trade disputes. Distribution runs through hospital centralized pharmacy committees and integrated delivery network procurement consortia in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where CAR-T complication management and sepsis protocols shift demand toward premium-grade IL-6 receptor antagonists with validated cold chain integrity.
For Market Incumbents: Anticipate extracorporeal substitution by securing dual-source plasma supply agreements and embedding diagnostic-to-therapeutic integration deeper into hospital IT workflows. Defensive moves center on backward integration into plasma collection networks and qualifying secondary manufacturing sites in India under CDSCO oversight. The priority lever sits with outcome-based contracting pilots that lock in multi-year offtake commitments before mechanical intervention technologies mature. For New Entrants and Emerging Players: Enter via combination protocol white space where sequential IL-6 and TNF-alpha blockade addresses refractory presentations in academic medical centers. The most penetrable segment spans investigator-initiated trials at Cleveland Clinic and Mayo Clinic equivalents seeking institutional review board sponsorship. Go-to-market angle emphasizes biomarker-guided triage integration with multiplex cytokine profiling platforms already adopted in German university hospitals. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scale advantages separate profitable biologics producers from capital-constrained development-stage programs. Long-term viability favors sponsors with FDA accelerated approval experience and pre-negotiated pandemic preparedness stockpiling agreements. Acquisition target archetype: mid-cap cytokine inhibitor developers with Phase III assets and EMA adaptive pathway eligibility. Signal to watch: WHO pandemic protocol updates mandating specific immunomodulatory therapy categories for national strategic reserves.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-to-Therapeutic Integration | Cleveland Clinic and Mayo Clinic anchor closed-loop cytokine monitoring with automated ordering workflows. |
| EMA Adaptive Pathway Submission | Conditional approval based on surrogate biomarker endpoints reduces Phase III patient exposure requirements. |
| India Manufacturing Qualification | CDSCO oversight enables cost-competitive secondary supply sources reducing geographic concentration risk. |
| Outcome-Based Contracting Pilot | Texas and California integrated delivery networks test bundled critical care episode payments tied to ICU length-of-stay. |
| Pandemic Preparedness Stockpiling | METI protocols in Japan secure multi-year offtake commitments insulating revenue from routine demand fluctuation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned drug development executives at top-tier biopharmaceutical firms, regulatory affairs leads navigating FDA and EMA submission pathways, hospital formulary directors at academic medical centers, and payer access specialists designing outcome-based reimbursement frameworks. Secondary validation drew from FDA accelerated approval filings, EMA adaptive pathway decisions, ClinicalTrials.gov cytokine storm intervention listings, and hospital procurement database extracts. Bottom-up patient volume modeling and top-down revenue reconciliation anchored segment-level estimates.
Historical reference periods spanning pre-pandemic baseline through recent protocol standardization informed projection anchor points across the analysis window. Segmentation dimensions encompassed therapeutic modality, care setting acuity, administration route, patient population severity, and regional regulatory cluster typology. CAGRs derived from fitted growth curves adjusted for ICU infrastructure expansion rates and biomarker test adoption trajectories. Forecast inputs incorporated plasma supply elasticity coefficients and adaptive licensing approval probability weights.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-world cytokine level reporting infrastructure introduce uncertainty bands around adoption curve timing. Forecasts reflect documented assumptions about hospital IT upgrade cycles and immunology specialist fellowship graduation rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
Global Vaginal Rejuvenation Market