
 Superheater Market | 2026-2036
Superheater Market Size, Share, and Industry Trends Forecast 2026-2036
Superheater Market Outlook
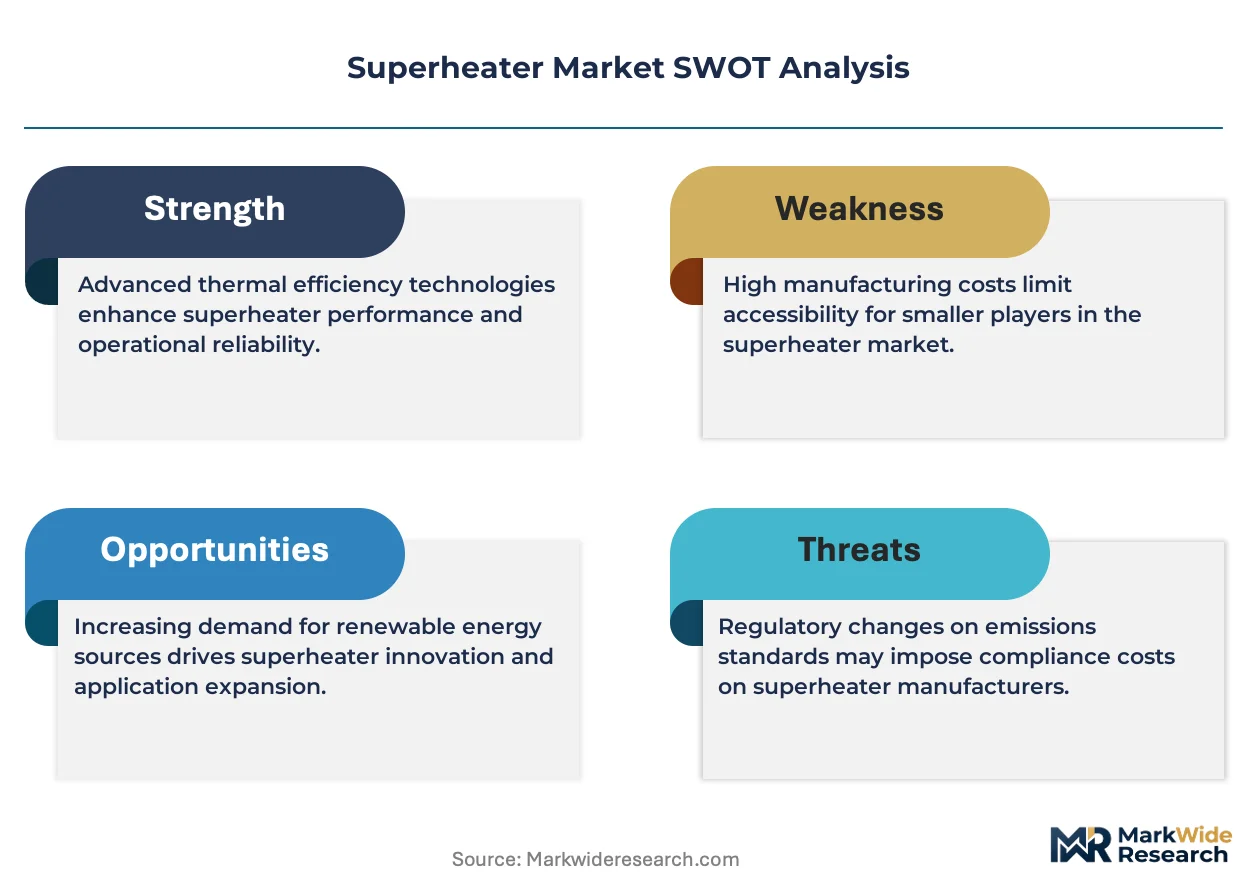
Advanced alloy composites are decoupling superheater performance from traditional carbon-steel cost curves. Sandvik leverages its metallurgical R&D pipeline to supply high-temperature resistant tubing for extreme-pressure environments. Alfa Laval anchors its position through marine and industrial heat transfer specialization across Nordic and Asian ports. Chromalox competes on electric superheater configurations for precision process heating in North American manufacturing.
A superheater is a heat exchange device that raises steam temperature above saturation levels using exhaust gases or dedicated firing systems, typically constructed from austenitic stainless steel or nickel-chrome alloys to withstand temperatures exceeding 540°C; its primary purpose is to enhance thermodynamic cycle efficiency in power plants and process steam systems. Steam-type superheaters occupy the largest installed base across coal and combined-cycle power generation, while high-temperature technology variants represent the fastest-expanding margin pool as utilities retrofit for efficiency gains. Modular technology configurations are gaining traction in chemical processing where flexible capacity scaling reduces capital commitment.
The US EPA enforces Maximum Achievable Control Technology standards that compel boiler operators toward higher-efficiency superheater retrofits, while China's MEE implements dual carbon goals that tighten thermal efficiency benchmarks for industrial steam systems. The EU F-Gas Regulation indirectly shapes superheater demand by restricting fluorinated gas use in alternative heating technologies. Stakeholders must monitor alloy supply chain concentration and regulatory efficiency mandates to time capacity investments.
Market Dynamics
Ultra-supercritical steam cycles are compressing thermal efficiency thresholds, forcing boiler operators to specify nickel-chrome alloys capable of sustained operation above 600°C. This metallurgical escalation is redrawing procurement priorities across power generation and process steam applications.
Growth Catalysts
- US EPA Clean Air Act enforcement:Maximum Achievable Control Technology standards compel utilities toward higher-temperature superheater retrofits that improve combustion efficiency and reduce stack emissions.
- China ultra-supercritical coal expansion:State-backed projects under MEE dual carbon goals drive procurement volumes for advanced superheater tubing in 1000MW+ units.
- Industrial boiler upgrade cycles:Chemical processing and refining sectors replace saturated steam systems with superheated configurations to capture thermodynamic efficiency gains.
Market Restraints
- Nickel alloy supply concentration:Specialty tubing production clusters in Nordic and East Asian metallurgical corridors, exposing procurement to concentrate supply risk.
- Capital intensity of supercritical retrofits:Boiler operators face extended payback periods when upgrading subcritical units to ultra-supercritical steam parameters.
- Fluorinated gas restrictions:EU F-Gas Regulation limits alternative heating technologies, indirectly constraining superheater substitution pathways in some industrial segments.
Strategic Opportunities
- Modular superheater configurations:Chemical processors adopt skid-mounted units that reduce capital commitment and enable flexible capacity scaling.
- Electric superheater penetration:Precision manufacturing segments in North America specify electric configurations for process heating applications with strict temperature control requirements.
- Marine heat transfer specialization:Port infrastructure upgrades across Nordic and Asian harbors create demand for compact superheater systems in auxiliary power and cargo heating.
Industry Challenges
- Welding technician scarcity:Austenitic stainless and nickel-chrome alloy joining requires certified specialists that utilities and EPC contractors struggle to source at scale.
- Legacy system integration friction:Superheater retrofits into existing boiler architectures demand custom engineering that extends project timelines and inflates commissioning costs.
- Alloy certification timelines:ASME and ISO material qualification protocols stretch 18-24 months, delaying deployment of next-generation high-temperature formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superheater Market |
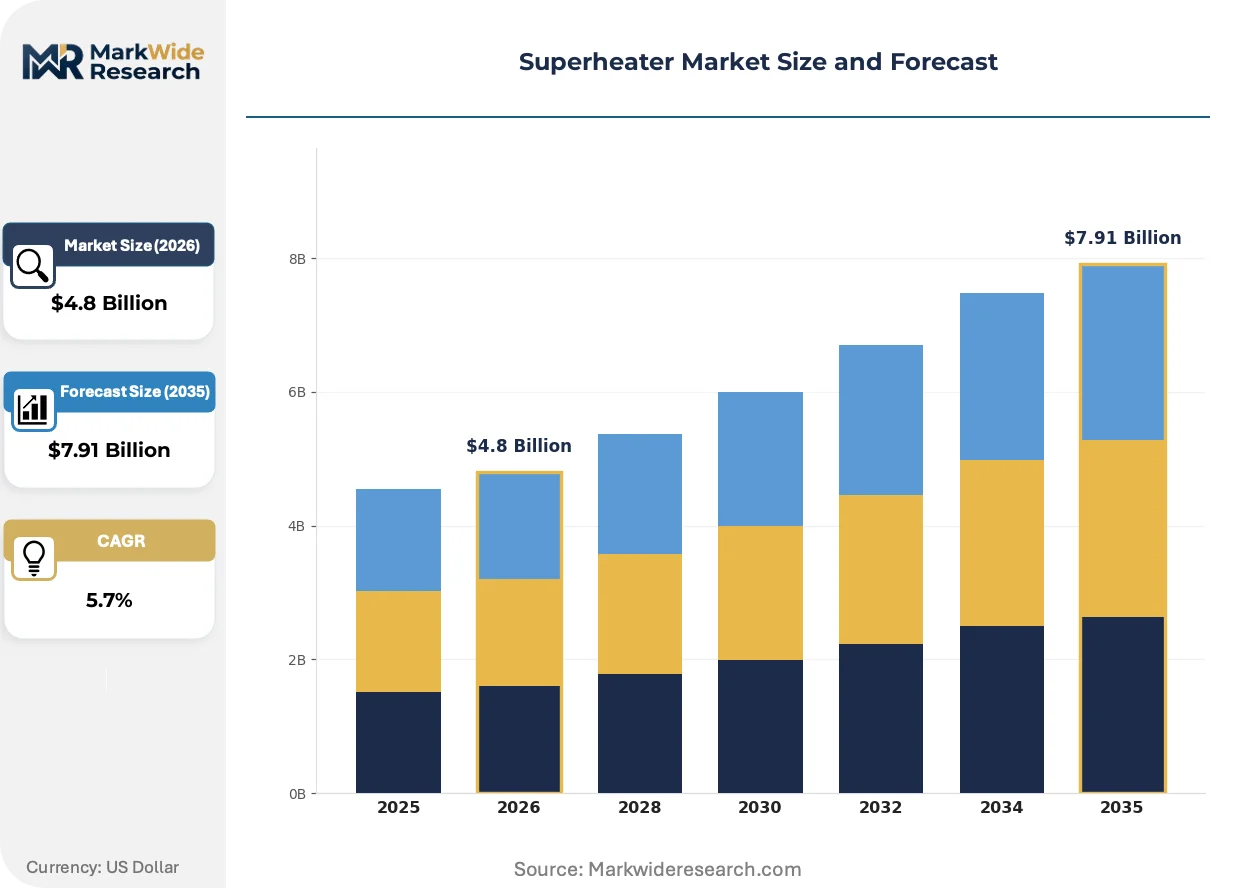
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Water, Steam, Fired, Non-Fired Application: Power Generation, Process Industries, Oil Refining, Chemical Processing End User: Utilities, Refiners, Petrochemical, Manufacturing Technology: Conventional, Advanced, Modular, High-Temperature |
| Companies Covered | National Boiler Service, Chromalox, Optimus Industries, Alfa Laval, Sussman Electric Boilers, Birwelco, Maarky Thermal Systems, Sandvik, KNM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superheater Market Strategic Shifts
Computational metallurgy and additive manufacturing are compressing alloy development cycles, enabling superheater designs that previously required decades of empirical testing. These capabilities are redrawing competitive boundaries between specialized tubing suppliers and integrated boiler OEMs.
Additive manufacturing of nickel-chrome superalloy components is automating the production of complex internal geometries that enhance heat transfer coefficients. Power utilities in China and the United States are piloting these configurations in ultra-supercritical test rigs. The technology is automating quality assurance protocols that previously required destructive testing of cast or wrought tubing samples.
REACH authorization requirements for nickel compounds are tightening material documentation obligations across European supply chains. Boiler operators must now trace alloy provenance through smelting and processing stages to demonstrate compliance. Industrial steam users in Germany and Poland face the steepest compliance gradients as they retrofit aging coal-fired units.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts. Independent service providers now compete for superheater inspection, tube replacement, and creep-life assessment work that boiler manufacturers previously captured. This pattern concentrates in North American independent power producers seeking to reduce fixed maintenance costs.
Superheater Market Segmentation
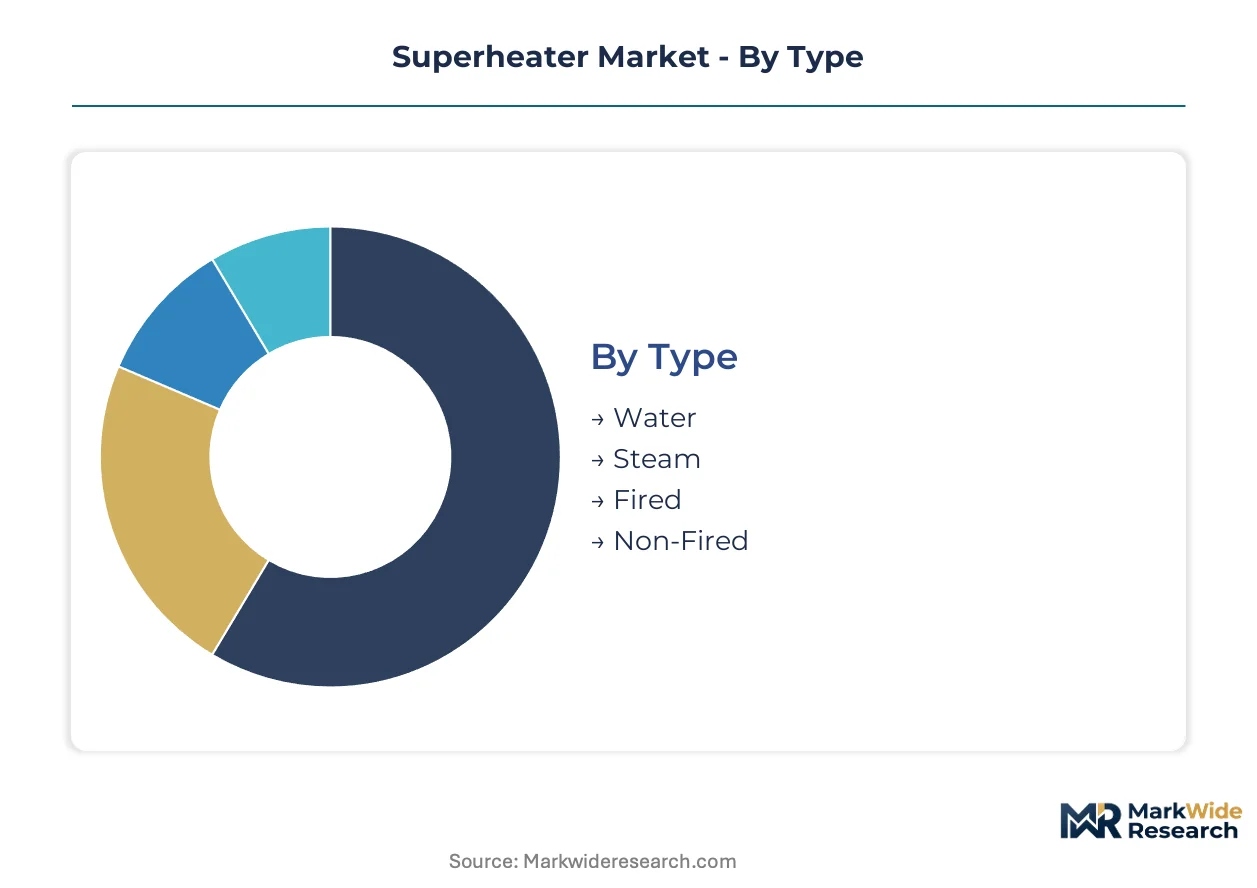
Superheater procurement patterns diverge sharply between bulk replacement cycles in mature power fleets and precision-engineered orders from process industries. Understanding these segment boundaries clarifies where alloy premiumization commands pricing power versus where standardized configurations dominate.
Type:
Steam-type superheaters anchor installed volume across coal and combined-cycle fleets, while high-temperature variants capture expanding margin pools as efficiency retrofits accelerate.
- Steam:Dominant configuration in thermal power plants, utilizing exhaust gas heat to elevate steam temperature above saturation. Demand concentrates in China's state-backed ultra-supercritical coal projects where 1000MW+ units require sustained operation above 540°C.
- Water:Specialized design for auxiliary heating and preheating applications in marine and industrial settings. Procurement clusters in Nordic and Asian port infrastructure upgrades where compact footprint requirements override thermal efficiency maximization.
- Fired:Dedicated combustion systems for process steam applications requiring precise temperature control beyond waste heat availability.
- Non-Fired:Heat recovery configurations leveraging existing thermal streams without supplemental firing, common in refinery and chemical integration.
Today's leader: Steam. Tomorrow's challenger: Fired.
Application:
Power generation absorbs the heaviest superheater tonnage, yet chemical processing offers the steepest expansion trajectory for modular and electric configurations.
- Power Generation:Coal, gas, and biomass plants deploy superheaters to boost Rankine cycle efficiency. US EPA Maximum Achievable Control Technology enforcement drives retrofits toward nickel-chrome alloys capable of 600°C+ operation.
- Chemical Processing:Flexible capacity scaling through skid-mounted units reduces capital commitment for batch operations. REACH authorization requirements for nickel compounds tighten material documentation obligations across European supply chains.
- Oil Refining:Hydrocracker and reformer units specify high-reliability superheaters for hydrogen and process steam generation.
- Process Industries:Pulp, paper, and food processing deploy saturated-to-superheated steam upgrades for energy recovery.
Power generation commands current procurement volumes; chemical processing climbs fastest on modular adoption.
End User:
Utilities prioritize metallurgical durability for baseload duty cycles, while petrochemical operators emphasize rapid startup flexibility.
- Utilities:Grid-scale operators specify superheaters for 30-year service life with minimal tube replacement. China's MEE dual carbon goals tighten thermal efficiency benchmarks for industrial steam systems under state-backed upgrade programs.
- Petrochemical:Olefin and aromatics producers require superheated steam for cracking and reforming reactions with tight temperature tolerances.
- Refiners:Fluid catalytic cracking and coking units integrate superheaters into complex heat recovery networks.
- Manufacturing:Discrete and process manufacturers adopt electric superheaters for precision heating in North American facilities.
Utilities hold the installed base; petrochemical buyers drive specification innovation.
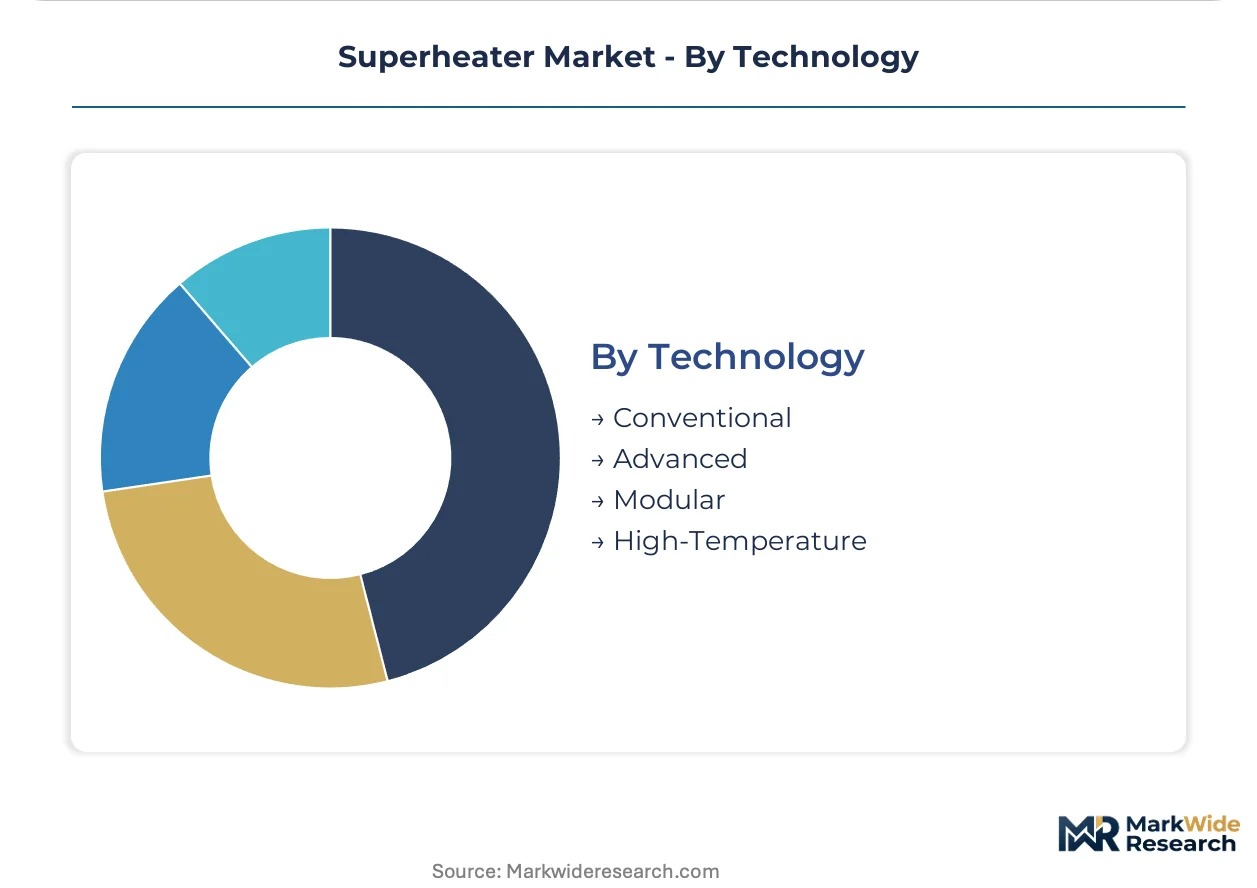
Technology:
Conventional designs saturate replacement demand, but advanced and modular architectures are capturing greenfield and retrofit share.
- High-Temperature:Nickel-chrome superalloy configurations enable ultra-supercritical steam parameters above 600°C. Additive manufacturing pilots in China and the United States automate production of complex internal geometries that enhance heat transfer coefficients.
- Modular:Skid-mounted systems reduce field construction duration and enable capacity scaling without full plant shutdown. Chemical processors in Germany and Poland adopt these configurations to navigate REACH compliance gradients during aging coal unit retrofits.
- Advanced:Computational metallurgy compresses alloy development cycles, accelerating deployment of next-generation formulations.
- Conventional:Established austenitic stainless steel designs serve cost-sensitive replacement cycles in mature boiler fleets.
Conventional technology defends replacement volume; high-temperature systems gain fastest on efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed ultra-supercritical coal projects dominate procurement volumes for advanced superheater tubing, while metallurgical supply corridors in Sweden and Japan constrain alloy availability across multiple industrial clusters.
China
State-owned utilities commission 1000MW+ ultra-supercritical units under MEE dual carbon goals, driving nickel-chrome alloy procurement at unprecedented scale. The Ministry of Ecology and Environment tightens thermal efficiency benchmarks annually, forcing boiler upgrades in industrial zones. Procurement concentrates in the Yangtze River Delta where state-backed fabricators integrate superheater production with captive alloy casting.
United States
Independent power producers retrofit aging coal fleets to meet EPA Maximum Achievable Control Technology standards, specifying high-temperature superheaters for 600°C operation. The Clean Air Act enforcement accelerates replacement cycles in the Ohio River Valley and Southeast manufacturing corridors. Houston and Pittsburgh anchor aftermarket service demand for creep-life assessment and tube replacement.
Germany
REACH authorization requirements for nickel compounds tighten material documentation obligations across boiler supply chains. The country's national environmental regulator enforces strict traceability from smelting through fabrication stages. Industrial steam users in the Ruhr region and Bavaria retrofit aging coal units while navigating compliance gradients for alloy provenance.
Japan
Utilities pilot additive-manufactured nickel-chrome components in ultra-supercritical test rigs under METI efficiency programs. The Ministry of Economy, Trade and Industry funds computational metallurgy initiatives that compress alloy development cycles. Nagoya and Osaka industrial clusters specialize in precision superheater fabrication for export markets across Southeast Asia.
India
Central Electricity Authority mandates supercritical technology adoption for new thermal capacity, expanding domestic superheater fabrication. State-owned NTPC and private utilities commission ultra-supercritical units in Gujarat and Maharashtra industrial corridors. Domestic alloy production lags demand, forcing reliance on Nordic and East Asian tubing imports.
Superheater Market Competitive Environment
Global majors compete with regional champions across metallurgical specialization and aftermarket service density. The vendor base stratifies into three tiers: integrated alloy suppliers with captive tubing production, specialized heat transfer fabricators serving marine and chemical segments, and electric heating specialists targeting precision manufacturing. Consolidation pressures concentrate among Nordic metallurgical houses and East Asian boiler OEMs seeking backward integration into alloy supply. Strategic moves center on capacity expansion in nickel-chrome tubing and technology licensing for additive manufacturing of complex superheater geometries.
Among Nordic metallurgical suppliers, Sandvik anchors the high-temperature alloy tier through captive R&D pipelines for extreme-pressure environments. Chromalox and Alfa Laval occupy distinct specialization vectors—electric configurations for North American precision heating and marine heat transfer systems across port infrastructure respectively. These three exemplify how competitive positioning diverges between material science depth, application-specific engineering, and geographic service density rather than converging on undifferentiated scale.
| Leading Market Players |
|---|
| National Boiler Service |
| Chromalox |
| Optimus Industries |
| Alfa Laval |
| Sussman Electric Boilers |
| Birwelco |
| Maarky Thermal Systems |
| Sandvik |
| KNM Group |
| Others |
Value Chain & Pricing Dynamics
LME nickel price volatility cascades through superheater supply chains into three distinct pricing tiers: premium nickel-chrome superalloy configurations for ultra-supercritical duty, mid-grade austenitic stainless systems for industrial retrofits, and standardized carbon-steel replacements for mature boiler fleets.
Pricing Analysis
Input-cost pass-through from nickel and chromium benchmarks drives contract-based long-term offtake structures that insulate utilities from spot volatility. Price differentiation separates ASME-certified superalloy tubing from standard-grade industrial configurations, with premium tiers commanding 40-60% markups based on metallurgical certification and creep-life guarantees. Cost compression in the mid-tier is intensifying as Chinese state-backed fabricators expand captive alloy casting capacity. Independent power producers in the Ohio River Valley exhibit the highest price sensitivity, while Chinese ultra-supercritical project developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Nordic metallurgical corridors for specialty nickel-chrome tubing, where Sandvik and a concentrated supplier base control high-temperature alloy formulation. Raw material dependencies center on Indonesian nickel ore, South African chromium, and Swedish specialty steel feedstocks. Tariff exposure on Chinese semi-finished tubing creates procurement friction for North American boiler OEMs. Distribution runs through integrated boiler fabricators in China, Germany, and Japan who bundle superheater systems with complete steam generator packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The superheater market represents a late-cycle quality story as utilities and chemical processors prioritize 30-year service life and 600°C+ operational thresholds over upfront capital minimization.
For Market Incumbents: Deploy metallurgical R&D pipelines to extend creep-life performance beyond current ASME certification limits. Backward integration into captive nickel-chrome casting capacity defends margin position against Chinese state-backed fabricators. After-sales service unbundling by independent providers threatens traditional OEM maintenance revenue; anchor customer relationships through predictive creep-life monitoring contracts. For New Entrants and Emerging Players: Digital-channel routes through marine equipment procurement platforms offer low-friction entry into Nordic and Asian port infrastructure upgrades. Modular skid-mounted configurations for chemical processing represent the most penetrable white-space segment, with German and Polish industrial clusters navigating REACH compliance gradients during aging unit retrofits. Target electric superheater specifications for North American precision manufacturing through direct specification with plant engineering teams. For Investors and Strategic Acquirers: Asymmetric upside sits with additive manufacturing specialists for nickel-chrome superalloy components. Long-term viability favors technology licensing plays over capital-intensive fabrication assets. Watch for inflection signals in ASME material qualification timelines, as 18-24 month certification protocols compress through computational metallurgy adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Chrome Casting | Captive alloy supply secures margin control against Nordic supply concentration. |
| Additive Manufacturing Technology Licensing | Computational metallurgy compresses ASME certification timelines for next-generation formulations. |
| Modular Skid-Mounted Configuration Expansion | Flexible capacity scaling captures chemical processing demand in Germany and Poland. |
| After-Sales Predictive Monitoring Contracts | Creep-life assessment services defend OEM revenue against independent service providers. |
| Electric Superheater Product Line Development | Precision temperature control specifications penetrate North American manufacturing segments. |
Study Parameters
Bottom-up power generation and chemical processing modeling reconciled against top-down metallurgical supply tracking forms the analytical core of this study. Primary interviews with utility planning officers, EPC contractor procurement leads, boiler OEM technical directors, and aftermarket service heads were validated against secondary sources including EPA MACT enforcement records, China MEE dual carbon policy filings, ECHA REACH authorization databases, and SEC 10-K disclosures from listed alloy suppliers. Trade data from customs authorities in China, Germany, Japan, and the United States provided volume triangulation for nickel-chrome tubing flows.
The input-output matrix framing connects superheater procurement volumes to underlying thermal capacity additions, retrofit cycles, and alloy substitution patterns across the projection horizon. Segmentation dimensions include steam type configuration, application sector, end-user archetype, and technology tier. CAGRs were derived from regression analysis of historical procurement against regulatory enforcement intensity and efficiency mandate trajectories. Forecast inputs incorporate EPA Clean Air Act implementation pacing, China MEE annual efficiency benchmark tightening, and EU REACH nickel compound authorization timelines.
The model assumes a particular technology adoption path; alternative pathways for additive-manufactured superalloy components would alter the outlook if ASME qualification protocols compress faster than baseline assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency, alloy supply concentration persistence, and welding technician scarcity severity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
North America Commercial Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Steam Boiler Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
US Industrial Boiler Market
Boilers
Electric Boiler Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
GCC Electric Water Heater Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
US Commercial Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Biomass Boiler Market