
 North America Commercial Boiler Market | 2026-2036
North America Commercial Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Boiler Market Analysis
The split between premium condensing systems and commodity non-condensing units is realigning procurement patterns across the North American installed base. Cleaver-Brooks leverages its vertical manufacturing footprint to control lead times on custom boiler packages. Miura America differentiates through compact modular steam systems that target space-constrained facilities in urban cores.
North America commercial boilers are pressurized vessels designed to generate hot water or steam for heating and process applications, typically operating at pressures up to 150 psi with combustion efficiencies ranging from eighty to ninety-eight percent depending on condensing architecture. Condensing product types now command the fastest expansion trajectory as building operators pursue fuel cost reductions, while natural gas fuel types retain dominant share due to pipeline density across the United States and Canadian provinces. Electric segments occupy niche positions in jurisdictions with low grid carbon intensity or strict emissions restrictions.
The U.S. Department of Energy enforces minimum efficiency standards under the Energy Policy and Conservation Act, while EPA regulations under the National Emission Standards for Hazardous Air Pollutants limit mercury and particulate outputs from oil-fired units. Canada's Natural Resources Canada administers the EnerGuide and ENERGY STAR certification programs that shape product eligibility for federal procurement. Stakeholders must monitor evolving federal efficiency rulemakings and provincial carbon pricing mechanisms to anticipate product mix shifts and compliance cost trajectories.
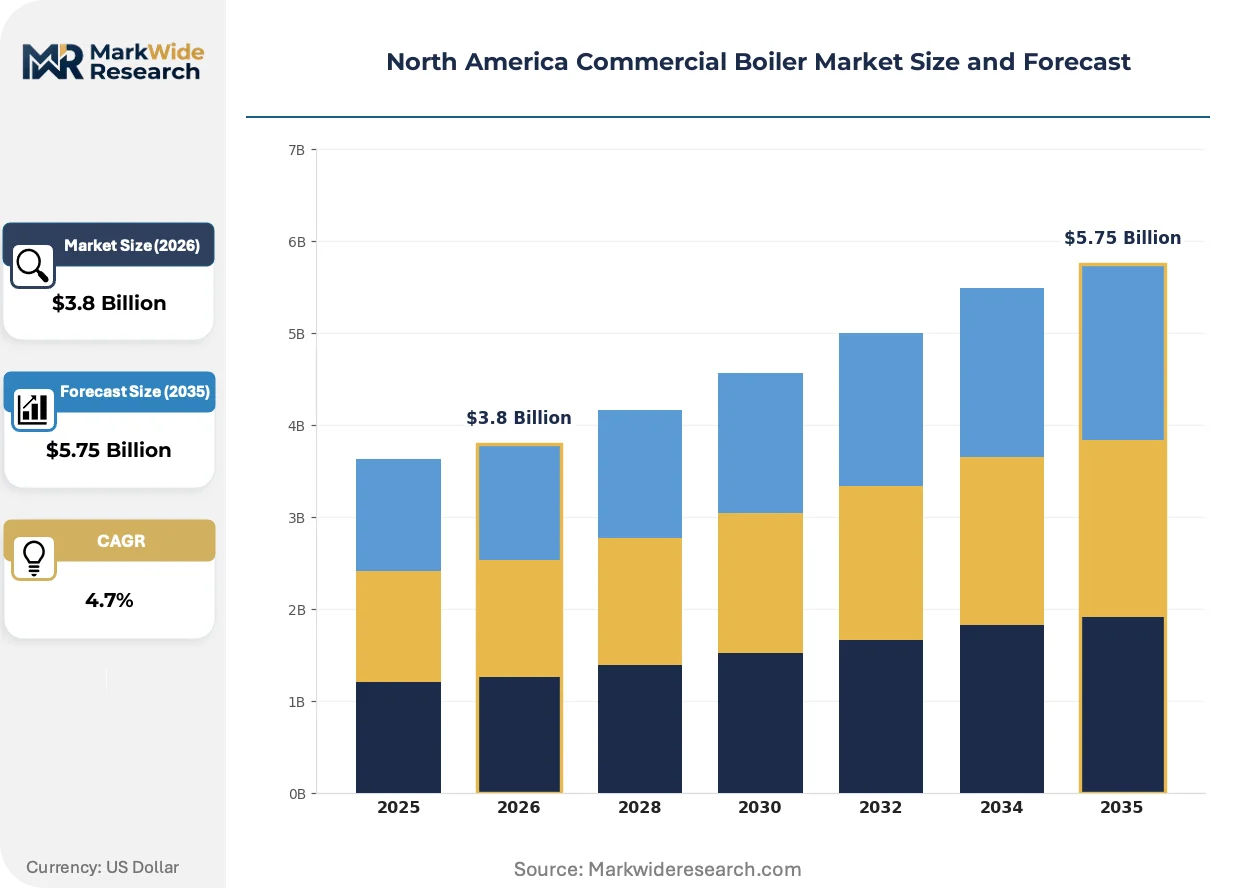
Market Dynamics
The U.S. Department of Energy's escalating efficiency mandates are compressing replacement cycles and forcing capital deployment toward condensing architectures across the installed base.
Growth Catalysts
- EPA NESHAP compliance deadlines:Oil-fired unit operators face mercury and particulate emission limits that accelerate boiler retirement timelines in the Northeast and Midwest.
- Hospitality sector capital programs:Hotel chains operating in cold-climate states are executing systematic boiler refresh programs to reduce operational energy expenditures.
- Condensing technology maturation:Stainless steel heat exchanger fabrication advances have extended service intervals and reduced maintenance burdens for building operators.
Market Restraints
- Copper and steel input volatility:Pressure vessel fabrication depends on commodity metal pricing that fluctuates with global scrap and ore markets.
- Certified technician concentration:Licensed boiler installation and service capacity clusters in legacy industrial corridors, constraining deployment speed in peripheral markets.
- Natural gas infrastructure lock-in:Pipeline density variations across Canadian provinces and U.S. rural counties limit fuel-switching flexibility for electrification advocates.
Strategic Opportunities
- Canadian provincial carbon pricing:British Columbia and Quebec carbon levy mechanisms create operating cost advantages for high-efficiency condensing deployments versus conventional units.
- Modular steam in urban cores:Space-constrained facilities in Manhattan, Toronto, and Chicago commercial districts present untapped demand for compact footprint systems.
- Remote monitoring convergence:IoT sensor integration with predictive maintenance platforms enables service contract bundling that captures recurring revenue streams.
Industry Challenges
- Controls integration complexity:Building automation system interoperability demands specialized commissioning expertise that outstrips current field technician supply.
- Legacy piping adaptation:Existing hydronic distribution infrastructure in pre-1980 commercial buildings requires costly retrofitting to realize condensing efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Boiler Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condensing, Non-Condensing, Electric, Steam Fuel Type: Natural Gas, Propane, Oil, Biomass End User: Hospitality, Education, Healthcare, Manufacturing Installation Method: Indoor, Outdoor, Modular, Custom |
| Companies Covered | Fulton Boiler Company, Bosch Thermotechnology, Cleaver-Brooks, Burnham Holdings, Weil-McLain, Babcock and Wilcox Enterprises, A.O. Smith Corporation, Miura America, Superior Boiler Works, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Boiler Market Emerging Trajectories
Digitalization of boiler operations is reconfiguring how manufacturers capture value, shifting revenue from equipment sales toward continuous service relationships. This transformation intersects with tightening efficiency regulations and evolving buyer procurement calculus.
Condensing boiler technology is expanding into mid-rise commercial and institutional buildings where non-condensing cast iron units previously dominated. School districts and municipal facilities across Minnesota, Wisconsin, and upstate New York are specifying these systems in capital plans. The technology is expanding into applications previously considered uneconomical due to return-water temperature constraints, compressing the addressable market for conventional atmospheric designs.
The U.S. Department of Energy's Energy Policy and Conservation Act rulemakings are mandating minimum annual fuel utilization efficiency thresholds that phase out non-condensing product lines. Manufacturers must redesign heat exchanger geometries and combustion control systems to maintain certification eligibility. The commercial segment faces the steepest compliance cost trajectories, prompting consolidation among smaller fabrication shops lacking R&D scale.
Performance-based service agreements are displacing traditional break-fix maintenance contracts in the hospitality and healthcare verticals. Facility managers at hospital systems in Pennsylvania and Ohio are purchasing thermal output guarantees rather than equipment ownership. This restructuring concentrates vendor risk and rewards predictive maintenance capabilities, favoring suppliers with established remote monitoring infrastructure over regional service-only contractors.
North America Commercial Boiler Market Segmentation
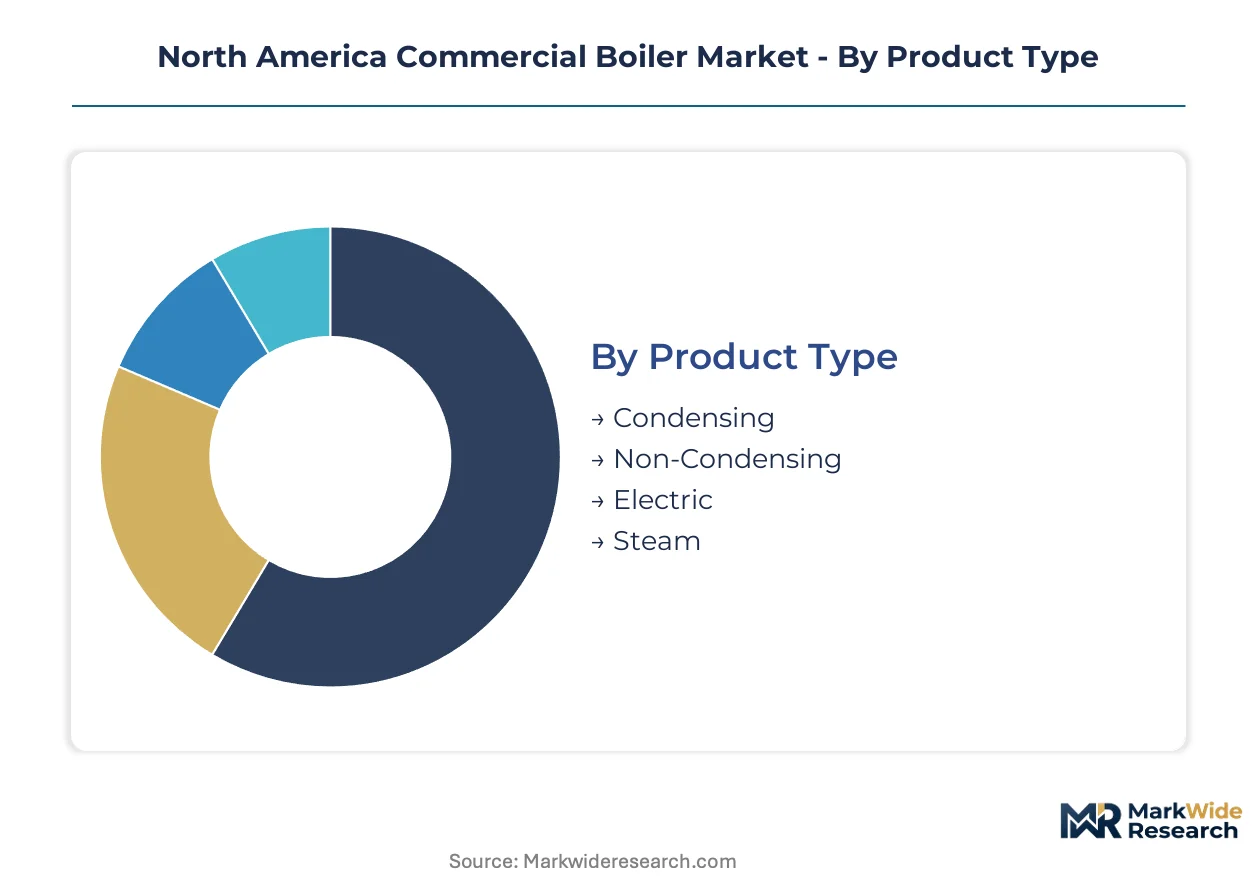
Commercial boiler procurement decisions hinge on thermal load profiles, fuel access infrastructure, and regulatory compliance timelines. Segmentation reveals where capital deployment concentrates and which technology architectures command premium positioning across the North American installed base.
Product Type:
Capital intensity varies sharply across product architectures, with condensing systems requiring stainless steel heat exchanger investments that non-condensing cast iron designs avoid.
- Condensing:Stainless steel or aluminum alloy heat exchangers recover latent heat from flue gases, achieving combustion efficiencies up to ninety-eight percent. Hotel chains in Minnesota and Wisconsin are specifying these systems in systematic refresh programs to reduce operational energy expenditures under tightening utility rate pressure.
- Non-Condensing:Cast iron sectional designs operate at higher return-water temperatures without corrosion risk, carrying lower upfront equipment costs but higher fuel consumption over service life. These units retain footholds in budget-constrained municipal facilities and legacy buildings where distribution piping cannot achieve condensing-mode temperatures.
- Electric:Resistance or electrode steam generators eliminate on-site combustion, finding niche deployment in jurisdictions with low grid carbon intensity or strict urban emissions restrictions.
- Steam:Pressurized vessel designs serve process applications in food processing and pharmaceutical manufacturing where saturated steam is required for sterilization or direct injection heating.
Non-condensing units absorb the bulk of installed capacity across the North American commercial base; condensing architectures are expanding most quickly as efficiency mandates compress replacement cycles.
Fuel Type:
Distribution infrastructure density and carbon pricing exposure create divergent operating economics across fuel categories.
- Natural Gas:Pipeline networks across the United States and Canadian provinces deliver lowest-cost thermal energy to commercial facilities, with metered service eliminating on-site fuel storage requirements. Urban cores in Toronto, Chicago, and Manhattan default to gas-fired systems where infrastructure exists.
- Propane:Liquefied petroleum gas serves rural counties and Canadian provinces beyond pipeline reach, requiring tank farm investments that elevate capital intensity for hospitality and healthcare facilities in peripheral markets.
- Oil:Residual and distillate fuel oils retain installed base concentration in the U.S. Northeast where legacy tank infrastructure persists, though EPA NESHAP mercury and particulate limits are accelerating retirement timelines.
- Biomass:Wood pellet and chip combustion systems occupy limited commercial deployment, constrained by fuel supply chain reliability and emissions permitting complexity in urban airsheds.
Natural gas commands dominant share across fuel categories; biomass is climbing the fastest as provincial carbon levy mechanisms in British Columbia and Quebec improve relative economics.
End User:
Operational uptime requirements and thermal load predictability shape procurement sophistication across vertical markets.
- Hospitality:Hotel and resort operators prioritize redundant capacity and rapid steam availability for laundry and kitchen operations, with franchise-level capital programs standardizing efficiency specifications across portfolios.
- Education:K-12 districts and university campuses face compressed summer installation windows, favoring modular replacement strategies that minimize classroom disruption during heating season transitions.
- Healthcare:Hospital systems purchase thermal output guarantees through performance-based service agreements rather than equipment ownership, concentrating vendor risk and rewarding predictive maintenance capabilities.
- Manufacturing:Process steam demands in food, pharmaceutical, and chemical plants require pressure vessel certifications and specialized combustion controls that exceed standard commercial specifications.
Hospitality and education absorb the bulk of replacement volume; healthcare is gaining share fastest as outcome-based contracting restructures procurement relationships.
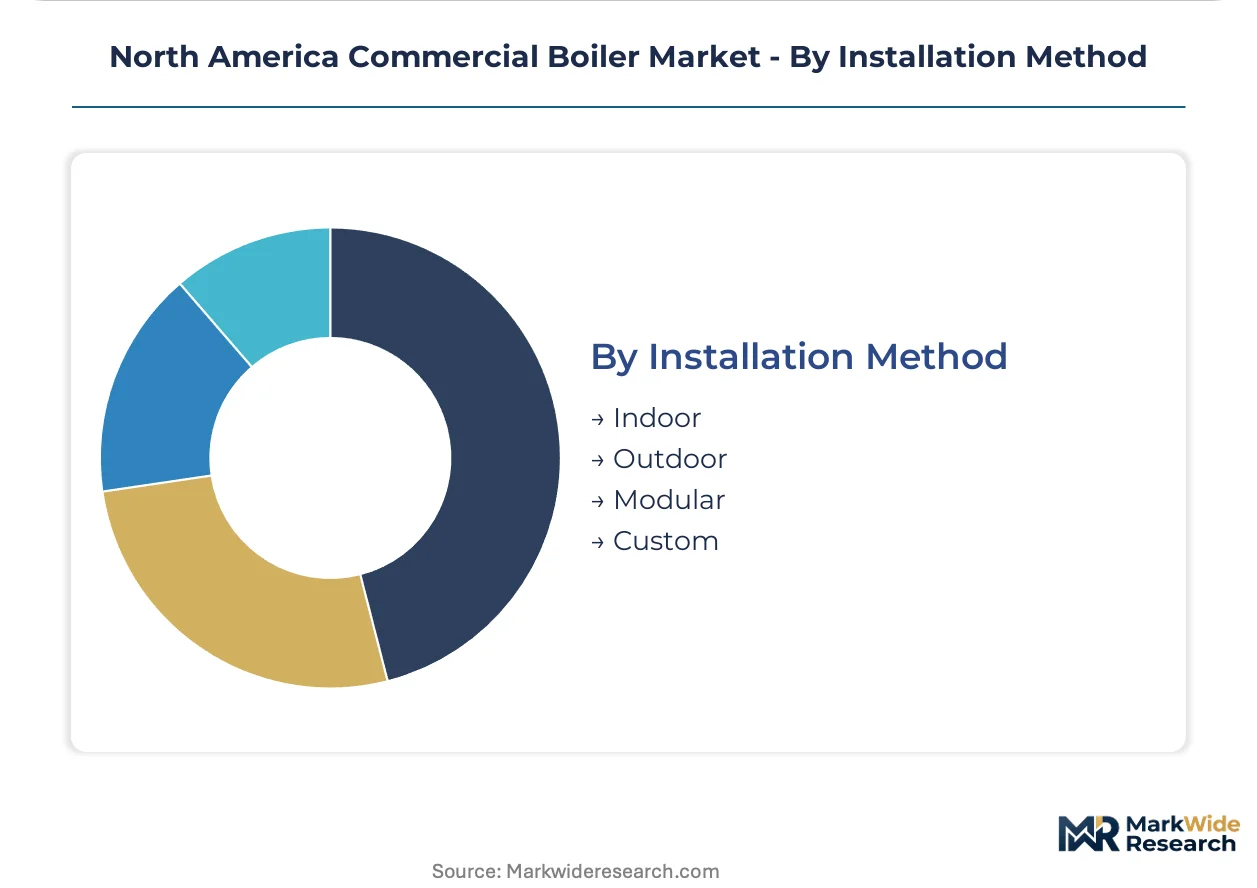
Installation Method:
Spatial constraints and regulatory jurisdiction determine whether systems deploy as standardized packages or engineered custom solutions.
- Indoor:Mechanical room installations dominate mid-rise commercial and institutional buildings, requiring combustion air supply and venting coordination with architectural enclosure systems.
- Outdoor:Weatherized enclosures serve facilities where interior mechanical space is unavailable or where noise and emissions separation is required by local ordinance.
- Modular:Compact footprint multiple-boiler arrays target space-constrained facilities in Manhattan, Toronto, and Chicago commercial districts where floor loading and ceiling clearance limit conventional equipment selection.
- Custom:Engineered-to-order packages address unique thermal load profiles, fuel combinations, or regulatory requirements that exceed standard product catalog capabilities.
Indoor installation retains dominant share across the installed base; modular configurations are expanding most quickly as urban density intensifies space competition in commercial cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American commercial boiler demand through its dense concentration of aging institutional buildings and harsh winter thermal loads that accelerate replacement cycles across the Midwest corridor.
United States
Hotel chains in Minnesota and Wisconsin execute systematic boiler refresh programs to reduce operational energy expenditures under tightening utility rate pressure. The U.S. Department of Energy enforces escalating efficiency mandates under the Energy Policy and Conservation Act that compress replacement cycles toward condensing architectures. Hospital systems in Pennsylvania and Ohio are purchasing thermal output guarantees through performance-based service agreements rather than equipment ownership.
Canada
British Columbia and Quebec carbon levy mechanisms create operating cost advantages for high-efficiency condensing deployments versus conventional units. Natural Resources Canada administers the EnerGuide and ENERGY STAR certification programs that shape product eligibility for federal procurement. Toronto commercial districts present untapped demand for compact footprint modular systems where floor loading and ceiling clearance limit conventional equipment selection.
Mexico
Industrial corridors in Nuevo León and the Bajío Region expand food processing capacity that requires pressurized steam for sterilization applications. The country's national energy regulator monitors pipeline infrastructure development that determines natural gas access for commercial thermal systems. Mexico City Metro facilities face space constraints that favor modular boiler arrays over conventional mechanical room installations.
North America Commercial Boiler Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the North America Commercial Boiler Market, with foundry-owning fabricators controlling heat exchanger supply chains while specification-engineering firms outsource vessel production. The vendor base clusters around three strategic archetypes: integrated manufacturers with captive foundry capacity, modular system specialists targeting urban density constraints, and regional service contractors bundling installation with maintenance contracts. Consolidation pressure intensifies as EPA NESHAP compliance costs and DOE efficiency rulemakings demand R&D scale that smaller fabrication shops cannot sustain. Dominant competitive moves include backward integration into stainless steel heat exchanger production and strategic partnerships with building automation system providers.
Among integrated manufacturers, Cleaver-Brooks and Fulton Boiler Company exemplify the capital-intensive archetype with vertical manufacturing footprints that control lead times on custom boiler packages. Miura America occupies a distinct position within the modular specialist tier, with its compact steam system designs targeting space-constrained facilities in Manhattan, Toronto, and Chicago commercial districts where conventional equipment selection faces physical constraints.
| Leading Market Players |
|---|
| Fulton Boiler Company |
| Bosch Thermotechnology |
| Cleaver-Brooks |
| Burnham Holdings |
| Weil-McLain |
| Babcock and Wilcox Enterprises |
| A.O. Smith Corporation |
| Miura America |
| Superior Boiler Works, Inc |
| Others |
Supply Flow & Price Mechanics
Captive foundry ownership among integrated manufacturers anchors both supply security and pricing power across the North American commercial boiler market. Cleaver-Brooks and Fulton Boiler Company control stainless steel heat exchanger fabrication in-house, insulating their custom package lead times from commodity metal volatility while commanding premium positioning against specification-engineering competitors who outsource vessel production.
Pricing Analysis
Thermal output guarantees anchor value-based pricing in the healthcare and hospitality verticals, where hospital systems in Pennsylvania and Ohio purchase uptime commitments rather than equipment ownership. Pricing stratifies across premium condensing systems with stainless steel heat exchangers, standard cast iron non-condensing units, and economy-grade atmospheric designs. Cost compression in the standard tier is intensifying because EPA NESHAP compliance deadlines force accelerated retirement of oil-fired legacy units. Municipal facilities and budget-constrained school districts exhibit the highest price sensitivity, while healthcare systems prioritize reliability metrics over capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers in Ohio, Pennsylvania, and Illinois anchor hub-and-spoke patterns that position finished boilers within one-day trucking distance of Midwest and Northeast demand clusters. Manufacturing concentration rests on domestic pressure vessel fabrication in Wisconsin, Minnesota, and Ontario, with stainless steel coil feedstock drawn from North American mills. Single-source vulnerability persists in specialized combustion control components sourced from German and Japanese automation suppliers. Distribution runs through manufacturer-direct field sales organizations for large custom projects, while standardized units move through HVAC wholesale distributors serving mechanical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Commercial Boiler Market sits in a technology-transition phase as condensing architectures displace non-condensing cast iron designs under DOE efficiency mandates. Stainless steel heat exchanger technology and IoT-enabled predictive maintenance platforms are compressing the addressable market for legacy atmospheric units.
For Market Incumbents: Lock in service contract bundling with remote monitoring infrastructure to capture recurring revenue streams as equipment sales margins tighten. Deepen backward integration into stainless steel heat exchanger production to control lead times against commodity input volatility. Consolidate regional fabrication shops lacking R&D scale to defend certification eligibility under escalating DOE rulemakings.
For New Entrants and Emerging Players: Enter via modular steam system deployments targeting space-constrained facilities in Manhattan, Toronto, and Chicago commercial districts where floor loading limits conventional equipment selection. Target the hospitality sector's franchise-level capital programs, which standardize efficiency specifications across portfolios and reward rapid installation capabilities. Pursue strategic partnerships with building automation system providers to overcome controls integration complexity that outstrips current field technician supply.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated manufacturers seeking captive foundry capacity and regional service footprints. Long-term viability favors vendors with established remote monitoring infrastructure and predictive maintenance platforms over pure equipment fabricators. Watch for inflection signals in Canadian provincial carbon pricing expansion, which would accelerate condensing deployment economics beyond British Columbia and Quebec.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Production | Cleaver-Brooks controls stainless steel fabrication lead times against commodity volatility. |
| IoT Sensor Integration with Predictive Maintenance | Remote monitoring platforms enable service contract bundling in healthcare verticals. |
| Modular System Development for Urban Cores | Miura America targets space-constrained facilities in Manhattan and Toronto districts. |
| Strategic Partnership with BAS Providers | Controls integration expertise addresses commissioning capacity constraints. |
| Consolidation of Regional Fabrication Shops | EPA NESHAP and DOE compliance costs demand R&D scale smaller players cannot sustain. |
Methodological Framework
Independent corroboration across facility maintenance directors, OEM procurement teams, aftermarket service heads, and mechanical engineering consultants underwrites the qualitative findings. Primary fieldwork combined structured interviews with plant engineers at hospital systems in Pennsylvania and Ohio, franchise operators in Minnesota and Wisconsin hospitality chains, and municipal facilities managers across upstate New York. Secondary validation drew from DOE efficiency rulemaking dockets, EPA NESHAP compliance records, Natural Resources Canada EnerGuide certifications, and SEC filings of publicly traded boiler manufacturers. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations across the analysis window.
Comparable-period anchoring linked forward projections to historical replacement cycle data from pre-1980 commercial building stock in the U.S. Northeast and Midwest. The modeling framework segmented demand by product architecture, fuel type, end-use vertical, and installation method, with thermal load profiles and regulatory compliance timelines as cross-cutting dimensions. CAGRs were derived from replacement rate assumptions tied to building age distributions and efficiency mandate phase-in schedules. Forecast inputs incorporated natural gas pipeline density variations, provincial carbon pricing exposure, and hospitality sector capital program announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA enforcement acceleration or copper and steel input price spikes. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that controls integration complexity and certified technician concentration constraints may compress deployment velocity below modeled trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Fire Tube Industrial Boiler Market
Boilers
Boiler Control Solutions Market
Boilers
Boiler Combustion Chamber Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Industrial Biomass Boiler Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Residential Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
Steam Boiler Market
Boilers
Watertube Boilers Market
Boilers
Power Plant Boiler Market
Boilers
Germany Combined Heat and Power Market
Boilers
US Commercial Boiler Market
Boilers
Combi Boiler Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Advanced Utility Boilers Market