
 Ballistic Shields Market | 2026-2036
Ballistic Shields Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistic Shields Market Analytics
NIJ Level IIIA ballistic certification is redrawing competitive boundaries for shield suppliers. Chase Tactical leverages domestic manufacturing capacity to sustain rapid fulfillment cycles for federal and municipal contracts. United Shield International anchors European demand through specialized composite engineering capabilities. Baker Ballistics differentiates via proprietary trauma-reduction backing systems that exceed baseline stopping-power requirements.
A ballistic shield is a hand-held or mounted protective panel engineered from layered aramid fibers, ultra-high-molecular-weight polyethylene, or ceramic-composite matrices to defeat specified projectile threats while maintaining maneuverability. Primary purpose centers on preserving operator survivability during armed engagements, warrant service, and active-threat interdiction. Tactical shields command premium positioning due to integrated viewport and weapon-mount configurations demanded by specialized response units. Composite materials represent the fastest-expanding material category as manufacturers balance weight reduction against multi-hit durability requirements. Riot shields retain volume dominance in municipal procurement driven by crowd-control mandates and lower per-unit acquisition costs.
The NIJ administers compliance testing that determines market access for United States suppliers, while the European Committee for Standardization (CEN) governs CE-marked ballistic protection through EN 1063 and EN 1522 frameworks. Military end-users increasingly require STANAG 4569-adjacent performance benchmarks that exceed traditional law enforcement specifications. Procurement officers and product engineers must monitor divergence between civilian certification cycles and emerging military threat-level requirements to align development roadmaps with funded demand streams.
Market Dynamics
The NIJ Level IIIA certification standard is compressing supplier margins while elevating technical barriers, forcing manufacturers to absorb testing costs or exit federal procurement channels entirely. This regulatory gatekeeping is redrawing competitive boundaries across the North American tactical equipment landscape.
Growth Catalysts
- Municipal Crowd-Control Mandates:Post-2020 operational reviews have driven sustained budget allocations for riot-control equipment across mid-sized US police departments. Procurement cycles now prioritize multi-threat protection over single-purpose designs.
- Ultra-High-Molecular-Weight Polyethylene Maturation:Domestic fiber spinning capacity has reduced raw material lead times from eighteen months to under eight weeks. Shield fabricators can now quote fixed-price multi-year contracts without commodity escalation clauses.
- STANAG 4569 Adjacent Benchmarking:Military end-users are cross-walking law enforcement NIJ protocols with NATO armor standards. This convergence opens dual-use certification pathways that were previously siloed by procurement category.
Market Restraints
- Aramid Fiber Supply Concentration:Three Asian chemical conglomerates control over seventy percent of para-aramid global output. Any disruption to their precursor chemical streams immediately propagates through shield backorder queues.
- NIJ Compliance Testing Backlog:The National Institute of Justice maintains a fourteen-month queue for Level IIIA certification retests. Product refresh cycles are artificially elongated regardless of engineering readiness.
- Hard Armor Plate Substitution:Plate carriers with standalone rifle-rated plates are capturing budget share from traditional shield programs in federal tactical units. Weight and mobility trade-offs increasingly favor torso-mounted systems.
Strategic Opportunities
- Canadian Municipal Consolidation:Ontario and Quebec are centralizing provincial procurement through shared-service organizations. Vendors with bilingual technical documentation and Health Canada pre-qualification gain first-mover positioning.
- Integrated Ballistic-Decontamination Systems:Fentanyl-exposure protocols are driving demand for shields with sealed viewport gaskets and surface-washable composite skins. This hybrid requirement sits outside existing certification frameworks.
- Texas School District Defensive Equipment Programs:State-level funding streams now explicitly cover ballistic barriers for campus resource officers. District-level purchasing authority bypasses traditional municipal procurement bottlenecks.
Industry Challenges
- Composite Lamination Technician Scarcity:The specialized skill set for void-free multi-layer pressing commands wage premiums exceeding forty percent above general manufacturing rates. Training pipelines require eighteen-month apprenticeships.
- Legacy Viewport Retrofit Integration:Existing shield fleets with outdated viewport designs cannot accommodate modern weapon-mount interfaces without structural weakening. Field modification voids manufacturer warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballistic Shields Market |
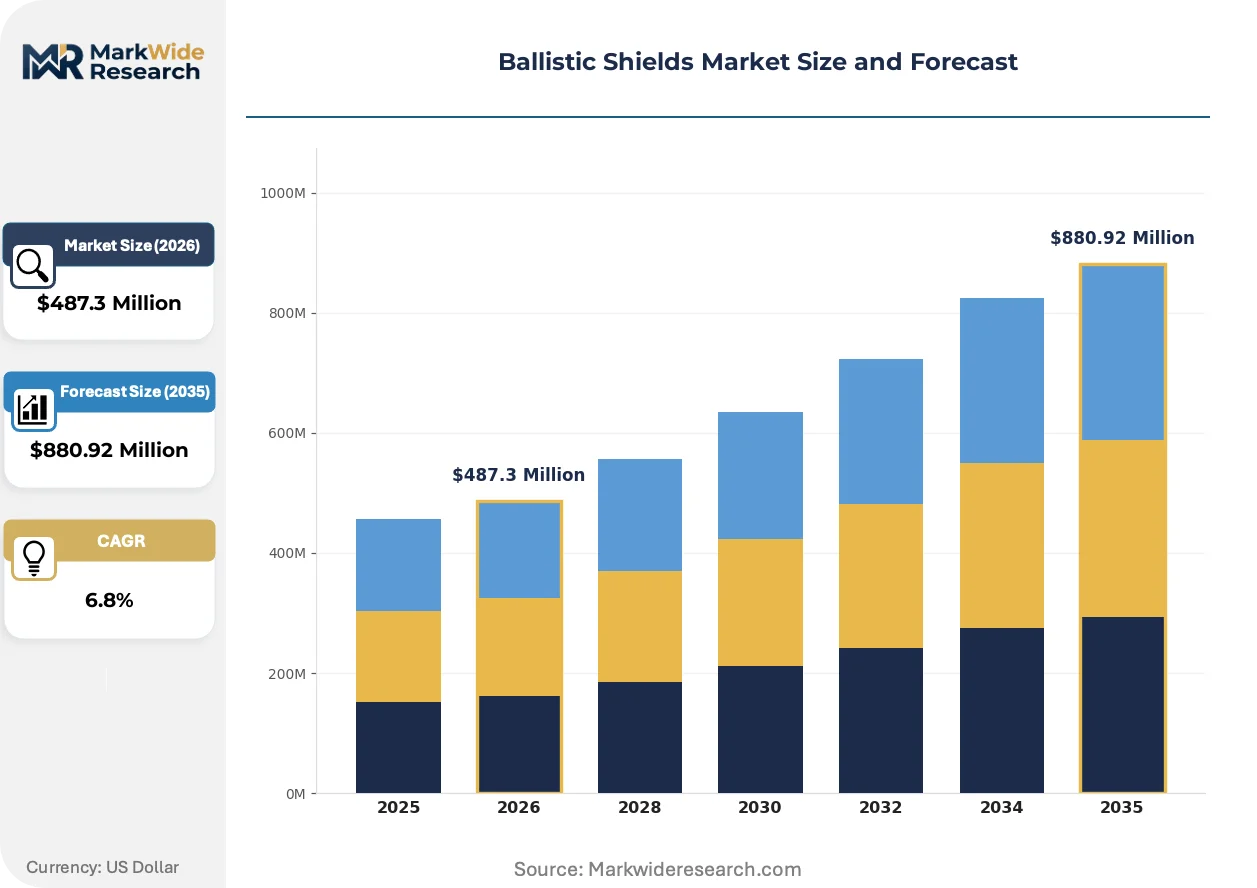
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Riot Shields, Tactical Shields, Bulletproof Barriers, Portable Shields Material: Polycarbonate, Aramid Fibers, Steel, Composite Materials End User: Law Enforcement, Military, Private Security, Civil Defense Application: Public Safety, Crowd Control, Tactical Operations, Emergency Response |
| Companies Covered | Chase Tactical, Advanced Technology Compliant Solutions (ATCS), The Cop Shield, DEW Engineering and Development, DMS Plastics, Securico, ATT Tactical, Baker Ballistics, United Shield International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistic Shields Market Evolving Landscape
Material science advances and procurement centralization are compressing product lifecycles while elevating performance benchmarks. Shield specifications now integrate multi-threat scenarios that exceed legacy single-purpose designs.
Non-Newtonian shear-thickening fluid layers are displacing traditional aramid-only backings in premium tactical shields. Specialized response units in federal agencies are specifying these systems for active-shooter interdiction despite thirty-percent weight penalties. The technology is displacing conventional composite stacks in contracts above fifty-unit volumes.
REACH Annex XVII restrictions on certain flame-retardant additives are forcing reformulation of shield edge-sealing compounds. European fabricators must validate alternative chemistries through extended aging protocols before CE marking. German tactical units are delaying fleet replacements until compliant formulations achieve equivalent seven-year service life.
Consolidated procurement through state-level cooperative purchasing agreements is compressing vendor counts in municipal channels. Texas and Florida have centralized riot-shield acquisitions through their respective department of public safety frameworks. Smaller fabricators without dedicated government contract specialists are exiting these bid pools entirely.
Ballistic Shields Market Segmentation
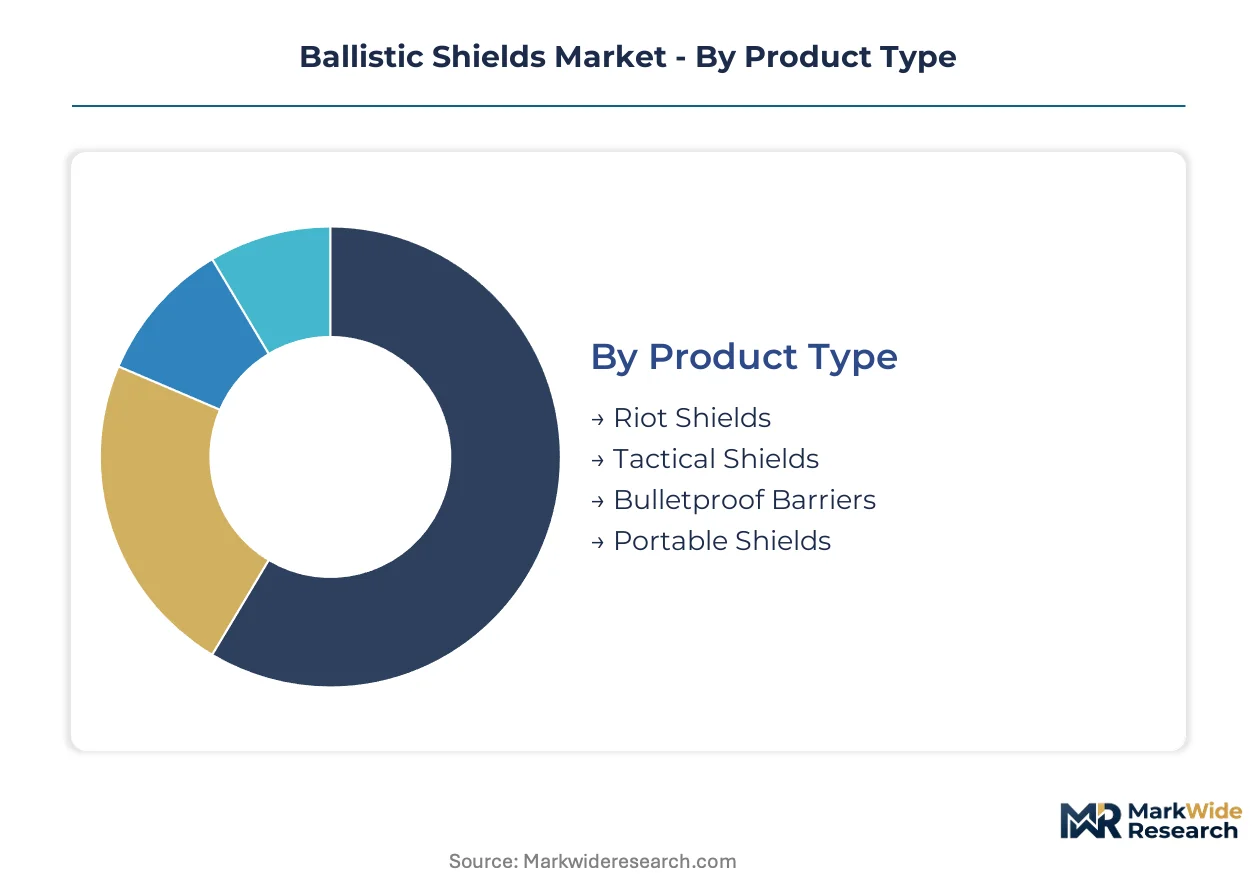
Procurement channels for ballistic shields diverge sharply by threat level and operational mandate. Municipal buyers prioritize cost-efficient volume acquisition, while federal tactical units demand certified performance with integrated accessory mounting.
Product Type:
Riot shields flow through municipal cooperative purchasing agreements, tactical shields through federal GSA schedules, barriers via institutional construction contracts, and portable units through private security distributors.
- Riot Shields:Transparent polycarbonate panels with reinforced edges, typically NIJ Level I rated or unrated for impact protection. US mid-sized police departments sustain volume demand through post-2020 crowd-control budget allocations, though procurement is consolidating under state-level frameworks in Texas and Florida.
- Tactical Shields:Composite or ceramic-faced systems with integrated viewports and weapon mounts, engineered to NIJ Level IIIA or STANAG 4569-adjacent specifications. Federal tactical units and specialized response teams drive specification escalation toward multi-hit durability and reduced weight profiles.
- Bulletproof Barriers:Fixed or mobile ballistic panels for facility hardening, typically Level III+ rifle-rated. Schools, courthouses, and corporate campuses in Texas deploy these through district-level purchasing authority bypassing traditional municipal bottlenecks.
- Portable Shields:Lightweight foldable or collapsible systems for rapid deployment. Private security contractors in Ontario and Quebec represent emerging demand as provincial procurement centralizes through shared-service organizations.
Riot shields dominate installed base. Tactical shields are where expansion concentrates.
Material:
Material selection maps directly to weight-stopping power trade-offs and certification tier, with cost per unit escalating from thermoplastics through ceramic composites.
- Polycarbonate:Thermoplastic sheets for riot-control and training applications, offering optical clarity at sub-five-pound weights. Municipal procurement cycles prioritize surface-washable skins for fentanyl-exposure protocols, creating hybrid requirements outside existing NIJ frameworks.
- Aramid Fibers:Para-aramid woven layers in Kevlar or Twaron formulations, the historical standard for Level IIIA soft armor. Supply concentration among three Asian chemical conglomerates creates immediate backorder vulnerability from precursor chemical disruptions.
- Steel:Rolled homogeneous armor plates for budget-conscious institutional barriers. German tactical units delay fleet replacements pending REACH Annex XVII compliance validation for edge-sealing compounds.
- Composite Materials:Ultra-high-molecular-weight polyethylene matrices with ceramic or metallic strike faces. Domestic fiber spinning capacity reduction from eighteen-month to eight-week lead times enables fixed-price multi-year contracting without commodity escalation clauses.
Aramid fibers anchor legacy fleet maintenance. Composite materials are climbing the fastest as manufacturers balance weight reduction against multi-hit durability.
End User:
End-user categories separate by procurement authority, threat environment, and certification stringency, with military specifications increasingly cross-walking civilian NIJ protocols.
- Law Enforcement:Federal, state, and municipal agencies representing the primary demand anchor. NIJ Level IIIA certification retest backlogs extending fourteen months artificially elongate product refresh cycles regardless of engineering readiness.
- Military:Domestic and allied defense forces requiring STANAG 4569-adjacent performance benchmarks. NATO armor standard convergence opens dual-use certification pathways previously siloed by procurement category.
- Private Security:Corporate protection details and contracted facility security. Canadian provincial consolidation creates first-mover positioning for vendors with bilingual technical documentation and Health Canada pre-qualification.
- Civil Defense:Emergency management agencies and disaster response coordinators. Texas school district defensive equipment programs now explicitly fund ballistic barriers for campus resource officers through state-level streams.
Law enforcement commands volume leadership. Military specifications are where technical barriers are concentrating.
Application:
Application segmentation reflects operational tempo and multi-threat scenario planning, with procurement officers prioritizing protection breadth over single-purpose designs.
- Public Safety:Routine patrol and community policing operations. Riot shields retain dominance through lower per-unit acquisition costs and optical clarity requirements for de-escalation visibility.
- Crowd Control:Protest management and civil disturbance response. Post-2020 operational reviews sustain budget allocations across mid-sized US departments for multi-threat protection systems.
- Tactical Operations:High-risk warrant service, hostage rescue, and active-threat interdiction. Non-Newtonian shear-thickening fluid layers displace conventional aramid-only backings in premium contracts above fifty-unit volumes despite thirty-percent weight penalties.
- Emergency Response:Medical evacuation and disaster site security. Fentanyl-exposure protocols drive demand for sealed viewport gaskets and surface-washable composite skins in hybrid configurations.
Crowd control maintains fleet scale. Tactical operations represent the steepest expansion trajectory as specialized response units escalate performance benchmarks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal tactical units and municipal police departments anchor procurement concentration across North America and Western Europe. Certification backlogs and raw material supply chains determine regional competitive positioning.
United States
NIJ Level IIIA certification queues extending fourteen months constrain product refresh cycles for federal tactical units. The National Institute of Justice administers compliance testing that gates market access for domestic suppliers. Chase Tactical and Baker Ballistics concentrate manufacturing capacity in the Southeast to sustain rapid fulfillment for federal and municipal contracts.
Canada
Ontario and Quebec are centralizing provincial procurement through shared-service organizations, creating first-mover positioning for pre-qualified vendors. Health Canada pre-qualification requirements govern ballistic protection equipment for law enforcement agencies. DEW Engineering and Development anchors Canadian demand through specialized composite engineering capabilities in the Ottawa corridor.
Germany
REACH Annex XVII restrictions on flame-retardant additives delay fleet replacements pending compliant formulation validation. The European Committee for Standardization governs CE-marked protection through EN 1063 and EN 1522 frameworks. Bavarian tactical units are extending aging protocols to seven-year service life equivalents before authorizing new acquisitions.
United Kingdom
United Shield International leverages specialized composite engineering to anchor European demand from its British manufacturing base. CEN frameworks for EN 1063 certification shape procurement requirements for domestic law enforcement. The West Midlands cluster concentrates shield fabrication expertise serving NATO-aligned military specifications.
Australia
Private security contractors and civil defense agencies drive incremental demand for portable shield systems. The Therapeutic Goods Administration does not regulate ballistic equipment, leaving procurement to state-level police services. New South Wales and Victoria maintain separate certification preferences that fragment vendor qualification requirements.
Ballistic Shields Market Competitive Landscape
Player mix skews toward mid-cap specialists with captive composite lamination capabilities and tier-one defense contractors with STANAG-adjacent certification portfolios. The vendor base separates into three strategic archetypes: domestic rapid-fulfillment fabricators, European composite-engineering specialists, and trauma-reduction technology developers. M&A activity concentrates on acquiring NIJ-certified product lines to bypass testing backlogs, while capacity expansion targets UHMWPE fiber spinning integration to compress raw material lead times.
Among North American fabricators, Chase Tactical exemplifies the domestic rapid-fulfillment archetype through its positioning for federal contract cycles. Baker Ballistics occupies a specialist tier focused on proprietary backing systems that exceed baseline stopping-power requirements. United Shield International anchors the European composite-engineering vector from its United Kingdom base, representing the CEN-certification pathway for NATO-aligned demand. These three named entities collectively illustrate the geographic and technical segmentation that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Chase Tactical |
| Advanced Technology Compliant Solutions (ATCS) |
| The Cop Shield |
| DEW Engineering and Development |
| DMS Plastics |
| Securico |
| ATT Tactical |
| Baker Ballistics |
| United Shield International |
| Others |
Value Network & Pricing Analysis
Eighteen-month aramid fiber lead times collapsing to under eight weeks have redistributed pricing power from raw material suppliers to shield fabricators capable of quoting fixed-price multi-year municipal contracts without commodity escalation clauses. This compression of input cost volatility is reshaping competitive positioning across the North American tactical equipment landscape.
Pricing Analysis
Cost-plus contracts with UHMWPE fiber indexation dominate federal procurement channels, though municipal cooperative purchasing agreements increasingly favor fixed-price arrangements. Price differentiation centers on NIJ certification tier and integrated accessory mounting capability, with tactical shields commanding substantial premiums over riot-control configurations. Pricing pressure stems from plate carrier substitution in federal tactical units as torso-mounted systems capture budget share. Municipal police departments exhibit highest price sensitivity, while specialized federal response units prioritize performance over per-unit cost.
Supply Chain Analysis
Inbound logistics costs from Asian chemical conglomerates through West Coast ports remain vulnerable to container availability fluctuations on transpacific trade lanes. Raw material supply concentrates in China, Japan, and South Korea for para-aramid precursors, while domestic UHMWPE fiber spinning capacity expands in the southeastern United States. The supply chain draws from ceramic strike face suppliers in Germany and transparent polycarbonate sheet producers in North America. Single-source vulnerability in para-aramid precursor chemicals propagates immediately through shield backorder queues. Distribution runs through federal GSA schedules, state cooperative purchasing agreements, and private security distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent shield manufacturers face sustained substitution pressure from plate carrier systems with standalone rifle-rated plates, requiring defensive repositioning around integrated capability bundles that torso-mounted alternatives cannot replicate.
For Market Incumbents: Consolidate manufacturing footprint around captive UHMWPE fiber spinning capacity to compress raw material lead times and sustain fixed-price contract competitiveness. Deepen backward integration into composite lamination technician training pipelines to alleviate wage premium pressures exceeding forty percent above general manufacturing rates. Defend against plate carrier substitution by accelerating integrated ballistic-decontamination system development for fentanyl-exposure protocols.
For New Entrants and Emerging Players: Anchor in Canadian provincial consolidation through Health Canada pre-qualification and bilingual technical documentation capabilities, where Ontario and Quebec shared-service organizations create first-mover positioning. Target Texas school district defensive equipment programs leveraging state-level funding streams that bypass traditional municipal procurement bottlenecks. Pursue portable shield white space in private security contractor channels across Ontario and Quebec.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-anchored consolidation play because NIJ Level IIIA testing backlogs extending fourteen months create durable barriers to rapid competitive entry. Acquisition candidates with existing certified product lines bypass artificial elongation of market access timelines. Watch STANAG 4569-adjacent military specification convergence as inflection signal for dual-use certification pathway expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Certification Investment | Fourteen-month testing queues create defensive moats for pre-qualified suppliers in federal procurement channels. |
| UHMWPE Fiber Spinning Integration | Domestic capacity expansion enables fixed-price multi-year contracting without commodity escalation exposure. |
| Ballistic-Decontamination System Development | Fentanyl-exposure protocols drive hybrid requirements outside existing NIJ frameworks for first movers. |
| Canadian Provincial Pre-Qualification | Health Canada certification and bilingual documentation secure positioning in Ontario and Quebec consolidation. |
| Composite Lamination Technician Apprenticeship | Eighteen-month training pipelines address wage premiums exceeding forty percent above general manufacturing rates. |
Research Methodology
Desk research of NIJ compliance testing records, federal procurement databases, and composite materials trade publications preceded structured interviews with shield product engineers, municipal procurement officers, federal tactical equipment specialists, and composite lamination technicians. Secondary validation drew from customs filings tracking para-aramid and UHMWPE fiber imports, SEC disclosures of defense contractors with shield divisions, and state cooperative purchasing agreement awards. Bottom-up unit demand estimates triangulated against top-down budget allocation analysis across federal, state, and municipal law enforcement agencies.
Variance decomposition across product type, material composition, end-user category, and application scenario anchored the analytical framework over the projection horizon. CAGRs were derived from segmented unit demand projections calibrated to procurement cycle timing and certification backlog constraints. Industry-specific forecast inputs incorporated NIJ testing queue dynamics, UHMWPE fiber spinning capacity expansion timelines, and STANAG 4569 specification convergence patterns.
Underlying assumptions cover sustained municipal crowd-control budget allocations, stable para-aramid precursor chemical supply from Asian conglomerates, and gradual STANAG-NIJ specification convergence, with deviation risk concentrated in plate carrier substitution acceleration or REACH Annex XVII regulatory expansion beyond European boundaries. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Instrumentation Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market