
 Australia Emergency Lighting Market | 2026-2036
Australia Emergency Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Emergency Lighting Market Outlook
Commercial property managers is collapsing into industrial and institutional buyers as warehouse construction and hospital expansion outpace office development across Australia. Eaton Industries Pty Ltd leverages its vertical integration into battery and control systems to secure large-scale infrastructure contracts. Clevertronics Pty Ltd specializes in photoluminescent exit signage that reduces long-term maintenance burdens for facility operators. WBS Technology ABN competes through aggressive channel control in the electrical wholesaler network, locking out smaller distributors in Queensland and Western Australia.
Emergency lighting comprises self-powered luminaires, exit signs, and central battery systems engineered to deliver minimum illuminance levels measured in lux during mains power failure, with LED sources now dominating due to their lower wattage draw and extended backup duration. The technology dimension splits between self-contained units that dominate retrofit installations and central battery architectures that anchor new commercial builds where wiring economies justify capital investment. LED product types command the widest application scope across installation categories, while fluorescent retains residual share in legacy institutional buildings where full replacement cycles lag.
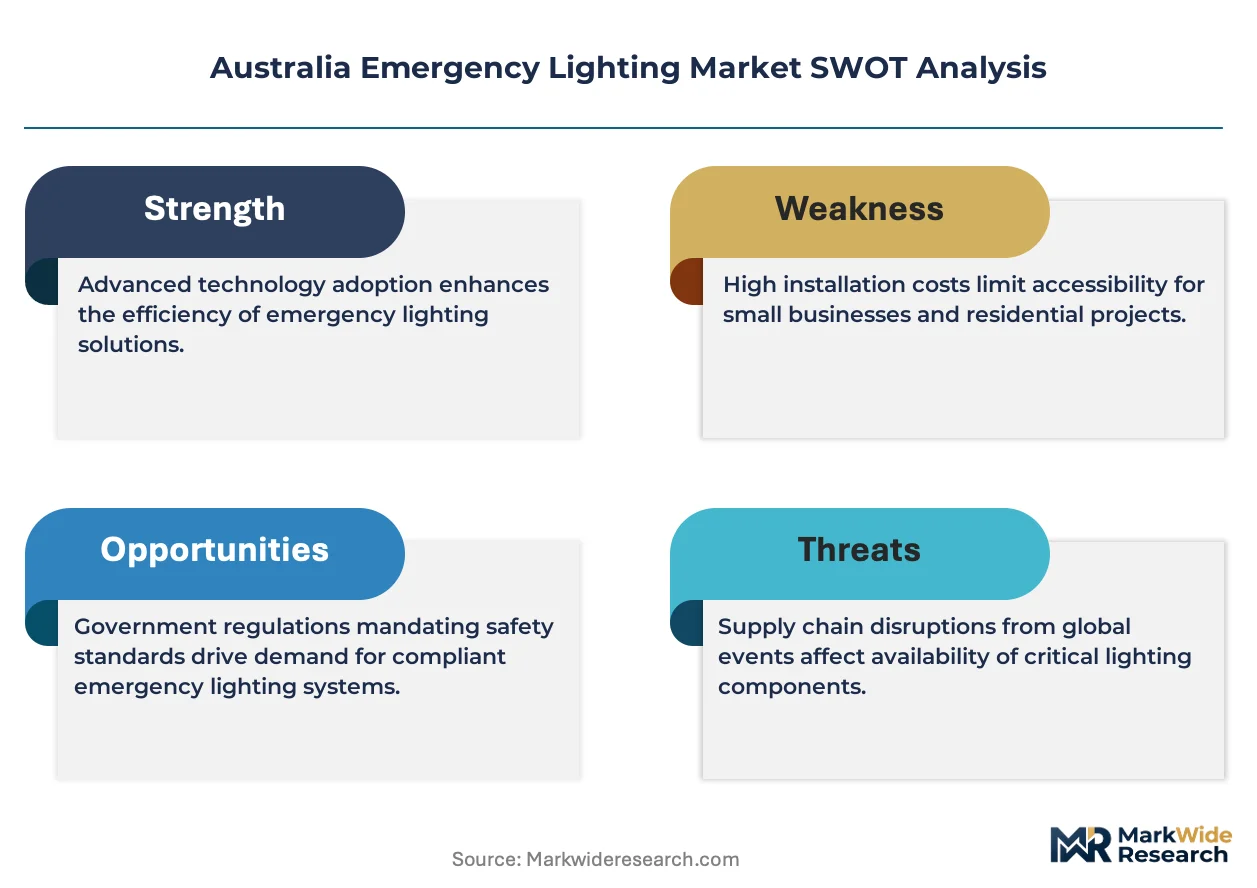
TGA building product certifications intersect with AS 2293 emergency escape lighting requirements to create a dual-compliance burden that filters out uncertified imports. The National Construction Code triggers mandatory emergency lighting provisions in all Class 5-9 buildings, directly shaping specification behavior among electrical consultants. State-level electrical safety regulators in Victoria and New South Wales enforce periodic testing intervals that sustain recurring demand for replacement components. Stakeholders must monitor potential harmonization between AS 2293 and evolving IEC standards that could force design modifications for export-oriented manufacturers.
Market Dynamics
The National Construction Code's 2022 amendments tightened luminance compliance thresholds, forcing Class 5-9 building owners into accelerated replacement cycles and compressing product lifecycles across Australia's eastern seaboard.
Growth Catalysts
- AS 2293.1 luminance mandates:Emergency escape lighting requirements now demand higher maintained illuminance levels, compelling retrofit investments in aging commercial stock across New South Wales and Victoria.
- Healthcare facility expansion:Hospital construction pipelines in Melbourne and Sydney are procuring self-contained LED systems for operating theatres and patient evacuation routes.
- Photoluminescent exit signage:Maintenance-free photoluminescent materials are displacing electrically powered exit signs in institutional buildings where lifecycle cost dominates specification criteria.
Market Restraints
- Lithium battery input volatility:Self-contained luminaire manufacturers face margin pressure from raw material cost swings in battery cell supply chains concentrated in East Asian production hubs.
- Central battery system concentration:New commercial build specifications favor centralized architectures that concentrate procurement power with electrical engineering consultants, squeezing smaller installation contractors.
- Fluorescent legacy overhang:Residual fluorescent installations in institutional buildings delay full LED conversion cycles where capital replacement budgets remain constrained.
Strategic Opportunities
- Western Australia warehouse construction:Industrial logistics expansion around Perth creates demand for high-bay emergency luminaires with extended backup duration specifications.
- Smart building convergence:Integration of emergency lighting with building management systems and IoT sensor networks opens specification channels with facilities management platforms.
- TGA building product certification:Dual compliance burden with therapeutic goods administration requirements filters import competition and protects domestic manufacturer margins.
Industry Challenges
- Electrical contractor skill scarcity:Installation of central battery architectures requires specialized commissioning expertise that remains concentrated among licensed contractors in Sydney and Melbourne metropolitan markets.
- AS 2293 periodic testing compliance:Six-monthly and annual testing intervals mandated by state electrical safety regulators generate recurring service revenue but strain contractor capacity during peak construction seasons.
- Legacy system integration friction:Retrofit LED installations must interface with existing fire detection and alarm infrastructure, complicating specification and extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Emergency Lighting Market |
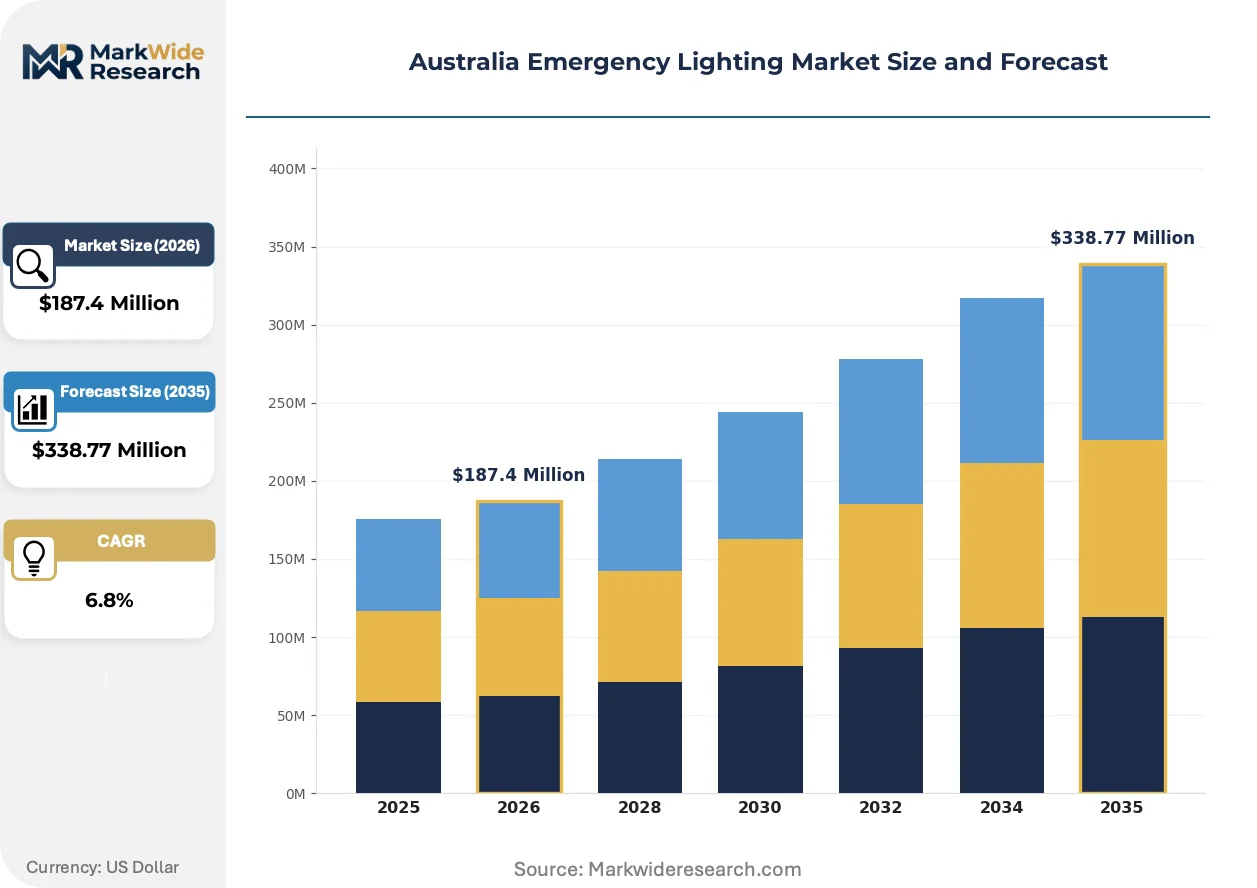
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, HID, Incandescent Installation Type: Ceiling Mount, Wall Mount, Portable, Surface Mount End User: Commercial, Industrial, Residential, Institutional Technology: Self-Contained, Central Battery, Standalone, Hybrid |
| Companies Covered | Eaton Industries Pty Ltd, WBS Technology ABN, Clevertronics Pty Ltd, BARDIC, E&E Lighting Australia, ABB Ltd, Haneco Lighting Australia Pty Ltd, Famco Lighting Pty Ltd, Legrand Australia Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Emergency Lighting Market Strategic Shifts
Emergency lighting technology is fragmenting along installation-type lines, with divergent product architectures serving retrofit versus new-build market segments. Three forces are reshaping competitive positioning and procurement patterns.
Self-contained LED emergency luminaires is bifurcating the technology landscape between battery-integrated retrofit units and centrally powered new-build systems. Facility managers in Queensland's aging commercial stock favor plug-and-replace self-contained units that minimize electrical contractor hours. This technology split is compressing central battery system penetration in renovation projects while reinforcing wired architecture dominance in greenfield developments.
TGA building product certification intersects with AS 2293 standards to create a dual-compliance burden that filters uncertified imports from Australian distribution channels. Electrical consultants now specify certified product families exclusively, eliminating price-competitive Asian manufacturers from tender shortlists. Healthcare and aged-care verticals face the strictest enforcement, with state electrical safety regulators in Victoria conducting unannounced installation audits.
Electrical wholesaler channel consolidation is compressing distributor margins and locking out smaller independent suppliers from specification influence. WBS Technology ABN's exclusive arrangements with national wholesaler networks in Queensland and Western Australia demonstrate how channel control determines market access. This concentration shifts procurement leverage toward large-scale contractors capable of volume commitments, marginalizing regional installation specialists in secondary markets.
Australia Emergency Lighting Market Segmentation
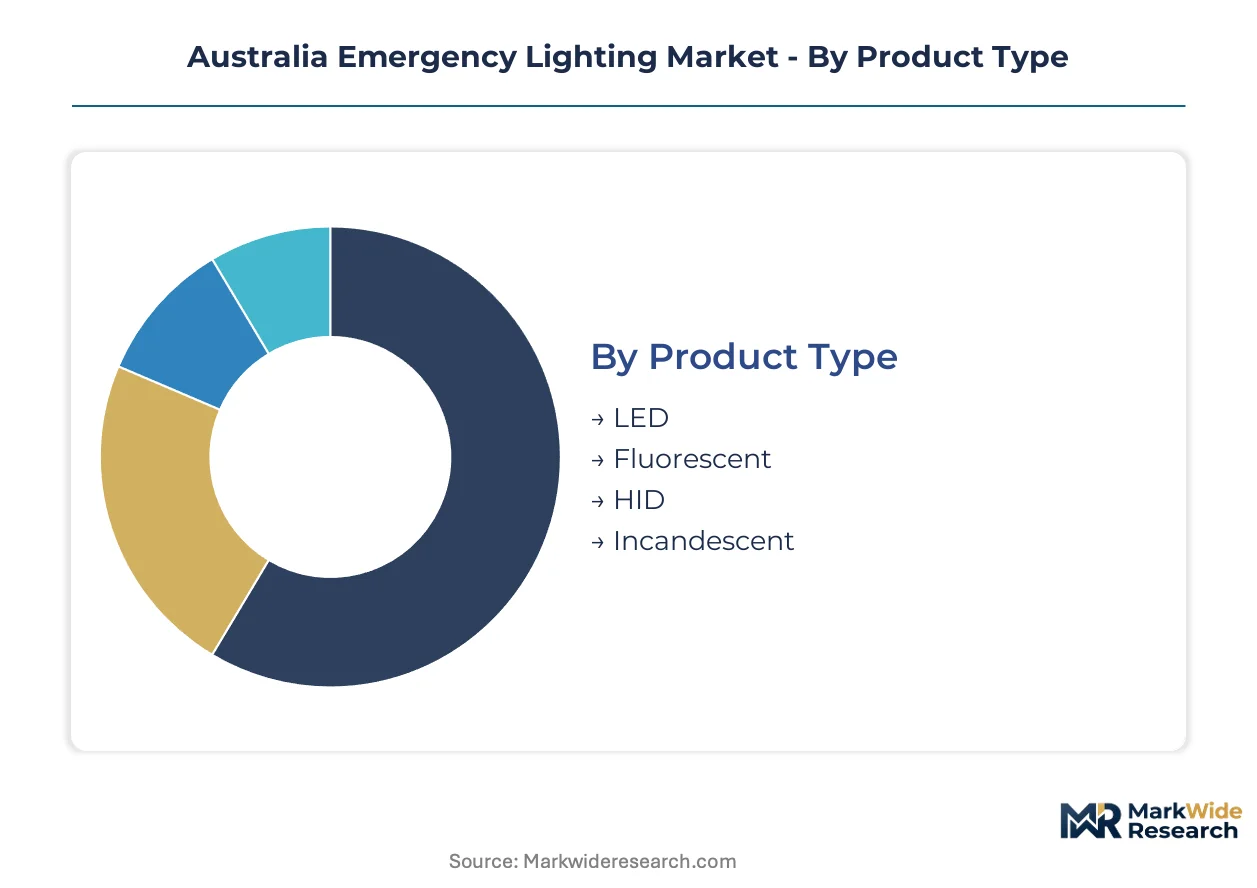
Emergency lighting procurement in Australia splits across four dimensions that shape specification behavior and channel economics. Electrical consultants weight technology architecture and installation type most heavily, while end-use verticals determine compliance stringency and maintenance burden.
Product Type:
Electrical wholesalers in New South Wales and Victoria stock LED and fluorescent lines most deeply, with HID and incandescent treated as special-order items for legacy institutional retrofits.
- LED:Solid-state semiconductor sources deliver 50,000-hour lifespans and draw minimal battery load during emergency operation. Hospital construction pipelines in Melbourne and Sydney specify LED exclusively for operating theatre evacuation routes where AS 2293 luminance mandates are strictest. By volume, LED leads. By growth pace, LED is climbing the fastest.
- Fluorescent:Gas-discharge tubes with phosphor coatings remain specified in aged-care facilities and public schools where capital replacement budgets lag technology cycles. Queensland's regional institutional buildings retain fluorescent installations that compress full conversion timelines.
- HID:High-intensity discharge lamps serve high-bay industrial applications in Western Australia warehouse construction where lumen output requirements exceed LED economics at extreme mounting heights.
- Incandescent:Tungsten filament technology persists only in specialized heritage building retrofits where aesthetic matching overrides efficiency considerations.
Margin structures favor LED at the premium tier, fluorescent at mid-tier, with HID and incandescent capturing residual specialty demand.
Installation Type:
Mounting configuration determines contractor labor allocation and project timeline, with ceiling and wall mounts dominating new commercial builds while portable units serve temporary construction site requirements.
- Ceiling Mount:Recessed and surface-mounted housings integrate with suspended ceiling grids in Class 5-9 office buildings. Sydney and Melbourne commercial developments specify ceiling mounts for aesthetic continuity with general lighting systems.
- Wall Mount:Bracket-fixed units above doorways and along egress corridors dominate retrofit installations where ceiling access is constrained by existing HVAC and fire suppression infrastructure.
- Portable:Battery-powered mobile luminaires serve construction phase emergency requirements and temporary event infrastructure where permanent installation is impractical.
- Surface Mount:Direct-to-substrate fixtures anchor industrial applications in Perth logistics facilities where exposed structure eliminates ceiling grid options.
Ceiling mount commands the largest installed base. Wall mount is expanding most quickly as retrofit activity accelerates across aging commercial stock.
End User:
Customer type shapes procurement channel selection, with commercial buyers routing through electrical engineering consultants and institutional purchasers favoring direct manufacturer engagement for large-scale hospital projects.
- Commercial:Office building owners and property managers in New South Wales drive replacement cycles through facility management contractors who bundle emergency lighting with fire safety system maintenance.
- Industrial:Warehouse developers and manufacturing operators in Western Australia specify high-bay emergency luminaires with extended backup duration for large-footprint evacuation scenarios.
- Residential:Multi-unit dwelling developers incorporate self-contained exit signage in apartment common areas where National Construction Code mandates apply to Class 2 buildings.
- Institutional:Hospital and aged-care facility operators in Victoria face TGA building product certification requirements that filter procurement to certified product families exclusively.
Commercial segment holds the deepest installed base. Institutional vertical is gaining share fastest as healthcare construction pipelines expand.
Technology:
System architecture determines capital intensity and lifecycle cost structure, with self-contained units favored for retrofit speed and central battery systems preferred for wiring economies in greenfield developments.
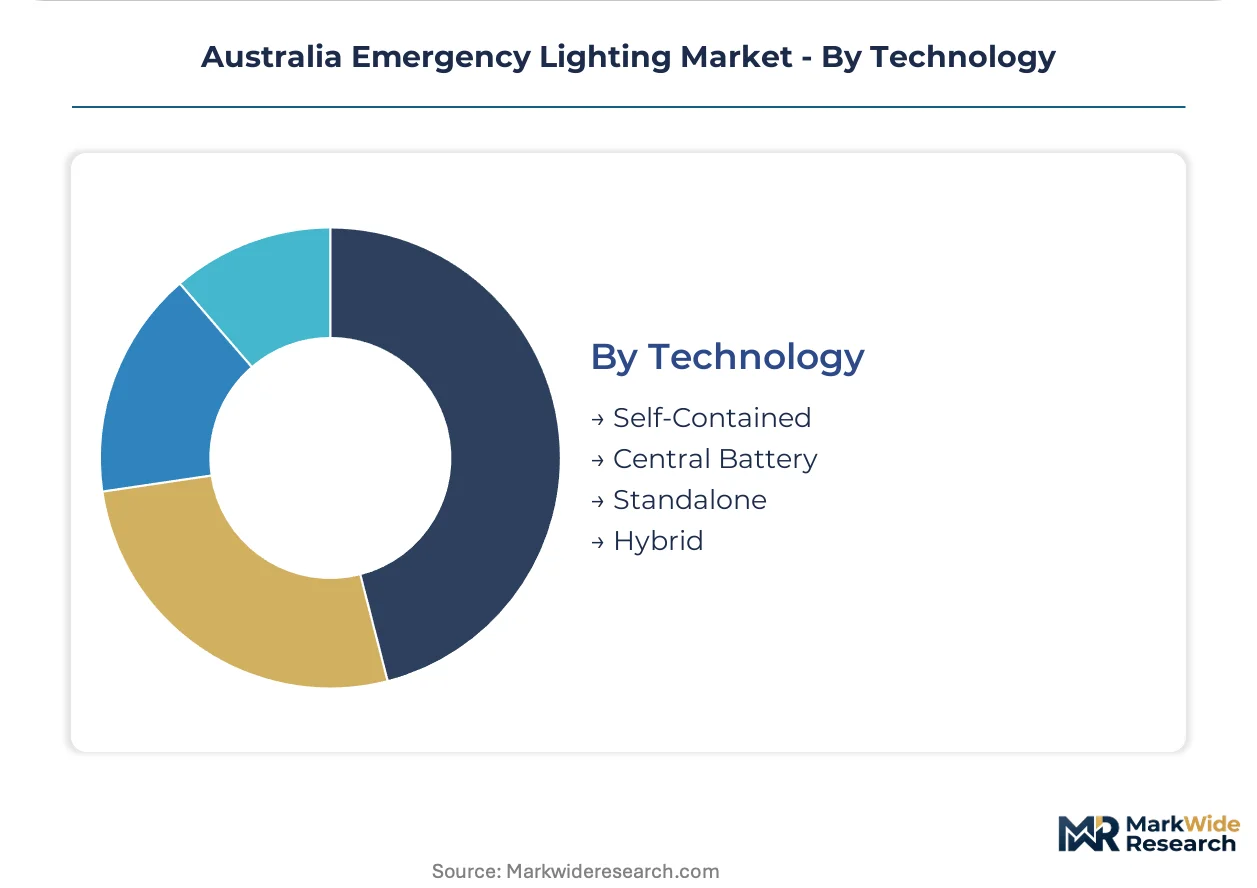
- Self-Contained:Battery-integrated luminaires minimize electrical contractor hours during retrofit installations. Queensland's aging commercial stock favors plug-and-replace self-contained units that avoid centralized infrastructure disruption.
- Central Battery:Wired architectures concentrate power supply in dedicated battery rooms, reducing per-unit hardware cost in large new-build commercial developments where installation scale justifies capital investment.
- Standalone:Single-point emergency luminaires operate independently of building-wide systems, serving isolated egress points and external exit routes in sprawling industrial campuses.
- Hybrid:Dual-mode systems combine local battery backup with central monitoring capability, appealing to facilities management platforms pursuing smart building convergence.
Self-contained technology dominates unit shipments. Hybrid configurations are expanding most quickly as building management system integration becomes a specification priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Broadband Network's fiber backbone underwrites Australia's emergency lighting connectivity infrastructure, enabling smart building integration across major metropolitan corridors.
New South Wales
Sydney's commercial property renewal and hospital construction pipelines drive self-contained LED procurement. The state's electrical safety regulator enforces strict AS 2293.1 compliance audits. Parramatta's emerging CBD cluster anchors specification activity for Class 5-9 building retrofits.
Victoria
Melbourne's healthcare expansion and aged-care facility upgrades accelerate photoluminescent exit signage demand. TGA building product certification requirements filter procurement to certified manufacturers exclusively. The Monash Medical Precinct exemplifies institutional procurement concentration for operating theatre evacuation systems.
Queensland
Brisbane's aging commercial stock sustains retrofit demand for plug-and-replace self-contained units. State electrical safety mandates require six-monthly testing intervals that generate recurring service revenue. Gold Coast hospitality developments drive replacement cycles in strata-titled properties.
Western Australia
Perth's logistics warehouse construction creates demand for high-bay emergency luminaires with extended backup duration. The National Construction Code triggers mandatory provisions in industrial Class 7-8 buildings. Kewdale's freight and distribution corridor concentrates specification activity for large-footprint evacuation scenarios.
South Australia
Adelaide's institutional building stock retains fluorescent installations that compress full LED conversion timelines. State-level electrical safety regulators enforce periodic testing compliance that sustains replacement component demand. The BioMed City precinct represents emerging healthcare construction activity with strict luminance requirements.
Australia Emergency Lighting Market Competitive Environment
Concentration sits with vertically integrated electrical conglomerates and specialized emergency lighting manufacturers. The vendor base splits between multinational industrial groups with captive battery supply chains and domestic specialists with channel control in wholesale distribution. Three archetypes dominate: integrated industrial conglomerates, photoluminescent technology specialists, and electrical wholesaler-aligned distributors. Competitive moves center on exclusive distribution arrangements and backward integration into battery cell supply.
Among the integrated industrial tier, Eaton Industries Pty Ltd and ABB Ltd represent multinational conglomerates with upstream control over power management components. Clevertronics Pty Ltd exemplifies the specialist archetype focused on maintenance-free photoluminescent systems. WBS Technology ABN anchors the wholesaler-aligned distributor category with concentrated channel presence in Queensland and Western Australia electrical supply networks.
| Leading Market Players |
|---|
| Eaton Industries Pty Ltd |
| WBS Technology ABN |
| Clevertronics Pty Ltd |
| BARDIC |
| E&E Lighting Australia |
| ABB Ltd |
| Haneco Lighting Australia Pty Ltd |
| Famco Lighting Pty Ltd |
| Legrand Australia Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day battery cell lead times from East Asian production hubs concentrate procurement leverage with electrical wholesalers who control volume-tier pricing negotiations across Australian distribution networks. This inventory compression amplifies margin pressure for self-contained luminaire manufacturers while reinforcing channel gatekeeper economics in Queensland and Western Australia.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales service bundling. Premium tiers capture TGA-certified product families specified for Melbourne hospital construction, while economy tiers serve Queensland retrofit contractors with price-sensitive procurement mandates. Cost compression in the mid-tier is intensifying because lithium battery input volatility erodes manufacturer margins. Electrical engineering consultants exhibit lowest price sensitivity due to specification authority, whereas regional installation contractors face acute margin pressure from wholesaler volume requirements.
Supply Chain Analysis
China, South Korea, and Japan anchor lithium-ion cell production for self-contained emergency luminaires, with Australia-dependent manufacturers drawing from concentrated East Asian battery supply chains. LED chip fabrication rests on Taiwanese and Chinese substrate suppliers, while phosphor coatings for photoluminescent exit signage source from Japanese specialty chemical producers. Single-source vulnerability in battery cell supply creates exposure to commodity price swings and logistics chokepoints at Port of Melbourne. Distribution runs through national electrical wholesaler networks that concentrate inventory holding and specification influence in Sydney and Melbourne metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emergency lighting procurement is converging with building management system platforms, creating interoperability requirements that favor manufacturers with IoT sensor integration capabilities and API-accessible control architectures.
For Market Incumbents: Fortify channel control through exclusive electrical wholesaler arrangements in Queensland and Western Australia where WBS Technology ABN's lockout strategy has proven effective. Deepen backward integration into battery cell supply to offset lithium input volatility that threatens margin stability. Prioritize TGA certification maintenance as state electrical safety regulators in Victoria intensify unannounced installation audits.
For New Entrants and Emerging Players: Anchor in Western Australia warehouse construction corridors around Perth where high-bay emergency luminaire demand outpaces established supplier coverage. Target hybrid technology configurations that combine local battery backup with central monitoring capability, as facilities management platforms prioritize smart building convergence. Pursue direct engagement with industrial logistics developers rather than routing through electrical engineering consultants who favor incumbent relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-mandated replacement-cycle play because AS 2293 periodic testing compliance and National Construction Code amendments sustain recurring demand regardless of macroeconomic conditions. Acquisition targets should display photoluminescent technology specialization or captive battery supply chain access. Monitor harmonization negotiations between AS 2293 and IEC standards as the signal for export-oriented manufacturer consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captive lithium cell sourcing insulates margins from East Asian commodity volatility. |
| Photoluminescent Technology Acquisition | Maintenance-free exit signage captures aged-care facility upgrade cycles in Victoria. |
| Smart Building Platform Partnership | IoT sensor integration opens specification channels with facilities management platforms. |
| Exclusive Wholesaler Distribution Arrangement | Channel lockout in Queensland and Western Australia blocks competitor market access. |
| TGA Certification Investment | Dual compliance burden with AS 2293 filters import competition from Asian manufacturers. |
Study Parameters
Operator-level perspectives from electrical contractors, facilities managers, hospital procurement officers, and electrical engineering consultants anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against National Construction Code amendments, AS 2293 standards documentation, state electrical safety regulator enforcement records, and electrical wholesaler inventory data. Bottom-up unit shipment estimates triangulated with top-down construction pipeline valuations across New South Wales, Victoria, Queensland, and Western Australia.
Sensitivity analysis across technology adoption curves, battery cost trajectories, and regulatory enforcement intensity shaped the forecast framework. Segmentation dimensions modeled include product type, installation configuration, end-use vertical, and system architecture, with additional granularity on TGA certification status and smart building integration capability. CAGRs derived from regression analysis of historical replacement cycles and projected construction completions across the analysis window. Industry-specific inputs incorporated hospital construction pipeline data from Melbourne and Sydney, plus warehouse development permits from Perth logistics corridors.
Material uncertainties — lithium battery input cost swings, AS 2293 and IEC harmonization timing, state electrical safety regulator audit intensity — sit outside the modeled envelope. Forecasts reflect assumptions regarding National Construction Code enforcement consistency and electrical contractor labor availability in metropolitan markets. Recalibration cycles align with material shifts in healthcare construction pipelines and battery chemistry cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market