
 Policing Technologies Market | 2026-2036
Policing Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Policing Technologies Market Outlook
FBI Criminal Justice Information Services compliance is reorganizing vendor eligibility for federal law enforcement contracts in the United States. Motorola Solutions leverages its Project 25 radio infrastructure footprint to anchor public safety communications procurement. Palantir Technologies competes on data integration depth across intelligence-led policing workflows. Axon Enterprise dominates body-worn camera ecosystems through vertical control over evidence cloud storage.
Policing technologies encompass hardware and software systems engineered for real-time situational awareness, digital evidence capture, and predictive crime analytics, typically operating on encrypted networks with sub-300-millisecond latency requirements for emergency dispatch. These systems serve to augment officer safety, accelerate investigative throughput, and enable accountable transparency in civilian interactions. Body camera and license plate recognition segments carry the deepest installed bases, while drone surveillance represents the fastest-expanding technology type as aviation regulators clarify beyond-visual-line-of-sight operating rules. Cloud-based deployment models are capturing disproportionate new investment as agencies migrate from aging on-premise evidence servers.
FBI CJIS security policy, EU GDPR data handling mandates, and the emerging EU AI Act algorithmic transparency framework collectively determine which vendors qualify for government procurement and how biometric data may be processed across jurisdictions. Compliance costs are filtering smaller software providers from multi-agency federal contracts. Stakeholders must monitor evolving certification timelines and interoperability standards to anticipate which technology architectures will secure sustainable funding commitments.
Market Dynamics
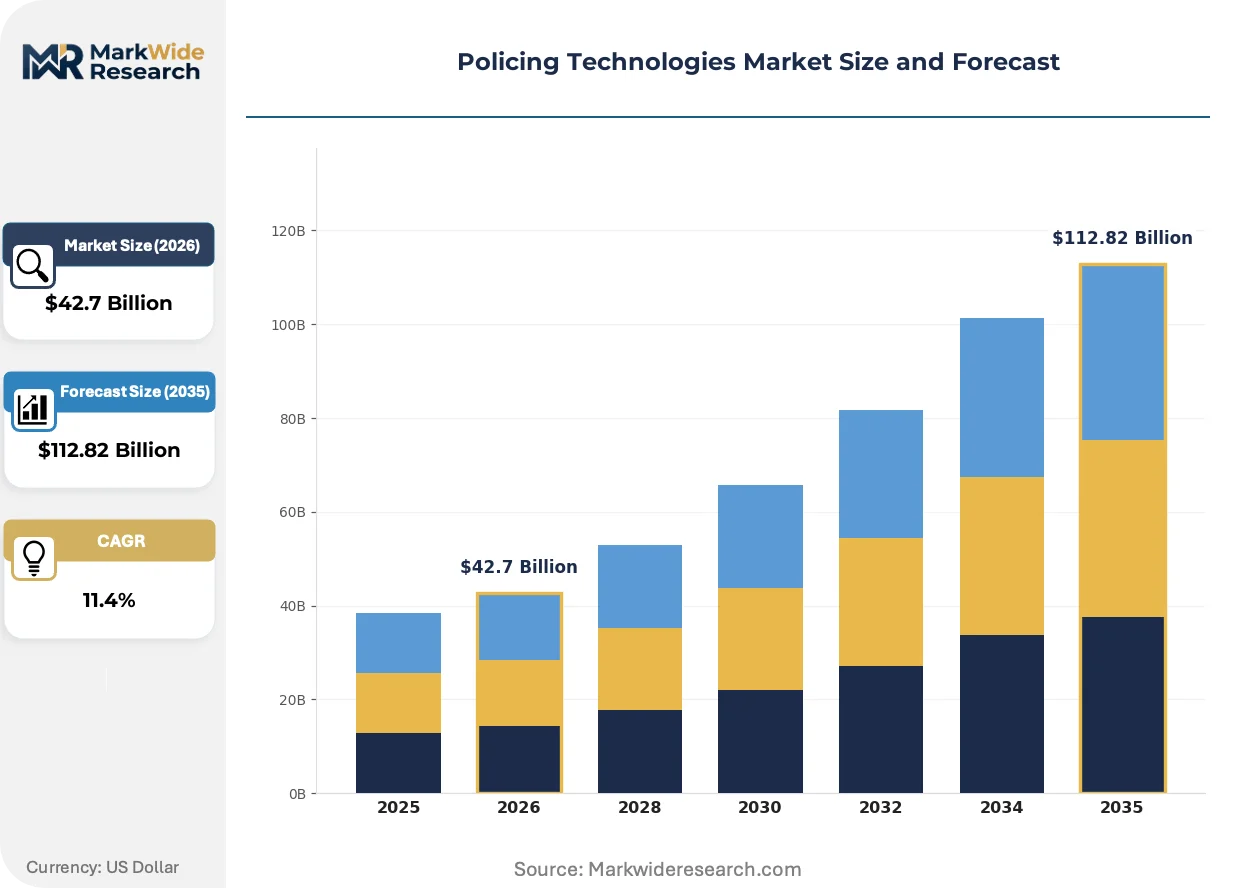
Cloud migration is compressing procurement cycles for municipal police departments while biometric data regulations fragment vendor qualification pathways across jurisdictions.
Growth Catalysts
- FBI CJIS Security Policy:Federal compliance mandates in the United States are disqualifying non-compliant vendors from multi-agency contracts, concentrating procurement among certified platform providers.
- Drone surveillance:Beyond-visual-line-of-sight aviation rule clarifications from the FAA are accelerating fleet deployments for aerial evidence collection and perimeter monitoring.
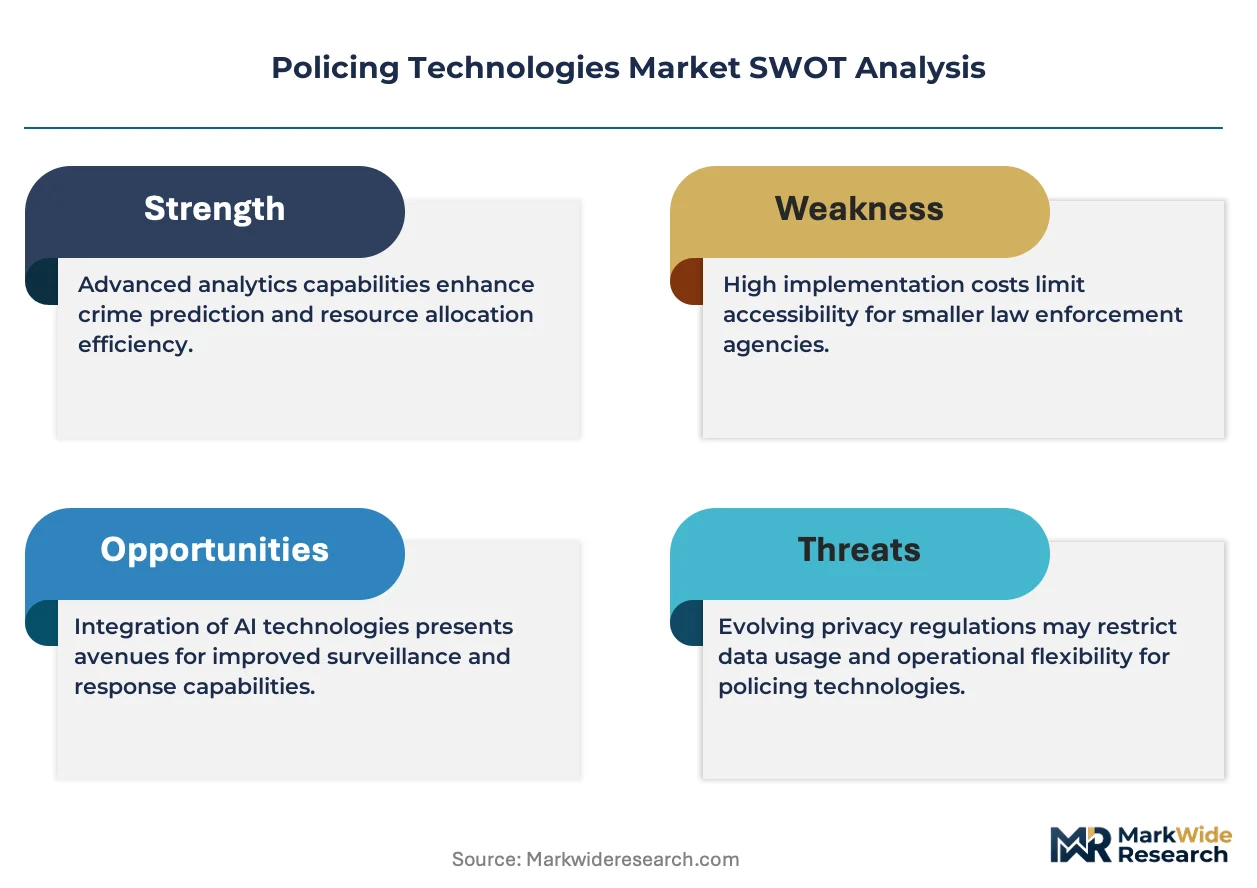
- EU AI Act algorithmic transparency:Predictive policing software vendors face new documentation requirements that favor established providers with dedicated compliance infrastructure.
Market Restraints
- Semiconductor supply concentration:Edge AI chip fabrication depends on Taiwan-based foundries, exposing body camera and license plate recognition hardware to geopolitical disruption risk.
- GDPR biometric processing friction:Cross-border evidence sharing between EU and non-EU agencies requires data localization investments that inflate platform operating costs.
- Legacy radio infrastructure lock-in:Project 25 protocol dependencies create switching costs that delay migration to LTE-based emergency communications.
Strategic Opportunities
- Rural agency underpenetration:Smaller sheriff departments in the United States lack dedicated IT staff, creating demand for managed evidence platform services with bundled technical support.
- Computer vision and thermal imaging convergence:Night-time drone operations are integrating multi-spectral sensors for search-and-rescue applications previously requiring helicopter deployment.
- CSRD sustainability disclosure:EU corporate reporting mandates are opening procurement pathways for vendors with documented supply chain carbon accounting.
Industry Challenges
- Forensic video analyst talent scarcity:Agencies struggle to recruit personnel qualified in authentication standards for AI-enhanced evidence admissibility.
- Multi-jurisdiction certification timelines:Vendors must maintain parallel compliance tracks for FBI CJIS, state-level encryption standards, and municipal procurement rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Policing Technologies Market |
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $112.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Body Cameras, Drone Surveillance, Gunshot Detection, License Plate Recognition Application Area: Traffic Management, Crime Prevention, Public Safety, Emergency Response End User Type: Law Enforcement Agencies, Security Firms, Government Bodies, Private Security Companies Deployment Model: On-Premise, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | NEC Corporation, Verint Systems, Motorola Solutions, Genetec, NICE, Axon Enterprise, Thales Group, L3Harris Technologies, Palantir Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Policing Technologies Market Strategic Shifts
Real-time edge processing is displacing centralized cloud workflows for latency-sensitive emergency dispatch applications. Three developments are compressing technology refresh cycles.
Edge AI inference chips embedded in body-worn cameras are miniaturizing on-device facial recognition and threat detection capabilities. Patrol officers in high-crime districts are piloting these units for immediate situational alerts. Onboard processing is miniaturizing bandwidth requirements and reducing evidence upload latency from minutes to seconds.
The EU AI Act's risk classification system for biometric identification is forcing predictive policing vendors to rearchitect algorithmic audit trails. High-risk system designations now require human-in-the-loop decision documentation. German state police procurement offices are prioritizing vendors with pre-certified transparency frameworks.
Subscription-based evidence platform licensing is displacing perpetual software purchases in municipal budget cycles. Annual recurring revenue models align vendor incentives with long-term data retention compliance. This transition is most visible in United Kingdom constabularies facing central government austerity constraints.
Policing Technologies Market Segmentation
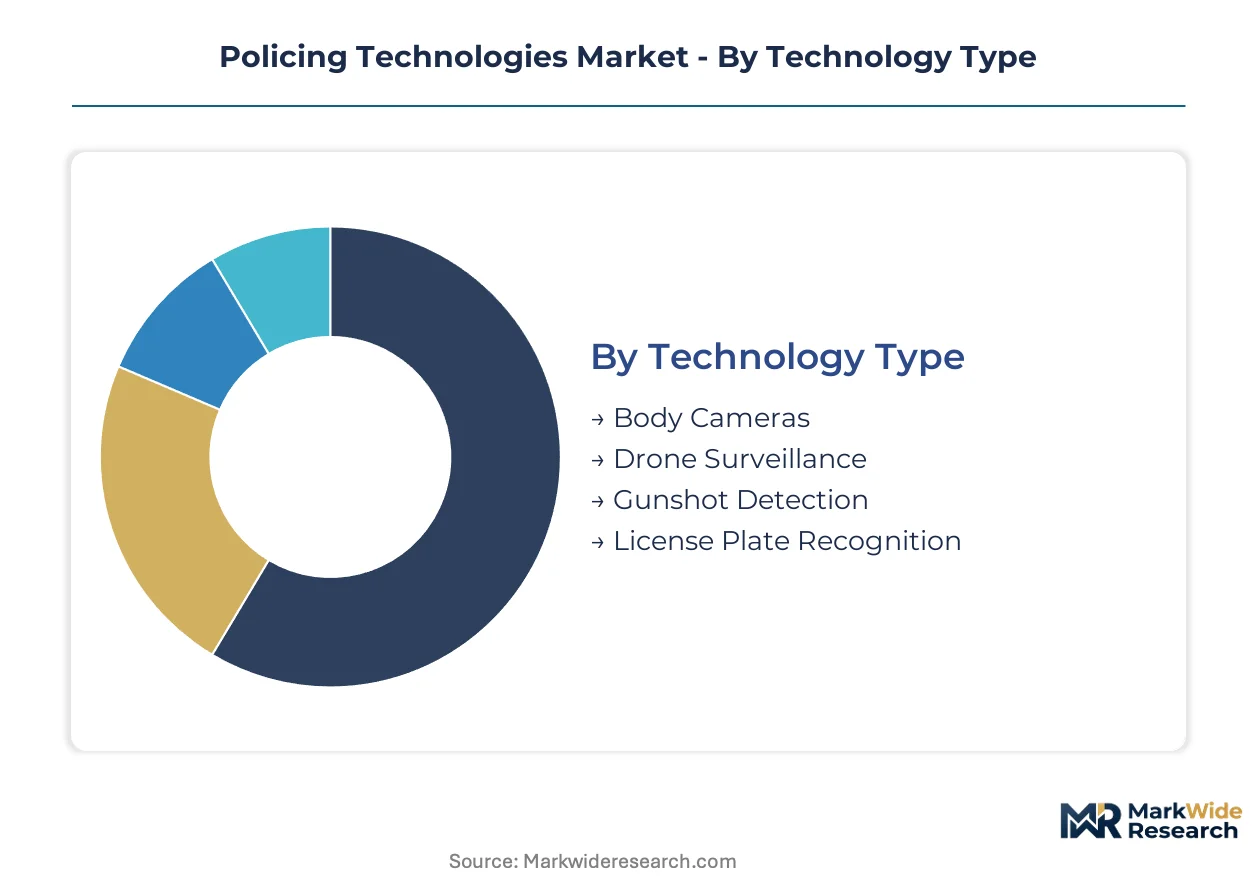
Technology procurement in policing diverges sharply between legacy hardware refresh cycles and cloud-native platform adoption. Segment boundaries are blurring as vendors bundle sensors, storage, and analytics into unified service contracts.
Technology Type:
Drone surveillance exerts the strongest substitution pressure on helicopter-based aerial units and fixed perimeter cameras, compressing unit economics for incumbent providers.
- Body Cameras:Wearable devices recording encrypted video with GPS metadata and chain-of-custody logging. Demand concentrates in United States municipal departments facing federal consent decree mandates for officer accountability documentation.
- Drone Surveillance:Unmanned aerial systems equipped with thermal imaging and real-time video downlink for search operations. FAA beyond-visual-line-of-sight rule clarifications are accelerating fleet procurement in Texas and California public safety agencies.
- Gunshot Detection:Acoustic sensor networks triangulating firearm discharge locations within urban coverage zones.
- License Plate Recognition:Optical character recognition systems mounted on patrol vehicles and fixed infrastructure for stolen vehicle recovery.
Body cameras retain volume leadership; drone surveillance holds the steepest expansion curve.
Application Area:
Cost tier stratification separates premium predictive analytics deployments from budget-constrained basic monitoring installations.
- Crime Prevention:Predictive analytics platforms aggregating historical incident data, weather patterns, and event calendars to allocate patrol resources. German state police offices prioritize vendors with EU AI Act pre-certified algorithmic transparency frameworks.
- Emergency Response:Real-time dispatch systems integrating CAD, radio, and mobile data terminals with sub-300-millisecond latency requirements. United Kingdom constabularies facing central government austerity constraints favor subscription-based licensing over capital purchases.
- Traffic Management:Automated enforcement systems for speed, red-light, and congestion monitoring.
- Public Safety:Crowd monitoring and perimeter security for large-scale events and critical infrastructure.
Emergency response commands the highest per-unit spending; crime prevention analytics are gaining share fastest.
End User Type:
Customer type determines procurement complexity, with federal agencies imposing certification burdens that filter smaller vendors from multi-agency contracts.
- Law Enforcement Agencies:Municipal, county, and state police departments with CJIS compliance mandates. FBI security policy disqualification risk concentrates procurement among certified platform providers with dedicated federal contracting teams.
- Government Bodies:National agencies and cross-jurisdictional task forces requiring interoperable standards.
- Security Firms:Private contractors supplementing public police presence at commercial and residential properties.
- Private Security Companies:Corporate campus and critical infrastructure protection services with lighter regulatory scrutiny.
Law enforcement agencies dominate absolute spending; private security companies represent the most price-sensitive demand pool.
Deployment Model:
Maturity gradients separate established on-premise installations from rapidly scaling cloud-native architectures.
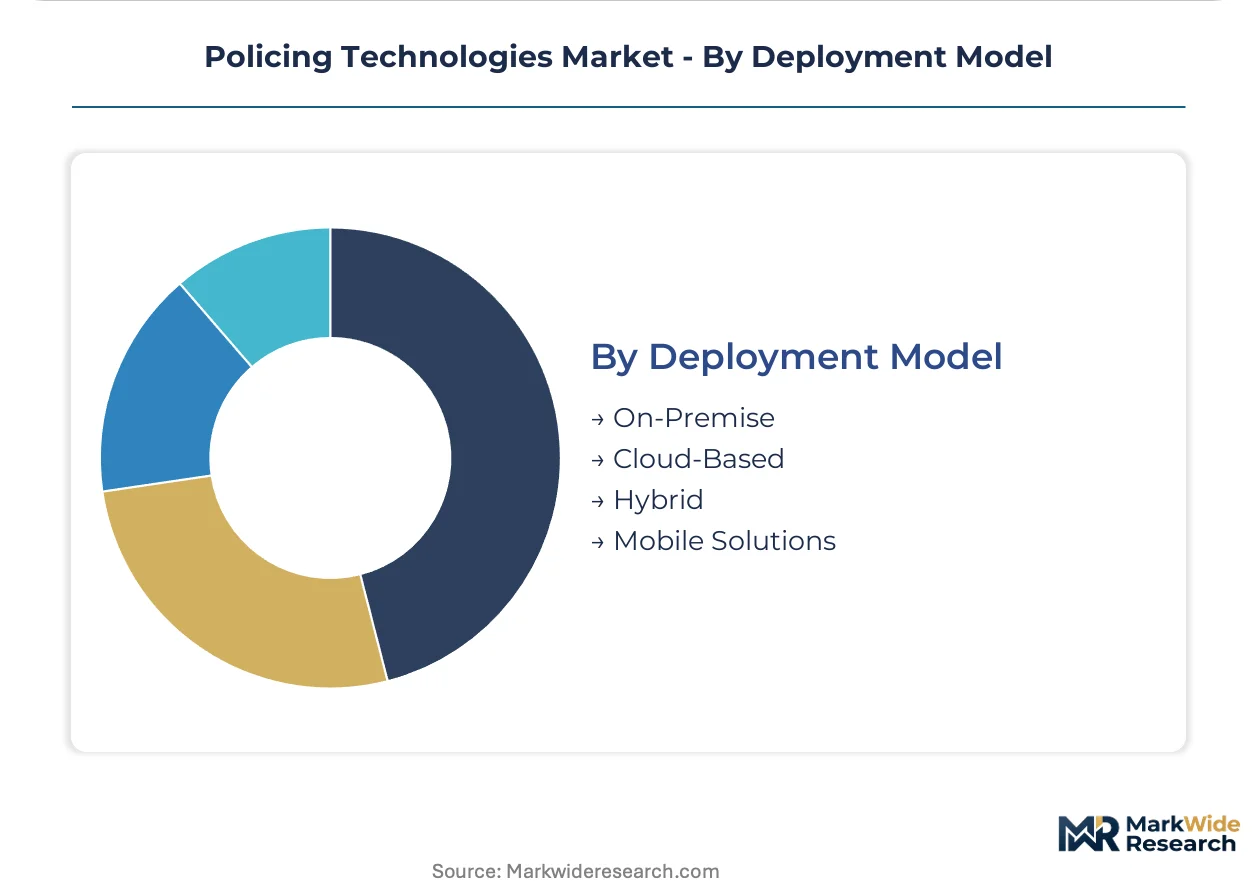
- Cloud-Based:Evidence management platforms with automatic scaling, disaster recovery, and vendor-managed security patching. Rural United States sheriff departments lacking dedicated IT staff drive demand for bundled technical support services.
- Hybrid:Split architectures retaining sensitive biometric processing on-premise while archiving cold evidence in cloud storage. GDPR data localization requirements inflate operating costs for cross-border evidence sharing between EU and non-EU agencies.
- On-Premise:Agency-operated servers with full physical control over evidence chain of custody.
- Mobile Solutions:Smartphone and tablet applications extending field access to case management systems.
On-premise retains installed base dominance; cloud-based deployments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement offices and municipal police departments concentrate technology acquisition in jurisdictions with active consent decrees and modernization mandates. Budget authority fragments across national, state, and local levels, creating multi-tier vendor qualification requirements.
United States
FBI CJIS Security Policy compliance filters vendor eligibility for federal law enforcement contracts, concentrating procurement among certified platform providers. The FAA's beyond-visual-line-of-sight rule clarifications accelerate drone fleet deployments in Texas and California public safety agencies. Chicago and New York City municipal departments drive demand for cloud-based evidence management platforms with bundled technical support.
Germany
State police procurement offices prioritize predictive analytics vendors with EU AI Act pre-certified algorithmic transparency frameworks. GDPR biometric processing mandates inflate operating costs for cross-border evidence sharing with non-EU agencies. Bavaria's law enforcement technology cluster anchors demand for integrated command-and-control systems with sub-300-millisecond latency specifications.
United Kingdom
Central government austerity constraints push constabularies toward subscription-based evidence platform licensing over capital purchases. The Home Office's national policing digital strategy mandates interoperability standards across 43 territorial police forces. London's Metropolitan Police Service pilots edge AI inference chips in body-worn cameras for real-time situational alerts.
France
CNIL oversight of biometric data processing shapes vendor selection for facial recognition and automated license plate recognition systems. The Ministry of Interior's security modernization program funds predictive policing deployments in Paris and Marseille. Île-de-France regional agencies consolidate procurement for drone surveillance units with thermal imaging capabilities.
Canada
RCMP national procurement standards influence municipal police department technology selection across provinces. Health Canada and PMRA regulatory frameworks intersect with emergency response system certification requirements. Ontario and Quebec provincial police services lead adoption of cloud-native evidence archiving with disaster recovery provisions.
Policing Technologies Market Competitive Environment
Player mix skews toward diversified defense-electronics conglomerates and specialized public safety software vendors. Market structure concentrates around vendors with pre-existing federal contracting relationships and CJIS certification infrastructure. Three archetypes dominate: radio infrastructure incumbents extending into software platforms, intelligence-software specialists repurposing defense-sector data integration capabilities, and body-camera hardware vendors capturing recurring cloud-storage revenue. Competitive moves center on vertical control over evidence chain-of-custody workflows and strategic bundling of sensors with managed platform services.
Within the radio infrastructure tier, Motorola Solutions and L3Harris Technologies occupy positions anchored by Project 25 protocol dependencies that create switching costs for municipal agencies. Palantir Technologies exemplifies the intelligence-software archetype, competing on data integration depth across multi-source policing workflows. Axon Enterprise sits within the hardware-to-cloud verticalization model, dominating body-worn camera installed bases through captive evidence storage subscriptions.
| Leading Market Players |
|---|
| NEC Corporation |
| Verint Systems |
| Motorola Solutions |
| Genetec |
| NICE |
| Axon Enterprise |
| Thales Group |
| L3Harris Technologies |
| Palantir Technologies |
| Others |
Value Chain & Pricing Dynamics
Edge AI inference chips displacing centralized cloud processing simultaneously relocate supply geography toward Taiwan and South Korea while compressing unit economics for legacy hardware vendors. This substitution dynamic concentrates pricing power among semiconductor foundries capable of sub-10-nanometer fabrication while eroding margins for body camera assemblers dependent on external chip sourcing.
Pricing Analysis
Cost-plus contracts with silicon indexation dominate procurement agreements between body camera OEMs and municipal police departments. Three-tier pricing structure across CJIS-certified premium, state-compliant standard, and non-certified economy levels separates federal contract-eligible vendors from regional competitors. Pricing pressure stems from subscription-based SaaS models displacing perpetual licenses in United Kingdom constabularies. Rural sheriff departments exhibit highest price sensitivity; federal agencies with dedicated modernization budgets show lowest.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for edge AI inference chips, while China dominates printed circuit board assembly and Mexico handles final device integration. Policing hardware draws from Taiwan Semiconductor Manufacturing Company foundry capacity, Sony image sensors, and Qualcomm Snapdragon platforms. Single-source vulnerability concentrates in Taiwan-based advanced node production exposed to geopolitical disruption. Distribution runs through Motorola Solutions and L3Harris direct federal contracting teams, with regional value-added resellers serving municipal departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor fragmentation creates acquisition opportunities as cloud migration splinters demand across specialized compliance tiers. FBI CJIS certification requirements and EU AI Act transparency mandates simultaneously expand the addressable market for certified providers while filtering sub-scale competitors from multi-agency contracts.
For Market Incumbents: Fortify evidence chain-of-custody workflows through backward integration into cloud storage infrastructure. Axon Enterprise's captive subscription model demonstrates how vertical control over data retention locks in municipal renewals. Counter emerging Palantir-style intelligence-software specialists by embedding predictive analytics within existing radio infrastructure footprints.
For New Entrants and Emerging Players: Lead with managed evidence platform services targeting rural United States sheriff departments lacking dedicated IT staff. Drone surveillance hardware for beyond-visual-line-of-sight operations offers the most penetrable segment given FAA rule clarifications. Partner with established Project 25 radio vendors to bypass certification barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors intelligence-software specialists with pre-certified EU AI Act frameworks. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volumes. Watch German state police procurement office vendor shortlists as inflection indicators for algorithmic transparency compliance premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| CJIS Certification Investment | FBI security policy compliance unlocks federal law enforcement procurement contracts. |
| EU AI Act Pre-Certification | German state police offices prioritize vendors with documented algorithmic audit trails. |
| Evidence Cloud Platform Integration | Subscription models align vendor incentives with long-term data retention mandates. |
| Edge AI Chip Partnership | On-device inference reduces bandwidth costs and accelerates emergency dispatch latency. |
| Rural Agency Service Bundling | Managed technical support addresses sheriff department IT capacity constraints. |
Study Parameters
A spread of perspectives from police procurement officers, CJIS compliance auditors, evidence platform engineers, and drone fleet managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FAA regulatory filings, FBI security policy documentation, EU AI Act draft provisions, and municipal budget appropriation records. Bottom-up installed base estimates triangulated against top-down federal modernization program allocations.
Segmentation dimensions modeled include technology type, deployment architecture, end-user agency tier, and geographic regulatory cluster across the projection horizon. CAGRs derived from unit economics analysis of subscription renewal rates and hardware replacement cycles. Forecast inputs incorporated edge AI chip cost curves and beyond-visual-line-of-sight aviation rule implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained federal funding commitments or accelerated EU AI Act enforcement would require recalibration. Forecasts reflect assumptions regarding CJIS certification timeline stability and semiconductor foundry capacity expansion. Recalibration cycles align with material shifts in FAA drone regulations and German state police procurement standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Global Data Center Physical Security Market
Physical Security
Active Geofencing Market
Physical Security
Security Guard Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Body Armor Plates Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Border Security Technologies Market
Physical Security
Global Wearable Security Device Market
Physical Security
Bulletproof Glass Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Physical Security Services Market
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Tactical Vests Market
Physical Security
Tactical Lights Market
Physical Security
South America Data Center Physical Security Market
Physical Security
Europe Physical Security Market