
 South America Data Center Physical Security Market | 2026-2036
South America Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
South America Data Center Physical Security Market Insights
Enterprise colocation operators are unwinding legacy reliance on telecom-owned facilities, shifting procurement toward independent data center specialists with dedicated security operations centers. Honeywell International Inc leverages its building automation heritage to integrate physical access with environmental controls across Brazilian facilities. Schneider Electric anchors its position through prefabricated modular data centers with embedded biometric access and video analytics. Axis Communications AB specializes in network camera architectures that reduce cabling complexity at edge deployments in Chile and Colombia.
South America data center physical security encompasses perimeter barriers, biometric access control, video surveillance, intrusion detection, and fire suppression systems engineered to protect critical IT infrastructure from unauthorized physical access, environmental threats, and deliberate sabotage. Systems typically integrate IP-based cameras with minimum 4K resolution, multi-factor authentication readers, and centralized security management platforms that correlate events across distributed sites. Surveillance Systems leads technology investment as operators face rising theft of copper cabling and cooling equipment, while Access Control captures margin pools through software subscription models tied to identity governance. Integration services within the Service Type dimension are expanding fastest as hyperscale entrants demand turnkey security architectures rather than discrete product procurement.
Brazil's ANATEL imposes physical security standards on telecommunications facilities that cascade into colocation operator compliance obligations, while Argentina's ENACOM mandates similar infrastructure protection for critical network nodes. Chile's cybersecurity framework under its Ministry of Interior requires data centers serving government contracts to maintain certified perimeter detection and 24-hour manned response capabilities. Stakeholders must monitor how evolving national critical infrastructure designations across the continent reshape liability allocation between facility operators and security vendors.
Market Dynamics
Hyperscale cloud operators are consolidating procurement around integrated security platforms, collapsing the traditional multi-vendor stack into single-source turnkey contracts that bundle perimeter detection, access control, and video analytics.
Growth Catalysts
- LGPD compliance mandates:Brazil's data protection law requires granular access logging and audit-ready documentation for facilities processing personal data, forcing facility upgrades across São Paulo's colocation corridor.
- Copper theft escalation:Organized theft of cabling and cooling infrastructure drives replacement demand for hardened perimeter barriers and intelligent video surveillance with real-time alerting capabilities.
- Edge computing proliferation:Distributed micro-data centers in Chilean mining regions and Colombian logistics hubs require compact, IP-based security systems that operate without dedicated on-site personnel.
Market Restraints
- Import duty burdens:Brazilian industrial equipment tariffs inflate landed costs for biometric readers and specialized surveillance hardware by 35-60 percent versus North American benchmarks.
- Foreign exchange volatility:Argentine and Brazilian currency instability compresses project budgets denominated in local currency while equipment contracts settle in dollars.
- Skilled technician scarcity:Certified integration specialists for multi-factor authentication and video management platforms concentrate in São Paulo and Santiago, leaving secondary markets underserved.
Strategic Opportunities
- Colombian market penetration:Bogotá's emerging data center cluster lacks established security vendor relationships, creating first-mover advantage for integrated platform providers.
- Subscription revenue models:Cloud-native access control platforms with per-door monthly pricing displace capital-intensive perpetual license sales, improving vendor cash flow predictability.
- Convergence of physical and cyber:Unified threat management platforms that correlate badge swipes with network login events command premium positioning in financial services verticals.
Industry Challenges
- Legacy system integration:Decades-old building management systems in Brazilian telecom facilities resist API-based connectivity with modern IP security architectures, extending deployment timelines.
- Certification bottlenecks:ANATEL type-approval processes for radio-frequency security devices stretch 8-14 months, delaying product launches and freezing vendor roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Data Center Physical Security Market |
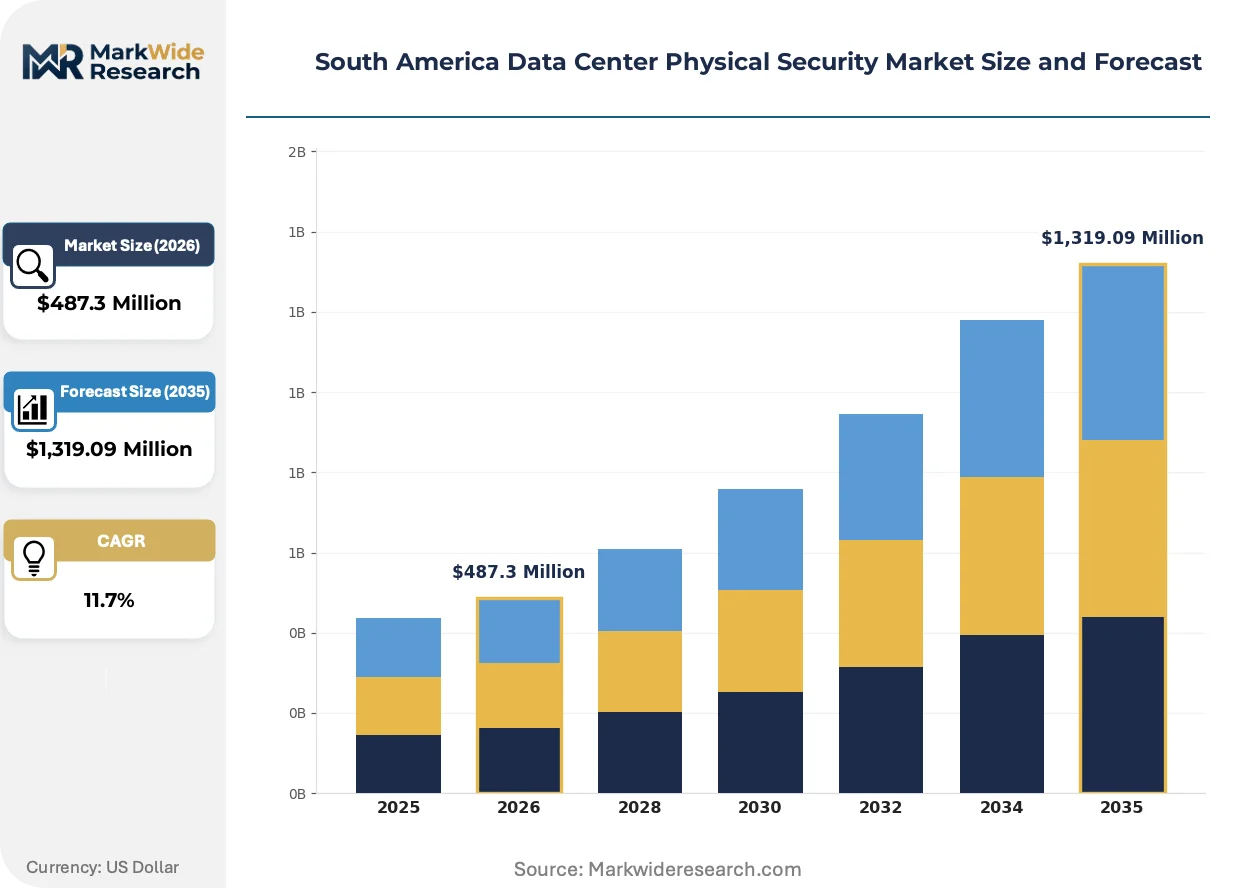
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Access Control, Surveillance Systems, Fire Detection, Intrusion Detection Service Type: Consulting, Integration, Maintenance, Monitoring Offering: Hardware, Software, Training, Solutions End User: Telecommunications, BFSI, Government, Healthcare |
| Companies Covered | Honeywell International Inc, Johnson Controls International, Schneider Electric, Axis Communications AB, Bosch Sicherheitssysteme GmbH, ABB Ltd, Hangzhou Hikvision Digital Technology Co Ltd, Genetec Inc, Siemens AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Data Center Physical Security Market Trends and Innovations
Software-defined security architectures are displacing hardware-centric deployments, enabling remote configuration and predictive maintenance that reduces truck rolls across vast Andean geographies.
AI-powered video analytics is fragmenting the traditional manned guarding model. Edge-deployed GPUs process behavioral recognition and anomaly detection locally, eliminating latency to cloud backhauls. Chilean mining operators and Peruvian logistics campuses adopt these systems fastest, compressing guard force headcount by half while expanding coverage density.
Argentina's ENACOM critical infrastructure designation is tightening physical security standards for network facilities. The regulation mandates redundant power, biometric access logging, and 24-hour incident response capabilities. Colocation operators in Buenos Aires retrofit existing facilities or exit the government contracting segment entirely.
Enterprise buyers now demand outcome-based service level agreements rather than equipment procurement. Contracts specify uptime guarantees and incident response times, transferring operational risk to security vendors. This shift concentrates in Brazilian financial services and São Paulo-based multinational headquarters seeking predictable operational expenditures.
South America Data Center Physical Security Market Segmentation
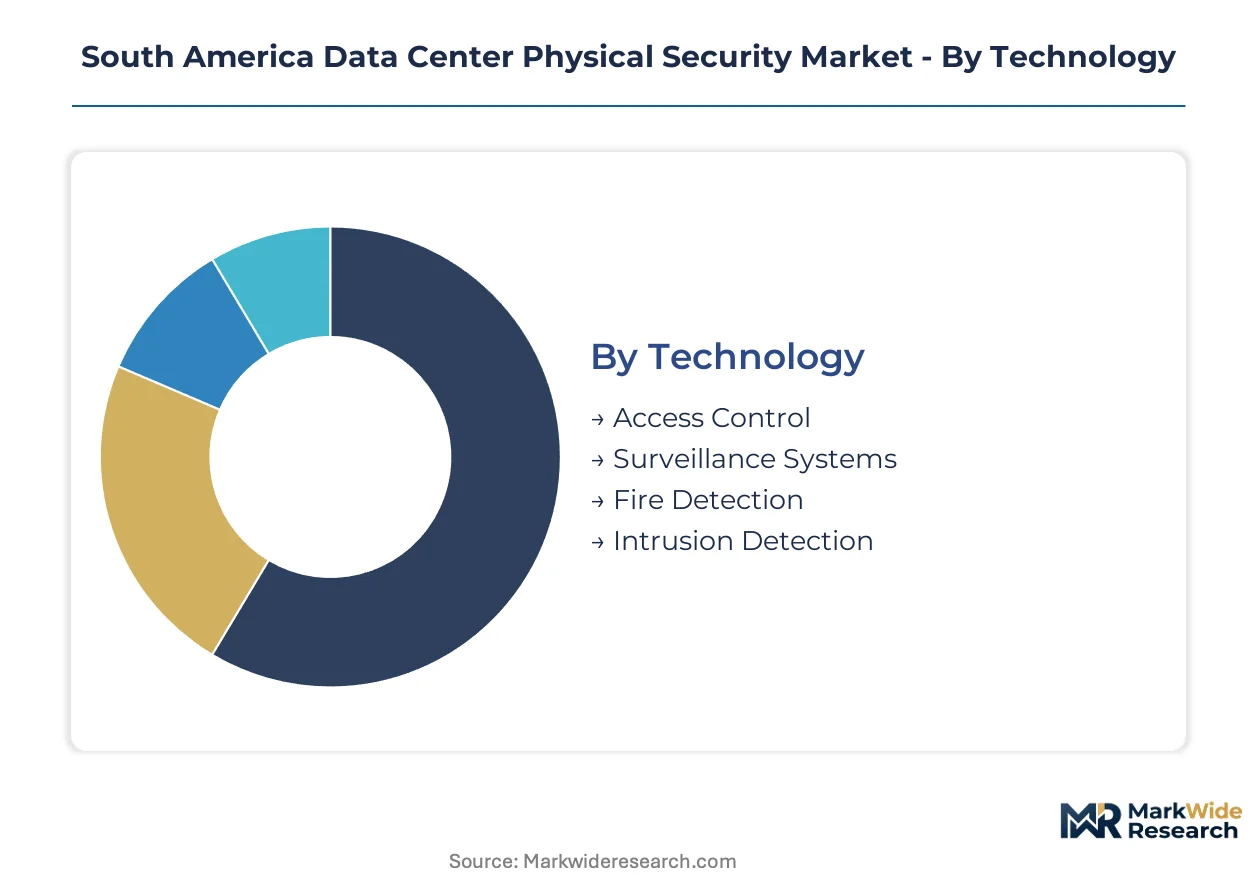
Segmentation reveals how Brazil's LGPD compliance mandates and Chile's critical infrastructure designations reshape procurement patterns across distinct technology and service categories. Operators prioritize integrated platforms that bundle hardware, software, and ongoing monitoring to satisfy audit requirements while containing operational complexity.
Technology:
ANATEL's telecommunications facility standards in Brazil and ENACOM's critical infrastructure rules in Argentina create divergent technical requirements for perimeter protection and access logging systems.
- Surveillance Systems:IP-based camera networks with minimum 4K resolution and edge-deployed GPUs for behavioral analytics. Brazilian hyperscale campuses in São Paulo's metropolitan corridor deploy these most intensively to combat organized copper theft and cooling equipment theft. Real-time alerting capabilities command premium positioning.
- Access Control:Multi-factor authentication readers with biometric templates and centralized identity governance platforms. Demand concentrates in Buenos Aires colocation facilities retrofitting for ENACOM government contract eligibility. Software subscription models tied to per-door monthly pricing displace capital-intensive perpetual licenses.
- Fire Detection:Very early smoke detection apparatus with aspirating sensors for high-density server environments.
- Intrusion Detection:Perimeter barrier sensors and volumetric detection for unmanned edge facilities in Chilean mining regions.
Established volume favors Surveillance Systems; emerging adoption favors Access Control.
Service Type:
Cost tier differentiation separates turnkey bundled contracts from discrete professional services across the Andean geography.
- Integration:Turnkey security architecture deployment combining perimeter detection, access control, and video analytics into unified platforms. Hyperscale cloud operators in Brazil consolidate procurement around single-source contracts that collapse traditional multi-vendor stacks. This segment climbs the fastest as entrants demand outcome-based service level agreements.
- Monitoring:24-hour incident response and centralized security operations center oversight. Chile's Ministry of Interior mandates certified capabilities for data centers serving government contracts, concentrating demand in Santiago and Valparaíso facilities.
- Consulting:Compliance gap analysis and LGPD readiness assessment for facility operators.
- Maintenance:Predictive service contracts reducing truck rolls across vast distances.
Margin concentration sits with Integration; volume scale accumulates to Monitoring.
Offering:
Maturity curves separate legacy hardware-centric deployments from cloud-native software architectures gaining share fastest.
- Software:Cloud-native security management platforms with remote configuration and API-based connectivity to building automation systems. Brazilian financial services verticals in São Paulo adopt these to correlate physical badge events with network login anomalies. Software-defined architectures displace hardware-centric models most aggressively.
- Solutions:Outcome-based bundled offerings specifying uptime guarantees and incident response times. Multinational headquarters seek predictable operational expenditures through risk transfer to vendors.
- Hardware:Biometric readers, specialized cameras, and perimeter sensors facing 35-60 percent import duty inflation in Brazil.
- Training:Certification programs for multi-factor authentication and video management platforms addressing technician scarcity outside São Paulo and Santiago.
Revenue momentum favors Software; installed base dominance remains with Hardware.
End User:
Customer type determines compliance stringency and procurement centralization across national jurisdictions.
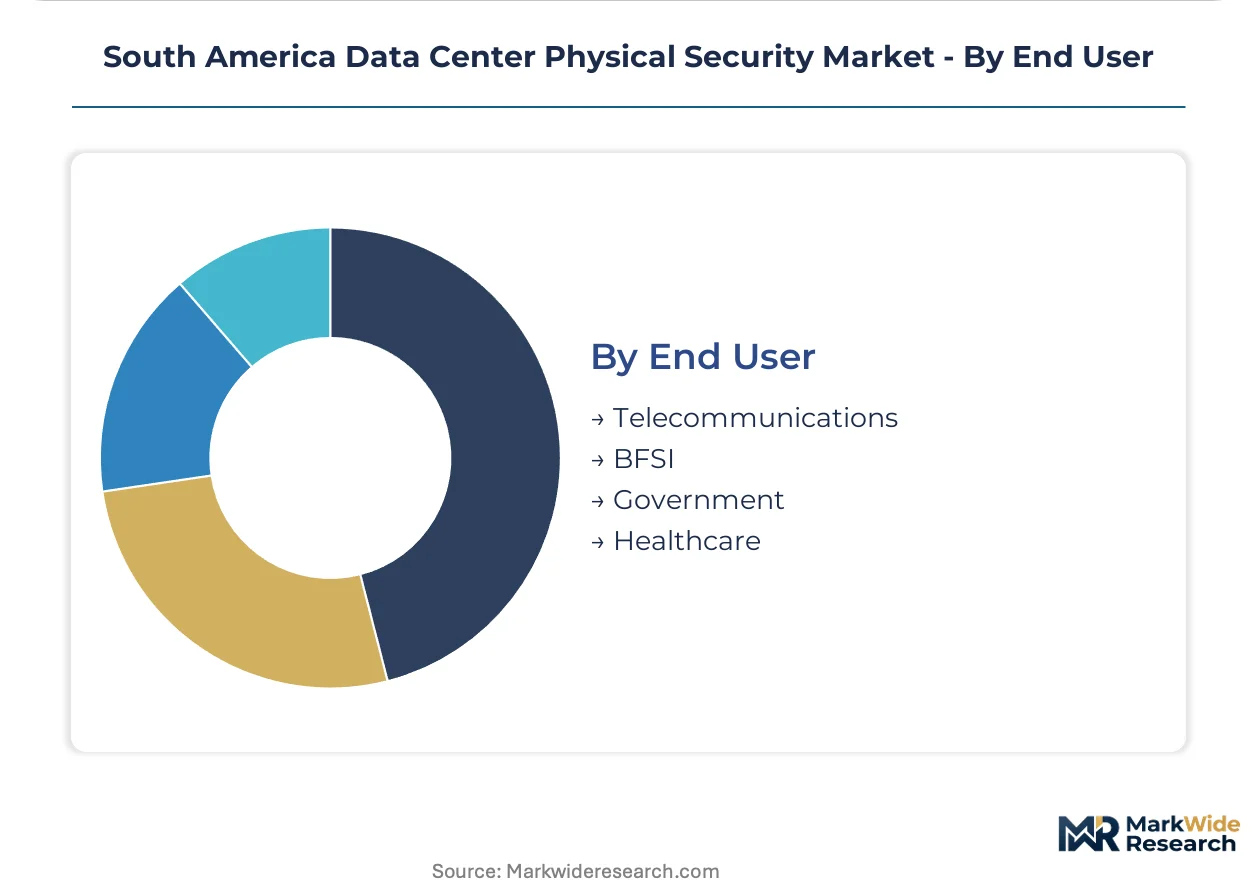
- Telecommunications:ANATEL-regulated facilities with cascading compliance obligations into colocation operator supply chains. Legacy building management systems in Brazilian telecom-owned properties resist API connectivity, extending deployment timelines for modern IP security architectures.
- Government:ENACOM-mandated redundant power, biometric logging, and 24-hour response capabilities in Argentina. Buenos Aires operators face retrofit-or-exit decisions for critical infrastructure designation.
- BFSI:Unified threat management platforms correlating physical and cyber events for financial services compliance.
- Healthcare:LGPD-aligned access logging for facilities processing patient personal data.
Procurement scale concentrates in Telecommunications; compliance-driven replacement cycles peak in Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility construction clusters along Brazil's fiber-dense São Paulo corridor, with secondary concentration emerging in Chilean mining regions and Colombian logistics hubs. Tax incentives and submarine cable landings pull investment toward specific metropolitan zones rather than distributing evenly across national territories. Regulatory fragmentation across ANATEL, ENACOM, and Chile's Ministry of Interior forces vendors to maintain country-specific compliance roadmaps.
Brazil
Hyperscale cloud campuses drive perimeter defense investment across São Paulo's metropolitan corridor. ANATEL imposes physical security standards on telecommunications facilities that cascade into colocation operator compliance obligations. Fiber-dense infrastructure and tax incentives cluster data center construction in São Paulo state, where copper theft of cabling and cooling equipment accelerates replacement demand for hardened barriers.
Chile
Edge computing proliferation in mining regions requires compact IP-based security systems operating without dedicated on-site personnel. The Ministry of Interior mandates certified perimeter detection and 24-hour manned response capabilities for data centers serving government contracts. Santiago and Valparaíso facilities concentrate monitoring demand as operators retrofit for critical infrastructure eligibility.
Argentina
ENACOM's critical infrastructure designation tightens physical security standards for network facilities, mandating redundant power and biometric access logging. Buenos Aires colocation operators face retrofit-or-exit decisions for government contract eligibility. Currency instability compresses project budgets denominated in pesos while equipment contracts settle in dollars, stretching procurement timelines.
Colombia
Bogotá's emerging data center cluster lacks established security vendor relationships, creating first-mover advantage for integrated platform providers. Distributed micro-data centers in logistics hubs require compact security architectures operable without permanent staff. The absence of legacy system baggage allows direct adoption of cloud-native access control platforms with per-door monthly pricing.
South America Data Center Physical Security Market Competitive Landscape
Concentration sits with building automation conglomerates and specialized surveillance technology providers. The vendor base spans three distinct tiers: diversified industrial conglomerates with security divisions, pure-play physical security specialists, and IT infrastructure vendors extending into facility protection. Strategic moves center on collapsing multi-vendor stacks into single-source turnkey contracts and shifting revenue models from perpetual licenses toward subscription-based access control.
Within the building automation tier, Honeywell International Inc and Schneider Electric exemplify integrated platform strategies that bundle environmental controls with physical access systems. Axis Communications AB occupies a position among network camera specialists reducing cabling complexity at edge deployments. These three anchors demonstrate how heritage in adjacent building systems or video architecture translates into data center security positioning without requiring pure-play security DNA.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Johnson Controls International |
| Schneider Electric |
| Axis Communications AB |
| Bosch Sicherheitssysteme GmbH |
| ABB Ltd |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Genetec Inc |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
ANATEL type-approval certification for radio-frequency security devices gates both vendor qualification and price differentiation simultaneously, compressing procurement timelines for compliant suppliers while inflating landed costs for non-certified alternatives. Brazilian import duties on industrial equipment compound this dynamic, forcing buyers to weigh certification premiums against tariff exposure when sourcing biometric readers and specialized surveillance hardware.
Pricing Analysis
LGPD compliance mandates dictate the pricing tier structure across São Paulo's colocation corridor, with three-tier pricing separating audit-ready integrated platforms from discrete hardware procurement and legacy system retrofits. Price differentiation rests on certification grade and software subscription bundling, with cloud-native access control platforms commanding recurring revenue premiums over perpetual licenses. Cost compression in hardware-centric tiers intensifies because import duty burdens squeeze margins on biometric readers and specialized cameras. Hyperscale cloud operators exhibit least price sensitivity due to outcome-based SLA requirements, while secondary market colocation providers in tertiary Brazilian cities face acute budget constraints.
Supply Chain Analysis
Panama Canal transit chokepoints and Port of Santos congestion underwrite logistics vulnerability for security hardware bound to Brazilian hyperscale campuses. Manufacturing concentration centers on China, Taiwan, and South Korea for edge-deployed GPUs, network cameras, and multi-factor authentication readers. Raw material dependencies span rare earth elements for sensor components, copper cabling for power infrastructure, and specialized optical glass for 4K camera lenses. Single-source vulnerability concentrates in Taiwanese semiconductor fabrication for video analytics chipsets. Distribution runs through São Paulo-based systems integrators with ANATEL certification authority, channeling hardware through certified partners rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined security architectures are reshaping competitive positioning across South American data center infrastructure, with LGPD enforcement and copper theft escalation compressing replacement cycles for legacy perimeter systems. This regulatory-technological inflection creates asymmetric opportunity for platform providers against hardware-centric incumbents.
For Market Incumbents: Compound defensive moats through backward integration into cloud-native security management platforms and captive certification services for ANATEL compliance. Threat from pure-play SaaS entrants in access control demands rapid subscription model migration. Priority lever sits with consolidating multi-vendor stacks into single-source turnkey contracts that transfer operational risk to vendor balance sheets. For New Entrants and Emerging Players: ENACOM fast-track certification for Argentine government contract eligibility opens white-space penetration in Buenos Aires colocation retrofit market. Bogotá's emerging data center cluster offers most penetrable geography given absence of entrenched vendor relationships. Go-to-market angle centers on per-door monthly pricing models that displace capital-intensive perpetual licenses among mid-tier colocation operators. For Investors and Strategic Acquirers: Chile's cybersecurity framework under its Ministry of Interior reshapes the acquisition landscape by mandating certified perimeter detection capabilities that concentrate vendor viability. Long-term viability favors integrated platform providers with software subscription revenue exceeding fifty percent of total mix. Target archetype: cloud-native access control specialists with API-first architectures and established presence in Santiago or São Paulo. Signal to watch: ANATEL approval timeline compression as indicator of regulatory pathway risk reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies perimeter detection, access control, and video analytics into single-source contracts for hyperscale operators. |
| Subscription Model Migration | Transforms perpetual license revenue into recurring per-door monthly pricing, improving cash flow predictability for vendors. |
| Certification Fast-Track Investment | Compresses ANATEL type-approval timelines from fourteen months to competitive eight-month windows. |
| Backward Integration into Cloud Software | Captures margin pools in security management platforms that correlate physical badge events with network login anomalies. |
| Geographic Expansion to Colombia | Establishes first-mover positioning in Bogotá's emerging data center cluster before entrenched vendor relationships solidify. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center facility managers, physical security systems integrators, colocation procurement leads, and ANATEL certification specialists. Secondary validation drew from ANATEL regulatory filings, ENACOM infrastructure designations, Chilean Ministry of Interior cybersecurity framework documentation, and hyperscaler capital expenditure disclosures. Customs and trade data for security hardware imports into Brazil, Argentina, and Chile provided volume triangulation against bottom-up facility construction tracking.
Across the analysis window, the forecasting framework modeled technology segmentation by surveillance systems, access control, intrusion detection, and fire suppression; service type by integration, monitoring, consulting, and maintenance; and end-user verticals spanning telecommunications, government, BFSI, and healthcare. CAGRs were derived through regression analysis of facility construction pipelines against security spend per square meter benchmarks, with inputs from edge computing deployment rates in Chilean mining regions and LGPD compliance retrofit cycles in São Paulo.
Underlying assumptions cover sustained ANATEL enforcement intensity, stable import duty regimes, and continued hyperscale investment concentration in São Paulo state, with deviation risk concentrated in Argentine currency volatility and Colombian regulatory framework evolution. Practitioners should keep alternative scenarios live as ENACOM critical infrastructure designations and Chilean government contract eligibility requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Airport Full Body Scanner Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Security Guard Market
Physical Security
Active Geofencing Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Border Security Technologies Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Tactical Lights Market
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Physical Security Market
Physical Security
Policing Technologies Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Smart Police Helmet Market