
 Border Security Technologies Market | 2026-2036
Border Security Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Border Security Technologies Market Outlook
Software-defined sensor fusion is broadening what border security contracts deliver, shifting procurement from discrete hardware to integrated threat-detection platforms with recurring analytics subscriptions. BAE Systems leverages its sovereign UK manufacturing base to anchor large-scale perimeter programs across British and Commonwealth borders. RTX Corporation competes through dense R&D investment in radar and electronic warfare subsystems purpose-built for harsh terrain monitoring. Elbit Systems specializes in thermal imaging and unmanned border patrol technologies, occupying a distinct niche in desert and maritime frontier environments.
Border security technologies encompass integrated hardware-software systems engineered to detect, identify, and interdict unauthorized cross-border movement, typically operating across spectral bands from visible light through long-wave infrared with detection ranges exceeding ten kilometers under adverse weather conditions. These systems serve sovereign states by creating layered defensive depth against smuggling, irregular migration, terrorism, and trafficking at air, land, and maritime entry points. Surveillance Systems currently absorbs the largest share of procurement budgets as governments prioritize wide-area persistent coverage over point solutions. Perimeter Security and Smart Fencing applications are gaining structural momentum where terrain complexity demands autonomous ground-based detection rather than airborne patrol alone. Cloud-Based deployment models are emerging fastest among customs authorities seeking centralized data fusion across multiple frontier stations without capital-intensive on-site server infrastructure.
The US Department of Homeland Security and US Customs and Border Protection shape North American demand through technical specifications for interoperable command-and-control networks, while India's BIS and Ministry of Home Affairs mandate domestic content thresholds for critical surveillance procurement. The EU Green Deal and CSRD reporting requirements are beginning to influence energy consumption standards for remote border sensor arrays, adding compliance dimensions to product design. Stakeholders must weigh sovereign data-localization mandates against the operational efficiency of cross-border intelligence sharing architectures as they configure future platform investments.
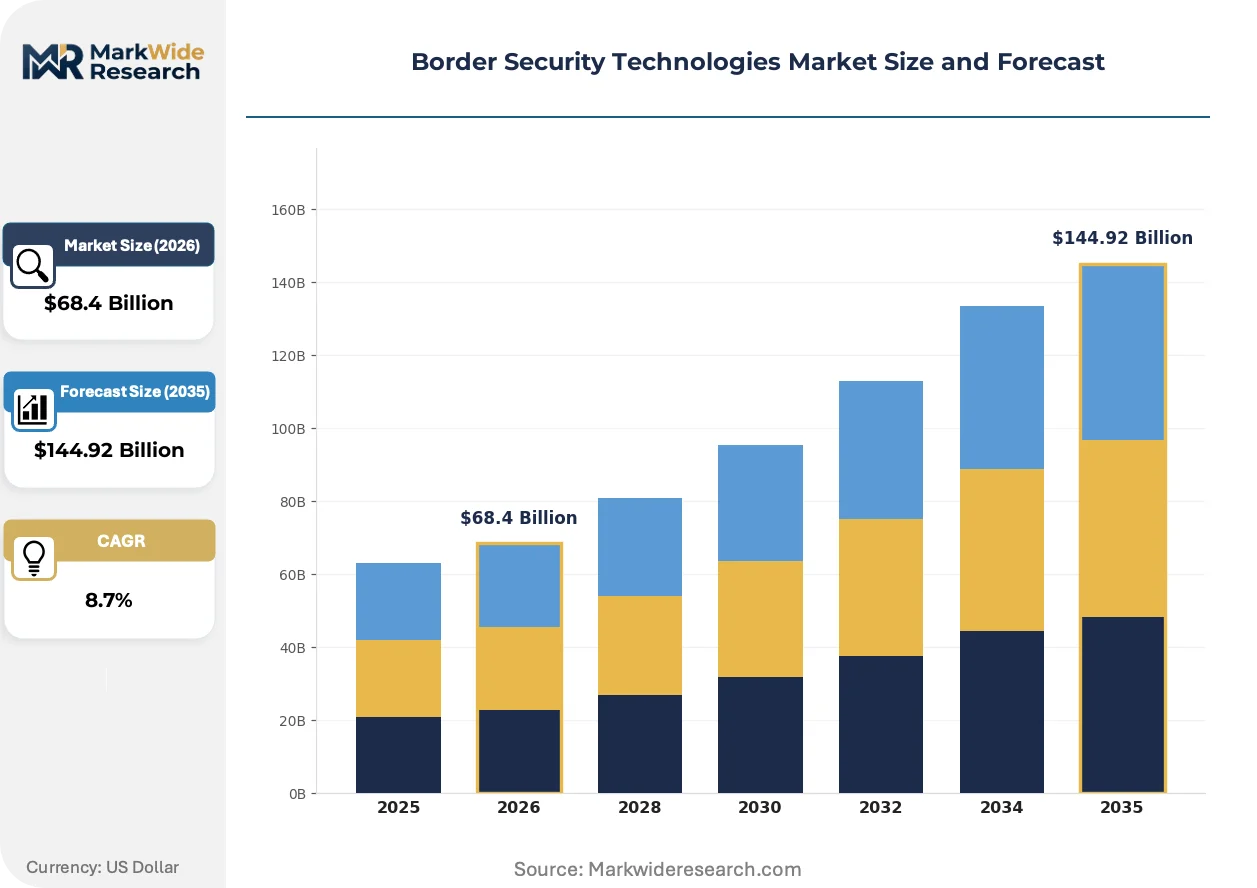
Market Dynamics
Software-defined sensor fusion is compressing procurement cycles by bundling hardware acquisition with recurring analytics subscriptions, forcing legacy perimeter vendors to restructure revenue models around platform stickiness rather than one-time equipment sales.
Growth Catalysts
- CSRD Reporting Mandates:The EU Green Deal and CSRD requirements are accelerating replacement of energy-intensive legacy sensor arrays with low-power autonomous detection nodes across European frontier stations.
- India BIS Localization:India's Bureau of Indian Standards mandates domestic content thresholds for critical surveillance procurement, creating captive demand for locally manufactured thermal imaging and radar subsystems.
- Maritime Frontier Expansion:Sovereign states are extending perimeter security investments into littoral zones and exclusive economic zones, driving demand for naval-integrated coastal surveillance networks.
Market Restraints
- Semiconductor Supply Concentration:Advanced sensor processing chips for long-wave infrared and synthetic aperture radar concentrate in East Asian foundries, exposing procurement timelines to geopolitical supply disruptions.
- Legacy Infrastructure Lock-in:Decades-old hardwired command-and-control networks at major land borders create technical debt that slows cloud-based platform migration and drives integration costs upward.
- Dual-Use Export Controls:International Traffic in Arms Regulations and EU dual-use technology restrictions fragment vendor addressable markets and lengthen sales cycles for thermal imaging and electronic warfare subsystems.
Strategic Opportunities
- AI-Enabled Predictive Analytics:Convergence of edge computing with machine learning inference engines enables real-time threat pattern recognition without continuous human operator monitoring.
- Subscription Service Models:Customs authorities in Germany and the United Kingdom are piloting managed detection-as-a-service contracts that shift capital expenditure to operational budgets and lock in multi-year vendor relationships.
- Desert and Maritime Niches:Extreme terrain environments underserved by conventional radar—Saharan transit corridors, Andean highlands, South China Sea atolls—present white space for specialized unmanned patrol platforms.
Industry Challenges
- Interoperability Certification:US Customs and Border Protection technical specifications for command-and-control networks require extensive protocol compliance testing that extends product launch timelines by 18-24 months for non-incumbent vendors.
- Sensor Fusion Engineering Talent:Scarce expertise in integrating multi-spectral data streams—combining radar returns, thermal signatures, and acoustic patterns—drives recruitment competition between defense primes and autonomous vehicle developers.
- Cross-Border Data Sovereignty:Conflicting national data-localization mandates complicate architecture design for intelligence-sharing networks spanning multiple sovereign jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Border Security Technologies Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Systems, Perimeter Security, Access Control, Intrusion Detection Application: Coastal Security, Airport Security, Land Border Control, Smart Fencing End User: Government Agencies, Military, Private Security Firms, Customs Authorities Deployment: On-Premises, Cloud-Based, Hybrid, Remote Monitoring |
| Companies Covered | BAE Systems, RTX Corporation, Lockheed Martin, L3Harris Technologies, Elbit Systems, Northrop Grumman, Thales Group, Teledyne FLIR, General Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Border Security Technologies Market Strategic Shifts
Active sensor fusion architectures are displacing standalone detection modalities, compressing procurement from discrete hardware categories toward unified threat-intelligence platforms with embedded machine learning inference.
Hyperspectral imaging combined with synthetic aperture radar is automating target classification under degraded visibility conditions that previously required human analyst intervention. US Customs and Border Protection is accelerating field trials of these fused systems along the southwest land frontier. The technology is automating shift reductions in remote monitoring stations and compressing response times from detection to interdiction.
The EU AI Act's risk classification framework for biometric identification systems is forcing redesign of facial recognition and gait analysis modules deployed at Schengen external borders. Vendors must now demonstrate algorithmic auditability and human-in-the-loop override capabilities to achieve CE marking. Maritime entry points in Greece and Italy are experiencing the most acute compliance-driven procurement delays as authorities await certified platform availability.
Consolidated procurement through national homeland security frameworks is displacing fragmented agency-level purchasing across European interior ministries. Germany's Federal Police and France's National Gendarmerie are channeling perimeter security investments through centralized technical specifications managed by interior ministry procurement offices. This concentration is visible most acutely in Nordic countries where cross-border interoperability requirements have eliminated single-nation vendor selection autonomy.
Border Security Technologies Market Segmentation
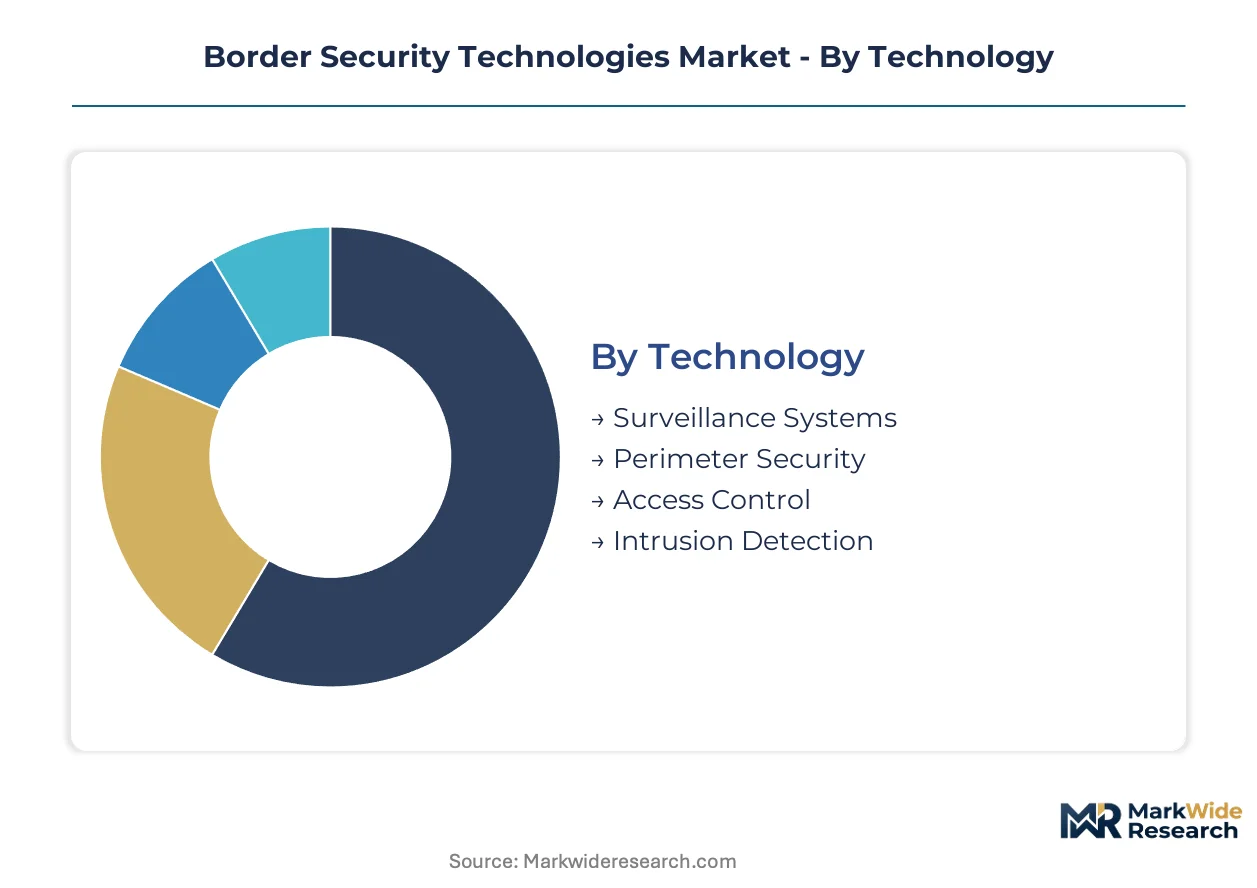
Border security procurement cycles now favor integrated platforms over discrete hardware purchases, forcing vendors to restructure offerings around recurring service models. Segmentation clarity helps identify where legacy infrastructure replacement creates immediate contract opportunities versus where emerging technologies open new addressable markets.
Technology:
Upgrade cycles favor systems that retrofit into existing command-and-control networks without full infrastructure replacement.
- Surveillance Systems:Multi-spectral imaging arrays combining electro-optical, thermal, and radar feeds deliver persistent wide-area coverage exceeding ten kilometers. Demand concentrates in US Customs and Border Protection southwest corridor modernization programs where detection range requirements under extreme heat conditions drive specification intensity.
- Perimeter Security:Autonomous ground sensors with buried seismic and magnetic detection create defensive depth without continuous aerial patrol. India's BIS-mandated domestic content thresholds are accelerating local manufacturing partnerships for thermal imaging subsystems deployed along the Pakistan and Bangladesh frontiers.
- Access Control:Biometric enrollment stations and automated gate systems process authorized crossings at high-volume land ports.
- Intrusion Detection:Fiber-optic fence-mounted sensors and ground-based radar detect tunneling and cutting attempts.
Volume placements concentrate in Surveillance Systems; the faster expansion belongs to Perimeter Security.
Application:
Deployment cost tiers separate sovereign-funded critical infrastructure from commercially operated auxiliary facilities.
- Coastal Security:Naval-integrated coastal radar and automatic identification systems monitor exclusive economic zones against smuggling and irregular maritime entry. Greece and Italy are experiencing acute procurement delays as authorities await EU AI Act-compliant biometric platforms for maritime entry point integration.
- Airport Security:Perimeter intrusion detection and runway approach monitoring systems protect civil aviation infrastructure. Germany's Federal Police channels investments through centralized interior ministry procurement specifications that mandate cross-border interoperability with neighboring Schengen states.
- Land Border Control:Vehicle and pedestrian inspection systems at official crossing points.
- Smart Fencing:Intelligent barrier systems with embedded sensor networks and automated response triggers.
Procurement volumes cluster in Land Border Control; Coastal Security is climbing the fastest as littoral zone investments extend beyond traditional port boundaries.
End User:
Customer type determines funding mechanism flexibility and contract structure preferences across capital versus operational expenditure models.
- Government Agencies:National interior ministries and homeland security departments operate integrated border management platforms with multi-year procurement frameworks. US Department of Homeland Security technical specifications for interoperable command-and-control networks require extensive protocol compliance testing that extends vendor onboarding timelines.
- Military:Defense forces deploy hardened perimeter systems in expeditionary and fixed-site configurations for forward operating bases and strategic frontier positions.
- Private Security Firms:Commercial operators manage auxiliary screening at secondary ports and industrial facility perimeters under government contract.
- Customs Authorities:Revenue collection agencies prioritize cargo inspection and contraband detection technologies at commercial entry points.
Government Agencies absorb the largest contract values; Customs Authorities are gaining share fastest through detection-as-a-service pilot programs in Germany and the United Kingdom.
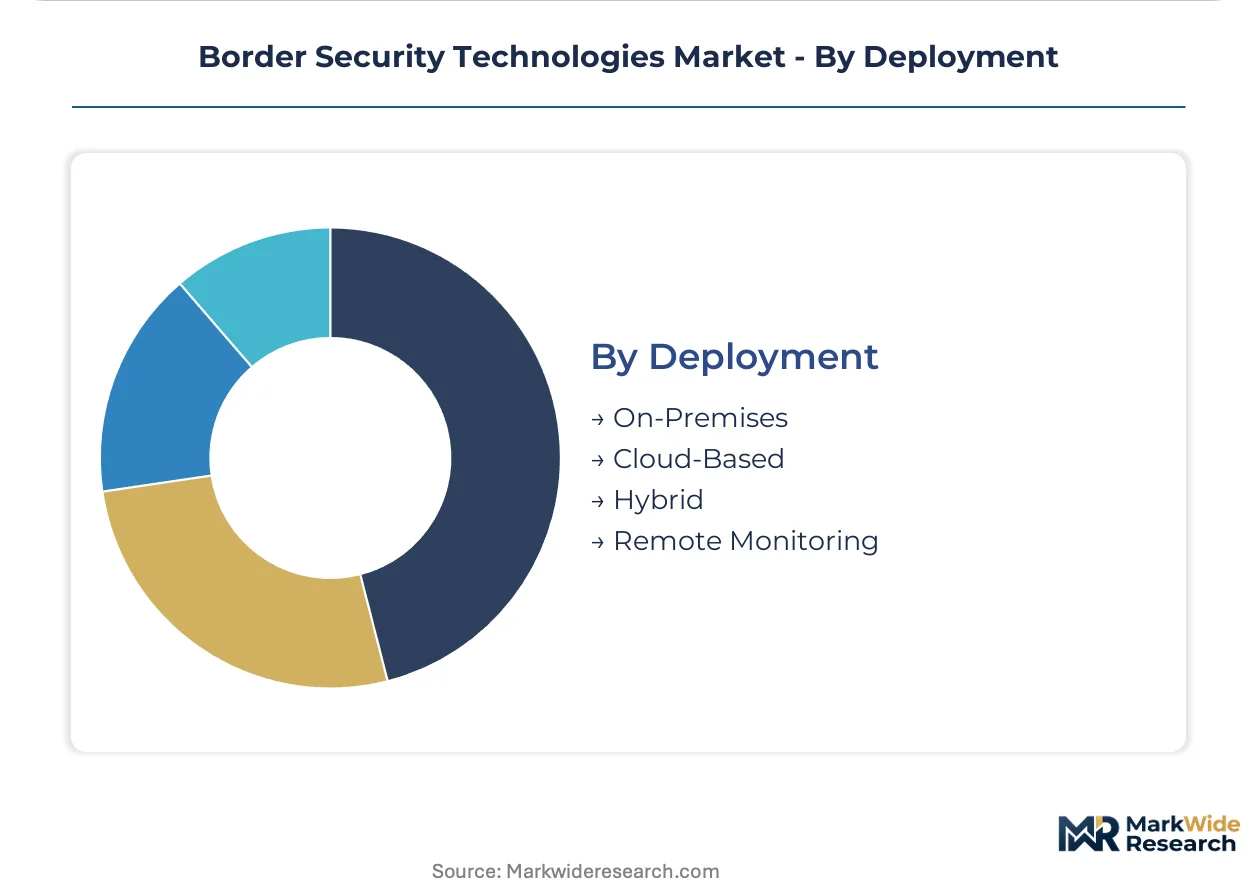
Deployment:
Maturity gradients separate established on-site infrastructure from emerging cloud architectures requiring sovereign data localization compliance.
- On-Premises:Dedicated server infrastructure and localized data storage meet stringent national security classification requirements for sensitive border intelligence. Legacy hardwired command-and-control networks at major land borders create technical debt that slows migration and drives integration costs upward for hybrid configurations.
- Cloud-Based:Centralized data fusion platforms enable multi-station coordination without capital-intensive server deployment at remote frontier posts. Conflicting national data-localization mandates complicate architecture design for intelligence-sharing networks spanning multiple sovereign jurisdictions.
- Hybrid:Edge processing with cloud analytics combines local response latency with centralized pattern recognition.
- Remote Monitoring:Distributed sensor networks with cellular or satellite backhaul for unmanned station operation.
On-Premises retains dominant installed base; Cloud-Based deployment is expanding most quickly among customs authorities seeking centralized fusion without frontier capital expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington DC anchors procurement specification development for interoperable border command networks, with technical standards radiating outward to frontier deployment zones across multiple sovereign jurisdictions.
United States
US Customs and Border Protection drives demand through southwest corridor modernization programs requiring extreme-heat detection capabilities. The Department of Homeland Security mandates protocol compliance testing that extends vendor onboarding timelines. Arizona and Texas host concentrated deployment of multi-spectral imaging arrays along the Mexico frontier.
Germany
The Federal Police channels perimeter investments through centralized interior ministry procurement offices mandating cross-border Schengen interoperability. EU AI Act compliance requirements are redesigning biometric identification modules for CE marking. Bavaria's industrial corridor supplies thermal imaging subsystems for frontier station retrofit programs.
India
The Bureau of Indian Standards enforces domestic content thresholds for critical surveillance procurement along Pakistan and Bangladesh frontiers. The Ministry of Home Affairs accelerates local manufacturing partnerships for radar and thermal subsystems. Gujarat's defense electronics cluster scales production of autonomous ground sensors for desert terrain deployment.
United Kingdom
Customs authorities pilot managed detection-as-a-service contracts shifting capital expenditure to operational budgets. The sovereign manufacturing base anchors large-scale perimeter programs across British and Commonwealth borders. Scotland's technology corridor develops edge computing platforms for remote maritime monitoring stations.
Israel
Defense forces deploy hardened perimeter systems in expeditionary configurations for strategic frontier positions. Military procurement specifications influence civilian border technology standards through dual-use technology pathways. Tel Aviv's surveillance technology cluster specializes in thermal imaging and unmanned patrol platforms for desert environments.
Border Security Technologies Market Competitive Environment
Capital-heavy producers compete with asset-light designers across integrated platform development, with sovereign manufacturing requirements and extended certification timelines favoring established defense primes over new entrants. The vendor base organizes around three strategic archetypes: systems integrators bundling hardware with analytics subscriptions, component specialists supplying thermal and radar subsystems, and platform developers focused on unmanned patrol technologies. Competitive moves concentrate on strategic partnerships for local manufacturing compliance and portfolio diversification into adjacent maritime and airport security segments.
Within the systems integrator tier, BAE Systems and Lockheed Martin occupy positions shaped by sovereign manufacturing mandates and defense procurement relationships. RTX Corporation exemplifies the component specialist archetype through dense investment in radar and electronic warfare subsystems. Elbit Systems represents the platform developer category with concentration in thermal imaging and unmanned border patrol technologies for extreme terrain environments.
| Leading Market Players |
|---|
| BAE Systems |
| RTX Corporation |
| Lockheed Martin |
| L3Harris Technologies |
| Elbit Systems |
| Northrop Grumman |
| Thales Group |
| Teledyne FLIR |
| General Dynamics |
| Others |
Value Chain & Pricing Dynamics
Sensor fusion engineering talent concentrated in Tel Aviv, Bangalore, and Bavaria creates labor-cost differentials that widen pricing-tier spreads between premium integrated platforms and commodity perimeter hardware.
Pricing Analysis
Outcome-based pricing tied to detection accuracy and interdiction response time anchors contract structures in this market. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-grade systems with full analytics subscriptions from basic hardware-only procurement. Cost compression in the standard tier is intensifying because Indian BIS localization mandates force vendors to absorb domestic manufacturing partnership overheads. Government agencies exhibit the lowest price sensitivity given multi-year procurement frameworks, while private security firms operating auxiliary screening facilities face acute budget constraints.
Supply Chain Analysis
Reverse-logistics flows for radar subsystems and thermal imaging modules concentrate refurbishment activity in the United Kingdom, Israel, and Germany. Advanced sensor processing chips for long-wave infrared and synthetic aperture radar draw from Taiwan, South Korea, and Japan. Gallium arsenide substrates, precision optics, and edge-computing processors constitute critical input dependencies. Single-source vulnerability in East Asian semiconductor foundries exposes procurement timelines to geopolitical disruption. Distribution runs through defense prime direct sales teams and national homeland security procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Border security procurement is transitioning from discrete hardware acquisition to software-defined sensor fusion platforms, with AI-enabled predictive analytics displacing legacy rule-based detection systems.
For Market Incumbents: Anchor sovereign manufacturing positions through local partnerships in India and Germany to satisfy BIS and EU domestic content thresholds. Deepen in-house production of thermal imaging subsystems to offset semiconductor supply concentration risks. Invest in CE marking and EU AI Act compliance engineering to capture Schengen biometric upgrade cycles before certified platform shortages harden competitor positions. For New Entrants and Emerging Players: Systems integrators lacking defense prime status should target customs authorities piloting detection-as-a-service contracts in the United Kingdom and Germany. Maritime frontier expansion into exclusive economic zones presents the most penetrable white space, with coastal surveillance networks underserved by incumbent land-border specialists. Pursue white-label partnerships with established radar subsystem suppliers to accelerate protocol compliance testing. For Investors and Strategic Acquirers: Re-rating potential sits with platform developers specializing in unmanned desert and maritime patrol technologies given sovereign littoral zone investment acceleration. Long-term viability favors asset-light designers with proven edge-computing inference engines over capital-heavy hardware producers facing legacy infrastructure lock-in. Monitor EU AI Act certification timelines as an inflection indicator for biometric identification module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Partnership | Indian BIS localization mandates create captive demand for locally produced thermal and radar subsystems. |
| AI Act Compliance Engineering | CE marking for biometric identification modules unlocks Schengen external border procurement delayed by regulatory redesign. |
| Detection-as-a-Service Launch | German and UK customs pilots demonstrate operational budget flexibility and multi-year vendor lock-in potential. |
| Maritime Platform Development | Coastal surveillance networks in Greece and Italy face acute procurement delays awaiting certified integrated platforms. |
| Sensor Fusion Talent Acquisition | Scarce expertise in multi-spectral data integration drives recruitment competition with autonomous vehicle developers. |
Study Parameters
Multi-period observation of procurement contract awards, regulatory filing timelines, and vendor certification status anchored the trend analysis, supplemented by interviews with homeland security procurement officers, defense prime program managers, thermal imaging subsystem engineers, and customs authority technology leads. Secondary validation drew from EU public procurement databases, US Federal Business Opportunities filings, BIS technical specification releases, and defense ministry budget appropriations. Bottom-up segment sizing triangulated against top-down sovereign spending forecasts.
Segment-weighting across technology type, deployment model, application, and end-user category shaped the analytical framework. CAGRs were derived from fitted growth curves calibrated to historical procurement cycle data and policy announcement impacts. Modeled inputs included India PLI scheme disbursement trajectories, EU Green Deal energy efficiency mandates for remote sensor arrays, and US Customs and Border Protection southwest corridor modernization schedule announcements.
Several conditions sit outside the modeled scope, including classified military procurement figures, unannounced dual-use technology export control enforcement actions, and sudden geopolitical disruptions to East Asian semiconductor supply. Practitioners should monitor EU AI Act delegated act publications and Indian BIS technical specification revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Europe Cargo Inspection Market
Physical Security
Security Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Physical Security Market
Physical Security
Airport Full Body Scanner Market
Physical Security
France Data Center Physical Security Market
Physical Security
Body Armor Plates Market
Physical Security
Active Geofencing Market
Physical Security
Smart Police Helmet Market
Physical Security
Body Armor Market
Physical Security
United States Data Center Physical Security Market
Physical Security
Tactical Vests Market
Physical Security
Europe Physical Security Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Tactical Lights Market