
 Surface Protection Services Market | 2026-2036
Surface Protection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Protection Services Market Outlook
REACH compliance is hardening the cost-of-entry calculus for European coating applicators, forcing investments in VOC-free formulation labs and certified application protocols. PPG Industries leverages its automotive OEM relationships to sustain premium positioning in machinery protection programs. BASF SE anchors its European footprint through integrated polyurethane supply chains that feed directly into industrial coating services.
Surface protection services encompass the application of engineered barrier materials—polyurethane films, epoxy coatings, PVC wraps, and Teflon sealants—to shield substrates from abrasion, corrosion, chemical attack, and environmental degradation in industrial and commercial settings. These services typically involve surface preparation, material selection based on substrate compatibility and exposure conditions, and controlled application to achieve specified thickness and adhesion parameters. Coating services dominate value generation due to recurring maintenance cycles in heavy machinery and infrastructure, while film-based protection is expanding fastest in electronics and precision glass applications where removable, residue-free barriers are critical. Wrapping services occupy a specialized niche in automotive and aerospace fleets requiring temporary transit protection.
EPA oversight of volatile organic compound emissions shapes formulation choices and application methods for US-based service providers, while REACH registration requirements in Europe constrain material portfolios and elevate documentation burdens. OSHA workplace exposure limits further dictate personal protective equipment protocols and spray booth ventilation standards during application operations. Stakeholders must monitor evolving chemical restriction lists and carbon-border adjustment mechanisms to anticipate which material classes will face phasedown pressure.
Market Dynamics
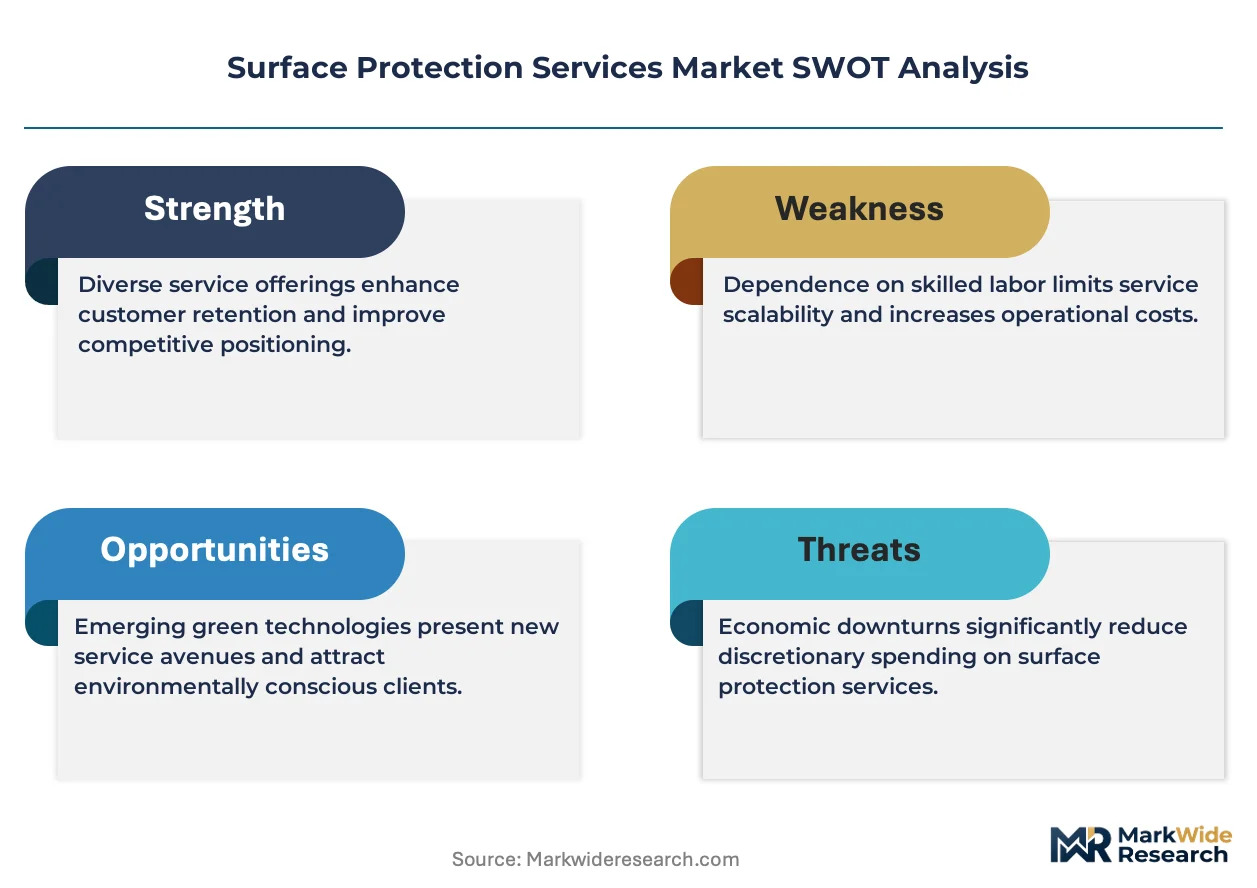
REACH registration requirements are fragmenting the European supplier base while EPA VOC rules reshape application protocols in the United States, creating divergent compliance cost structures across major demand centers.
Growth Catalysts
- Automotive OEM outsourcing:German manufacturers are contracting surface protection for production equipment maintenance, converting captive operations to third-party service relationships.
- E-waste directives:EU regulations on electronics recyclability are mandating removable protective films over permanent coatings in consumer device manufacturing.
- Polyurethane chemistry advances:Two-component waterborne systems are replacing solvent-based formulations in heavy machinery applications, extending re-coat intervals.
Market Restraints
- Isocyanate feedstock concentration:Four Asian producers control over sixty percent of MDI supply, exposing service providers to raw material volatility.
- REACH documentation burden:Substance registration costs exceed two hundred thousand euros per portfolio item, freezing SME formulation development.
- Thermal spray substitution:Plasma-deposited ceramic coatings are capturing high-temperature applications above four hundred degrees Celsius.
Strategic Opportunities
- India industrial corridor penetration:PLI scheme incentives for electronics manufacturing are creating first-mover advantages in cleanroom film application services.
- UV-cured coating convergence:Combination of LED curing arrays with robotics is enabling on-site infrastructure protection without extended downtime.
- Aviation MRO channel expansion:Airlines are unbundling protective coating programs from airframe heavy maintenance contracts.
Industry Challenges
- Certified applicator scarcity:NACE coating inspector credentials require eighteen-month training cycles, constraining service expansion.
- Legacy ERP integration:Field service management platforms must interface with decades-old manufacturing execution systems at client sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Protection Services Market |
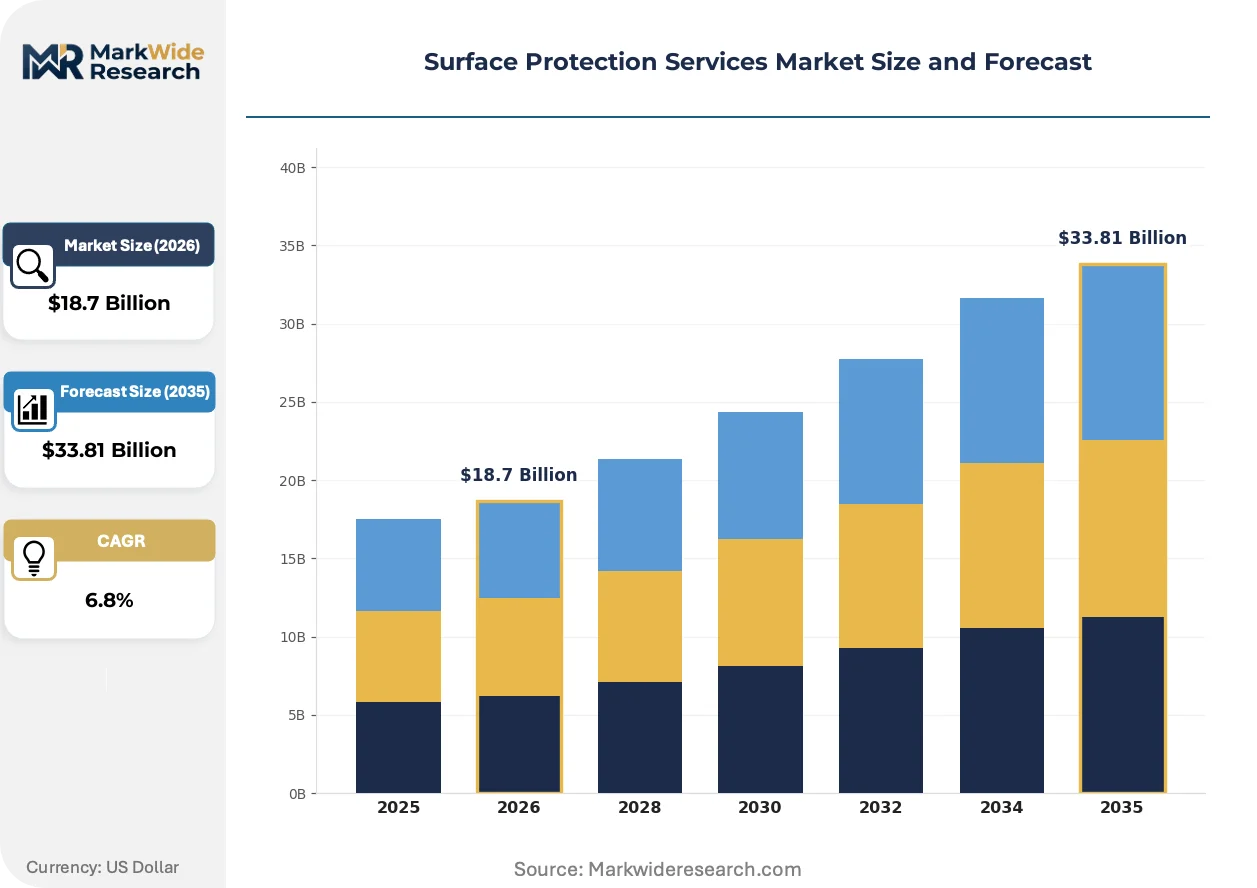
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Coating, Wrapping, Film, Sealants Industry Vertical: Aerospace, Automotive, Electronics, Construction Application: Flooring, Furniture, Glass, Machinery Material Type: Polyurethane, PVC, Teflon, Epoxy |
| Companies Covered | AkzoNobel, Nippon Paint, PPG Industries, 3M Company, BASF SE, Hempel, Sherwin-Williams, DuPont, Jotun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Protection Services Market Strategic Shifts
Digital specification tools and automated surface preparation are compressing project timelines while regulatory pressure on chemical content is accelerating formulation turnover rates across all major service categories.
Self-healing polymer networks incorporating microencapsulated repair agents are modularizing maintenance scheduling for chemical processing equipment. Refinery operators in the US Gulf Coast are piloting these systems on heat exchanger bundles. The technology is modularizing service contract structures by separating structural protection from cosmetic renewal cycles.
ECHA's 2023 restriction proposal on microplastics in coatings is forcing reformulation of textured anti-slip deck treatments. Marine and offshore service providers face eighteen-month transition windows to qualify replacement additives. Nordic shipyards are responding fastest, already specifying bio-based grip aggregates in newbuild contracts.
Specification authority is migrating from maintenance departments to procurement centers with centralized category management. Industrial facility operators are consolidating vendor panels from fifteen-plus regional applicators to three national contractors with certified QA protocols. This concentration is most visible in US pharmaceutical manufacturing, where FDA facility inspection records now weight coating contractor audit histories.
Surface Protection Services Market Segmentation
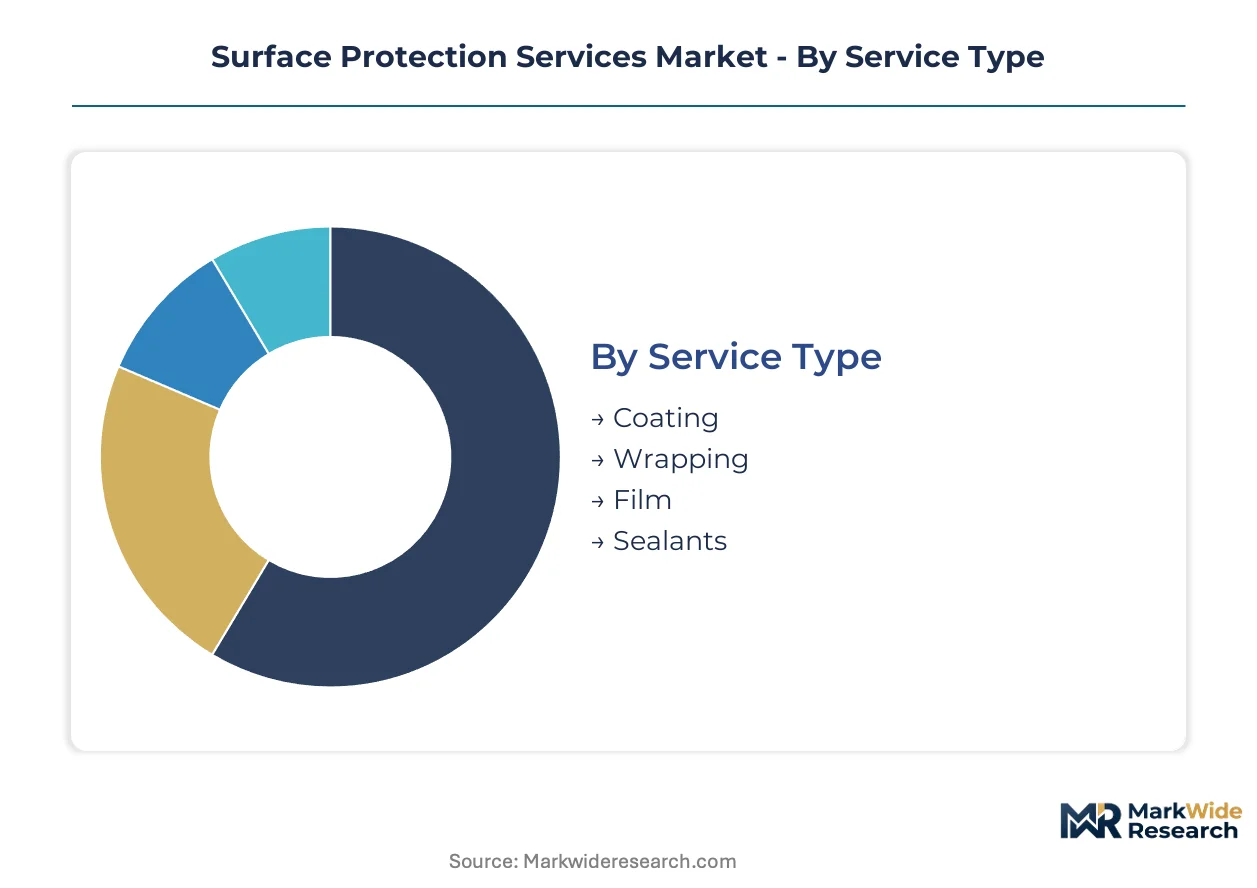
Service differentiation in surface protection hinges on substrate compatibility, exposure severity, and maintenance cycle economics. Buyers select categories based on whether protection must be permanent, removable, or reapplied at defined intervals.
Service Type:
Buyer differentiation rests on durability requirements versus reversibility needs.
- Coating:Liquid-applied barrier systems cure into permanent films with specified thickness and adhesion parameters. Demand concentrates in German automotive OEM equipment maintenance programs, where recurring heavy machinery re-coat cycles generate predictable revenue streams. REACH registration requirements are fragmenting European formulation portfolios.
- Film:Pre-manufactured polymer sheets applied with pressure-sensitive adhesives enable residue-free removal. Electronics manufacturers in India's PLI-subsidized corridors are driving cleanroom film adoption for precision glass and display substrates ahead of final assembly.
- Wrapping:Temporary transit protection for automotive and aerospace fleets requiring damage prevention during logistics. Airlines unbundling protective programs from heavy maintenance contracts are expanding this segment.
- Sealants:Gap-filling compounds providing environmental sealing alongside surface protection. Refinery operators on the US Gulf Coast specify these for heat exchanger bundles in chemical processing environments.
Volume sits with Coating; growth tilts toward Film.
Industry Vertical:
End-use concentration determines specification authority and contract structure.
- Aerospace:Protective coating programs tied to airframe heavy maintenance cycles. North American MRO expansion is converting bundled services into standalone contracts with certified QA protocols.
- Automotive:Production equipment protection outsourced from captive operations. German manufacturers in the industrial corridor are leading this conversion to third-party service relationships.
- Electronics:Removable barriers mandated by EU e-waste recyclability directives. Consumer device manufacturing specifies films over permanent coatings to satisfy disassembly requirements.
- Construction:Infrastructure and flooring applications requiring on-site application without extended downtime. UV-cured systems with LED curing arrays are penetrating this segment.
Revenue concentrates in Automotive; specification authority migrates fastest in Electronics.
Application:
Substrate geometry and exposure conditions dictate material selection and application method.
- Machinery:Abrasion and chemical attack protection for heavy industrial equipment. Two-component waterborne polyurethane systems are displacing solvent-based formulations, extending re-coat intervals in processing plants.
- Glass:Precision substrates in electronics manufacturing requiring scratch resistance without optical distortion. Cleanroom application protocols in Indian electronics corridors are creating certified service capacity.
- Flooring:Anti-slip and wear-resistant treatments for commercial and industrial facilities. ECHA's microplastics restriction is forcing eighteen-month reformulation timelines for textured deck treatments in marine applications.
- Furniture:Cosmetic and functional protection for high-value wood and metal surfaces. Self-healing polymer networks with microencapsulated repair agents are modularizing maintenance scheduling.
Contract value peaks in Machinery; technology turnover runs highest in Flooring.
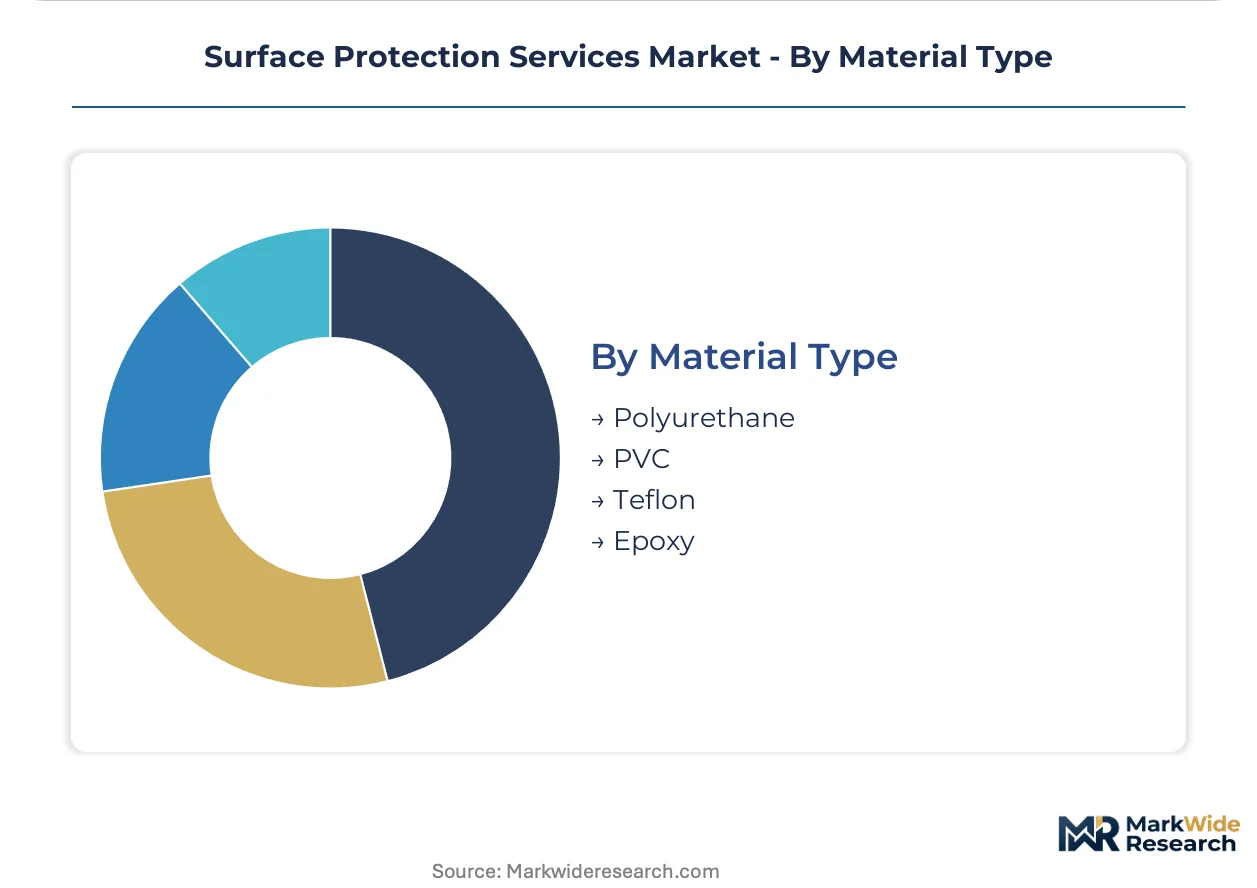
Material Type:
Supply chain positioning and regulatory compliance burden shape material economics.
- Polyurethane:Two-component systems dominating heavy machinery and industrial applications. Four Asian producers controlling over sixty percent of MDI feedstock expose service providers to raw material volatility.
- Epoxy:High-adhesion thermoset systems for chemical-resistant environments. Integrated supply chains from polyurethane producers anchor European service provider competitiveness.
- PVC:Cost-effective film and wrapping substrates with established application protocols. EU chemical restriction lists are elevating documentation burdens for plasticizer content.
- Teflon:Fluoropolymer sealants for extreme temperature and chemical exposure. Plasma-deposited ceramic coatings are capturing applications above four hundred degrees Celsius.
Supply concentrates in Polyurethane; substitution pressure mounts fastest against Teflon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for electronics manufacturing is concentrating cleanroom film demand in Karnataka and Tamil Nadu corridors. German automotive OEMs in the industrial belt are outsourcing equipment protection services at accelerating rates. EPA VOC enforcement and REACH registration burdens are fragmenting supplier bases in North America and Europe respectively.
United States
Petrochemical refineries on the US Gulf Coast are piloting self-healing polymer networks for heat exchanger protection. EPA oversight of volatile organic compound emissions shapes formulation choices and spray booth ventilation standards for service providers. Houston-area applicators are consolidating to meet pharmaceutical manufacturer QA protocol requirements.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria are converting captive surface protection operations to third-party contracts. EU REACH registration requirements exceed two hundred thousand euros per substance portfolio item, freezing SME formulation development. The Rhine-Main industrial corridor anchors BASF SE's integrated polyurethane supply chains feeding directly into coating services.
China
Four Asian producers control over sixty percent of MDI feedstock for polyurethane systems, exposing service providers to raw material volatility. The country's national chemical regulator maintains substance registration protocols that constrain imported formulation portfolios. Yangtze River Delta manufacturing clusters are driving demand for electronics-grade protective films.
India
PLI scheme incentives for electronics manufacturing are creating first-mover advantages in cleanroom film application services. Bureau of Indian Standards certification requirements elevate documentation burdens for coating contractors serving export-oriented units. Karnataka's electronics manufacturing clusters near Bangalore are certifying precision glass protection capacity ahead of display substrate demand.
Japan
Automotive and electronics manufacturers specify removable protective films to satisfy disassembly requirements under extended producer responsibility frameworks. Ministry of Economy, Trade and Industry guidelines on chemical substance management influence coating formulation selections. Kansai region industrial facilities are outsourcing machinery protection to certified applicator networks.
Surface Protection Services Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered service categories. The market structure shows moderate consolidation at the formulation level alongside fragmentation among regional applicators. Strategic archetypes include integrated chemical producers with captive coating services, independent application specialists with certified QA protocols, and film distributors expanding into installation services. Dominant competitive moves involve M&A to acquire certified applicator networks and strategic partnerships to secure MDI feedstock allocations.
Within the integrated chemical producer tier, BASF SE and PPG Industries represent archetypes of upstream-controlled service models. BASF SE anchors European competitiveness through captive polyurethane supply chains. PPG Industries exemplifies automotive OEM relationship leverage sustaining premium positioning in machinery protection programs. Among diversified materials conglomerates, 3M Company and DuPont occupy positions spanning film manufacturing through application technology licensing. AkzoNobel and Nippon Paint represent regional formulation leaders expanding service footprints beyond their home markets.
| Leading Market Players |
|---|
| AkzoNobel |
| Nippon Paint |
| PPG Industries |
| 3M Company |
| BASF SE |
| Hempel |
| Sherwin-Williams |
| DuPont |
| Jotun |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between NACE-certified applicators and uncertified regional operators splits both pricing power and supply chain access in surface protection services. Premium-tier providers command project premiums through eighteen-month credentialing cycles that lock out competitors from pharmaceutical and aerospace contracts, while commodity applicators compete on spot pricing for industrial maintenance with minimal barrier to entry.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid-response capacity with project premiums, while extended scheduling windows trade price discounts for planning certainty. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and QA protocol rigor rather than material cost alone. Cost compression in standard-tier machinery protection is intensifying because REACH-compliant formulation portfolios require dedicated lab investments. Pharmaceutical manufacturers show least price sensitivity given FDA audit history requirements, while construction contractors drive hardest bargain negotiations.
Supply Chain Analysis
Qualification gating through MDI feedstock allocation agreements and REACH registration credentials determines supplier tier access. Supply concentrates in China, Germany, and the United States for polyurethane systems, epoxy resins, and precision film substrates. Raw material portfolios draw from MDI isocyanates, two-component waterborne polymers, and pressure-sensitive adhesive backings. Single-source vulnerability runs through four Asian producers controlling majority MDI supply. Distribution runs through certified applicator networks with direct OEM contracting relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface protection services represent a consolidation play where REACH documentation burdens and certified applicator scarcity force weaker regional operators toward exit or acquisition.
For Market Incumbents: Lock in MDI feedstock allocation agreements with Asian producers before capacity constraints tighten. Acquire NACE-certified applicator networks in pharmaceutical corridors to defend against thermal spray substitution in high-temperature applications. Prioritize backward integration into waterborne polyurethane formulation to capture margin from REACH-compliant product shifts. For New Entrants and Emerging Players: UV-cured coating convergence with LED curing arrays offers technology-first wedge into infrastructure construction where downtime sensitivity blocks incumbent penetration. Target India's PLI-subsidized electronics corridors for cleanroom film application services ahead of display substrate demand maturation. Lead with robotics-enabled on-site deployment to bypass certified applicator scarcity constraints. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier applicator networks possessing NACE credentials but lacking national coverage, given specification authority migration to procurement centers with consolidated vendor panels. Long-term viability favors targets with pharmaceutical or aerospace QA protocols already embedded. Watch for ECHA microplastics restriction enforcement timelines as inflection indicator for bio-based additive formulation pivots.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstock | Captures margin from four-producer concentration in Asian isocyanate supply. |
| NACE-Certified Applicator Acquisition | Secures eighteen-month credentialing barrier against regional competitors. |
| UV-Cured Coating Robotics Deployment | Enables infrastructure penetration without extended downtime penalties. |
| REACH-Compliant Formulation Lab Investment | Unlocks pharmaceutical and aerospace contract access requiring audit histories. |
| PLI Corridor Cleanroom Film Capacity | Positions ahead of Karnataka and Tamil Nadu electronics manufacturing clusters. |
Study Parameters
Independent corroboration across plant maintenance directors, OEM procurement leads, coating formulation R&D heads, and certified applicator network managers underwrites the qualitative findings. Secondary validation draws from customs trade data for coating chemical flows, ECHA substance restriction proposals, SEC filings from integrated chemical producers, and pharmaceutical facility FDA inspection records. Bottom-up service provider capacity estimates triangulate against top-down end-use demand modeling across machinery protection, electronics film, and aerospace coating programs.
Comparable-period anchoring to historical maintenance cycle frequencies and outsourcing conversion rates in German automotive OEMs establishes the forecast baseline. Segmentation dimensions span service type, material chemistry, industry vertical, and application substrate across the modeling period. CAGRs derive from regression against industrial capital expenditure cycles and regulatory phase-in timelines. Forecast inputs incorporate PLI scheme electronics manufacturing projections and REACH registration cost escalation curves.
Several conditions sit outside the modeled scope, including unannounced ECHA substance restrictions, MDI producer capacity expansion decisions, and aviation MRO contract unbundling velocity. Forecasts reflect documented assumptions about certified applicator training pipeline throughput and formulation lab qualification timelines. A model refresh is warranted upon material change in ECHA microplastics restriction enforcement or Asian MDI feedstock allocation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Tube and Dressing Securement Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market