
 Boat Trolling Motor Market | 2026-2036
Boat Trolling Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Trolling Motor Market Insights
Composite polymer housings are expanding their share in trolling motor construction as manufacturers seek weight reduction and corrosion resistance against traditional aluminum and steel assemblies. Minn Kota leverages vertical integration across motor winding and propeller casting to control cost structures in the premium segment. Garmin anchors its position through integrated GPS trolling systems that merge navigation with autopilot functionality. MotorGuide competes aggressively on price-performance ratios in the freshwater tournament angler channel.
A boat trolling motor is an auxiliary marine propulsion unit designed for slow, precise maneuvering at speeds typically below five knots, employing electric DC motors rated from 30 to 160 pounds of thrust with shaft lengths calibrated to hull freeboard. These systems enable hands-free boat positioning for anglers and silent operation to avoid spooking fish. Electric type motors dominate unit sales while brushless technology captures the fastest expansion due to thermal efficiency and extended runtime. Individual anglers represent the deepest end-user pool, though charter services concentrate margin pools through fleet replacement schedules and bundled electronics packages.
The United States Coast Guard enforces electrical system standards for marine propulsion equipment under 33 CFR regulations, while the EPA oversees battery disposal and watershed protection rules affecting electric motor adoption near sensitive habitats. California Air Resources Board restrictions on gas-powered outboard emissions indirectly channel demand toward electric trolling alternatives in the state's inland waterways. Stakeholders must weigh lithium supply chain exposure against the durability advantages of brushless architectures as tournament formats and rental fleets accelerate electrification requirements.
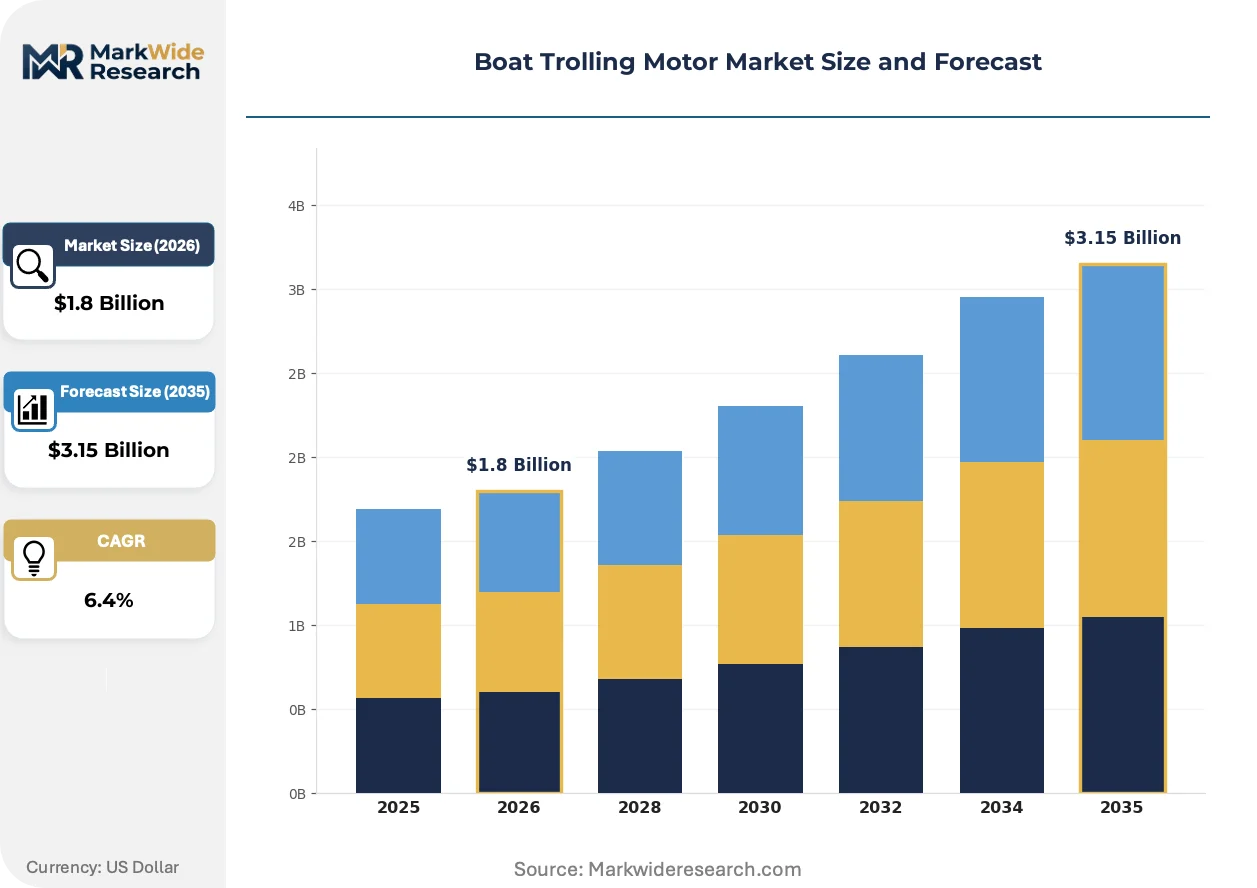
Market Dynamics
Brushless motor architecture is compressing replacement cycles across the freshwater tournament circuit as lithium-ion energy density improvements enable extended runtime without weight penalties. This technology migration is restructuring supplier economics and procurement patterns simultaneously.
Growth Catalysts
- Freshwater bass tournaments:Competitive angling formats in the United States mandate precise boat positioning, driving fleet-wide upgrades to GPS-integrated trolling systems.
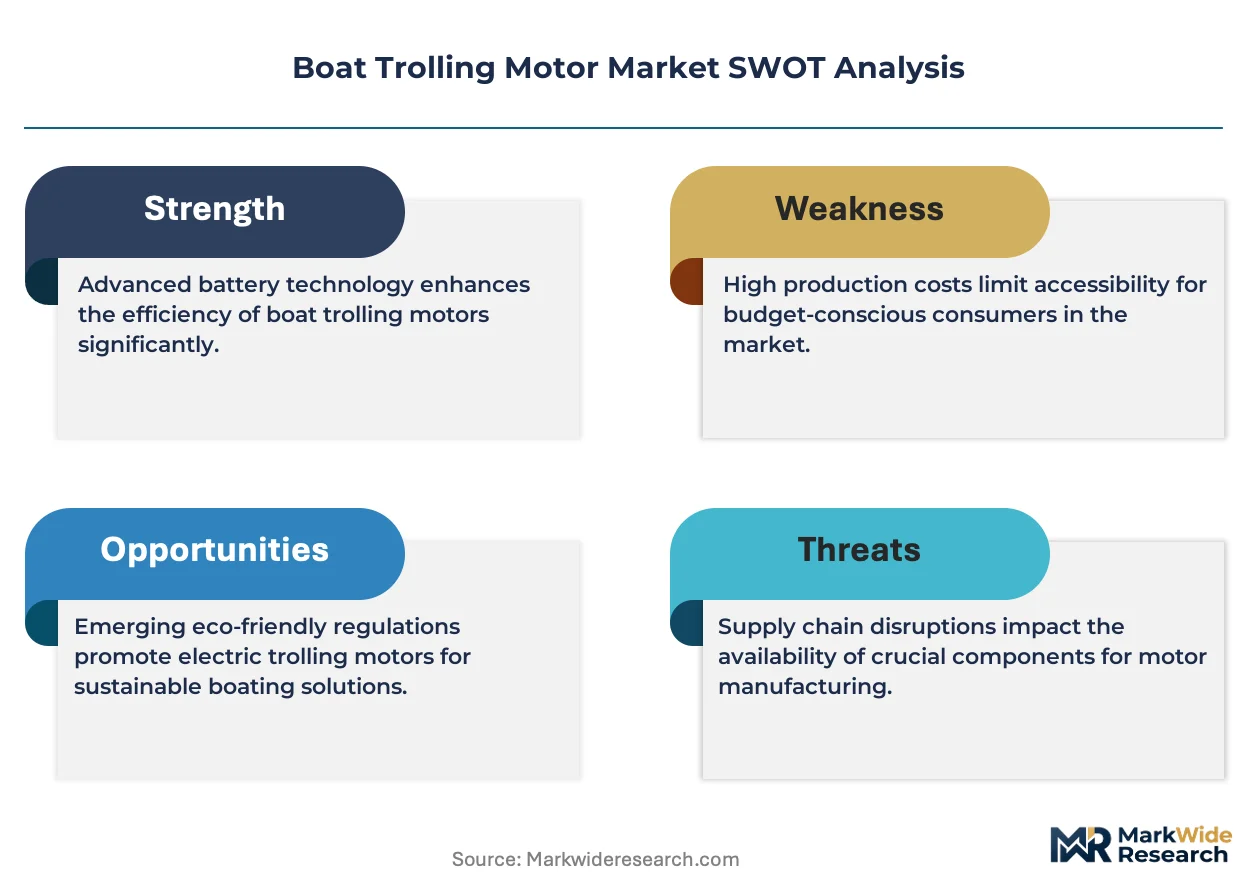
- 33 CFR electrical standards:Coast Guard regulations for marine propulsion equipment create compliance baselines that favor established electric motor architectures over unproven alternatives.
- Lithium-ion chemistry advances:Improved energy density in battery packs extends runtime per charge, reducing angler anxiety about power depletion during extended fishing sessions.
Market Restraints
- Lithium supply chain concentration:Cathode material processing concentrates in limited geographic corridors, exposing manufacturers to input volatility and export restriction risk.
- California Air Resources Board emissions rules:Restrictions on gas-powered outboards in inland waterways indirectly channel demand, yet create compliance documentation burdens for electric alternatives seeking certification.
- Shaft length calibration complexity:Hull freeboard variation across boat classes forces inventory proliferation, compressing margin on lower-volume shaft configurations.
Strategic Opportunities
- Charter service fleet electrification:Coastal operators in Florida and Texas face mounting pressure to reduce noise signatures and fuel costs, creating bundled electronics package demand.
- Composite polymer housing adoption:Weight reduction and corrosion resistance advantages over aluminum assemblies open premium positioning in saltwater applications.
- EPA watershed protection rules:Battery disposal regulations near sensitive habitats accelerate electric motor adoption as anglers seek equipment aligned with conservation access requirements.
Industry Challenges
- Motor winding technician scarcity:Brushless architecture requires specialized assembly skills that outpace vocational training pipeline output in manufacturing clusters.
- GPS-autopilot integration complexity:Navigation system convergence demands firmware coordination across marine electronics vendors, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Trolling Motor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric, Gas-powered, Hybrid, Hand-operated Application: Fishing, Recreational, Commercial, Professional Technology: Brushless, Gear-driven, Direct Drive, Integrated GPS End User: Individual Anglers, Rental Shops, Charter Services, Military |
| Companies Covered | Minn Kota, Garmin, Lowrance, MotorGuide, Power-Pole, Newport, Yamaha Motor, Brunswick Corporation, Honda Motor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Trolling Motor Market Trends and Innovations
Silent propulsion technology is reshaping competitive angling equipment specifications while regulatory pressure on combustion alternatives accelerates electric architecture investment. Three convergent developments are restructuring supplier priorities and buyer expectations.
Brushless DC motor technology is electrifying tournament-grade trolling motor design by eliminating brush friction losses and thermal degradation points. Competitive anglers operating in Texas and Florida freshwater circuits are specifying these architectures for extended practice-day endurance. The technology is electrifying supplier R&D allocation, compressing development timelines for brushed motor legacy platforms.
EPA battery disposal regulations under watershed protection frameworks are mandating closed-loop recycling infrastructure for lithium-ion packs used in electric propulsion. Manufacturers must now integrate reverse logistics partnerships into distribution contracts or face access restrictions to sensitive water bodies. Tournament organizers in coastal southeastern states are responding by requiring equipment compliance documentation as a condition of entry.
Rental fleet operators are consolidating procurement decisions through centralized electronics bundling rather than piecemeal motor replacement. This buyer concentration shifts margin capture toward integrated system vendors capable of delivering GPS-autopilot-motor packages. The pattern is most visible in Florida charter services, where fleet owners negotiate multi-unit replacement schedules with bundled warranty terms.
Boat Trolling Motor Market Segmentation
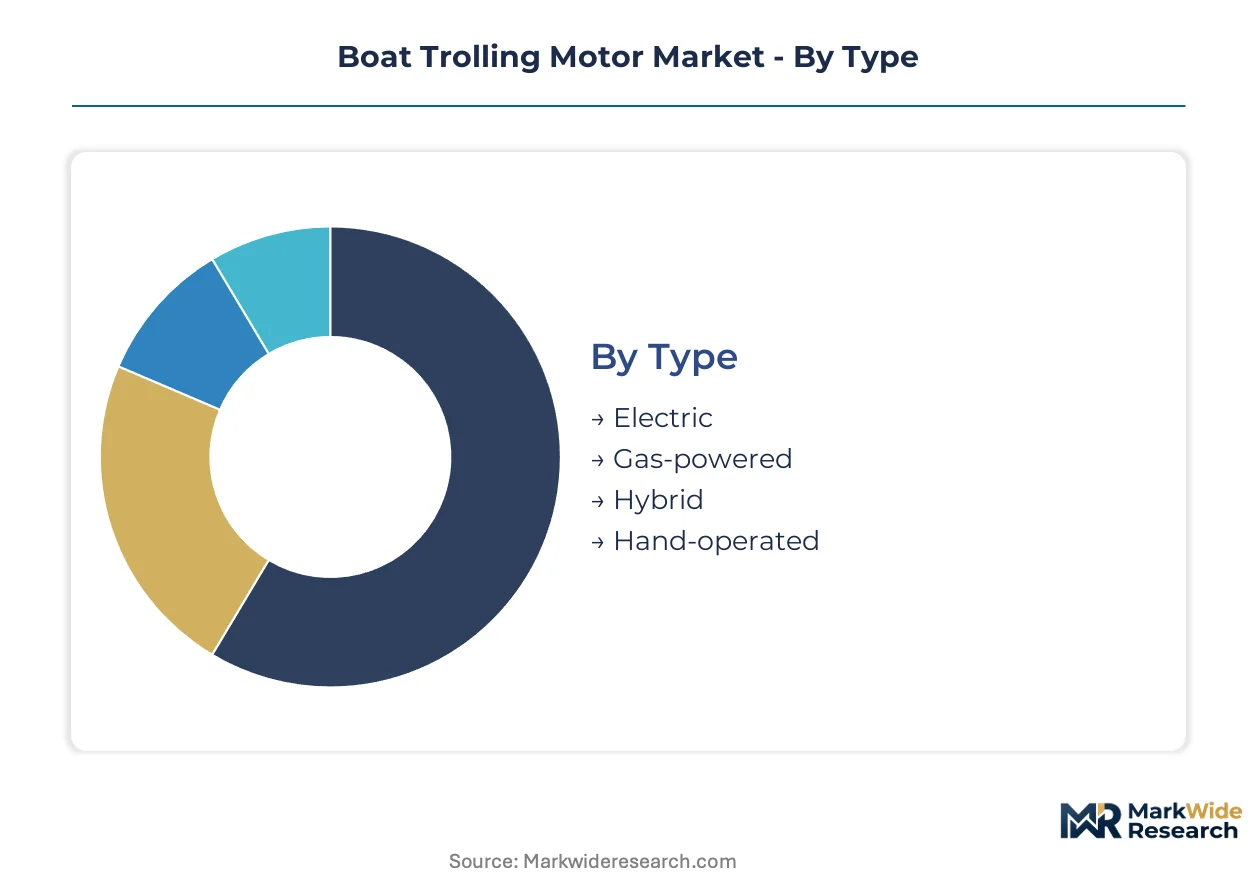
Trolling motor purchasing decisions split across propulsion architecture, use intensity, and operator sophistication. Each segmentation axis reveals distinct margin structures and replacement cycle dynamics that suppliers must navigate.
Type:
Propulsion chemistry defines the fundamental cost-reliability tradeoff that buyers confront at the point of sale.
- Electric:DC motor systems powered by lithium-ion or lead-acid battery banks deliver silent operation below five knots with thrust ratings from 30 to 160 pounds. Tournament circuits in Florida and Texas specify electric architectures for stealth requirements, though lithium supply concentration creates procurement volatility for fleet operators.
- Gas-powered:Small internal combustion engines provide extended range without battery weight penalties, appealing to offshore operators running multiple lines in deep-water conditions. California Air Resources Board restrictions on gas outboard emissions are compressing addressable market scope for this architecture in sensitive watersheds.
- Hybrid:Dual-mode systems switch between electric precision maneuvering and combustion endurance for extended trips.
- Hand-operated:Manual paddle or sculling mechanisms serve emergency backup roles and ultra-light craft where electrical system weight is prohibitive.
Mature deployment sits with gas-powered motors in commercial offshore settings. Newer deployment is concentrated in electric systems across competitive freshwater circuits.
Application:
Use-case intensity determines durability specifications and electronics integration depth.
- Fishing:Angling applications demand precise boat positioning with GPS anchor functionality and variable speed control for drift management. Bass tournament formats in the southeastern United States mandate hands-free operation that drives brushless motor upgrades and integrated autopilot specification.
- Recreational:Casual cruising and family boating prioritize simplicity and cost containment over precision features, with shorter shaft lengths dominating inventory for runabout hulls.
- Commercial:Charter fleets and guide services require continuous-duty ratings with redundant systems and centralized fleet management capabilities.
- Professional:Law enforcement and survey applications specify ruggedized housings and encrypted communications integration.
Volume concentrates in recreational use. Margin capture climbs fastest in fishing applications with bundled electronics packages.
Technology:
Motor architecture and control system integration define performance differentiation and thermal efficiency boundaries.
- Brushless:Permanent magnet synchronous motors eliminate brush friction losses and commutator maintenance intervals, extending runtime per battery charge by 15-30% over brushed equivalents. Competitive anglers in Texas and Florida specify brushless systems for multi-day tournament practice schedules where thermal degradation would compromise positioning precision.
- Gear-driven:Reduction gearboxes multiply torque output for high-thrust applications in heavy-current conditions, though mechanical complexity increases service intervals.
- Direct Drive:Propeller shaft coupling without intermediate gearing reduces parts count and noise signature for stealth-critical applications.
- Integrated GPS:Navigation system convergence enables autopilot waypoint following and virtual anchoring through geofenced position holding.
Gear-driven systems retain installed base in heavy-displacement hulls. Brushless architectures are climbing the fastest across tournament-grade replacement cycles.
End User:
Buyer concentration and procurement sophistication shape pricing power and warranty term negotiation.
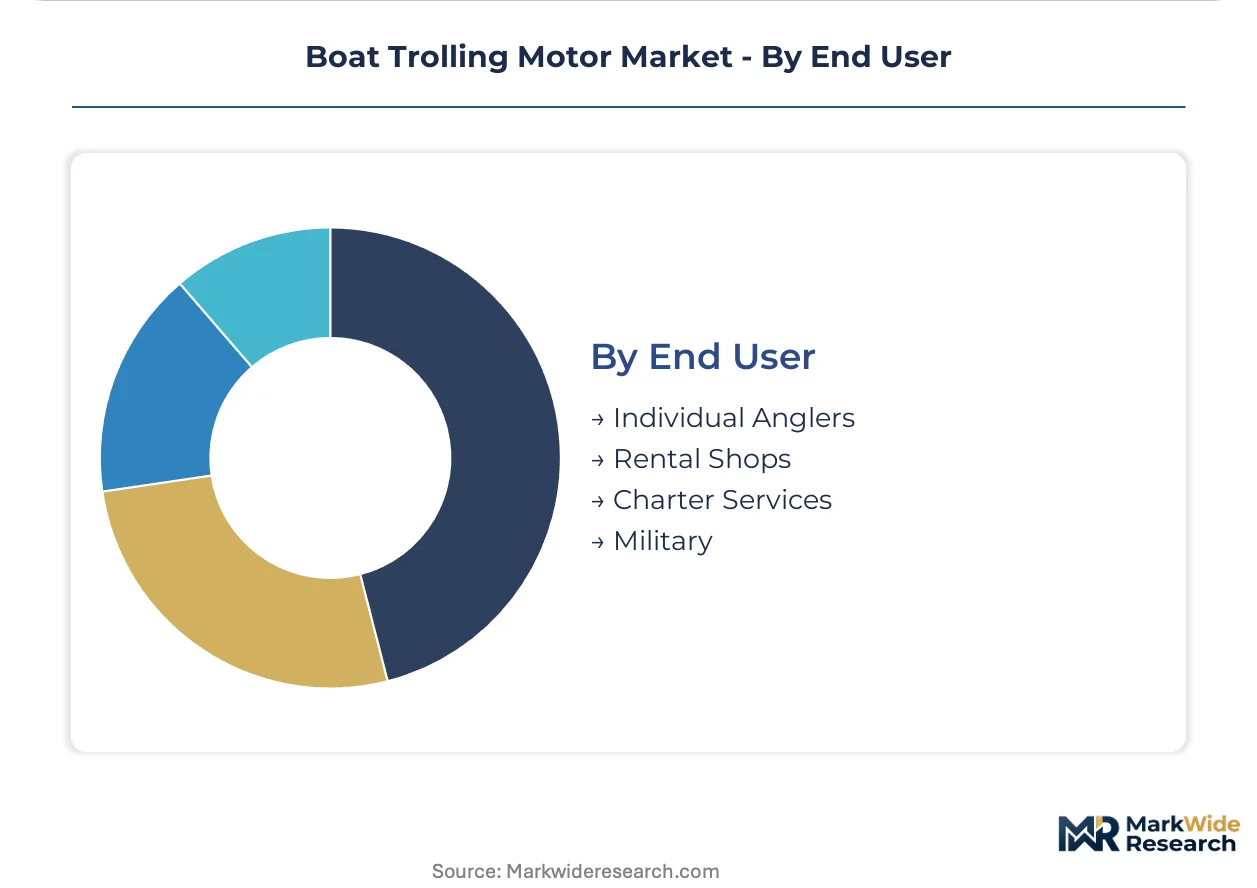
- Individual Anglers:Dispersed consumers purchase through retail channels with piecemeal replacement timing, though tournament participation elevates specification awareness and brand loyalty in competitive segments.
- Rental Shops:Fleet operators prioritize durability and standardized maintenance protocols over feature depth, with seasonal demand concentration in Great Lakes and coastal southeastern states.
- Charter Services:Coastal operators in Florida and Texas negotiate multi-unit procurement with bundled electronics packages and extended warranty terms, consolidating margin toward integrated system vendors capable of GPS-autopilot-motor coordination.
- Military:Special operations and riverine units specify silent propulsion with electromagnetic signature suppression and rapid deployment mounts.
Fragmented purchasing characterizes individual anglers. Procurement consolidation is accelerating fastest in charter services with fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freshwater bass tournaments and year-round coastal fishing seasons concentrate replacement demand in the United States, with secondary clusters forming in Canada and select European markets where recreational angling infrastructure supports premium motor adoption.
United States
Competitive angling circuits in Florida and Texas drive brushless motor upgrades through GPS-integrated procurement mandates. The EPA enforces watershed protection rules that accelerate electric motor adoption near sensitive habitats. Manufacturing clusters in the upper Midwest supply motor winding and propeller casting capacity to domestic OEMs.
Canada
Great Lakes charter operators and rental fleets sustain seasonal demand concentration in Ontario and Quebec. Health Canada regulates battery disposal protocols for lithium-ion packs used in marine propulsion. Toronto-area distributors coordinate cross-border procurement with US tournament equipment suppliers.
Germany
Recreational boating on Bavarian lakes and North Sea coastal waters supports modest electric trolling motor penetration. The ECHA administers REACH compliance for composite polymer housings and marine electronics materials. Hamburg marine equipment wholesalers serve Scandinavian export demand through Baltic distribution channels.
Australia
Estuary fishing and reef angling in Queensland and New South Wales generate demand for corrosion-resistant saltwater-rated systems. The TGA oversees electrical safety standards for marine propulsion equipment through alignment with IEC frameworks. Sydney-based charter consolidators negotiate fleet replacement schedules with bundled warranty terms.
Japan
Rocky shore fishing and inland reservoir angling sustain niche demand for precision maneuvering systems. METI promotes battery technology development through industrial policy coordination with marine equipment manufacturers. Osaka industrial zones supply precision motor components to regional OEM assembly operations.
Boat Trolling Motor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium GPS-integrated systems consolidating around vertically integrated marine electronics houses while price-sensitive freshwater tournament channels fragment across motor-focused suppliers. The structure tiers into three archetypes: navigation-convergent system integrators, thrust-optimized motor specialists, and offshore combustion-equipment incumbents with electric line extensions. Capacity expansion and backward integration into battery pack assembly represent the dominant competitive moves reshaping procurement economics.
Among US-based marine electronics houses, Minn Kota and Garmin occupy positions that exemplify the navigation-convergent archetype through GPS-autopilot integration, while MotorGuide represents the thrust-optimized specialist tier focused on freshwater tournament price-performance positioning.
| Leading Market Players |
|---|
| Minn Kota |
| Garmin |
| Lowrance |
| MotorGuide |
| Power-Pole |
| Newport |
| Yamaha Motor |
| Brunswick Corporation |
| Honda Motor |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in the upper Midwest anchor motor winding and propeller casting capacity, creating pricing discipline through captive supply of critical components while tournament-grade GPS-integrated systems command premium positioning through bundled electronics packages.
Pricing Analysis
Volume concentrates in recreational-grade electric motors with shorter shaft lengths, while margin capture climbs fastest in fishing applications where brushless architectures and integrated autopilot functionality separate premium tiers from standard offerings. Pricing stratifies across tournament-certified, recreational, and rental fleet tiers, with differentiation driven by thrust rating precision and GPS integration depth. Cost compression in the standard tier intensifies because lithium supply chain volatility compresses procurement economics for fleet operators. Charter services in Florida and Texas exhibit the lowest price sensitivity due to bundled procurement schedules, whereas individual anglers purchasing through retail channels face the highest price sensitivity.
Supply Chain Analysis
Domestic-content mandates under the Inflation Reduction Act are reshaping sourcing patterns for battery pack assembly, pressuring manufacturers to relocate cathode material processing and final motor integration to US-based facilities. Motor winding capacity draws from the upper Midwest, propeller casting feeds from coastal southeastern clusters, and lithium-ion cell production rests on South Korean and Japanese suppliers. Neodymium magnet supply hinges on Chinese processing corridors, creating single-source vulnerability for permanent magnet brushless architectures. Distribution runs through marine electronics wholesalers serving tournament circuits and direct OEM relationships with charter fleet consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into battery pack assembly and motor winding capacity represents the decisive competitive lever, with players racing to secure captive lithium supply and in-house brushless motor production to defend margin structures against supply volatility.
For Market Incumbents: Anticipate lithium supply chain concentration by securing long-term offtake agreements with cathode material processors or acquiring winding technician training pipelines to address brushless assembly bottlenecks. GPS-autopilot integration complexity from marine electronics vendors threatens certification timelines, making firmware coordination capabilities a critical defensive investment. Control over shaft length inventory proliferation through modular platform architectures preserves margin on lower-volume configurations. For New Entrants and Emerging Players: EPA watershed protection rules in the United States open a window for conservation-aligned positioning in sensitive habitat access markets where compliance documentation creates barriers for legacy gas-powered alternatives. The rental fleet channel in Great Lakes states offers the most penetrable entry point due to seasonal demand concentration and standardized maintenance protocol requirements. A direct-to-charter-service model bypassing wholesale distribution layers captures bundled procurement decisions in Florida and Texas coastal markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor brushless motor specialists with established winding technician pipelines in the upper Midwest manufacturing clusters. Long-term viability centers on lithium supply chain resilience and GPS integration firmware capabilities rather than pure thrust optimization. Watch EPA battery disposal enforcement intensity as the inflection indicator for electric motor adoption acceleration near sensitive water bodies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captive lithium supply hedges cathode material volatility from South Korean processors. |
| Brushless Motor Platform Standardization | Modular architectures compress shaft length inventory proliferation across hull classes. |
| GPS-Autopilot Firmware Coordination | Navigation system convergence accelerates tournament-grade certification timelines. |
| Composite Polymer Housing Adoption | Corrosion-resistant saltwater positioning opens premium tier in Florida coastal markets. |
| Reverse Logistics Partnership Development | Closed-loop recycling infrastructure satisfies EPA watershed protection compliance mandates. |
Research Methodology
Multi-period observation of tournament procurement schedules, lithium contract pricing, and brushless motor adoption rates anchored the trend analysis, supplemented by interviews with motor winding technicians, charter fleet procurement managers, marine electronics distributors, and EPA compliance officers. Secondary validation drew from Coast Guard 33 CFR regulatory filings, EPA watershed protection enforcement records, lithium trade customs data, and marine electronics vendor SEC disclosures. Bottom-up unit shipment estimates across thrust ratings and shaft lengths triangulated against top-down fleet replacement value projections.
Input-output matrices mapped battery energy density improvements to runtime extension values and GPS integration depth to premium pricing capture across the projection horizon. Segmentation dimensions modeled include propulsion architecture, use intensity tier, motor technology type, and end-user procurement sophistication. CAGRs were derived through logistic diffusion curves for brushless adoption and replacement cycle elasticity functions for fleet operators. Forecast inputs incorporated lithium supply contract renewal patterns and tournament format electrification mandates.
Caveats apply where lithium export restrictions, Coast Guard electrical standard revisions, or GPS-autopilot certification delays could materially shift the outlook. Forecasts reflect documented assumptions about battery chemistry evolution and tournament participation growth. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Sea Skimmer Market
Marine
Marine Gas Oil Market
Marine
Hydrogen Ships Market
Marine
Boat Steering Systems Market
Marine
Marine Transport Refrigeration Unit Market
Marine
Fishing Vessel Market
Marine
Shipbuilding Market
Marine
Swamp Boat Market
Marine
Marine Growth Removal Tool Market
Marine
Marine Elevators Market
Marine
Deep-V Boat Market
Marine
Furnace Boats Market
Marine
Hybrid Fishing Boats Market
Marine
Marine Communication Market
Marine
Marine Beacon Market
Marine
Autonomous Ships Market