
 Trolling Motor Market | 2026-2036
Trolling Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Trolling Motor Market Outlook
Market Context
Subscription-based sonar and GPS software layers is restructuring how manufacturers monetize trolling motor ownership beyond the hardware sale. Minn Kota leverages its extensive dealer network to sustain aftermarket parts availability across remote fishing regions. Garmin anchors its position through integrated chartplotter-motor ecosystems that reduce switching costs for boat owners. MotorGuide specializes in freshwater tournament configurations that dominate competitive angling circuits.
Technical Definition and Segment Structure
A trolling motor is an electric or fuel-powered auxiliary propulsion unit mounted on a watercraft bow, transom, or outboard engine, typically rated between 12 and 36 volts DC with thrust outputs from 30 to 150 pounds for precise low-speed maneuvering during fishing or docking operations. Bow mount configurations command premium positioning due to superior boat control in wind and current, while brushless motor technology captures the fastest expansion as manufacturers eliminate commutator wear and extend runtime on lithium battery packs. GPS-integrated systems concentrate margin pools through recurring mapping subscription attachments, whereas hand-controlled units occupy economy tiers in price-sensitive recreational segments.
Regulatory Environment
The EPA regulates lead-acid battery disposal patterns that shape power source transitions toward lithium-ion alternatives in electric trolling motors. Coast Guard flotation and electrical safety standards govern product certification requirements for aftermarket installation. Stakeholders must monitor state-level invasive species transport regulations that increasingly mandate sealed motor designs and equipment decontamination protocols at waterway access points.
Market Dynamics
Brushless motor architecture is compressing maintenance intervals and extending runtime on lithium battery packs, forcing incumbent manufacturers to retool production lines or cede premium positioning to specialized suppliers.
Growth Catalysts
- Lithium-ion battery chemistry:Energy density improvements enable 36-volt systems to deliver 150-pound thrust outputs previously requiring heavier lead-acid configurations. Tournament anglers in the United States prioritize extended water time over upfront cost.
- Precision agriculture waterway management:Aquatic vegetation control contractors adopt GPS-guided trolling systems for systematic herbicide application in Florida and Louisiana canal networks.
- EPA lead-acid disposal mandates:Stricter cradle-to-grave tracking requirements accelerate fleet replacement cycles in commercial fishing operations across the Great Lakes basin.
Market Restraints
- Neodymium magnet supply concentration:Brushless motor production depends on rare earth processing capacity concentrated in China, exposing manufacturers to export quota volatility and price spikes.
- Deep-cycle battery replacement cost:Lithium-ion pack prices remain three to four times lead-acid equivalents, blocking adoption in price-sensitive recreational segments.
- Coast Guard electrical certification timelines:Extended testing protocols for 36-volt systems delay product launches by eight to fourteen months versus 12-volt counterparts.
Strategic Opportunities
- Kayak fishing expansion:Compact 12-volt transom-mount units penetrate the United States inland waterway recreational segment where boat ownership rates lag coastal regions.
- Subscription chartplotter integration:Sonar mapping services create recurring revenue attachment to hardware sales, with freshwater bass anglers showing highest willingness-to-pay for real-time bottom contour updates.
- State invasive species mandates:Wisconsin and Minnesota regulations requiring sealed motor housings and decontamination protocols favor suppliers with rapid-seal quick-connect designs.
Industry Challenges
- Embedded software validation:GPS autopilot firmware requires extensive field testing across diverse magnetic declination zones, stretching engineering timelines.
- Dealer technician certification:Brushless controller diagnostics demand specialized training absent from traditional marine mechanic curricula, creating service bottlenecks in remote lake regions.
Report Scope
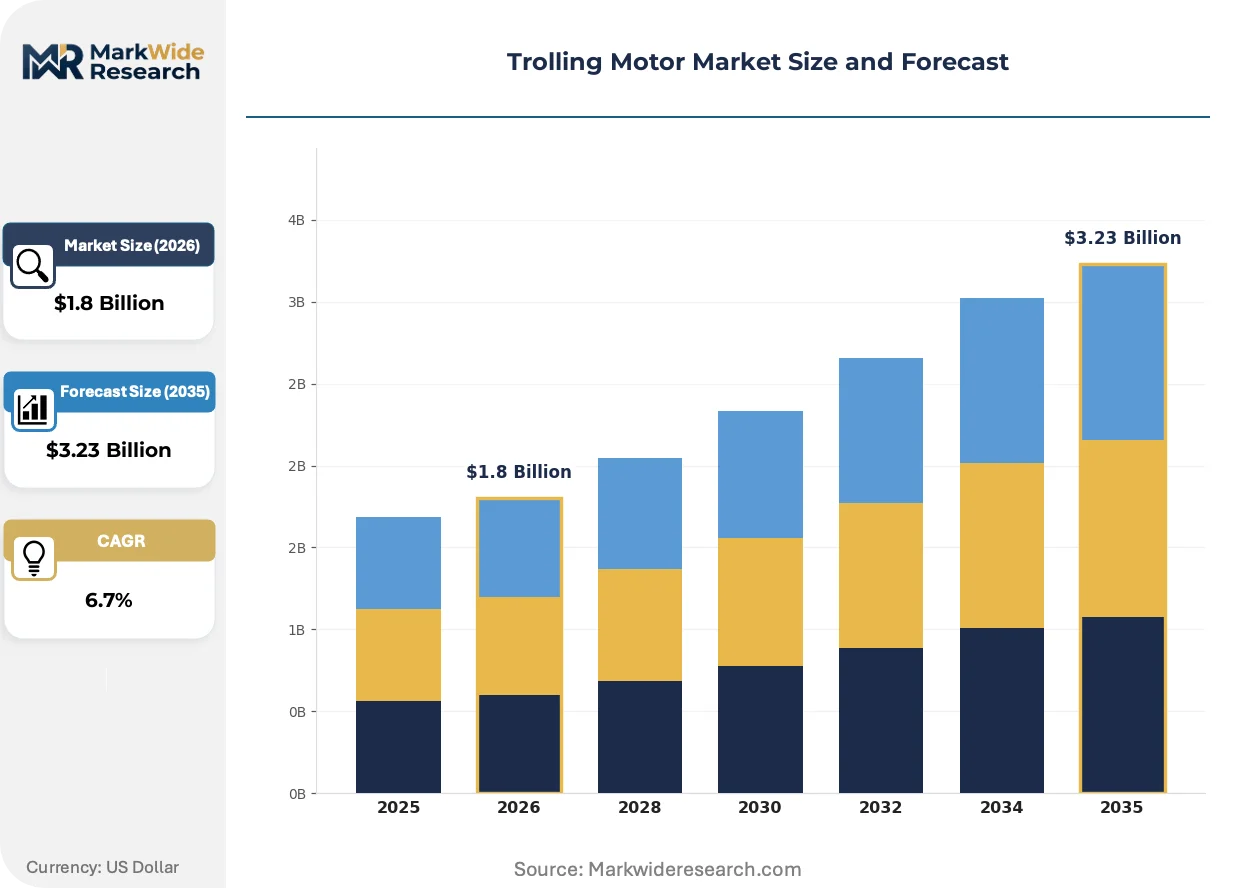
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trolling Motor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Bow Mount, Transom Mount, Engine Mount, Hand-Controlled Power Source: Electric, Gasoline, Hybrid, Solar Application: Freshwater Fishing, Saltwater Fishing, Commercial Use, Recreational Use Technology: GPS Integrated, Remote Control, Brushless Motors, Wireless Connectivity |
| Companies Covered | Lowrance, Watersnake, Minn Kota, Power-Pole, Haswing, MotorGuide, Newport Vessels, Bison, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trolling Motor Market Strategic Shifts
Control system digitization is redefining how operators interact with propulsion, shifting mechanical linkages to software-defined interfaces that enable remote diagnostics and over-the-air feature activation.
Brushless DC motor technology is absorbing the high-thrust product tier as permanent magnet designs eliminate brush wear and commutator maintenance. Tournament fishing circuits in the United States Southeast have standardized on 36-volt brushless configurations for competitive reliability. This architecture is absorbing service revenue from traditional rebuild shops and redirecting it toward firmware update subscriptions.
EPA hazardous waste regulations now classify spent lithium trolling motor batteries as universal waste, triggering manifest documentation requirements for commercial operators. Marine service centers in coastal states face expanded liability for improper disposal. The regulatory burden falls heaviest on multi-boat charter fleets, which are consolidating vendor relationships to simplify compliance auditing.
Direct-to-consumer configuration tools now allow buyers to spec thrust rating, shaft length, and sonar integration before manufacturing, compressing traditional dealer inventory models. Independent marine retailers in the Great Lakes region are responding by emphasizing installation and calibration services that resist online disintermediation. This channel tension is most acute in Minnesota and Wisconsin, where seasonal demand concentration strains just-in-time fulfillment networks.
Trolling Motor Market Segmentation
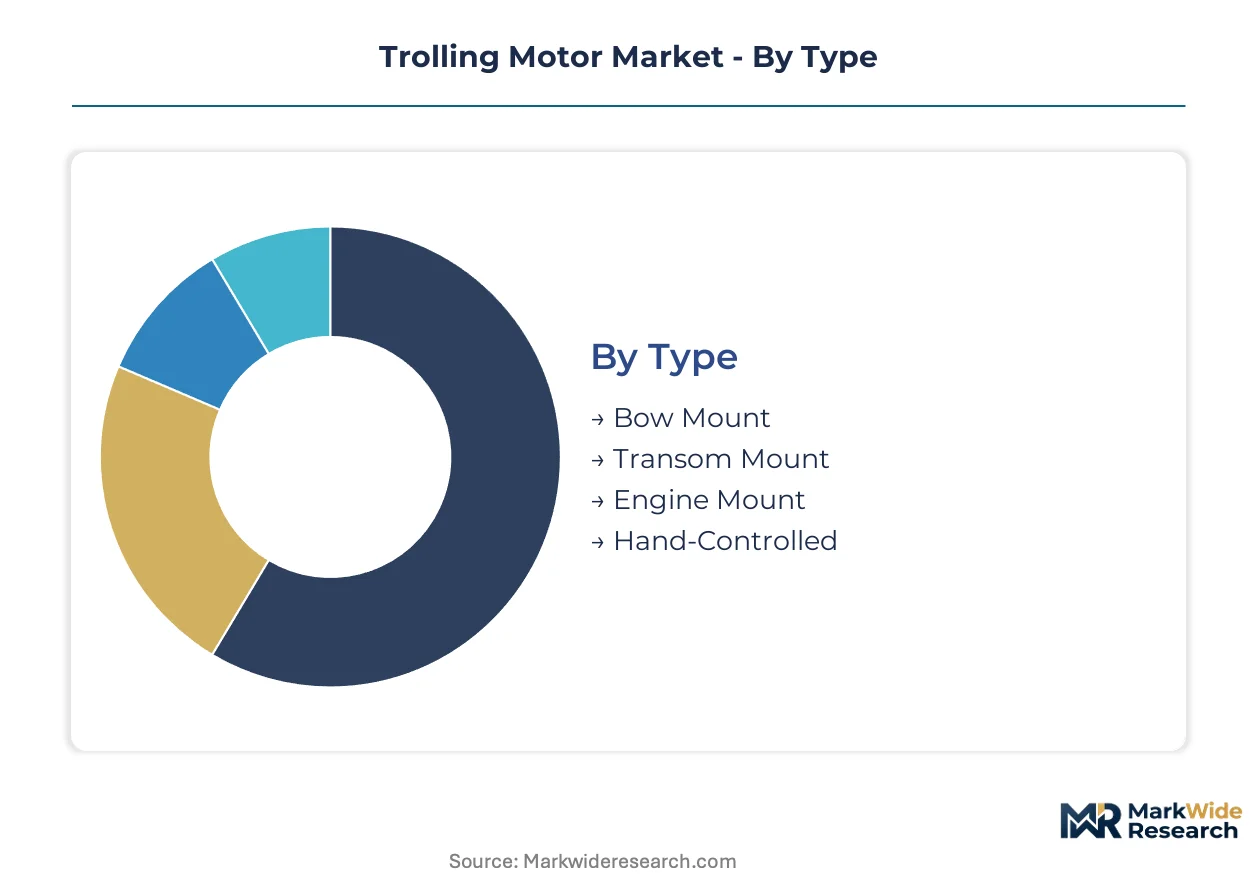
Tournament fishing circuits and recreational boating operators select trolling motor configurations based on hull geometry, battery infrastructure, and precision control requirements. Segmentation patterns reveal how voltage architecture and mounting position separate premium tournament equipment from economy recreational units.
Type:
Mounting position determines boat control precision and installation cost, with bow configurations demanding structural reinforcement and electrical routing that transom alternatives avoid.
- Bow Mount:Forward-mounted units deliver superior directional control in wind and current through vector thrust geometry. Bass tournament circuits in the United States Southeast specify bow configurations for spot-lock positioning during competitive events.
- Transom Mount:Stern-mounted designs clamp to flat transom surfaces without hull modification. Kayak anglers and small craft operators in Minnesota and Wisconsin inland lakes favor these units for portability and rapid installation.
- Engine Mount:Bracket systems attach to outboard cavitation plates, preserving deck space on compact vessels. Charter operators running multi-species trips on the Great Lakes deploy these for backup propulsion redundancy.
- Hand-Controlled:Mechanical tiller steering eliminates electronic complexity and battery drain. Price-sensitive recreational buyers in Florida canal systems select these for occasional weekend fishing without GPS subscription commitments.
Volume sits with Transom Mount; growth tilts toward Bow Mount.
Power Source:
Fleet operators and individual anglers balance runtime requirements against infrastructure investment, with lithium compatibility becoming a decisive specification filter.
- Electric:DC motor systems rated 12 to 36 volts dominate tournament and recreational freshwater applications. EPA lead-acid disposal mandates accelerate fleet conversion to lithium-compatible electric architectures in commercial Great Lakes operations.
- Gasoline:Two-stroke and four-stroke combustion units deliver thrust independent of battery capacity. Remote Alaskan and Canadian lodge operators maintain gasoline inventory for extended backcountry expeditions beyond charging infrastructure.
- Hybrid:Dual-mode systems switch between electric precision and gasoline endurance. Emerging charter configurations in Louisiana marshlands test these for all-day redfish guiding with minimal environmental surface disturbance.
- Solar:Photovoltaic panel integration extends runtime on electric trolling motors during daylight operations. Experimental installations in Arizona reservoir systems evaluate panel durability against vibration and water exposure.
Electric captures current volume leadership; hybrid configurations are climbing the fastest as charter fleets seek operational flexibility.
Application:
End-use context dictates thrust rating, corrosion protection, and control system sophistication more than any technical specification alone.
- Freshwater Fishing:Lake and river targeting of bass, walleye, and panfish drives demand for GPS anchor modes and precise speed control. Tournament circuits across Texas, Alabama, and Tennessee standardize on integrated sonar-motor ecosystems.
- Saltwater Fishing:Coastal and offshore applications require sealed housings and anodized aluminum shafts against corrosion. Florida Keys and Louisiana Gulf guides prioritize 36-volt systems for fighting tidal currents during tarpon and redfish pursuits.
- Commercial Use:Charter fleets, aquaculture operations, and vegetation management contractors run extended daily cycles. Great Lakes salmon charter operators in Michigan and Ohio seek brushless reliability to minimize downtime during peak summer season.
- Recreational Use:Casual weekend anglers prioritize simplicity and portability over integrated electronics. Cabin owners across Minnesota's lake districts purchase basic hand-controlled units for occasional dock fishing and shoreline cruising.
Freshwater Fishing holds installed base dominance; Saltwater Fishing shows steepest expansion trajectory as sealed-system reliability improves.
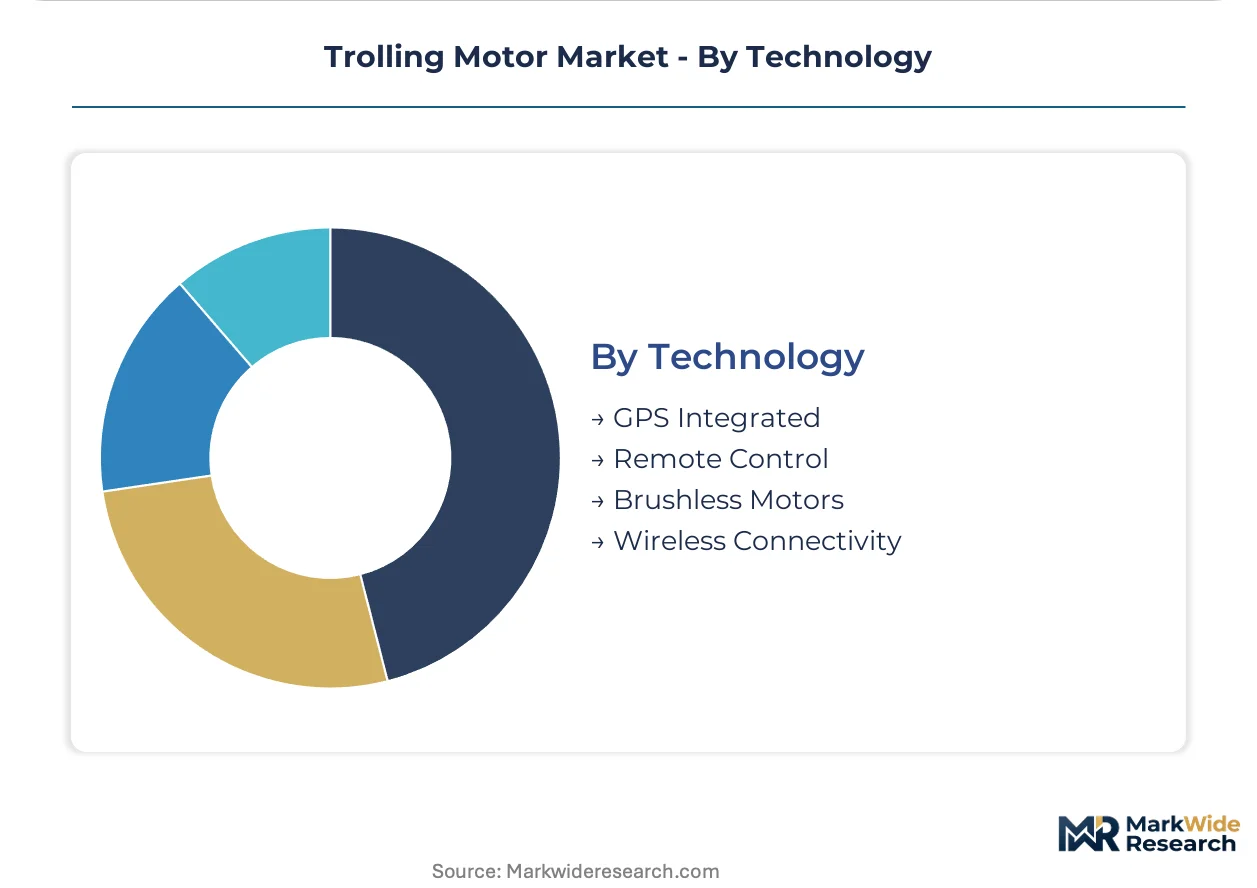
Technology:
Control layer integration separates premium pricing tiers, with software-defined features creating recurring revenue attachments that hardware margins cannot match.
- GPS Integrated:Autopilot firmware enables anchor lock, route recording, and drift compensation without physical anchoring. Competitive anglers demonstrate highest willingness-to-pay for real-time bottom contour subscription updates.
- Remote Control:Wireless handheld or foot pedal interfaces free operators from fixed steering positions. Tournament professionals value remote deployment for maintaining fishing posture while adjusting position.
- Brushless Motors:Permanent magnet DC designs eliminate commutator wear and extend runtime on lithium battery packs. United States Southeast tournament circuits have standardized on brushless configurations for competitive reliability.
- Wireless Connectivity:Bluetooth and proprietary radio links enable smartphone app control and over-the-air firmware updates. Younger demographics entering kayak fishing segments expect mobile-first interfaces.
Brushless Motors anchor current revenue; GPS Integrated systems are gaining share fastest through subscription attachment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in coastal Chinese industrial zones while consumption gravitates toward North American lake districts and European inland waterways. This geographic split shapes logistics networks and regulatory compliance burdens across the value chain.
United States
Tournament bass fishing circuits across Texas, Alabama, and Tennessee sustain premium equipment demand through standardized competitive specifications. EPA hazardous waste regulations now classify spent lithium trolling motor batteries as universal waste, triggering manifest documentation requirements for commercial charter fleets. Marine service centers in Michigan and Ohio's Great Lakes corridor face expanded liability for improper disposal during peak salmon season.
Canada
Remote lodge operators in Ontario's Kawartha Lakes and British Columbia's interior maintain gasoline inventory for extended backcountry expeditions beyond charging infrastructure reach. Health Canada electrical safety standards govern product certification requirements for aftermarket installation across provincial jurisdictions. Winnipeg-based distribution hubs coordinate seasonal fulfillment to Manitoba and Saskatchewan lake regions where summer demand concentrates.
China
Zhejiang and Guangdong province factories supply brushless motor components and complete transom-mount assemblies for export markets. MIIT industrial standards and GB certification requirements shape product specifications for domestic waterway applications. Ningbo port clusters handle bulk shipment of lithium-compatible electric architectures to North American and European distributors.
Germany
Precision engineering demand from Bavarian and Baden-Württemberg recreational boating operators favors GPS-integrated bow mount configurations. CE marking and RoHS compliance requirements filter economy-tier imports from non-EU suppliers. Hamburg marine equipment distributors serve Scandinavian re-export channels for sealed-system saltwater configurations.
Australia
Queensland and New South Wales barramundi and flathead anglers adopt compact kayak-mounted transom units for inland waterway accessibility. TGA electrical safety frameworks parallel Coast Guard standards for 36-volt system certification. Sydney and Melbourne retail clusters emphasize installation services that resist direct-to-consumer online disintermediation.
Trolling Motor Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the trolling motor supply base. The market structure tilts toward consolidated premium tiers where integrated electronics ecosystems command pricing power, while transom-mount and hand-controlled segments fragment across regional fabricators. Three archetypes dominate: vertically integrated marine electronics conglomerates, specialized freshwater tournament equipment suppliers, and contract manufacturers serving private-label distributors. Competitive moves concentrate on firmware ecosystem lock-in and dealer network exclusivity arrangements rather than pure manufacturing scale.
Among North American marine electronics conglomerates, Garmin and Minn Kota occupy positions anchoring integrated chartplotter-motor ecosystems that reduce switching costs for boat owners. MotorGuide exemplifies the specialized tournament equipment archetype, with configurations standardized across competitive angling circuits. Chinese contract manufacturers including Haswing and Newport Vessels represent the private-label supply tier, serving price-sensitive recreational segments through distributor-branded transom-mount offerings.
| Leading Market Players |
|---|
| Lowrance |
| Watersnake |
| Minn Kota |
| Power-Pole |
| Haswing |
| MotorGuide |
| Newport Vessels |
| Bison |
| Garmin |
| Others |
Value Chain & Pricing Dynamics
Backward integration into brushless motor controller production anchors both supply security and premium pricing power for manufacturers competing on GPS-integrated ecosystems. This captive production of electronic control modules insulates tier-one suppliers from neodymium magnet price volatility while locking in margin pools unavailable to assemblers sourcing commoditized transom-mount units from Zhejiang contract manufacturers.
Pricing Analysis
Margin tightening in economy-tier transom-mount units reflects lithium battery pack cost premiums that remain three to four times lead-acid equivalents. Three-tier pricing structure across premium GPS-integrated, standard remote-control, and economy hand-controlled levels separates subscription-enabled ecosystems from transactional hardware sales. Cost-down pressure on brushless configurations accelerates because tournament anglers in the United States Southeast prioritize runtime reliability over upfront expenditure. Recreational cabin owners across Minnesota lake districts exhibit highest price sensitivity, while competitive bass circuits demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Ningbo, Shenzhen, and Rotterdam handle hub-and-spoke fulfillment to North American marine retailers and European boating distributors. Manufacturing concentrates in Zhejiang and Guangdong provinces for complete assemblies, with South Korean and Japanese suppliers feeding precision magnetic components and sensor modules. Rare earth processing capacity tethered to Chinese export quotas constitutes the dominant supply chain risk. Distribution runs through independent marine dealers in the Great Lakes corridor and seasonal fulfillment networks in Minnesota and Wisconsin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around firmware ecosystem lock-in and dealer network exclusivity, with EPA hazardous waste regulations forcing smaller service centers out of commercial fleet maintenance.
For Market Incumbents: Anchor premium positioning through proprietary chartplotter-motor integration that raises switching costs for tournament anglers and charter operators. Deepen backward integration into lithium battery management systems to capture service revenue streams diverted from traditional rebuild shops. Defend against Chinese private-label encroachment by emphasizing Coast Guard certification investment and remote firmware update infrastructure. For New Entrants and Emerging Players: The price-point gap between Garmin-Minn Kota premium ecosystems and Haswing-Newport economy transom units offers white-space targeting for mid-tier kayak fishing configurations with mobile-first wireless connectivity. Wisconsin and Minnesota invasive species mandates create penetrable regulatory entry points for rapid-seal quick-connect designs. Pursue direct-to-consumer configuration tools that compress dealer inventory models while emphasizing installation services that resist online disintermediation. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical integration plays by marine electronics conglomerates seeking captive brushless motor production and GPS firmware assets. Five-to-ten-year viability favors suppliers with lithium-compatible architectures and subscription chartplotter attachment economics. Monitor neodymium export quota volatility as inflection indicator for margin compression across brushless-dependent product tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor Controller Integration | Captures margin pools from traditional rebuild shops and extends runtime on lithium battery packs. |
| Subscription Chartplotter Launch | Creates recurring revenue attachment to hardware sales among freshwater bass anglers. |
| Dealer Network Exclusivity Expansion | Locks out private-label competitors in remote lake regions lacking service infrastructure. |
| Lithium Battery Management Development | Addresses EPA universal waste classification and simplifies compliance auditing for charter fleets. |
| Quick-Connect Sealed Housing Design | Captures share in Wisconsin and Minnesota markets under invasive species transport mandates. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with tournament fishing circuit organizers, marine dealer network managers, charter fleet operators, and brushless motor controller engineers. EPA hazardous waste documentation, Coast Guard electrical safety standards, and state-level invasive species regulations provided regulatory boundary conditions. Bottom-up demand modeling across mounting position, voltage architecture, and application segments triangulated against top-down manufacturer shipment estimates.
Granularity-level modeling addressed voltage tier, mounting configuration, control system type, and regional adoption pattern across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by lithium battery penetration curves and GPS subscription attachment rates. Tournament fishing standardization patterns in the United States Southeast and Great Lakes charter fleet replacement cycles informed demand elasticity assumptions.
Inputs from EPA manifest documentation systems and marine service center disposal records were available through the study window; gaps in real-time lithium battery pricing volatility introduce uncertainty bands around fleet conversion timing assumptions. Forecasts reflect documented assumptions regarding neodymium supply stability and Coast Guard certification timeline standardization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Torque Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Electric Drives Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Automotive Seat Motor Market