
 Marine Beacon Market | 2026-2036
Marine Beacon Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Beacon Market Analysis
The marine beacon category is pivoting between premium solar-LED systems and commodity battery-operated units as price-performance thresholds diverge. ACR Electronics Inc. leverages its aviation heritage to dominate distress beacon certification tiers. Sealite Pty Ltd. anchors the commercial navigation segment with specialized LED lantern architectures for port authorities. SABIK Marine competes through integrated offshore platform lighting systems that bundle beacon, fog signal, and monitoring functions.
Marine beacons are self-contained luminous signaling devices, typically rated between one and twenty-five nautical miles of visible range, employing sealed LED arrays, xenon flash tubes, or halogen lamps within corrosion-resistant housings to mark channels, hazards, and structures for maritime traffic. LED beacons lead product type demand as port operators prioritize energy reduction and maintenance interval extension. Solar-powered technology grows fastest where grid access proves unreliable on remote buoys and unmanned platforms. Hardwired systems retain margin concentration in permanent offshore installations where continuous operation overrides capital cost sensitivity.
IMO SOLAS conventions, IALA recommendations, and national lighthouse authorities collectively mandate minimum intensity, color, and flash-characteristic standards that determine product eligibility for commercial deployment. The US Coast Guard, Trinity House in the United Kingdom, and the Japan Coast Guard enforce compliance through type-approval processes that filter non-certified suppliers from tender participation. Stakeholders must monitor how evolving MARPOL energy-efficiency frameworks and emerging autonomous vessel traffic rules reshape beacon specification requirements for unmanned and reduced-crew operations.
Market Dynamics
LED retrofits and SOLAS-mandated safety upgrades are compressing replacement cycles across commercial fleets, forcing suppliers to recalibrate service architectures around shorter hardware lifespans and predictive maintenance contracts.
Growth Catalysts
- SOLAS Convention Chapter V:Mandatory carriage requirements for distress beacons on vessels over 300 gross tonnage sustain replacement demand across aging commercial fleets.
- Port electrification programs:Hamburg, Rotterdam, and Singapore port authorities prioritize solar-LED beacon deployments to reduce grid dependency on remote channel markers.
- Autonomous vessel traffic management:Emerging rules for unmanned surface vessels require enhanced beacon visibility ranges and redundant signaling systems.
Market Restraints
- Lithium battery supply concentration:Cathode material processing dominates in China, creating single-source vulnerability for solar-powered beacon manufacturers.
- Corrosion-resistant alloy costs:Marine-grade aluminum and titanium price volatility directly compresses margin on sealed housing assemblies.
- IALA certification timelines:Type-approval processes extending 18-24 months filter smaller suppliers from tender participation in regulated markets.
Strategic Opportunities
- Indonesia archipelago expansion:Underpenetrated port infrastructure across 17,000 islands creates demand for solar-LED buoys where grid extension proves uneconomical.
- Offshore wind farm marker convergence:Integrated aviation-marine obstruction lighting systems bundle beacon, fog signal, and radar reflector functions for turbine installations.
- EU Green Deal maritime funding:Emissions-reduction incentives for port operators accelerate LED retrofit programs in North Sea and Baltic terminals.
Industry Challenges
- Optical engineering talent scarcity:Specialized lens design and photometric calculation expertise concentrates in Germany and Japan, constraining R&D scaling.
- Legacy halogen interoperability:Mixed-fleet operators face integration complexity when synchronizing LED flash characteristics with existing xenon-based systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Beacon Market |
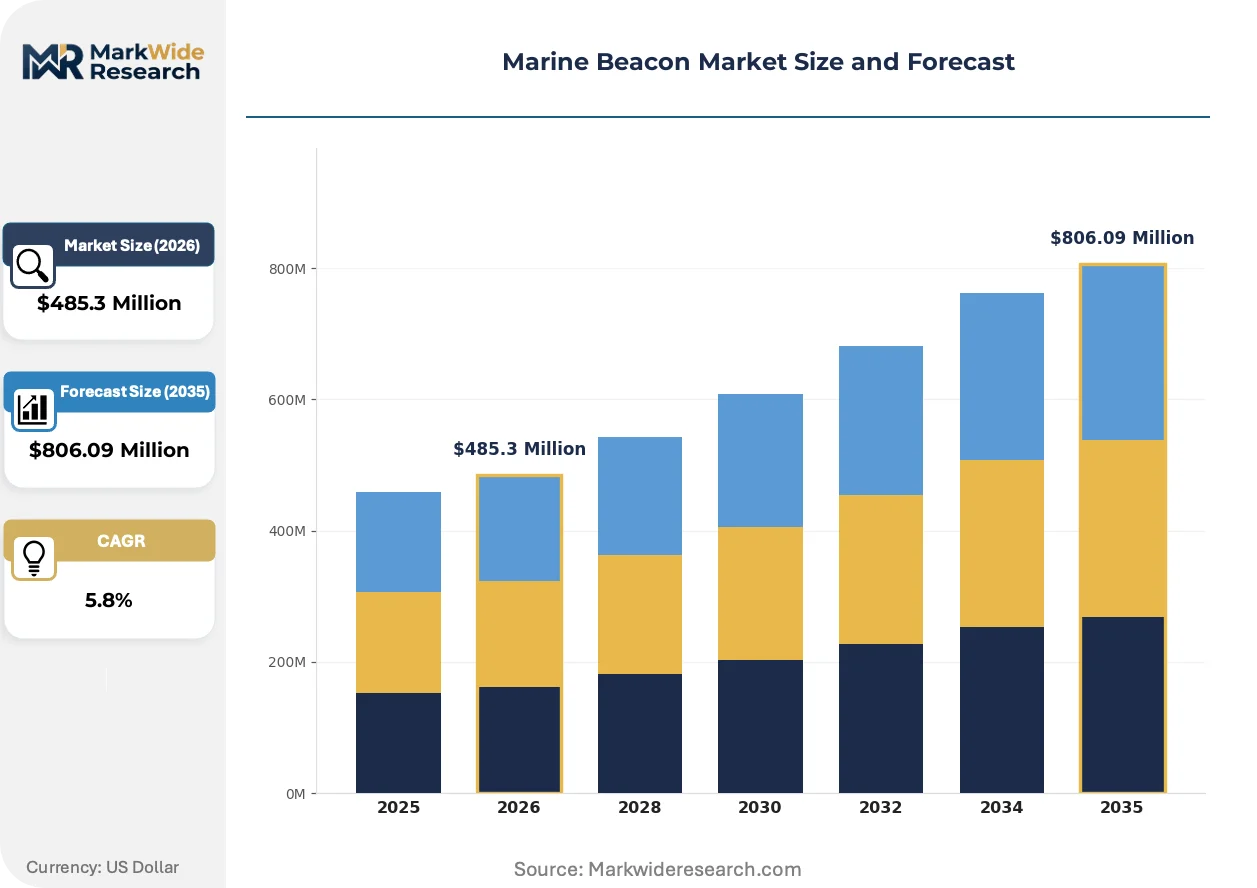
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Beacons, Xenon Beacons, Halogen Beacons, Strobe Beacons Technology: Solar-Powered, Battery-Operated, Hardwired, Wireless Application: Marine Navigation, Search and Rescue, Vessel Safety, Offshore Platforms End User: Commercial Shipping, Fishing Vessels, Recreational Boats, Authorities |
| Companies Covered | ACR Electronics Inc., Sealite Pty Ltd., Floatex Srl, SABIK Marine, Moflash Signalling Ltd., Ocean Signal Ltd., JFC Manufacturing Co., Ltd., Gisman, CR Control Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Beacon Market Emerging Trajectories
Beacon architecture is converging around solid-state illumination and autonomous power management, compressing the traditional divide between permanent offshore installations and portable emergency units.
Solid-state LED arrays with precision collimating optics are integrating adaptive intensity control and mesh-networked monitoring capabilities. Offshore platform operators in the North Sea adopt these systems to eliminate manual inspection cycles on unmanned structures. The technology is integrating predictive failure algorithms that trigger maintenance dispatch before luminous output degrades below IALA thresholds.
Revised MARPOL Annex VI energy-efficiency frameworks are tightening standby power allowances for navigation equipment. Shipowners operating trans-Pacific routes face compliance deadlines that accelerate LED conversion timelines. Container lines with Singapore and Long Beach port calls are prioritizing certified low-consumption beacon retrofits to avoid detention risk.
Port authorities are consolidating procurement through framework agreements that bundle beacon supply with 10-year maintenance liability. Trinity House in the United Kingdom and the Japan Coast Guard have shifted from unit purchase to availability-based contracts. This restructuring concentrates volume with suppliers capable of remote diagnostics and rapid response logistics.
Marine Beacon Market Segmentation
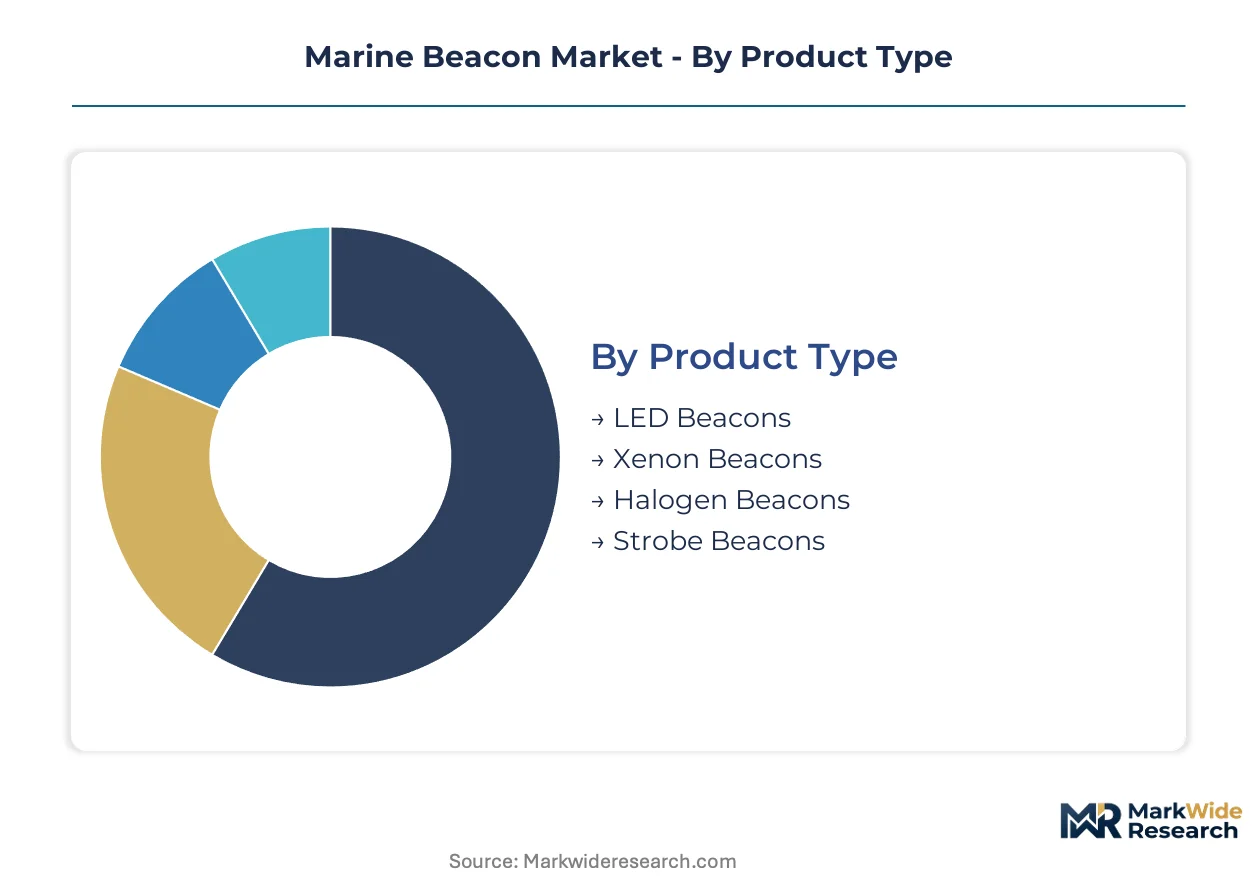
Beacon specification tiers determine procurement eligibility across SOLAS-mandated fleets and autonomous port infrastructure. Technology-product pairings create distinct margin profiles that separate premium integrated systems from commodity replacement units.
Product Type:
Optical emitter technology defines visible range, flash characteristic precision, and maintenance interval economics for maritime signaling systems.
- LED Beacons:Solid-state semiconductor arrays with precision collimating optics deliver 50,000-hour operational lifespans and adaptive intensity control. SOLAS-mandated retrofits across Singapore and Hamburg port authorities concentrate replacement demand as MARPOL Annex VI standby power limits tighten.
- Xenon Beacons:Gas-discharge flash tubes generate high-intensity short-duration pulses with superior long-range visibility. Legacy installations on North Sea offshore platforms sustain aftermarket demand where existing power infrastructure resists LED conversion costs.
- Halogen Beacons:Tungsten-filament lamps in sealed housings serve budget-constrained fishing fleets and developing-economy port authorities with lower capital thresholds.
- Strobe Beacons:High-frequency xenon or LED pulse configurations mark aviation-marine obstruction hazards on offshore wind turbines and drilling platforms.
Mature deployment sits with xenon systems on legacy offshore structures. Newer deployment is concentrated in LED configurations across electrified port terminals.
Technology:
Power architecture determines installation feasibility where grid access varies from dense harbor infrastructure to remote archipelago markers.
- Solar-Powered:Photovoltaic panels with lithium-iron-phosphate storage enable autonomous operation on unmanned buoys across Indonesia's 17,000 islands. Cathode material processing concentration in China creates supply vulnerability for beacon manufacturers dependent on imported battery cells.
- Battery-Operated:Sealed lead-acid or lithium primary cells power portable emergency beacons and temporary channel markers. Commercial fishing fleets in the Philippines and Vietnam prioritize these units for seasonal deployment flexibility.
- Hardwired:Grid-connected systems with battery backup dominate permanent offshore platform installations where continuous operation overrides capital cost sensitivity. North Sea oil operators specify these configurations for unmanned structure compliance.
- Wireless:Mesh-networked monitoring capabilities enable remote diagnostics and predictive maintenance dispatch before luminous output degrades below IALA thresholds.
Hardwired systems anchor revenue concentration on capital-intensive offshore energy infrastructure. Solar-powered configurations are climbing the fastest as archipelago nations expand unmanned marker networks.
Application:
Functional use case determines intensity requirements, color specification, and regulatory certification tier for beacon deployment.
- Marine Navigation:Channel marking, hazard indication, and range alignment for commercial traffic. Port authorities in Rotterdam and Long Beach consolidate procurement through framework agreements bundling supply with decade-long maintenance liability.
- Search and Rescue:Distress signaling with 406 MHz satellite integration for SOLAS-mandated vessel carriage requirements.
- Vessel Safety:Onboard emergency lighting and man-overboard marking systems for crew protection compliance.
- Offshore Platforms:Integrated aviation-marine obstruction lighting bundling beacon, fog signal, and radar reflector functions for wind turbine installations.
Navigation applications concentrate procurement volume with lighthouse authorities. Platform safety systems are gaining share fastest as offshore wind construction accelerates in the North Sea and Baltic.
End User:
Customer scale and regulatory exposure create divergent specification requirements across fleet types.
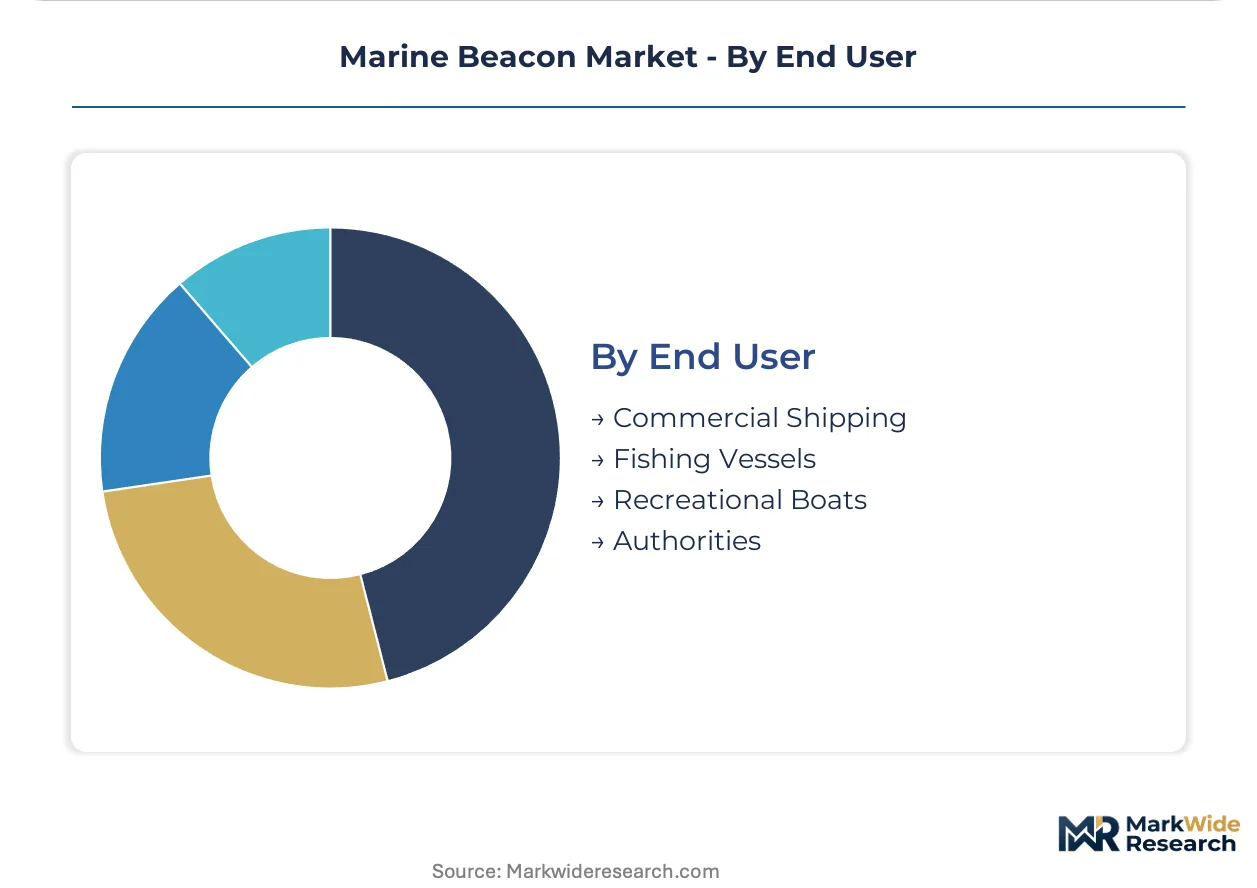
- Commercial Shipping:Container lines and bulk carriers above 300 gross tonnage face mandatory distress beacon carriage under SOLAS Convention Chapter V. Singapore and Long Beach port calls prioritize certified low-consumption retrofits to avoid detention risk.
- Fishing Vessels:Smaller-scale operators below SOLAS thresholds select battery-operated portable units with lower certification costs.
- Recreational Boats:Yacht owners and marina operators specify solar-LED aesthetic markers with minimal maintenance requirements.
- Authorities:Coast guard organizations and port authorities enforce compliance through type-approval processes that filter non-certified suppliers from tender participation.
Commercial shipping anchors procurement volume through mandatory replacement cycles. Recreational applications are expanding most quickly as marina infrastructure proliferates in coastal tourism economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam port electrification programs anchor European beacon procurement volume as SOLAS-mandated retrofits compress replacement cycles across North Sea commercial corridors.
China
Shanghai and Dalian shipyards drive LED beacon demand for newbuild container vessels and bulk carriers. MIIT maritime equipment standards enforce energy-efficiency compliance on domestic fleet operators. Ningbo-Zhoushan port cluster scales solar-LED channel marker deployment across unmanned buoy networks.
Germany
Hamburg port authority framework agreements consolidate decade-long maintenance liability with certified suppliers. KBA vessel safety regulations align with EU Green Deal maritime funding mechanisms. Bremen offshore wind construction clusters bundle aviation-marine obstruction lighting for North Sea turbine installations.
South Korea
Ulsan and Geoje shipbuilding complexes scale beacon procurement for LNG carrier and tanker newbuild programs. MFDS type-approval processes filter non-certified suppliers from government tender participation. Busan port authority prioritizes low-consumption LED retrofits to meet MARPOL Annex VI standby power limits.
United States
Long Beach and Los Angeles port calls enforce detention risk on non-compliant vessel beacon configurations. US Coast Guard type-approval mandates determine product eligibility for commercial deployment. Gulf of Mexico offshore platform operators specify hardwired systems for unmanned structure compliance.
Indonesia
Jakarta and Surabaya port authorities expand solar-LED buoy procurement across 17,000 islands where grid extension proves uneconomical. National lighthouse authority procurement frameworks prioritize autonomous power management for remote archipelago markers. Batam free trade zone clusters concentrate battery-operated beacon assembly for Southeast Asian fishing fleets.
Marine Beacon Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-tier and technology-integration dimensions. The vendor base stratifies between SOLAS-distress specialists, port-authority framework contractors, and offshore-platform integrators. Three archetypes dominate: aviation-heritage distress beacon certifiers, LED-lantern navigation specialists, and bundled offshore lighting system providers. Consolidation pressures concentrate volume with suppliers capable of remote diagnostics and predictive maintenance contracts.
Within the certification-tier specialist archetype, ACR Electronics Inc. and Ocean Signal Ltd. occupy positions leveraging aviation-safety heritage into maritime distress beacon compliance tiers. Sealite Pty Ltd. exemplifies the navigation-specialist archetype with LED lantern architectures for port authority frameworks. SABIK Marine anchors the offshore-integrator tier through bundled platform lighting systems.
| Leading Market Players |
|---|
| ACR Electronics Inc. |
| Sealite Pty Ltd. |
| Floatex Srl |
| SABIK Marine |
| Moflash Signalling Ltd. |
| Ocean Signal Ltd. |
| JFC Manufacturing Co., Ltd. |
| Gisman |
| CR Control Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
Trinity House and Japan Coast Guard framework agreements bundling decade-long maintenance liability into beacon procurement are compressing supplier margins and forcing manufacturers toward predictive service architectures that reshape cost structures across certification tiers.
Pricing Analysis
Availability-based contracts with remote diagnostics guarantees anchor value-based pricing for certified suppliers serving lighthouse authorities. Three-tier pricing structure across SOLAS-distress, port-navigation, and offshore-platform tiers separates premium integrated systems from commodity replacement units. Cost compression in battery-operated segments is intensifying because fishing fleet procurement concentrates on lowest capital-threshold units. Port authorities exhibit least price sensitivity where compliance detention risk overrides hardware cost.
Supply Chain Analysis
Domestic-content mandates in South Korea and Indonesia are reshaping sourcing patterns for assembly operations serving government tenders. Lithium-iron-phosphate cell production concentrates in China, with optical-grade aluminum and titanium feedstock anchored in Germany and Japan. Single-source vulnerability in cathode material processing creates supply risk for solar-powered beacon manufacturers. Distribution runs through port authority framework agreements and offshore EPC contractors rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IALA certification timelines extending 18-24 months are filtering smaller suppliers from tender participation, creating consolidation pressure that favors scaled incumbents with established type-approval track records.
For Market Incumbents: Cement framework contract dominance by embedding predictive maintenance platforms into port authority relationships. Deepen backward integration into lithium-iron-phosphate cell supply to offset China concentration risk. Acquire specialized optical engineering talent in Germany and Japan to constrain competitor R&D scaling.
For New Entrants and Emerging Players: Begin with solar-LED buoy deployment across Indonesia's underpenetrated archipelago where grid extension proves uneconomical. Target battery-operated portable units for Southeast Asian fishing fleets below SOLAS thresholds. Pursue co-development partnerships with local assembly clusters in Batam free trade zone to bypass certification timeline barriers.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated beacon manufacturers with captive LED array and housing production capabilities. Long-term viability hinges on positioning for autonomous vessel traffic rule implementation and offshore wind farm marker convergence. Watch MARPOL Annex VI enforcement intensity at Singapore and Long Beach as inflection indicator for LED retrofit acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Framework Agreement Consolidation | Trinity House and Japan Coast Guard shifts concentrate volume with predictive maintenance-capable suppliers. |
| Backward Integration into Battery Supply | Cathode material processing concentration in China forces beacon manufacturers toward captive cell sourcing. |
| Predictive Maintenance Platform Deployment | Remote diagnostics capabilities determine eligibility for availability-based contracts with lighthouse authorities. |
| Optical Engineering Talent Acquisition | Specialized lens design expertise concentration in Germany and Japan constrains competitor R&D scaling. |
| Offshore Wind Integration Bundling | North Sea turbine installations require combined aviation-marine obstruction lighting systems. |
Methodological Framework
Independent corroboration across primary interviews with port authority procurement officers, offshore platform maintenance directors, and lighthouse authority technical managers, alongside secondary validation through IALA recommendation documents, US Coast Guard type-approval registries, and customs trade data, underwrites the qualitative findings. Bottom-up triangulation across product-type shipment estimates and top-down validation against national fleet registry data anchor volume assessments.
Rate-of-change decomposition across the projection horizon segments the marine beacon market by optical emitter technology, power architecture, functional application, and end-user fleet type. CAGRs derive from fitted growth curves incorporating SOLAS-mandated replacement cycle compression, MARPOL Annex VI standby power limit enforcement, and offshore wind construction pipeline data. Forecast inputs include shipyard orderbook projections and port electrification program commitments.
Regulatory timeline delays, lithium battery supply disruption, and autonomous vessel rule implementation pace are the dominant revision risks to the analytical framework. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
North America Naval Vessels Market
Marine
Autonomous Ships Market
Marine
Marine Engine Cooling Systems Market
Marine
Sailboat Propellers Market
Marine
Marine Propeller Market
Marine
Furnace Boats Market
Marine
Boat Ladder Market
Marine
Global Foldable Inflatable Boats Market
Marine
Offshore AUV and ROV Market
Marine
Marine Shaft Power Meter Market
Marine
Fishing Vessel Market
Marine
Submarine Propulsion Systems Market
Marine
Marine Growth Removal Tool Market
Marine
Marine AIS Monitoring System Market
Marine
Asia-Pacific Offshore Support Vessels Market
Marine
Electric Ferry Market