
 Fishing Vessel Market | 2026-2036
Fishing Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Fishing Vessel Market Foresight
Buyer concentration among commercial fleet operators is consolidating as large-scale fishing enterprises replace fragmented small-scale ownership across North Atlantic and Southeast Asian waters. HD Hyundai Heavy Industries leverages its integrated shipyard ecosystem to dominate high-tonnage trawler construction for deep-sea operators. Damen Shipyards Group competes through modular platform flexibility, allowing rapid reconfiguration between purse seiner and gillnetter specifications. Mitsubishi Heavy Industries anchors its position via advanced hull-form R&D, sustaining technology leadership in fuel-efficient longliner designs.
A fishing vessel is a purpose-built marine craft, typically 15 to 120 meters in length, constructed from steel or aluminum with refrigerated fish holds, deck machinery for net and line handling, and propulsion systems rated for continuous operation in harsh sea states; its primary function is the harvesting, storage, and transport of wild-caught or aquaculture-supported seafood to processing facilities. Trawlers and purse seiners command the largest share of current order books, reflecting their dominance in volume fisheries targeting pelagic and demersal species. Hybrid propulsion systems represent the fastest-expanding segment within propulsion type categories, as operators navigate rising fuel costs and port-entry emissions restrictions. Deep sea fishing applications concentrate margin pools due to higher vessel specifications and longer replacement cycles compared to coastal alternatives.
The International Maritime Organization enforces MARPOL Annex VI emissions standards that directly constrain engine specifications and retrofit timelines for fishing fleets worldwide. EU Green Deal implementation through the F-Gas Regulation and REACH compliance requirements shapes material selection for insulation and refrigeration systems in European-built vessels. The US Coast Guard and EPA jointly administer construction and environmental standards affecting market access for imported hulls and propulsion packages. Stakeholders must monitor accelerating regulatory divergence between major building regions as compliance costs reshape competitive positioning across vessel type and propulsion categories.
Market Dynamics
IMO MARPOL Annex VI emissions standards are compressing engine replacement timelines and forcing shipyards to accelerate hybrid propulsion integration across newbuild programs and retrofit queues.
Growth Catalysts
- EU Green Deal F-Gas mandates:European operators must replace high-GWP refrigerants in onboard cold storage, triggering fleet-wide refrigeration system upgrades and vessel replacement cycles.
- Pelagic quota consolidation:Large-scale Norwegian and Spanish fleet operators are capturing transferable catch rights, concentrating capital for new high-tonnage trawler orders.
- Battery-hybrid propulsion maturation:Lithium-ion energy density improvements now enable meaningful fuel displacement in 40-80 meter vessel classes previously restricted to conventional diesel-mechanical systems.
Market Restraints
- Specialized steel plate supply:High-tensile marine-grade steel production concentrates in South Korean and Chinese mills, exposing European and North American builders to input cost volatility and delivery uncertainty.
- Deep-sea certification complexity:Lloyd's Register and DNV GL classification timelines for ice-class and extended-range fishing vessels now stretch 18-24 months, delaying revenue recognition for shipyards.
- Aquaculture substitution:Land-based recirculating aquaculture systems in Norway and Chile are displacing wild-catch volume in salmon and whitefish supply chains, eroding demand for certain purse seiner specifications.
Strategic Opportunities
- Indonesian fleet modernization:The national fisheries ministry's decommissioning program for wooden vessels creates opening for aluminum-hulled coastal trawler imports from Korean and Spanish builders.
- Dual-fuel methanol readiness:Engine makers are certifying medium-speed blocks for methanol combustion, positioning early-adopter shipyards to capture EU Emissions Trading System compliance premiums.
- Digital catch monitoring integration:Real-time electronic monitoring systems for quota compliance represent attach-rate opportunity for vessel electronics integrators serving North Atlantic operators.
Industry Challenges
- Marine electrical engineering talent:Shipyards in Norway and South Korea report acute shortages of power systems engineers capable of integrating battery-hybrid architectures with diesel-generator sets.
- Legacy refrigeration retrofit compatibility:Aging steel-hulled trawlers built to 1990s specifications often lack structural margins for ammonia-based cooling system conversions required by REACH compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fishing Vessel Market |
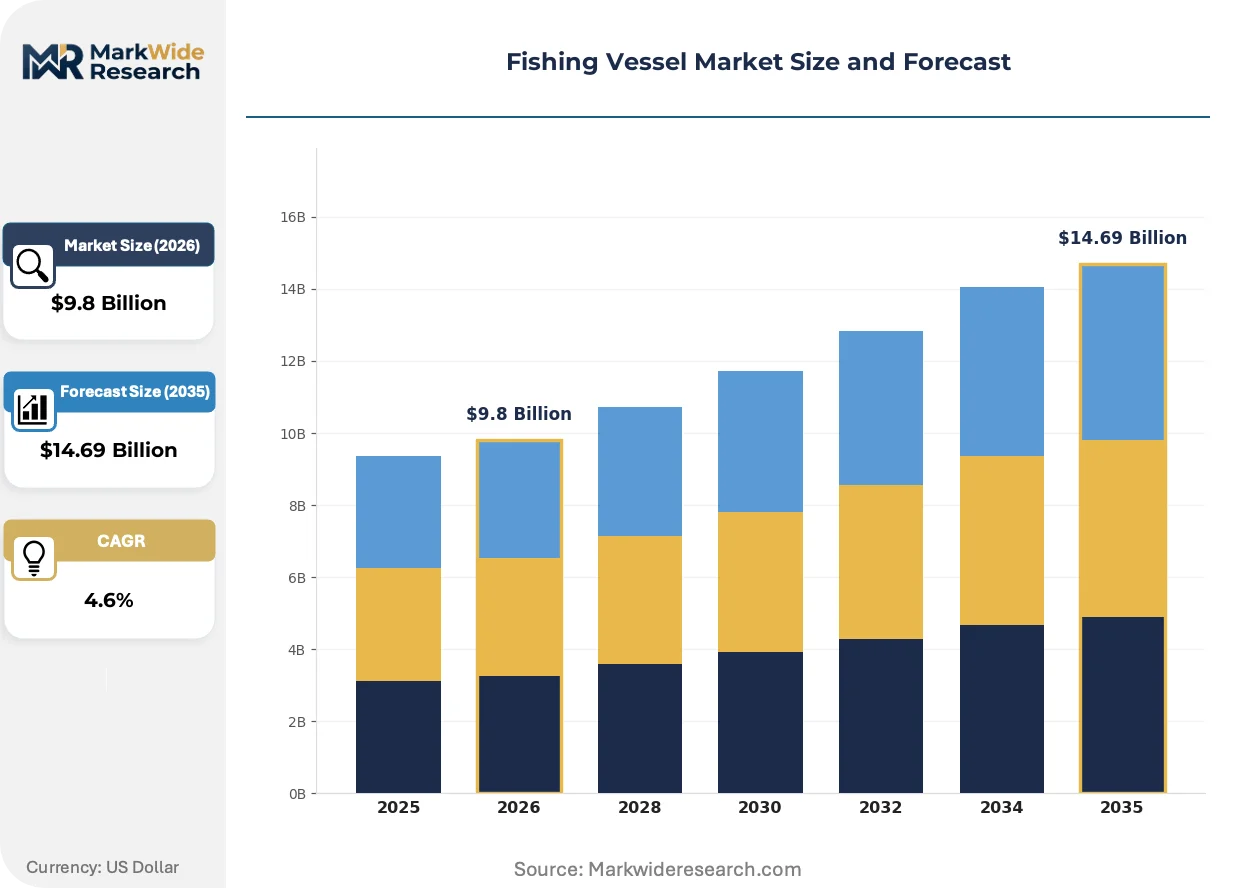
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Trawlers, Purse Seiners, Longliners, Gillnetters, Dredgers Propulsion Type: Diesel Engines, Gas Turbines, Electric Motors, Hybrid Systems, Steam Turbines Application: Deep Sea Fishing, Coastal Fishing, Freshwater Fishing, Aquaculture Support, Research Vessels End User: Commercial Fleet Operators, Small-Scale Fishers, Government Agencies, Research Institutions, Charter Services |
| Companies Covered | HD Hyundai Heavy Industries Co. Ltd., Mitsubishi Heavy Industries Ltd., Fincantieri S.p.A., Damen Shipyards Group, Wärtsilä Corporation, Vard Group, Rolls-Royce PLC, Samsung Heavy Industries, Eastern Shipbuilding Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fishing Vessel Market Shifts & Advancements
Propulsion electrification and digital catch verification are converging to reshape vessel specification priorities, with regulatory compliance now driving technology adoption faster than operational efficiency alone.
Modular battery container systems are decentralizing hybrid propulsion architecture in mid-sized fishing vessels. Norwegian fleet operators are retrofitting 50-70 meter trawlers with swappable 20-foot battery units rather than integrated hull-mounted banks. This approach is decentralizing capital deployment, allowing operators to stage electrification investments across multiple vessels rather than concentrating resources in single newbuilds.
EU F-Gas Regulation phase-down schedules are compressing hydrofluorocarbon availability for onboard refrigeration. Shipbuilders serving European operators are accelerating ammonia and CO2 transcritical system certifications to maintain market access. Spanish and French Atlantic coast yards report that refrigeration specification now determines hull contract viability before propulsion or deck machinery discussions.
Buyers are consolidating procurement authority at fleet-operator headquarters rather than delegating to individual vessel captains. Large-scale Norwegian and South Korean fishing enterprises now centralize specification decisions for propulsion, monitoring systems, and catch handling equipment. This concentration is most visible in long-term framework agreements with single shipyards, displacing the traditional vessel-by-vessel competitive tendering pattern.
Fishing Vessel Market Segmentation
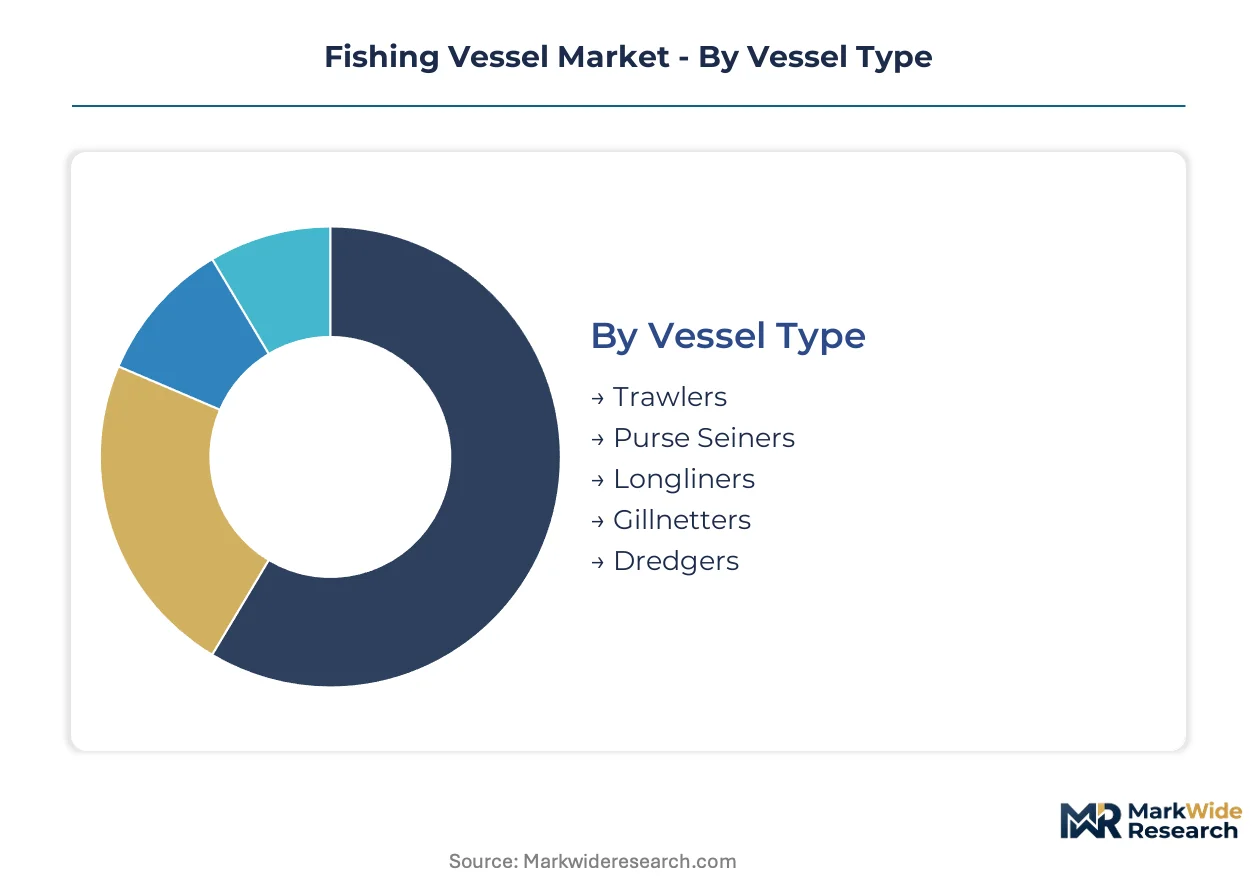
Fishing vessel procurement splits sharply between standardized hull platforms and purpose-built specifications. Shipyards compete on modular flexibility where reconfiguration costs determine contract winners. Understanding segment boundaries reveals where margin pools concentrate versus where volume commoditizes.
Vessel Type:
Standardization varies dramatically across this category, with some hull forms mass-produced and others engineered to individual operator specifications.
- Trawlers:Steel-hulled designs from 25 to 120 meters dominate deep-water demersal fisheries. Norwegian and Spanish fleet operators are consolidating orders for high-tonnage freezer trawlers as transferable catch quotas concentrate capital in fewer hands.
- Purse Seiners:These vessels deploy massive seine nets for pelagic species capture, requiring specialized deck machinery and high-volume refrigerated holds. Demand clusters in the North Atlantic and Southeast Asian waters where large-scale operators modernize aging fleets.
- Longliners:Purpose-built for line-deployed catch of tuna and swordfish with extended-range fuel capacity.
- Gillnetters:Smaller coastal vessels with net-handling systems for fixed-gear fisheries.
- Dredgers:Heavy-bottom equipment for shellfish and benthic species harvesting.
Most installed capacity flows through Trawlers. Expansion is steepest in Purse Seiners.
Propulsion Type:
Cost tiers separate this category, with capital intensity climbing sharply from conventional mechanical systems to integrated electric architectures.
- Diesel Engines:Medium-speed marine diesels remain the baseline for vessel classes under 60 meters, offering proven reliability and global service networks. Operators in emerging fleet markets prioritize first-cost minimization over fuel efficiency premiums.
- Hybrid Systems:Battery-diesel integration enables fuel displacement and port-entry emissions compliance. EU Green Deal implementation and IMO MARPOL Annex VI standards are accelerating adoption among North Atlantic operators facing tightening environmental regulations.
- Gas Turbines:High-power density for military-derived patrol and research platforms.
- Electric Motors:Integrated pod or shaft-line configurations for full-electric newbuilds.
- Steam Turbines:Legacy installations in converted naval hulls and specialized factory vessels.
Diesel Engines retain the largest installed base. Hybrid Systems are gaining share fastest as regulatory pressure compounds fuel cost sensitivity.
Application:
Customer type and operational intensity create distinct specification requirements across this category.
- Deep Sea Fishing:Extended-range vessels with ice-class certification, factory processing equipment, and crew accommodations for 30-60 day voyages. Norwegian operators are capturing transferable quota rights that fund replacement cycles for these high-specification assets.
- Coastal Fishing:Day-trip and short-duration vessels under 40 meters with simplified refrigeration and lower capital requirements. Indonesian fleet modernization programs are displacing wooden hulls with aluminum alternatives from Korean and Spanish builders.
- Freshwater Fishing:Inland waterway vessels for lake and river fisheries with draft restrictions.
- Aquaculture Support:Workboats for feed delivery, net maintenance, and harvest operations.
- Research Vessels:Scientific equipment platforms with quiet propulsion and precise station-keeping.
Deep Sea Fishing commands the highest vessel valuations. Coastal Fishing represents the largest unit volume opportunity.
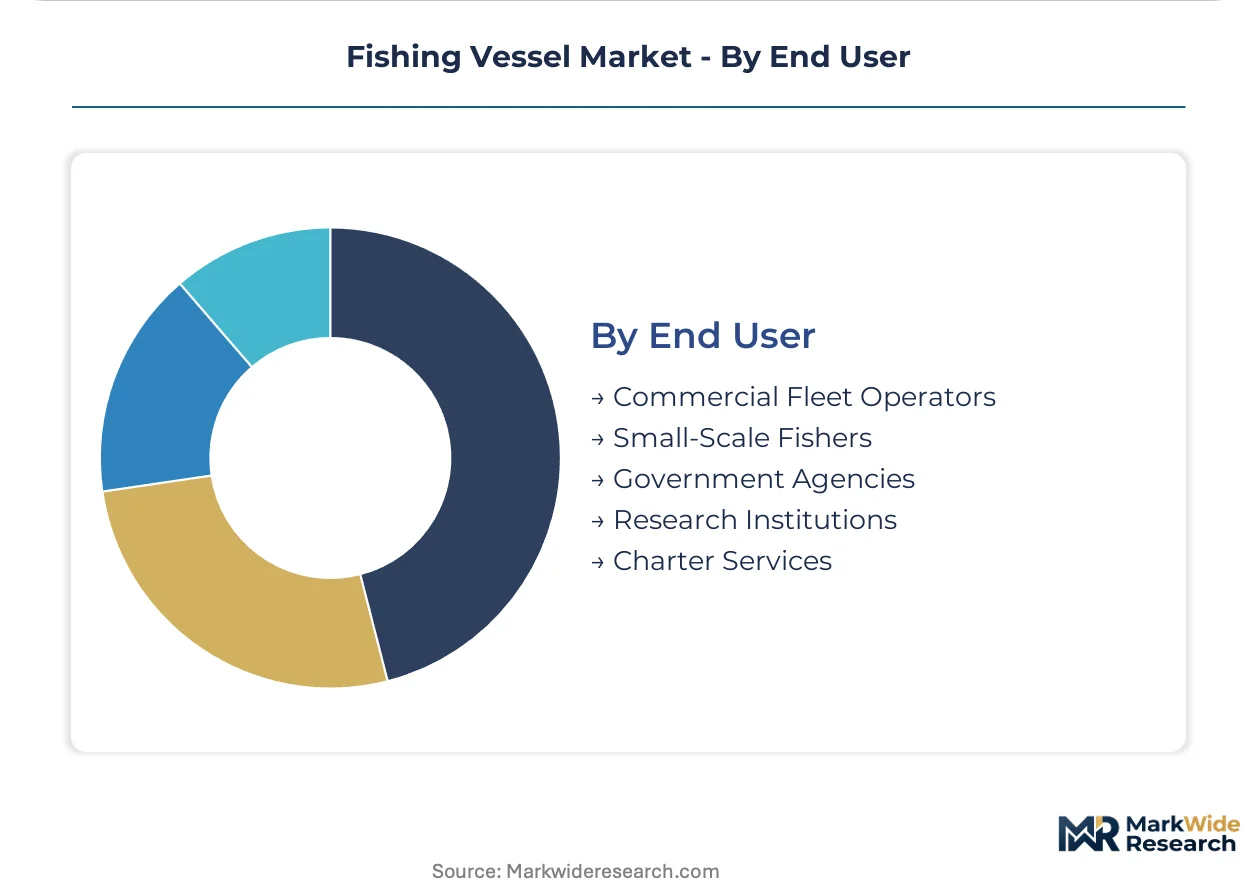
End User:
Procurement authority concentration varies, with some buyers negotiating fleet-wide frameworks and others purchasing vessel-by-vessel.
- Commercial Fleet Operators:Large-scale enterprises with centralized specification authority and multi-vessel order books. Norwegian and South Korean fishing enterprises now delegate procurement decisions to headquarters rather than individual vessel captains.
- Small-Scale Fishers:Owner-operators with fragmented purchasing power and financing constraints. Government subsidy programs in Indonesia and West Africa shape accessible vessel specifications for this segment.
- Government Agencies:Patrol, enforcement, and fishery research vessels with domestic build requirements.
- Research Institutions:Scientific mission platforms with specialized sensor and laboratory equipment.
- Charter Services:Recreational and sport-fishing operations with seasonal utilization patterns.
Commercial Fleet Operators drive premium segment demand. Small-Scale Fishers represent volume expansion potential where financing mechanisms improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway concentrates transferable quota rights that fund high-tonnage freezer trawler orders, while Spain modernizes aging purse seiner fleets under EU Green Deal pressure. South Korea anchors hybrid propulsion R&D for deep-sea vessel classes. Indonesia displaces wooden hulls with aluminum coastal trawlers. Each geography shapes distinct specification priorities and regulatory compliance pathways.
Norway
Large-scale commercial fleet operators capture transferable catch quotas that concentrate capital for vessel replacement cycles. The Norwegian Maritime Authority enforces strict emissions standards aligned with IMO MARPOL Annex VI timelines. Shipyards in Bergen and Alesund specialize in ice-class freezer trawlers with factory processing equipment for extended North Atlantic voyages.
South Korea
Integrated shipyard ecosystems dominate high-tonnage trawler construction for deep-sea operators facing fuel cost volatility. The Ministry of Oceans and Fisheries administers fleet modernization subsidies tied to hybrid propulsion adoption. Ulsan and Geoje industrial clusters anchor battery-hybrid R&D and marine-grade steel fabrication for export markets.
Spain
Atlantic and Mediterranean fleet operators replace aging purse seiners to maintain pelagic species catch efficiency. EU F-Gas Regulation mandates drive refrigeration system upgrades across vessel classes. Shipyards in Vigo and Pasajes concentrate on modular platform flexibility for rapid reconfiguration between fishing specifications.
Indonesia
The national fisheries ministry decommissions wooden vessels under fleet modernization programs creating import demand for aluminum-hulled alternatives. Domestic content requirements shape coastal trawler specifications for small-scale fishers. Surabaya and Makassar serve as distribution hubs for Korean and Spanish builder exports.
United States
Alaska and New England commercial operators face tightening catch quotas and extended-range fuel requirements. The US Coast Guard and EPA jointly administer construction and environmental standards affecting imported hull market access. Seattle and New Bedford anchor specialized longliner and trawler retrofit capabilities for domestic fleet operators.
Fishing Vessel Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across vessel specification tiers. The market structure concentrates among integrated shipyard groups with captive steel supply and classification society relationships. Three archetypes dominate: full-service shipbuilders with naval and commercial portfolios; modular platform specialists emphasizing reconfiguration speed; and propulsion system integrators capturing hybrid electrification premiums. Competitive moves center on fleet-wide framework agreements with large-scale operators and certification pre-positioning for emerging fuel standards.
Among diversified Korean shipbuilders, HD Hyundai Heavy Industries Co. Ltd. and Samsung Heavy Industries exemplify integrated ecosystem players with steel fabrication through outfitting capabilities. Damen Shipyards Group occupies a position as the modular platform archetype, representing European flexibility in rapid specification changes. Mitsubishi Heavy Industries Ltd. anchors Japanese technology leadership in advanced hull-form efficiency. These three entities collectively illustrate how geographic industrial clustering shapes competitive positioning across propulsion integration and hull engineering tiers.
| Leading Market Players |
|---|
| HD Hyundai Heavy Industries Co. Ltd. |
| Mitsubishi Heavy Industries Ltd. |
| Fincantieri S.p.A. |
| Damen Shipyards Group |
| Wärtsilä Corporation |
| Vard Group |
| Rolls-Royce PLC |
| Samsung Heavy Industries |
| Eastern Shipbuilding Group Inc. |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation mandates for ammonia-based refrigeration systems are forcing European operators to absorb specification premiums or defer fleet replacement, compelling shipyards to restructure procurement contracts around staged payment terms and captive steel sourcing to manage working capital exposure.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for mid-tonnage trawler classes as HD Hyundai Heavy Industries and Samsung Heavy Industries leverage integrated steel fabrication to compress build-cycle economics. Three-tier pricing structure across ice-class premium, standard North Atlantic specification, and economy coastal configurations separates contract tiers. Cost compression in economy coastal segments is intensifying because Indonesian fleet modernization programs prioritize first-cost minimization over fuel efficiency premiums. Small-scale fishers in West Africa and Southeast Asia exhibit highest price sensitivity, while Norwegian quota-concentrated fleet operators accept premium positioning for extended-range freezer trawlers.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Chinese mills for high-tensile marine-grade steel plate, exposing European and North American builders to input cost volatility and delivery uncertainty. Raw material dependencies center on specialized steel alloys, lithium-ion battery cells for hybrid architectures, and ammonia-compatible refrigeration compressors. Tariff exposure runs through EU import duties on Chinese-built hull sections and US Coast Guard certification delays for non-domestic propulsion packages. Distribution runs through direct fleet-operator framework agreements with single shipyards, displacing traditional vessel-by-vessel competitive tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between South Korean integrated shipyard ecosystems with captive steel supply and European modular specialists facing input cost volatility from Asian mill dependence.
For Market Incumbents: To counter margin compression from Korean conglomerate pricing power, European modular specialists should accelerate certification pre-positioning for methanol-ready propulsion systems to capture EU Emissions Trading System compliance premiums, while securing long-term offtake agreements with Norwegian and Spanish fleet operators to lock in replacement-cycle timing. For New Entrants and Emerging Players: The price-point gap between premium ice-class freezer trawlers and economy aluminum coastal vessels creates entry territory for mid-tier hybrid specialists targeting Indonesian government decommissioning programs with Korean-financed build-operate-transfer structures, leveraging domestic content requirements to establish local assembly presence. For Investors and Strategic Acquirers: Asymmetric upside sits with battery-hybrid propulsion integrators possessing marine electrical engineering talent pools in Norway and South Korea, where capability scarcity sustains margin premiums. Long-term viability hinges on regulatory compliance service attach rates rather than hull construction economics alone. Watch EU F-Gas phase-down acceleration as inflection signal for ammonia refrigeration system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit Program | Battery-diesel integration captures EU MARPOL Annex VI compliance premiums for North Atlantic operators. |
| Ammonia Refrigeration Certification | REACH-compliant cooling system pre-qualification determines hull contract viability before propulsion discussions. |
| Fleet-Wide Framework Agreement | Centralized procurement authority with Norwegian and Spanish operators displaces vessel-by-vessel tendering patterns. |
| Methanol-Ready Engine Pre-Positioning | Early-adopter shipyards capture EU Emissions Trading System positioning as dual-fuel blocks gain classification approval. |
| Modular Platform Standardization | Rapid reconfiguration between purse seiner and gillnetter specifications accelerates contract velocity for Damen-style specialists. |
Research Methodology
Direct dialogue with shipyard procurement directors, fleet operations managers at Norwegian and Spanish fishing enterprises, classification society surveyors from Lloyd's Register and DNV, and marine electrical engineering specialists grounded qualitative assessment, validated against customs trade data for steel plate and vessel exports, IMO regulatory filing databases, EU F-Gas Regulation implementation reports, and SEC 10-K disclosures from listed shipbuilders. Bottom-up vessel order-book aggregation and top-down macroeconomic demand modeling were triangulated to establish market sizing.
Bottom-up modeling traced individual hull contracts through shipyard reporting and fleet operator announcements, while top-down analysis indexed fishery quota allocations and fuel cost elasticity to project replacement-cycle timing across the analysis window. Segmentation dimensions included vessel type, propulsion architecture, application intensity, and end-user procurement authority concentration. CAGRs were derived from regression analysis of historical order patterns against regulatory compliance deadlines and quota transfer activity.
The model assumes a particular technology adoption path; alternative pathways for methanol combustion certification or solid-state battery commercialization would alter the outlook. Forecasts reflect documented assumptions regarding EU Green Deal implementation velocity and IMO MARPOL Annex VI enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
LNG Bunkering Vessel Market
Marine
Marine Navigation System Market
Marine
Boat Cleat Market
Marine
Buoys and Beacon Market
Marine
Ballast Water Management Market
Marine
Japan Marine Composites Market
Marine
Hybrid Fishing Boats Market
Marine
Azimuth Thrusters Market
Marine
Furnace Boats Market
Marine
Marine Suspension Seat Bases Market
Marine
Boat Steering Systems Market
Marine
Jack-Up Vessels Market
Marine
Dynamic Positioning System Market
Marine
North Sea Offshore Support Vessels Market
Marine
Pneumatic Marine Fender Market
Marine
Shipbuilding Market