
 Data Transmission Module Market | 2026-2036
Data Transmission Module Market Size, Share, and Industry Trends Forecast 2026-2036
Data Transmission Module Market Insights
REACH compliance is decoupling European market access from low-cost Asian supply chains, forcing module vendors to redesign material compositions and documentation trails. Coherent Corp. leverages vertical integration across laser chip fabrication and module assembly to sustain margin control amid these regulatory shifts. INNOLIGHT anchors its competitive position through concentrated R&D spending on high-speed optical engines. Accelink Technology Co. Ltd. dominates domestic procurement channels within China's telecommunications infrastructure buildouts.
A data transmission module integrates transceiver electronics, signal conditioning circuitry, and physical layer interfaces into a standardized form factor, typically operating at data rates from 1 Gbps to 800 Gbps depending on application requirements. These modules perform electro-optical or radio-frequency conversion to enable reliable information transfer across copper, fiber, or wireless media in network equipment, industrial controllers, and automotive systems. Fiber optic modules command the dominant share of value given their indispensability in data center interconnects and long-haul telecommunications, while Ethernet modules represent the fastest-expanding category as enterprise networks migrate to 400G and 800G switching fabrics. Wireless communication technology is gaining share in transportation and industrial automation deployments where cabling constraints limit wired alternatives.
The FCC governs electromagnetic emissions and spectrum allocation for modules deployed in US telecommunications and transportation infrastructure, while the EU AI Act and CE marking requirements impose conformity obligations on modules processing data in automated systems. China's MIIT enforces GB standards for optical and wireless transmission equipment, creating divergent certification pathways for multinational suppliers. Stakeholders must monitor regulatory fragmentation across these jurisdictions to determine whether localized production or modular platform designs offer superior compliance economics.
Market Dynamics
The Data Transmission Module Market is bifurcating between fiber-dominant data center interconnects and wireless modules for industrial mobility, with regulatory divergence across the US, EU, and China forcing parallel certification tracks that reshape vendor economics.
Growth Catalysts
- 5G backhaul fiberization:Telecommunications operators in the United States are replacing copper backhaul with single-mode fiber modules to meet FCC latency mandates for mid-band spectrum deployments.
- REACH material compliance:The EU's chemical registration framework is accelerating substitution of lead-based solders in optical transceivers, opening procurement channels for redesigned module portfolios.
- Cloud hyperscaler buildouts:Data center operators are standardizing on 800G pluggable optics for spine-leaf architectures, pulling demand for co-packaged photonics and linear drive technology.
Market Restraints
- III-V semiconductor supply concentration:Indium phosphide and gallium arsenide wafer fabrication clusters in Taiwan and Japan create chokepoints for high-speed laser chip supply.
- Copper interconnect substitution:Active electrical cables and retimed copper assemblies are capturing rack-scale connectivity below 3 meters, compressing addressable module volume in hyperscale facilities.
- Dual-use export controls:US Bureau of Industry and Security restrictions on 400G+ coherent DSPs are fragmenting supply chains for Chinese telecommunications infrastructure procurement.
Strategic Opportunities
- Automotive optical networking:In-vehicle backbone architectures for software-defined vehicles are adopting multi-gigabit optical links to isolate electromagnetic interference from battery systems.
- India PLI scheme alignment:The country's production-linked incentive framework for telecom equipment is attracting module assembly investments to serve domestic 5G and BharatNet rural fiber programs.
- Coherent-lite PON convergence:Access network operators are trialing DSP-enabled 100G PON optics to collapse metro aggregation layers into unified fiber platforms.
Industry Challenges
- Photonic integration talent scarcity:Module vendors face acute shortages of silicon photonics design engineers capable of bridging CMOS foundry processes with optical packaging.
- Multi-jurisdiction certification timelines:Simultaneous FCC Part 15, CE marking, and MIIT GB standard approvals extend product launch cycles by 8-14 months for new form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Transmission Module Market |
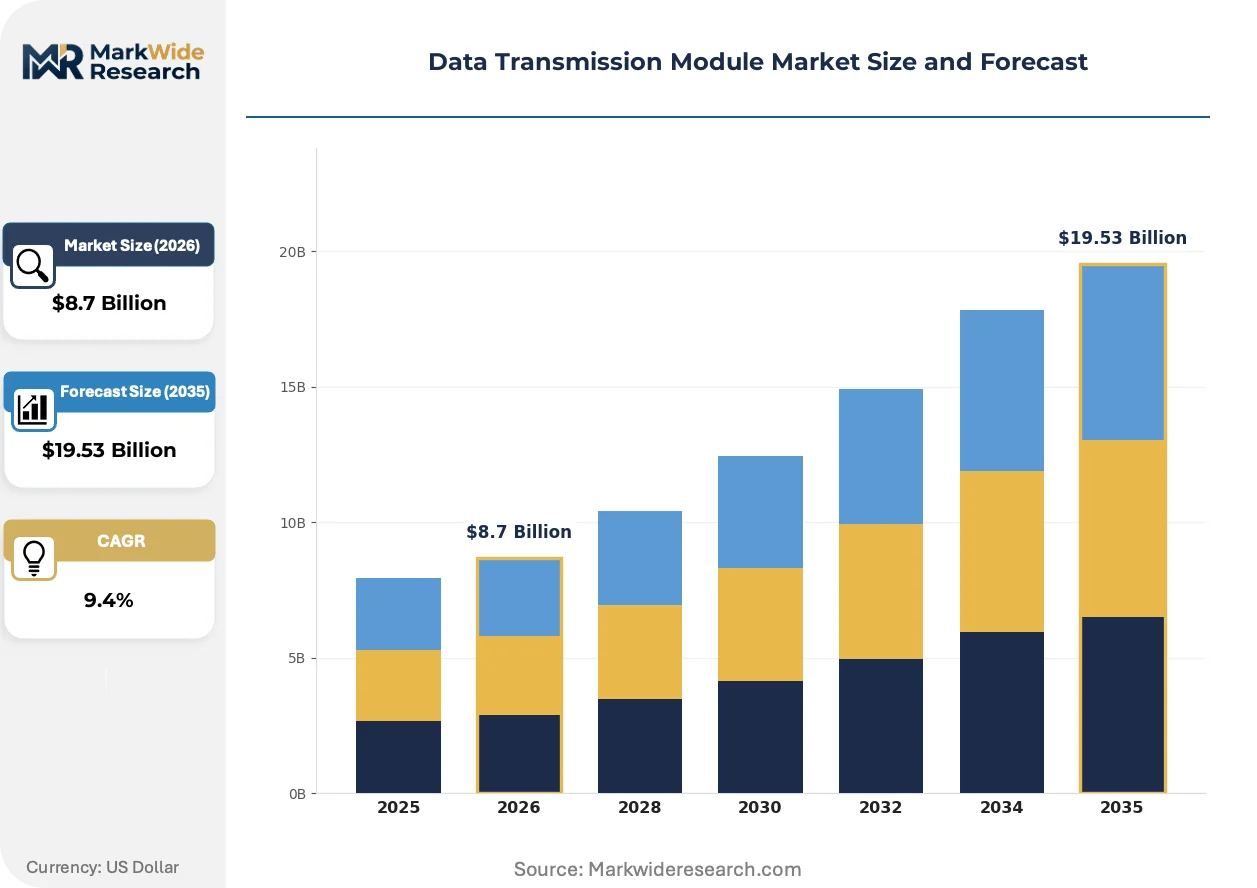
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RF Modules, Fiber Optic Modules, Ethernet Modules, Serial Communication Modules Technology: Wired Communication, Wireless Communication, Satellite Communication, Optical Communication End User: Telecommunications, Transportation, Healthcare, Industrial Automation Deployment: On-Premise, Cloud-Based, Edge Computing, Integrated Solutions |
| Companies Covered | Coherent Corp., INNOLIGHT, Accelink Technology Co. Ltd., Cisco Systems, Inc., Lumentum Operations LLC, Sumitomo Electric Industries, Ltd., Broadcom Inc., Hisense Broadband, Inc., Microchip Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Transmission Module Market Trends and Innovations
Silicon photonics is collapsing the cost curve for high-speed optical interconnects while coherent detection migrates from long-haul to access networks, rewiring competitive advantage toward foundry-scale manufacturing capabilities.
Linear pluggable optics is rewriting the power-performance tradeoff for data center switches by eliminating digital signal processors from the module, cutting thermal load by 30-40% compared to re-timed alternatives. Cloud operators at Meta and Google are qualifying these DSP-free designs for 800G deployment. This compression of module complexity is shifting value capture from fabless chip vendors to switch ASIC suppliers with integrated SerDes.
REACH substance restrictions are forcing reformulation of module housing alloys and underfill epoxies across European supply chains, with ECHA SVHC candidate list updates triggering annual bill-of-materials reviews. Vendors with captive materials characterization labs are compressing compliance response times. The automotive and industrial segments face the steepest redesign burdens given their 10-15 year qualification cycles.
Hyperscalers are consolidating optical module procurement through direct sourcing relationships that bypass traditional distributor channels, concentrating annual contract value among three to four qualified suppliers per speed class. This channel compression is visible most acutely in North American cloud regions where Microsoft, Amazon, and Google account for the majority of 400G+ volume. Remaining distributors are pivoting toward value-added services including burn-in testing and forward logistics for edge deployments.
Data Transmission Module Market Segmentation
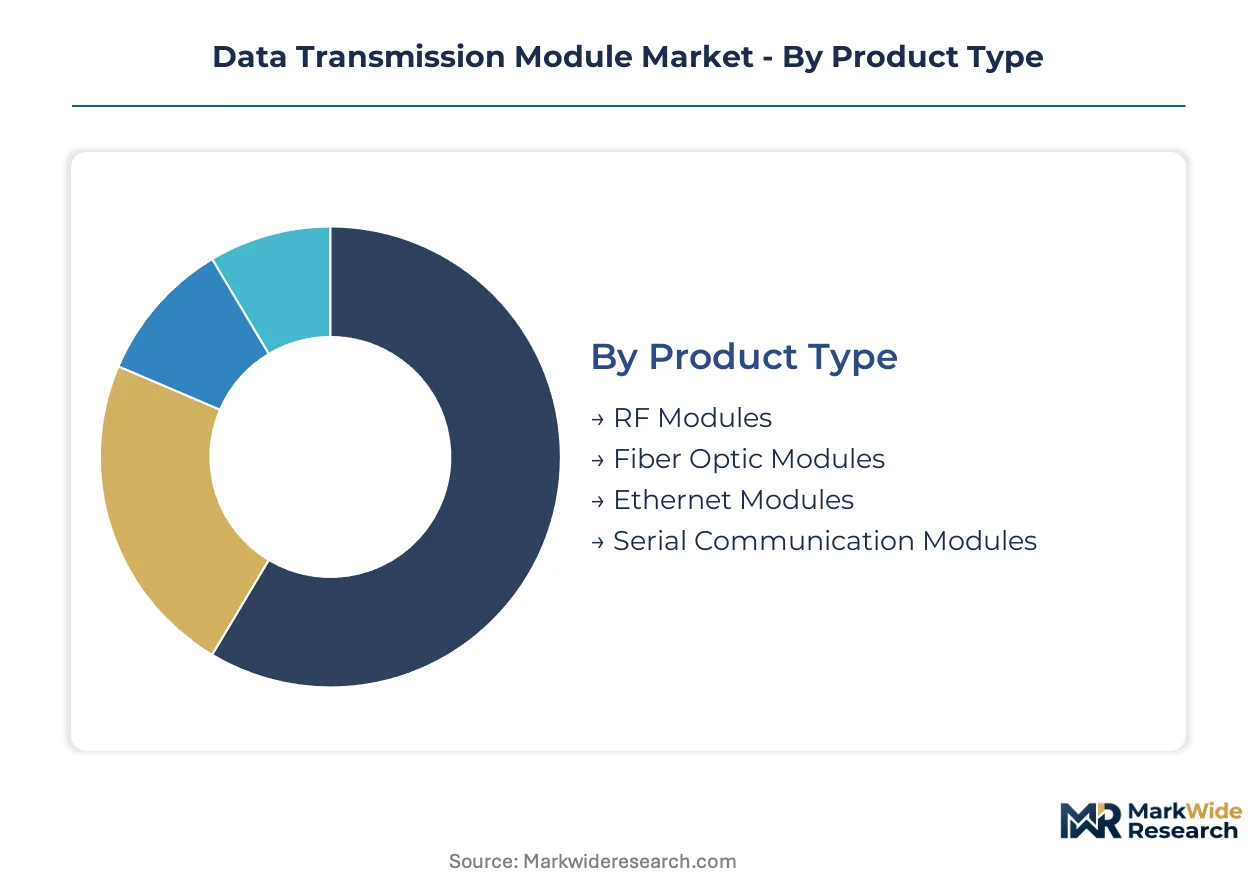
Data transmission module procurement patterns diverge sharply across product architectures, with fiber and RF technologies commanding distinct supply chain ecosystems. Understanding these segment boundaries clarifies where vendor specialization creates sustainable margin structures versus commodity exposure.
Product Type:
Supply concentration clusters around fiber optic and Ethernet portfolios, where III-V semiconductor fabrication and silicon photonics foundry access determine competitive viability.
- Fiber Optic Modules:These assemblies integrate laser diodes, photodetectors, and waveguide packaging into pluggable form factors for single-mode and multimode fiber. Data center interconnects in Ashburn, Virginia and Frankfurt, Germany absorb the highest volume, driven by cloud hyperscaler spine-leaf architecture standardization.
- Ethernet Modules:Copper and optical PHY implementations supporting 10G through 800G signaling rates with auto-negotiation and forward error correction. Enterprise campus networks in Japan and South Korea are upgrading access layer switches, pulling demand for 2.5G and 5G BASE-T modules.
- RF Modules:Radio-frequency transceivers for sub-6 GHz and mmWave spectrum with integrated power amplifiers and beamforming arrays.
- Serial Communication Modules:RS-232, RS-485, and CAN bus interfaces for industrial controllers and automotive ECUs.
Fiber optic modules absorb the bulk of installed capacity; Ethernet modules are expanding most quickly.
Technology:
Cost tier differentiation separates mature copper implementations from emerging photonic integration platforms requiring specialized packaging infrastructure.
- Optical Communication:Coherent and direct detection schemes using silicon photonics or indium phosphide platforms for 100G to 800G channels. Metro aggregation networks in China and long-haul routes across the Atlantic corridor are deploying 400G ZR+ coherent pluggables, pressured by traffic growth from video streaming and cloud storage.
- Wireless Communication:Cellular, Wi-Fi, and private 5G radio modules with integrated baseband processing. Factory automation deployments in Stuttgart, Germany and Detroit, Michigan are adopting 5G LAN modules to replace wired sensor networks, constrained by electromagnetic interference from high-voltage battery systems.
- Wired Communication:Copper-based Ethernet and serial protocols for short-reach connectivity.
- Satellite Communication:Ka-band and Ku-band terminals for geostationary and low-earth orbit constellations.
Optical communication absorbs the bulk of installed capacity; wireless communication is gaining share fastest.
End User:
Application-specific qualification cycles create divergent margin profiles, with automotive and medical segments demanding 10-15 year supply guarantees.
- Telecommunications:Carrier-grade optical transceivers for core, metro, and access networks with temperature-hardened specifications. 5G backhaul fiberization programs by Verizon and Deutsche Telekom are standardizing on 25G and 100G bi-directional optics for cell tower connectivity.
- Industrial Automation:Time-sensitive networking modules for programmable logic controllers and robotic systems. German automotive assembly plants in Wolfsburg and Munich are deploying TSN-enabled Ethernet modules to synchronize motion control across production lines.
- Transportation:In-vehicle and wayside communication for rail, aviation, and automotive applications.
- Healthcare:Isolated data links for imaging equipment and patient monitoring systems with FDA 510(k) and MDR compliance requirements.
Telecommunications absorbs the bulk of installed capacity; industrial automation is climbing the fastest.
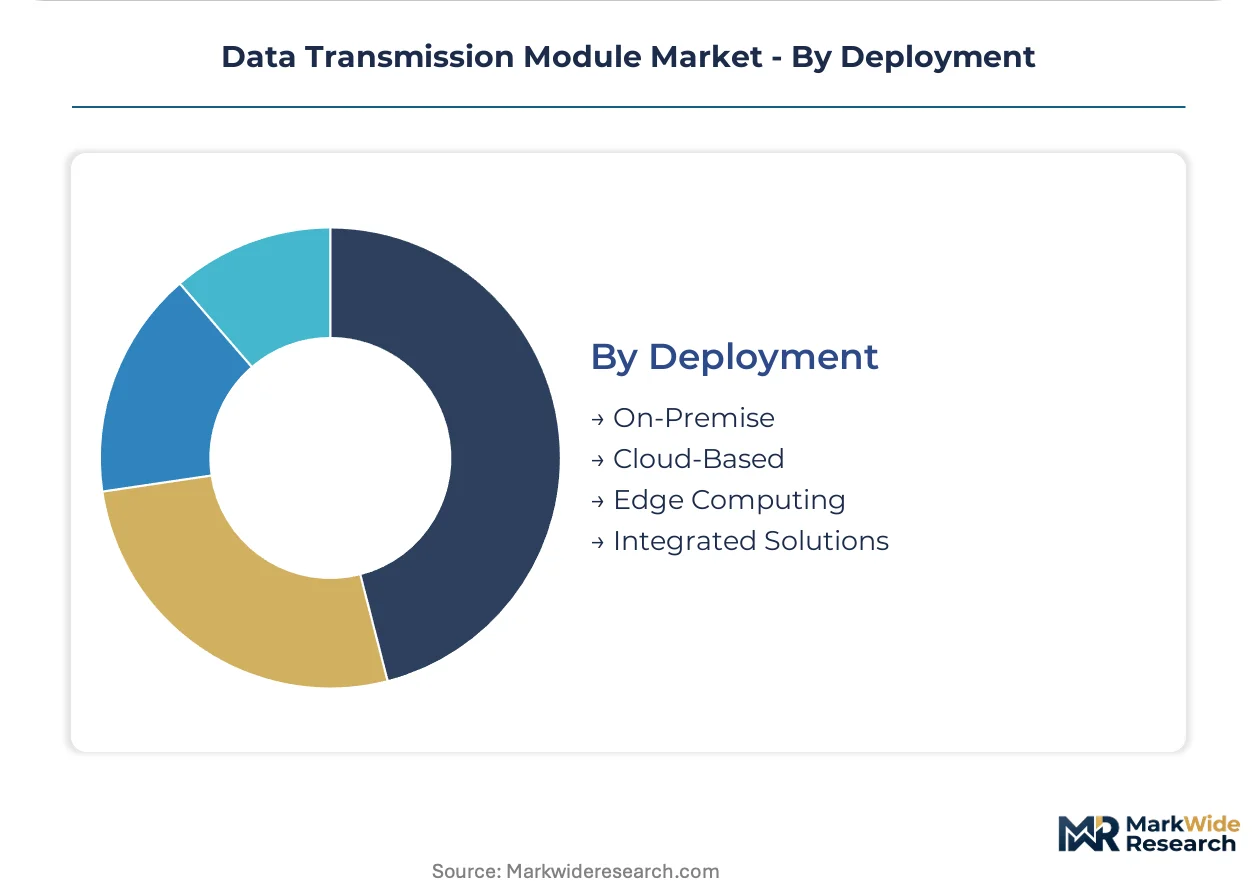
Deployment:
Customer type fragmentation separates hyperscale direct procurement from channel-mediated enterprise sales, with edge computing creating hybrid sourcing patterns.
- Cloud-Based:Massively parallel optical interconnects for hyperscale data centers with centralized procurement and custom form factors. Microsoft, Amazon, and Google facilities in Oregon, Ireland, and Singapore are qualifying 800G linear pluggable optics to reduce switch power consumption.
- Edge Computing:Distributed processing nodes requiring hardened modules for outdoor and industrial environments. Telefonica and Vodafone edge sites in Spain and the United Kingdom are deploying compact 100G coherent modules to collapse aggregation layers.
- On-Premise:Enterprise-owned infrastructure with traditional distributor channels and standard MSA modules.
- Integrated Solutions:Module subsystems bundled with switch ASICs or system-level platforms by original equipment manufacturers.
Cloud-based deployment absorbs the bulk of installed capacity; edge computing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of data transmission module procurement, with state-directed optical network buildouts reshaping supplier economics. The United States and Germany follow as centers of hyperscale data center deployment and industrial automation demand respectively.
China
MIIT's GB standards enforcement creates divergent certification pathways for optical and wireless transmission equipment. State-led investments in optical communication networks concentrate procurement power with domestic module manufacturers. Yangtze River Delta clusters in Suzhou and Wuhan host captive laser chip fabrication facilities serving national telecommunications infrastructure programs.
United States
FCC broadband infrastructure mandates accelerate module certification requirements for domestic suppliers targeting 5G backhaul fiberization. Cloud hyperscalers in Ashburn, Virginia and Hillsboro, Oregon standardize on 800G pluggable optics for spine-leaf architectures. Bureau of Industry and Security export controls on 400G+ coherent DSPs fragment supply chains for Chinese-facing procurement.
Germany
REACH substance restrictions force annual bill-of-materials reviews for module housing alloys and underfill epoxies. Factory automation deployments in Stuttgart and Wolfsburg adopt TSN-enabled Ethernet modules to synchronize motion control across automotive assembly lines. ECHA SVHC candidate list updates trigger compliance response investments among vendors with European distribution.
Japan
METI industrial policy supports domestic silicon photonics foundry capacity for high-speed optical engine production. Indium phosphide wafer fabrication clusters in Tokyo and Osaka create chokepoints for laser chip supply to global module assemblers. JIS standards alignment with international MSA specifications reduces friction for export-oriented manufacturers.
India
TRAI spectrum allocation frameworks and the PLI scheme for telecom equipment attract module assembly investments to serve domestic 5G and BharatNet rural fiber programs. Tamil Nadu and Karnataka industrial corridors host emerging optical packaging facilities targeting edge computing deployments. CDSCO medical device regulations impose parallel compliance burdens for healthcare-grade transmission modules.
Data Transmission Module Market Competitive Landscape
Chinese producers anchor the volume tier through state-linked procurement channels; US and Japanese specialists hold premium positions in coherent optics and silicon photonics. The vendor base organizes around three strategic archetypes: vertically integrated laser chip fabricators, fabless module assemblers with foundry partnerships, and captive hyperscale suppliers. Dominant competitive moves include backward integration into III-V semiconductor fabrication and strategic partnerships with cloud operators for custom form factor development.
Among US-based incumbents, Coherent Corp. exemplifies the vertically integrated archetype through captive laser chip fabrication and module assembly capabilities. Lumentum Operations LLC occupies a position within the optical communications specialist tier. Sumitomo Electric Industries, Ltd. represents Japanese industrial conglomerate participation with materials science heritage in compound semiconductors. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning across certification-intensive procurement environments.
| Leading Market Players |
|---|
| Coherent Corp. |
| INNOLIGHT |
| Accelink Technology Co. Ltd. |
| Cisco Systems, Inc. |
| Lumentum Operations LLC |
| Sumitomo Electric Industries, Ltd. |
| Broadcom Inc. |
| Hisense Broadband, Inc. |
| Microchip Technology Inc. |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler direct procurement consolidation in Ashburn, Virginia and Hillsboro, Oregon is compressing distributor margins and forcing module vendors to absorb qualification costs upfront, shifting pricing power toward buyers with multi-year volume commitments.
Pricing Analysis
Volume-margin splits separate commodity 10G-100G modules from premium 400G-800G coherent optics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and foundry partnership depth. Cost compression in the 25G-100G tier is intensifying because Chinese domestic suppliers are flooding procurement channels with state-subsidized production. Enterprise campus networks in Japan and South Korea show highest price sensitivity; cloud hyperscalers prioritize performance-per-watt over unit cost.
Supply Chain Analysis
Certification gating through FCC Part 15, CE marking, and MIIT GB standards fragments supplier qualification pools and extends production ramp timelines. III-V semiconductor fabrication clusters in Taiwan and Japan supply indium phosphide and gallium arsenide laser chips that module assemblers in China and the United States draw from. Single-source vulnerability concentrates in Tokyo-Osaka wafer fabrication for high-speed optical engines. Distribution runs through direct hyperscale contracts and value-added distributors serving edge computing deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics is displacing legacy indium phosphide platforms across data center interconnects, rewriting cost structures and supplier qualification requirements throughout the module ecosystem.
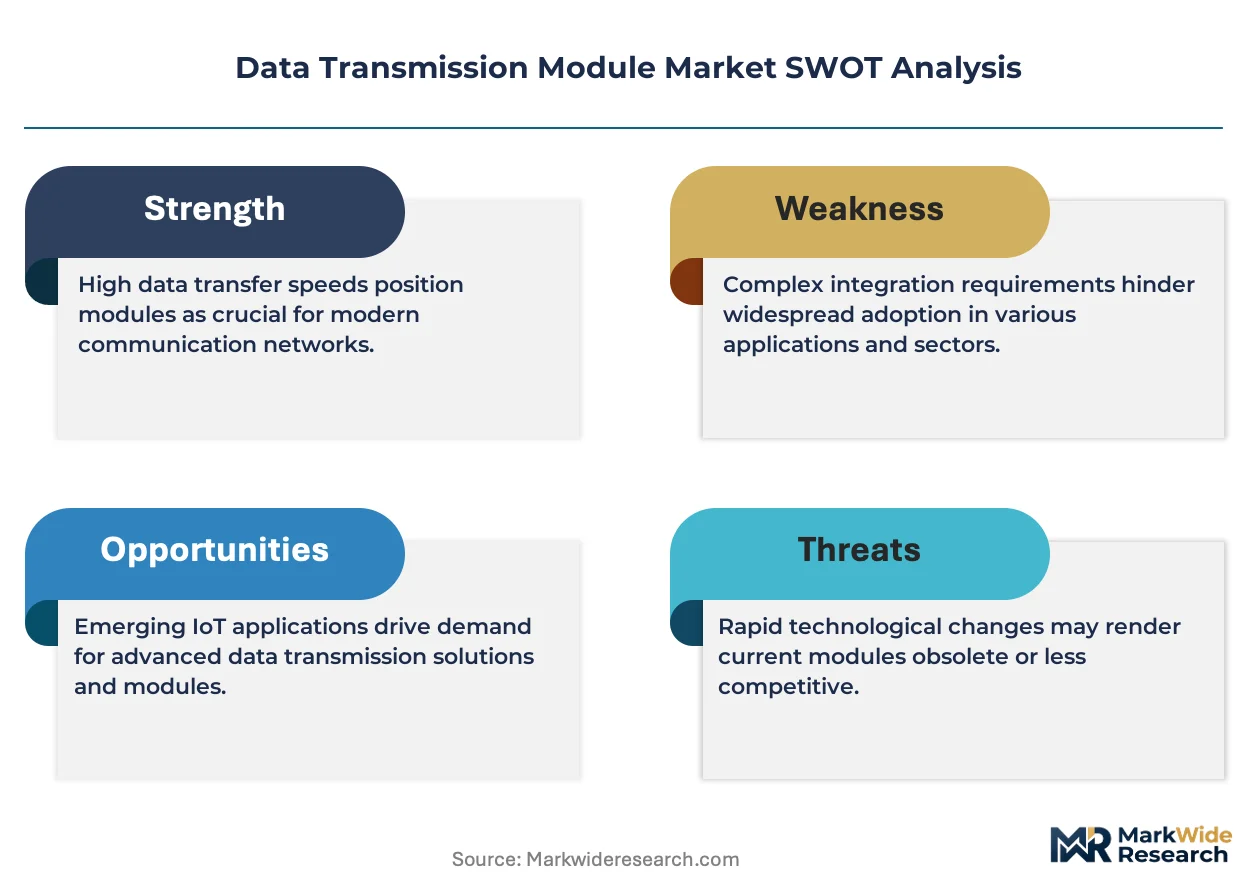
For Market Incumbents: Lock in hyperscale qualification slots for 800G linear pluggable optics before switch ASIC vendors integrate SerDes and bypass discrete module procurement. Secure captive III-V semiconductor supply through joint development agreements with Tokyo-Osaka fabrication clusters. Defend against DSP-free module architectures by accelerating co-packaged photonics roadmaps. For New Entrants and Emerging Players: Capture automotive optical networking opportunities in Stuttgart and Wolfsburg where electromagnetic isolation requirements favor multi-gigabit fiber links over copper alternatives. Target India's PLI scheme-aligned assembly corridors in Tamil Nadu and Karnataka for 5G backhaul module production. Lead with burn-in testing and forward logistics services to bypass hyperscale direct procurement barriers. For Investors and Strategic Acquirers: Re-rating potential sits with silicon photonics foundry-scale specialists given cloud hyperscaler capex inflection toward 800G spine-leaf buildouts. Long-term viability favors vendors with backward integration into laser chip fabrication and established MIIT GB certification pathways. Watch for Bureau of Industry and Security export control expansion on coherent DSPs as supply chain fragmentation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Investment | Coherent Corp. and Sumitomo Electric are scaling CMOS-compatible optical engine production to collapse 800G module cost curves. |
| Linear Pluggable Optics Qualification | Meta and Google are qualifying DSP-free designs that shift value capture from fabless chip vendors to switch ASIC suppliers. |
| REACH Compliance Material Reformulation | ECHA SVHC candidate list updates force annual bill-of-materials reviews for module housing alloys and underfill epoxies. |
| India PLI Scheme Alignment | Tamil Nadu and Karnataka corridors attract assembly investments targeting BharatNet rural fiber and domestic 5G programs. |
| Automotive Optical Backbone Development | Software-defined vehicle architectures in Wolfsburg and Stuttgart adopt multi-gigabit fiber links for electromagnetic isolation. |
Research Methodology
Document review covered FCC equipment authorization databases, ECHA SVHC candidate lists, MIIT GB standard filings, and hyperscaler capex disclosures, complemented by interviews with optical module procurement directors at cloud operators, silicon photonics design engineers, III-V semiconductor fabrication managers, and telecommunications infrastructure planners. Secondary validation drew from SEC 10-K filings, customs trade data, and industry association technical specifications. Bottom-up module shipment estimates triangulated against top-down optical interconnect demand projections.
Cross-referencing historical hyperscaler deployment patterns with panel input from equipment vendors established the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, technology platform, end-use application, and deployment customer type. CAGRs were derived from unit economics analysis of laser chip supply constraints and coherent DSP availability. Forecast inputs incorporated FCC broadband infrastructure mandate timelines and REACH substance restriction phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Bureau of Industry and Security export control expansion and silicon photonics yield improvement trajectories. Model outputs reflect assumptions regarding III-V semiconductor supply continuity and hyperscaler architecture standardization. A model refresh is warranted upon material change in cloud operator spine-leaf upgrade cadence or MIIT GB standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
Zigbee Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Bluetooth Low Energy Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Time-Of-Flight Chip Market