
 Zigbee Market | 2026-2036
Zigbee Market Size, Share, and Industry Trends Forecast 2026-2036
Zigbee Market Intelligence
The European Union's Cyber Resilience Act is decoupling market access from pure device functionality, instead tying it to verifiable cybersecurity standards. This shift elevates the importance of secure-by-design chipsets and software stacks. Silicon Laboratories Inc. specializes in low-power wireless system-on-chip solutions, providing a core technology for many Zigbee device makers. NXP Semiconductors N.V. leverages its extensive portfolio to serve demanding industrial and automotive IoT applications where reliability is paramount.
Zigbee is a specification for a suite of high-level communication protocols using low-power digital radios based on the IEEE 802.15.4 standard. It operates in unlicensed frequency bands, including 2.4 GHz, to create robust mesh networks for device-to-device communication. The primary purpose is enabling reliable, low-data-rate wireless monitoring and control in Internet of Things applications. Chipsets and modules represent the fundamental product segments, providing the core hardware for device integration. Within applications, smart lighting and building automation are mature, high-volume drivers of demand.
Compliance frameworks from the US Federal Communications Commission (FCC) and the EU's Radio Equipment Directive (RED) govern radio frequency emissions and market access. The Connectivity Standards Alliance (CSA) manages the Zigbee protocol itself, ensuring interoperability through certification programs. These standards create a baseline for device performance and safety. For semiconductor firms and device manufacturers, the strategic imperative is balancing investment between supporting the existing Zigbee ecosystem and preparing for the convergence with newer interoperability standards.
Market Dynamics
The central force shaping the Zigbee market is the technological convergence with the Matter protocol. This shift toward a unified application layer standardizes device communication, creating pressure on vendors to ensure forward compatibility while supporting a massive installed base of legacy Zigbee devices.
Growth Catalysts
- Smart Building Mandates:The European Union's Energy Performance of Buildings Directive (EPBD) encourages building automation for energy efficiency, directly stimulating demand for Zigbee-based lighting, HVAC, and sensor controls in commercial and residential retrofits.
- Chinese Smart City Projects:Large-scale urban development initiatives across China rely on low-power mesh networks for public infrastructure monitoring, including smart street lighting and environmental sensing, creating massive volume demand for Zigbee modules.
- Industrial IoT Expansion:The adoption of Zigbee in industrial environments for predictive maintenance and asset tracking is expanding its footprint beyond home automation, leveraging its low power consumption for battery-operated sensors on factory floors.
Market Restraints
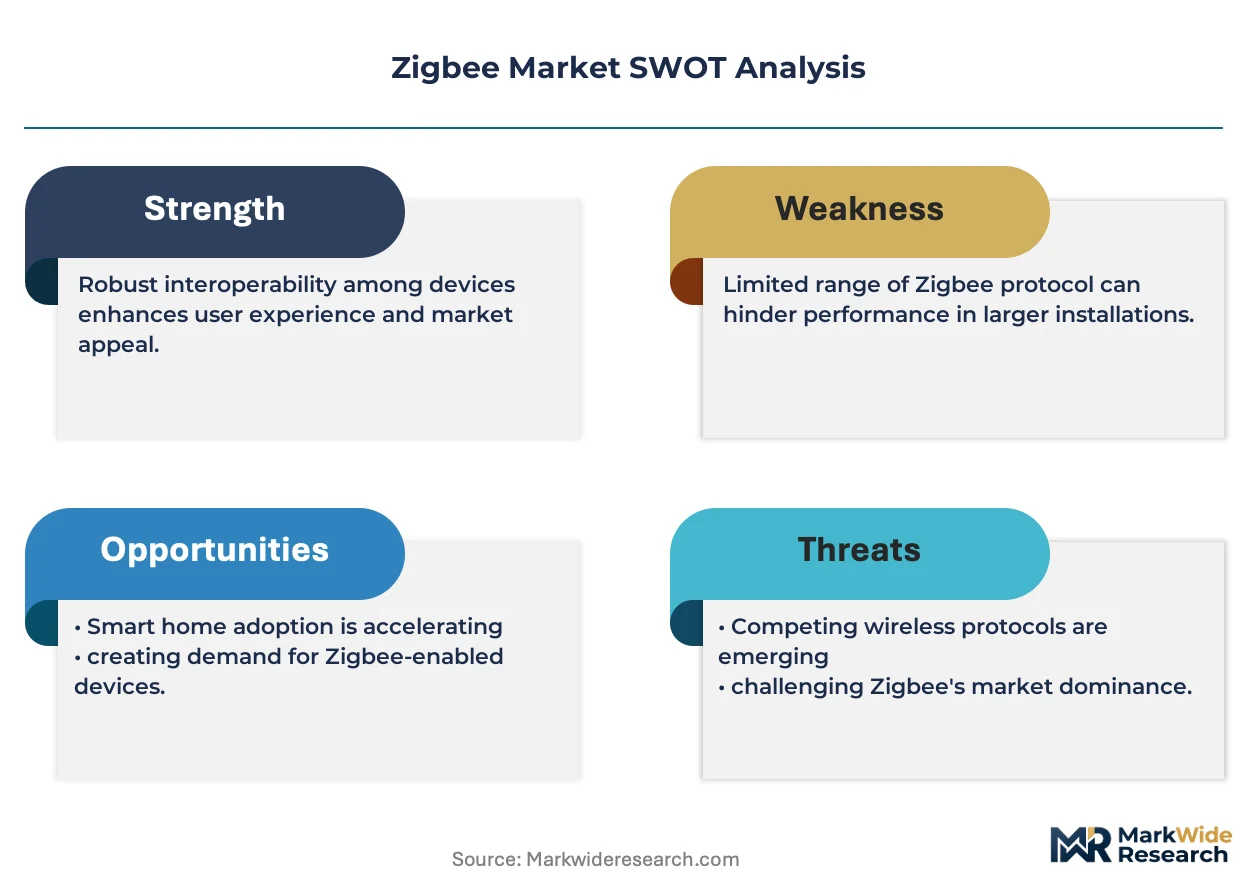
- Protocol Competition:Alternative low-power, wide-area network (LPWAN) technologies like LoRaWAN and NB-IoT present a substitution threat in applications where long-range communication is more critical than high-density mesh networking, such as in agriculture or logistics.
- Bandwidth Limitations:The IEEE 802.15.4 standard, upon which Zigbee is based, has inherent data rate limitations that make it unsuitable for high-bandwidth IoT applications like security cameras, confining its use to control and sensor data.
- Network Scalability:While effective in smaller deployments, ensuring stability, managing routing, and minimizing latency in very large-scale or dense Zigbee mesh networks with thousands of nodes remains a significant technical and implementation complexity.
Strategic Opportunities
- Unified Smart Home Fabric:Integration with the Matter protocol over Thread provides an opportunity for Zigbee to become a foundational technology within a broader, interoperable smart home ecosystem, extending its relevance and market access.
- Remote Healthcare and Assisted Living:Zigbee's low power and reliability are well-suited for battery-powered medical sensors and personal emergency response systems, opening a significant market in remote patient monitoring and elder care technology.
- Emerging Market Penetration:Markets in Southeast Asia and Latin America, where smart home and building automation adoption is still in early stages, offer new growth frontiers for Zigbee devices beyond the more mature markets of North America and Europe.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is ensuring seamless backward compatibility and interoperability between new Matter-enabled Zigbee devices and the extensive installed base of older, non-upgradable Zigbee products in homes and buildings.
- Dual Certification Complexity:Device manufacturers face increased development time and cost navigating the parallel certification processes required by both the Connectivity Standards Alliance for Zigbee protocol compliance and for the new Matter standard.
- Secure Firmware Management:The secure and reliable delivery of over-the-air (OTA) firmware updates across large, heterogeneous Zigbee mesh networks presents a persistent operational challenge for vendors, critical for patching security vulnerabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zigbee Market |
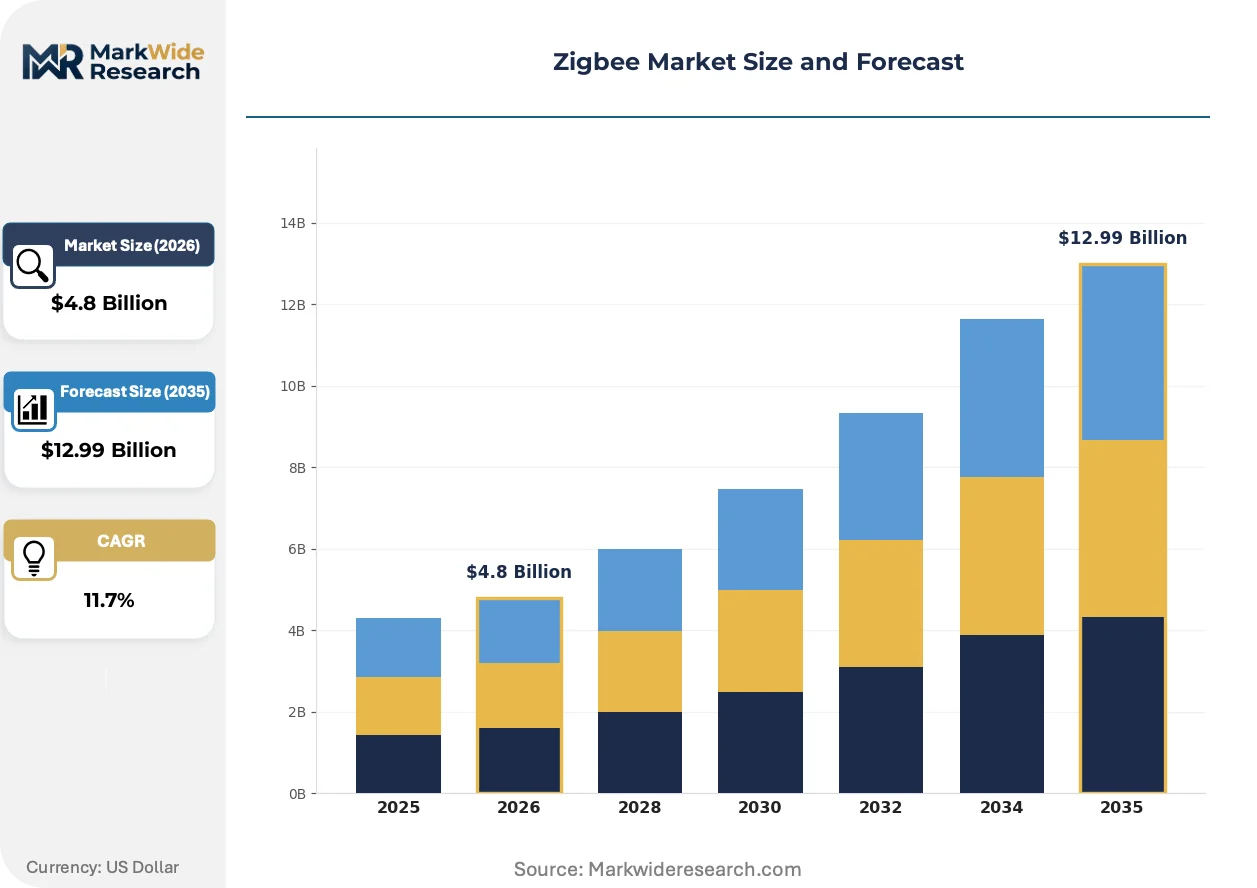
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chipsets, Modules, Routers, Gateways, Controllers Application: Smart Lighting, Building Automation, Smart Metering, Environmental Monitoring, Smart Agriculture End User Industry: Commercial Facilities, Energy Management Firms, Agriculture Enterprises, Residential Complexes, Hospitality Venues Deployment Mode: Standalone Networks, Integrated Systems, Cloud-Connected Networks, Hybrid Configurations |
| Companies Covered | Microchip Technology Inc., Qualcomm Incorporated, Silicon Laboratories Inc., STMicroelectronics N.V., Intel Corporation, Texas Instruments Incorporated, Digi International Inc., Telink Semiconductor, NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zigbee Market Strategic Shifts & Innovations
Protocol evolution is redefining device commissioning and user experience within the Zigbee ecosystem. The market is shifting from a collection of siloed, single-protocol devices toward an integrated fabric where interoperability, driven by standards like Matter, dictates value and competitive positioning.
Zigbee Direct is a key product innovation that simplifies device onboarding. It enables direct communication between a new Zigbee device and a commissioning device, like a smartphone, using Bluetooth Low Energy for initial setup. Smart home product manufacturers are rapidly adopting this feature to improve the out-of-box experience. This hub-less commissioning model is overtaking the traditional gateway-centric setup process for many consumer-facing applications.
Regulatory scrutiny over unlicensed spectrum is increasing globally. In China, the Ministry of Industry and Information Technology (MIIT) is enforcing stricter GB standards for devices operating in the 2.4 GHz band to mitigate interference. This action is forcing chipset and device makers to invest in improved radio frequency performance and more rigorous testing. The high-volume smart lighting and home appliance segments are most affected, requiring compliance to maintain market access.
Ecosystem-centric purchasing is displacing feature-based decision-making for end-users. Consumers and commercial buyers now prioritize a device's ability to integrate within a broader smart platform, such as those compatible with the Matter standard. This behavioral shift disrupts the market for standalone Zigbee products, compelling vendors to seek certification and partnerships with major ecosystem providers. This trend is most pronounced in the saturated smart home markets of North America and Western Europe.
Zigbee Market Segmentation
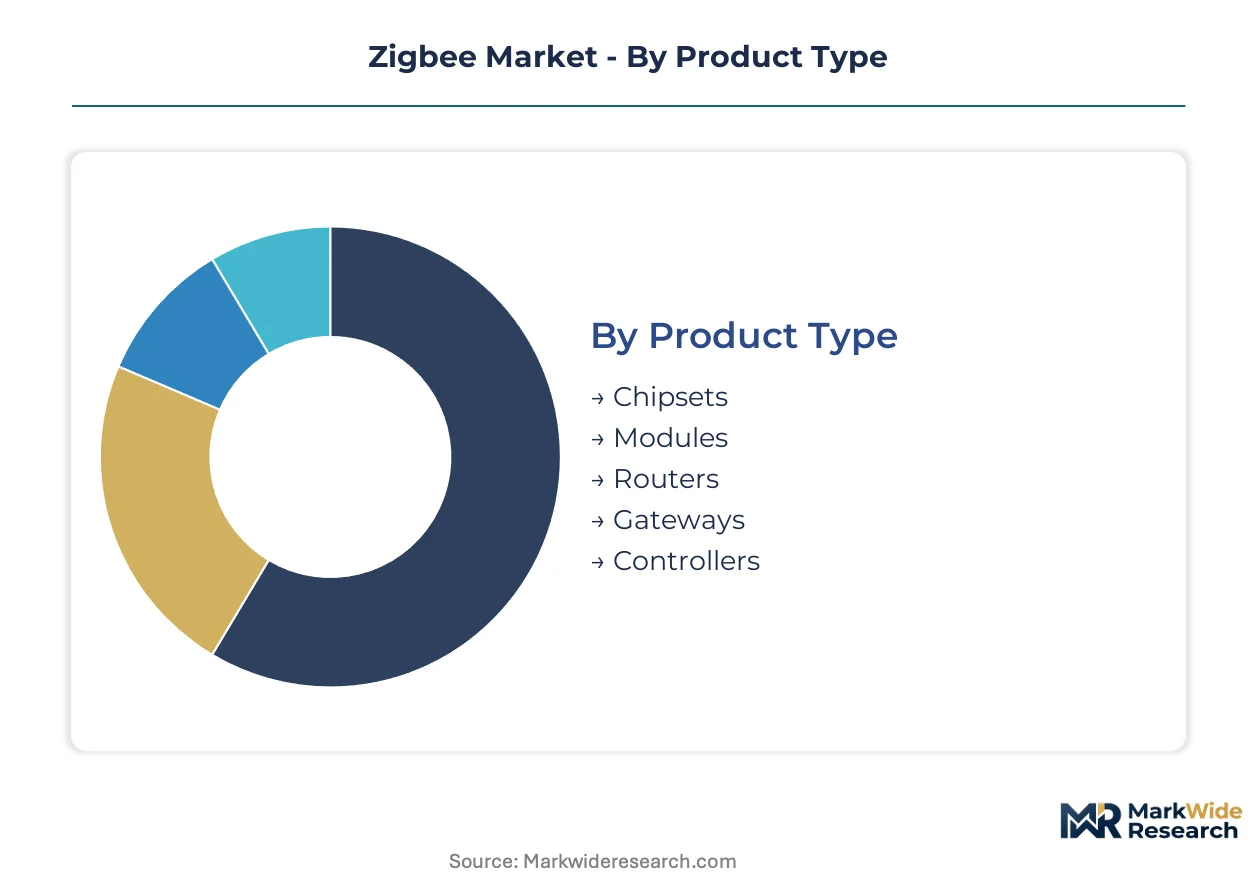
The Zigbee market's structure reflects the diverse technical requirements and application contexts for low-power wireless communication. Understanding these distinct segments is crucial for manufacturers and developers aiming to optimize product strategies and market penetration.
Product Type:
The technical foundation of Zigbee networks is built upon distinct product types, each fulfilling specific roles in device communication and control.
- Chipsets:These are the fundamental integrated circuits providing the core radio frequency and microcontroller capabilities for Zigbee devices. Silicon Laboratories Inc. and NXP Semiconductors N.V. supply these components, which are essential for original equipment manufacturers in China's consumer electronics sector.
- Modules:Pre-certified, self-contained units integrating a Zigbee chipset with necessary components like antennas and memory, offering quicker time-to-market for device makers. Demand for these is concentrating in Europe for building automation retrofits due to stringent energy efficiency mandates.
- Routers:Devices that extend the range of a Zigbee network by relaying data between other devices and the coordinator.
- Gateways:Central hubs that connect Zigbee networks to other communication protocols like Wi-Fi or Ethernet, providing internet access and cloud connectivity.
- Controllers:User interface devices, such as remote controls or wall switches, used to manage and interact with Zigbee-enabled devices.
Mature deployment sits with Chipsets. Newer deployment is concentrated in Modules.
Application:
Demand for Zigbee technology is segmented by its diverse applications, reflecting varying volume requirements across sectors.
- Smart Lighting:This application involves Zigbee-enabled bulbs, switches, and fixtures for energy-efficient, controllable illumination in residential and commercial settings. The European Union's Energy Performance of Buildings Directive directly stimulates high-volume demand.
- Building Automation:Zigbee facilitates control of HVAC systems, access control, and environmental sensors within commercial facilities and smart city infrastructure. Large-scale urban development initiatives across China create massive volume demand.
- Smart Metering:Utilized for wirelessly transmitting utility consumption data from electricity, gas, and water meters to service providers.
- Environmental Monitoring:Involves sensors for tracking temperature, humidity, air quality, and other environmental parameters in various indoor and outdoor environments.
- Smart Agriculture:Employs Zigbee for sensor networks monitoring soil conditions, irrigation systems, and livestock health in agricultural settings.
Smart Lighting applications are expanding most quickly. Smart Agriculture applications are also gaining significant share.
End User Industry:
The end-user industries adopting Zigbee solutions vary significantly, driven by distinct customer needs and operational scales.
- Commercial Facilities:This segment includes offices, retail spaces, and industrial complexes deploying Zigbee for building management, energy efficiency, and asset tracking. Companies in this sector prioritize robust, scalable mesh networks for large-scale operations.
- Residential Complexes:Encompasses individual homes and multi-dwelling units where Zigbee powers smart home devices for convenience, security, and energy management. Integration with the Matter protocol enhances interoperability within these environments.
- Energy Management Firms:These entities leverage Zigbee for smart grid applications, demand response, and remote monitoring of energy infrastructure.
- Agriculture Enterprises:Farms and agricultural businesses use Zigbee for precision agriculture, including sensor networks for crop monitoring and automated irrigation.
- Hospitality Venues:Hotels and resorts implement Zigbee for smart room controls, energy savings, and enhanced guest experiences.
Commercial Facilities demonstrate high adoption rates. Hospitality Venues show increasing interest for guest experience enhancements.
Deployment Mode:
Zigbee deployment modes reflect different architectural approaches, ranging from localized control to extensive cloud integration.
- Standalone Networks:These deployments operate independently without external internet connectivity, providing localized control for devices within a confined Zigbee mesh. Such networks are common in smaller smart home setups.
- Integrated Systems:Zigbee networks that seamlessly connect and interoperate with other smart home or building management systems, often through a central hub or gateway. These systems are crucial for unified smart home fabrics, especially with Matter protocol convergence.
- Cloud-Connected Networks:These deployments link Zigbee devices to cloud platforms for remote monitoring, data analytics, and advanced automation features.
- Hybrid Configurations:Combinations of standalone, integrated, and cloud-connected elements, designed to optimize performance, security, and cost for specific application needs.
Integrated Systems remain a prevalent deployment choice. Cloud-Connected Networks are driving future scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen Special Economic Zone in China drives significant concentration for Zigbee manufacturing and innovation. This zone benefits from a robust ecosystem of consumer electronics and smart device production. Global demand for Zigbee technology finds a significant supply base in such strategically designated areas.
China
China's extensive smart city initiatives and consumer electronics manufacturing base create substantial Zigbee demand. The Ministry of Industry and Information Technology (MIIT) enforces stricter GB standards for 2.4 GHz devices. Manufacturers in the Yangtze River Delta actively integrate Zigbee into high-volume smart lighting and home appliance segments.
United States
United States demand for Zigbee solutions stems from mature smart home markets and expanding industrial IoT deployments. The US Federal Communications Commission (FCC) ensures compliance for radio frequency emissions. Silicon Valley continues to drive innovation for advanced Zigbee chipsets and integrated smart home platforms.
Germany
Germany's building automation sector and energy efficiency mandates fuel strong demand for Zigbee-based HVAC and lighting controls. The European Union's Cyber Resilience Act elevates secure-by-design chipsets. Companies in Bavaria are integrating Zigbee into advanced industrial IoT applications and smart factory solutions.
India
India exhibits growing interest in Zigbee for its burgeoning smart home market and initial smart city developments. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for electronic devices. Bengaluru's technology hub actively develops localized IoT solutions, leveraging Zigbee for cost-effective connectivity.
Japan
Japanese industrial IoT applications and smart factory automation drive significant Zigbee adoption, alongside elder care technology. The Ministry of Internal Affairs and Communications (MIC) regulates radio equipment. Tokyo's dense metropolitan area serves as a key hub for Zigbee R&D and integration into consumer electronics.
Zigbee Market Key Industry Players
Chinese producers anchor one tier of the Zigbee market, focusing on high-volume, cost-effective module manufacturing; US-based specialists hold significant positions in advanced chipset design. The market structure exhibits a tiered consolidation, with established semiconductor giants competing with agile, niche IoT solution providers. Strategic archetypes include integrated silicon vendors, module assemblers, and full-stack IoT platform developers. Portfolio diversification into broader IoT standards and strategic partnerships are dominant competitive moves.
Among integrated silicon vendors, Silicon Laboratories Inc. exemplifies a strong focus on low-power wireless system-on-chip solutions, providing core technology that many Zigbee device makers utilize. NXP Semiconductors N.V. leverages its extensive semiconductor portfolio, serving demanding industrial and automotive IoT applications where device reliability and robust performance are paramount considerations. Qualcomm Incorporated occupies a significant position within the market as a diversified technology provider, offering solutions that extend across various wireless communication standards and broader IoT ecosystems, influencing next-generation interoperability.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| Qualcomm Incorporated |
| Silicon Laboratories Inc. |
| STMicroelectronics N.V. |
| Intel Corporation |
| Texas Instruments Incorporated |
| Digi International Inc. |
| Telink Semiconductor |
| NXP Semiconductors N.V. |
| Others |
Cost & Logistics Intelligence
The European Union's Energy Performance of Buildings Directive (EPBD) gates qualified supply for Zigbee components by mandating energy efficiency in building automation, thereby supporting premium-tier pricing for compliant modules and systems. This directive incentivizes secure-by-design chipsets and robust software stacks.
Pricing Analysis
Lead-time-driven pricing currently offers premiums for short delivery schedules, while spot inventory is subject to discounts, particularly for high-volume consumer electronics components. The dominant pricing structure is per-unit transactional, often with contract-based pricing for large enterprise deployments. Price differentiation stems from certification level, particularly for CSA and Matter compliance, and the quality grade required for industrial versus consumer applications. Pricing pressure originates from the proliferation of Chinese producers offering cost-effective modules, impacting standard-tier segments. Commercial facilities prioritize reliability and certified performance, making them less price-sensitive than residential complex developers.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream distribution of Zigbee components and modules, ensuring efficient delivery to diverse end-user industries. Geographic supply concentration for chipsets and modules centers on China's Shenzhen Special Economic Zone and the US's Silicon Valley. The market depends on raw materials such as silicon wafers, specialized passive components, and advanced packaging materials. A key structural risk is single-source vulnerability for highly specialized chipsets, particularly those integrating advanced security features. The dominant distribution model involves direct sales to large OEMs and indirect sales through specialized electronics distributors serving smaller integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Zigbee market presents a compelling cost-of-compliance story, where the EU's Cyber Resilience Act creates a significant barrier-to-entry moat for compliant players. This regulation ensures that only devices meeting stringent cybersecurity standards gain market access.
For Market Incumbents: To counter protocol competition from alternative LPWAN technologies like LoRaWAN, incumbents should deepen investment in Matter protocol integration for their existing Zigbee product lines. Strategic partnerships with major smart home ecosystem providers will also reinforce market position against emerging challengers. Focusing R&D on secure-by-design chipsets, as mandated by the EU's Cyber Resilience Act, enhances product differentiation and compliance.
For New Entrants and Emerging Players: Launch via ecosystem-centric partnerships within specific underpenetrated segments, such as remote healthcare and assisted living, offers a viable entry point. The most penetrable segment is smart agriculture in emerging markets, leveraging Zigbee's low power consumption for sensor networks. Developing Zigbee Direct-enabled devices provides a strong go-to-market angle by simplifying device onboarding and improving user experience for consumers.
For Investors and Strategic Acquirers: Widespread adoption of Matter protocol in building automation is the leading indicator that Zigbee has solidified its foundational role within the broader IoT ecosystem. Long-term viability rests on the continued convergence of Zigbee with unified standards and its expansion into industrial IoT applications. Acquisition targets should be agile, niche IoT solution providers with strong Matter certification portfolios or module assemblers demonstrating rapid compliance with evolving regulatory standards. The signal to watch is the rate of Matter-certified Zigbee device releases and their market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Matter | Ensures forward compatibility and broad market access within a unified smart home ecosystem. |
| Strategic Partnerships with Ecosystems | Expands market reach and accelerates adoption by aligning with major smart home platforms. |
| Acquisition of Specialist Firms | Gains expertise in niche applications or advanced security features, strengthening product portfolios. |
| Geographic Expansion into Emerging Markets | Captures new demand in regions with nascent smart home and building automation sectors. |
| Product Launch of Zigbee Direct Devices | Simplifies user onboarding and enhances out-of-box experience, driving consumer adoption. |
Research Approach
Document review covered IEEE 802.15.4 standards, Connectivity Standards Alliance certification documents, and regulatory compliance reports from the FCC and EU RED, complemented by interviews. Primary research involved discussions with chipset developers, device manufacturers, building automation integrators, and smart city project managers. This approach ensured a balanced perspective, triangulating insights from both bottom-up market activity and top-down regulatory frameworks.
Volume and value outputs were generated through a quantitative model that projects market size and growth across the analysis window. This framework integrated segmentation dimensions including product type, application, end-user industry, deployment mode, and regional adoption patterns. Compound annual growth rates were derived through regression analysis, factoring in market share shifts and technological adoption curves. Key forecast inputs included smart city project pipelines in China and building retrofit mandates in the European Union.
Geopolitical trade policies, unforeseen technological disruptions, and shifts in regulatory enforcement are the dominant revision risks for these market projections. Forecasts reflect assumptions documented regarding Matter protocol adoption and the pace of industrial IoT expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
Ethernet Phys Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market