
 Wifi Chip Market | 2026-2036
Wifi Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Wifi Chip Market Insights
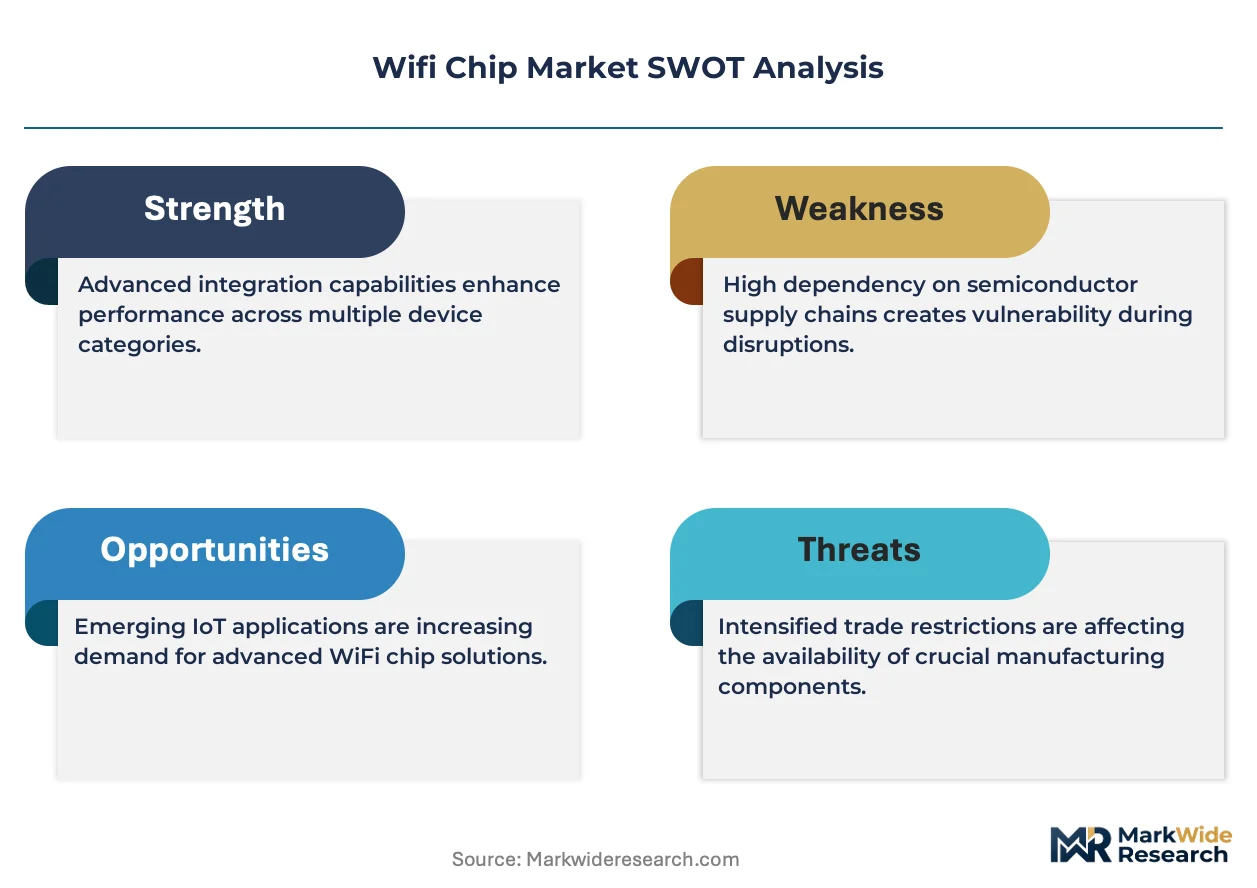
RF engineering talent scarcity across Taiwan and South Korea is reorganizing foundry allocation priorities for advanced node production. Qualcomm Technologies Inc. leverages its integrated baseband-WiFi design to dominate premium smartphone sockets. Broadcom Inc. sustains leadership in router and access point silicon through deep OEM partnerships. MediaTek Inc. competes aggressively on cost-engineered 802.11ax solutions for mid-tier consumer devices.
A WiFi chip is a semiconductor integrated circuit that modulates and demodulates radio frequency signals in the 2.4 GHz, 5 GHz, and 6 GHz unlicensed bands, typically fabricated on 12-inch CMOS wafers with integrated power amplifiers and switch components, enabling wireless local area network connectivity for data transmission. Its primary commercial purpose is to provide standardized, low-latency wireless connectivity infrastructure across consumer, enterprise, and industrial hardware platforms. The 802.11ax product category anchors current revenue as infrastructure refresh cycles accelerate, while 802.11ac maintains volume in cost-sensitive emerging markets. Beamforming and OFDMA technology segments capture expanding margin pools as enterprise access points and industrial gateways demand spatial stream optimization for dense device environments.
The FCC in the United States, ETSI in Europe, and Japan's MIC govern spectrum access and emission standards that directly determine which frequency bands each chip SKU can legally activate, forcing manufacturers to maintain region-specific certification inventories. China's MIIT and South Korea's MSIT impose additional domestic testing protocols that extend time-to-market for foreign suppliers. Stakeholders must monitor 6 GHz band harmonization progress across regulators to anticipate which product architectures warrant R&D commitment versus geographic segmentation.
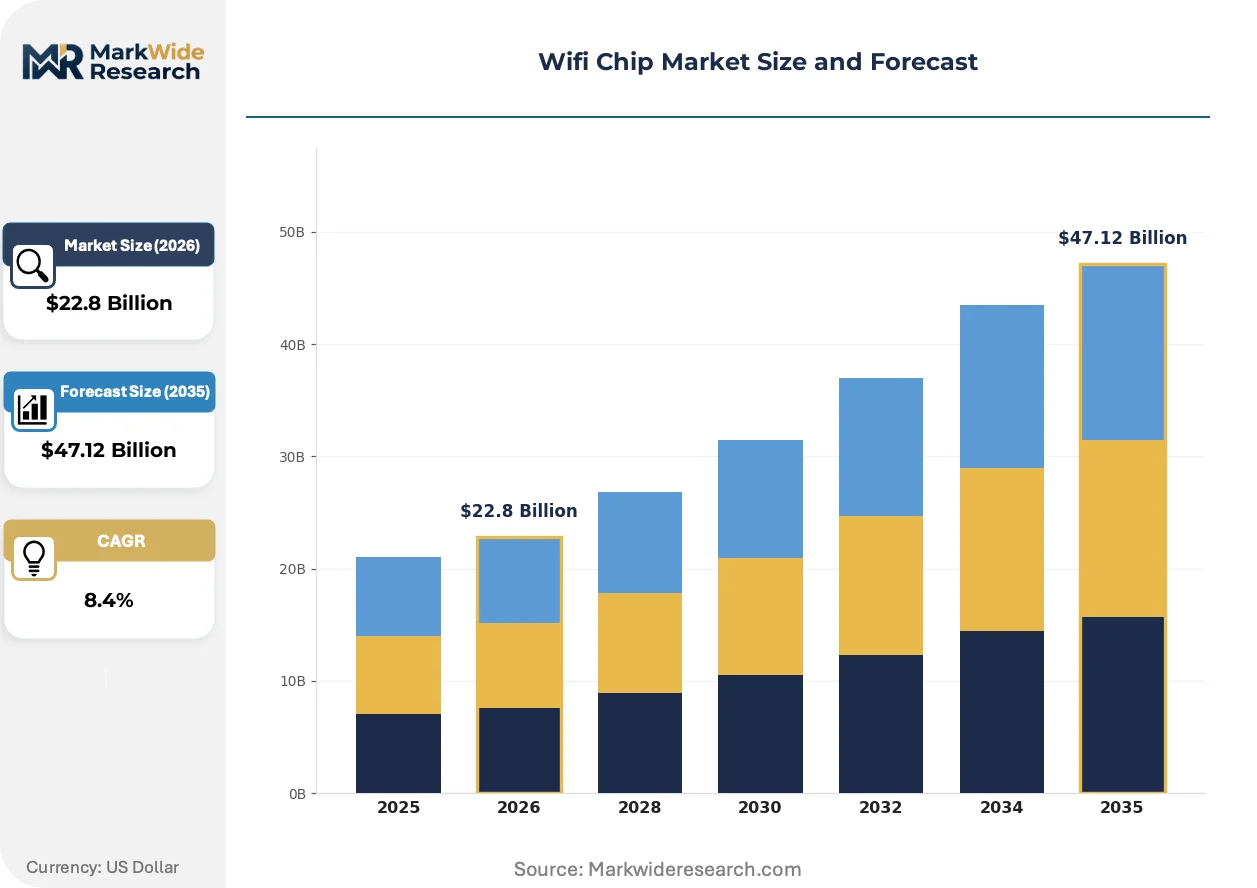
Market Dynamics
Wi-Fi 6E spectrum expansion is compressing refresh cycles across enterprise infrastructure, forcing foundries to reallocate 12-inch CMOS capacity toward tri-band architectures while smartphone OEMs and industrial integrators compete for allocation priority.
Growth Catalysts
- 6 GHz Spectrum Liberalization:FCC rulings in the United States, alongside parallel allocations by Germany's BNetzA and Japan's MIC, unlock 1200 MHz of contiguous bandwidth for high-throughput applications. Enterprise access point manufacturers are certifying tri-band SKUs to capture this capacity.
- Industrial Automation Density:Factory floor wireless sensor networks in China's Yangtze River Delta and Pearl River Delta are driving module assembly scale for 802.11ax gateways. Automotive OEMs in Stuttgart and Detroit are specifying Wi-Fi 6E for over-the-air update infrastructure.
- OFDMA Latency Reduction:Orthogonal frequency-division multiple access technology enables simultaneous low-latency transmission to hundreds of endpoints. Smart building integrators in Singapore and Dubai are specifying this for elevator control and HVAC mesh networks.
Market Restraints
- RF Engineering Talent Scarcity:Taiwan and South Korea face acute shortages of millimeter-wave design specialists, constraining foundry expansion for advanced node RF-CMOS processes. Foundry booking lead times for 28nm RF extend beyond eighteen months.
- Regional Certification Fragmentation:China's MIIT mandates domestic SAR testing protocols that add four to six months to foreign supplier time-to-market. South Korea's MSIT imposes additional KC mark requirements for 6 GHz power spectral density limits.
- Silicon Germanium Cost Volatility:Power amplifier integration depends on SiGe BiCMOS substrates subject to germanium concentrate price swings. Module assemblers in Vietnam and Mexico face margin compression when raw material costs spike.
Strategic Opportunities
- Matter Protocol Convergence:The Connectivity Standards Alliance's Matter specification unifies Wi-Fi, Thread, and Zigbee stacks. Smart home device OEMs in Shenzhen and Taipei are redesigning combo chips to capture cross-platform certification.
- Private 5G-Wi-Fi Convergence:Industrial campuses in Germany's Ruhr region and Japan's Kansai corridor are deploying converged access networks. Chip vendors integrating 5G NR and Wi-Fi 6E basebands capture systems-level socket wins.
- India PLI Scheme Incentives:India's production-linked incentive scheme for telecom and networking equipment subsidizes domestic module assembly. EMS providers in Tamil Nadu and Karnataka are expanding SMT lines for export-bound Wi-Fi modules.
Industry Challenges
- Millimeter-Wave Test Equipment Bottleneck:6 GHz and future 7 GHz validation requires vector network analyzers and over-the-air chambers in short supply. Taiwan's test houses report six-month queues for full RF characterization.
- Legacy 802.11n Integration Drag:Enterprise IT departments in regulated industries maintain dual-stack compatibility requirements. Chip designers sacrifice die area to preserve backward compatibility, elevating cost per square millimeter.
- Patent Pool Licensing Complexity:Wi-Fi 6 implements OFDMA and 1024-QAM under IEEE 802.11ax, but essential patent holders in the Sisvel and Avanci pools impose overlapping royalty structures. Module vendors face stacking liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wifi Chip Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 802.11ax, 802.11ac, 802.11n, 802.11g, 802.11b Technology: 2x2 MIMO, 4x4 MIMO, Beamforming, Channel Bonding, OFDMA Application: Smartphones, Wearables, Laptops, Smart Home Devices, Industrial Automation End User: Consumer Electronics Manufacturers, Network Equipment Providers, IoT Solution Providers, Telecommunication Companies |
| Companies Covered | Qualcomm Technologies Inc., Broadcom Inc., MediaTek Inc., Intel Corporation, Texas Instruments Incorporated, Realtek Semiconductor Corporation, NXP Semiconductors, Infineon Technologies AG, Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wifi Chip Market Trends and Innovations
Silicon integration density and spectrum policy are compressing product lifecycles, forcing architectural bets on tri-band convergence and packaging innovation before 7 GHz allocations finalize.
RF front-end modules are miniaturizing through silicon-on-insulator and chip-scale packaging techniques that integrate power amplifiers, low-noise amplifiers, and switches into single die stacks. Smartphone OEMs in Korea and China are specifying these for sub-3mm z-height designs. This compression is enabling full-band coverage in mid-tier devices previously limited to discrete component architectures.
The FCC's 6 GHz unlicensed rules and Europe's harmonized decision under the Radio Equipment Directive are mandating automated frequency coordination for standard-power outdoor access points. Infrastructure vendors must implement contention-based protocols that detect incumbent radar systems. Enterprise deployments in Dallas, Frankfurt, and Tokyo are piloting these AFC-certified systems ahead of 2025 outdoor certification deadlines.
Consolidated procurement by hyperscale cloud providers is compressing supplier qualification cycles from eighteen months to nine. Microsoft Azure and Amazon Web Services are specifying custom Wi-Fi 6E silicon for data center management networks. Taiwan-based ODMs report direct RFQ pipelines bypassing traditional distribution, concentrating volume among three to four qualified chip vendors per platform generation.
Wifi Chip Market Segmentation
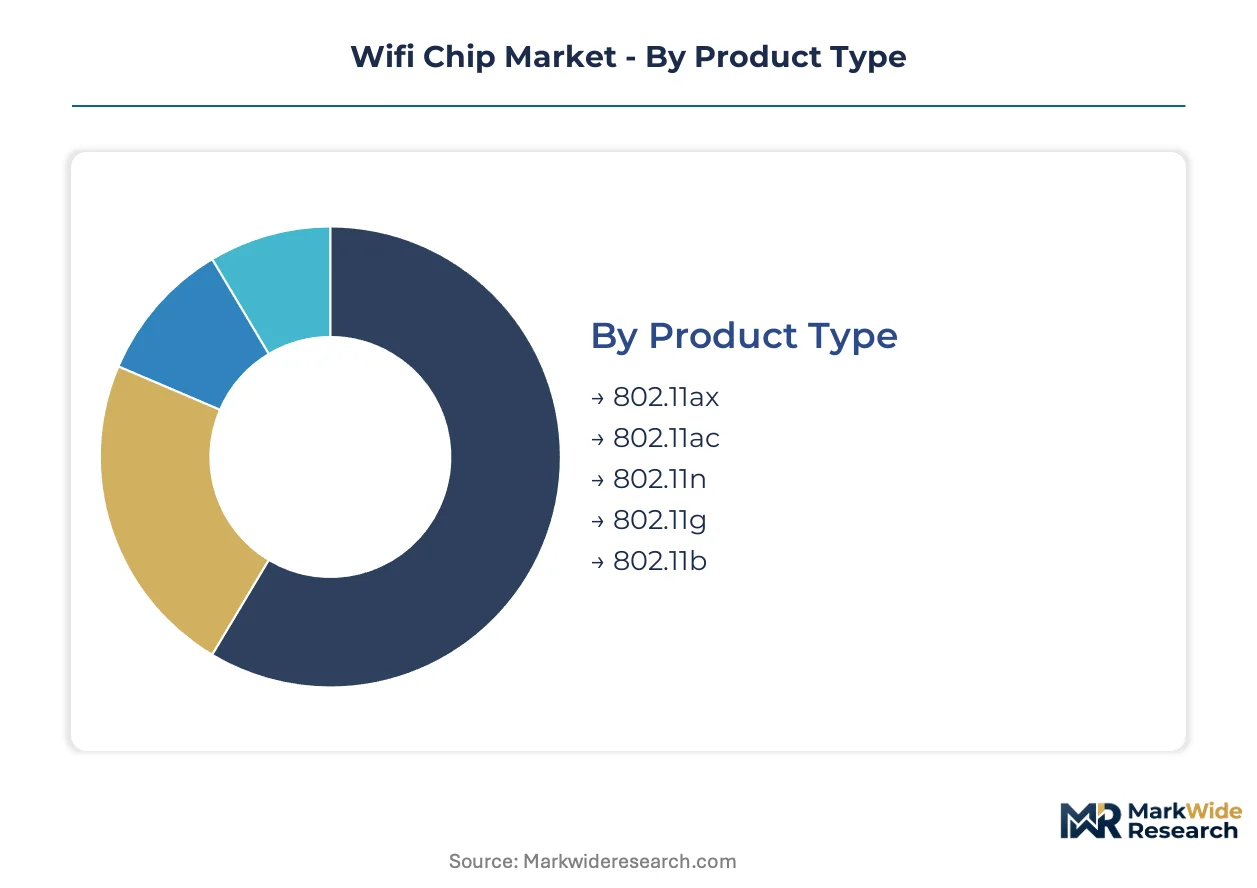
WiFi chip segmentation reveals distinct procurement patterns across product generations and application tiers. Channel strategies diverge sharply between enterprise infrastructure vendors sourcing through direct foundry relationships and consumer OEMs relying on module distributors.
Product Type:
Channel mix varies by protocol maturity—802.11ax flows primarily through direct ODM partnerships, while legacy standards concentrate in distributor-led module assembly.
- 802.11ax:Tri-band architectures integrating 2.4 GHz, 5 GHz, and 6 GHz radios on 12-inch CMOS wafers. Enterprise access point manufacturers in Dallas and Frankfurt are certifying SKUs for automated frequency coordination compliance.
- 802.11ac:Dual-band 5 GHz-capable silicon with mature cost curves. Volume concentrates in emerging market smartphones where MediaTek and Realtek compete on module price points.
- 802.11n:Single and dual-stream legacy compatibility silicon. Industrial integrators in regulated sectors maintain dual-stack requirements for backward compatibility.
- 802.11g:2.4 GHz-only legacy protocol for embedded control systems.
- 802.11b:Original 11 Mbps specification retained for minimal-cost IoT endpoints.
802.11ax dominates installed base refresh cycles. 802.11ac is where expansion concentrates in cost-sensitive volume tiers.
Technology:
Cost tier stratification separates premium spatial stream configurations from baseline connectivity solutions.
- 4x4 MIMO:Four spatial stream architectures enabling 1.2+ Gbps throughput in enterprise access points. Stadium and convention center deployments in Singapore and Dubai specify these for high-density environments.
- OFDMA:Orthogonal frequency-division multiple access for simultaneous low-latency transmission to hundreds of endpoints. Smart building integrators deploy this for elevator control and HVAC mesh networks.
- Beamforming:Directional signal steering for range extension. Residential mesh systems leverage this for whole-home coverage.
- 2x2 MIMO:Dual-stream standard for mainstream smartphones and laptops.
- Channel Bonding:80 MHz and 160 MHz aggregation for throughput scaling.
4x4 MIMO dominates enterprise infrastructure sockets. OFDMA is expanding most quickly into industrial automation gateways.
Application:
Customer type determines module packaging—smartphone OEMs demand chip-scale packages while industrial integrators accept larger form factors with extended temperature ratings.
- Smartphones:Chip-scale packaged silicon with integrated RF front-end modules. Korean and Chinese OEMs specify sub-3mm z-height designs for flagship devices.
- Industrial Automation:Ruggedized modules for factory floor wireless sensor networks. China's Yangtze River Delta and Pearl River Delta drive assembly scale for 802.11ax gateways.
- Laptops:M.2 module form factors with PCIe interfaces. Enterprise fleet refresh cycles align with Intel and AMD platform generations.
- Smart Home Devices:Cost-optimized single-band or dual-band solutions for voice assistants and cameras.
- Wearables:Ultra-low-power 802.11b/g/n for fitness trackers and smartwatches.
Smartphones dominate semiconductor revenue contribution. Industrial Automation is where expansion concentrates as private 5G-WiFi convergence accelerates.
End User:
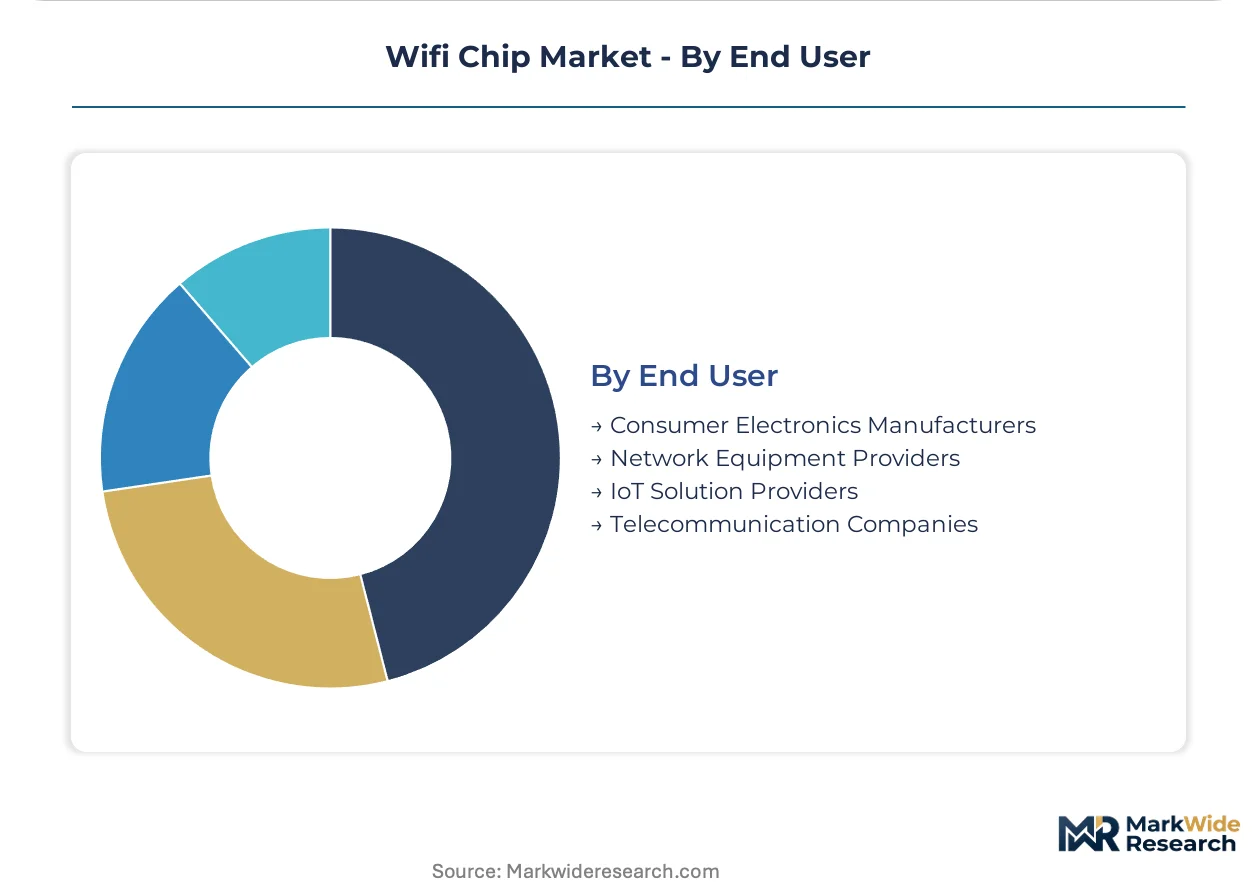
Supply concentration varies by procurement sophistication—telecommunication companies maintain captive engineering teams while IoT solution providers rely on turnkey module sourcing.
- Network Equipment Providers:Enterprise and carrier-grade infrastructure vendors with direct foundry relationships. Cisco, Aruba, and Juniper qualify silicon through eighteen-month vendor cycles.
- Consumer Electronics Manufacturers:Smartphone, laptop, and smart home OEMs sourcing through Taiwan-based ODMs. Procurement concentrates among three to four qualified vendors per platform generation.
- IoT Solution Providers:Industrial and commercial system integrators specifying module-level solutions. These customers prioritize certification completeness over die-level optimization.
- Telecommunication Companies:Carrier-led CPE and small cell programs with custom firmware requirements.
Network Equipment Providers dominate premium socket allocation. IoT Solution Providers represent the steepest expansion trajectory as edge computing deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC anchors the dominant geography through 6 GHz spectrum liberalization, while semiconductor fabrication capacity concentrates in Taiwan and South Korea. Foundry booking lead times for advanced RF-CMOS nodes now exceed eighteen months across these jurisdictions.
United States
Enterprise access point manufacturers in Dallas and Austin are certifying tri-band SKUs for automated frequency coordination compliance. The FCC's 2020 unlicensed rules for 6 GHz standard-power outdoor operation mandate radar detection protocols. Microsoft's Azure and Amazon Web Services specify custom silicon for data center management networks, compressing supplier qualification cycles.
Germany
Industrial campuses in the Ruhr region deploy converged private 5G-Wi-Fi access networks for factory automation. BNetzA's parallel 6 GHz allocation aligns with the FCC's 1200 MHz bandwidth unlock. Stuttgart-based automotive OEMs specify Wi-Fi 6E for over-the-air update infrastructure in connected vehicle programs.
China
Domestic module assembly scales fastest in the Yangtze River Delta and Pearl River Delta for 802.11ax industrial gateways. MIIT mandates domestic SAR testing protocols that add four to six months to foreign supplier time-to-market. Shenzhen and Taipei smart home device OEMs redesign combo chips for Matter protocol cross-platform certification.
Japan
MIC's 6 GHz allocation supports high-throughput applications in dense urban environments. Enterprise deployments in Tokyo pilot AFC-certified systems ahead of 2025 outdoor certification deadlines. Kansai corridor industrial campuses integrate 5G NR and Wi-Fi 6E basebands for converged access networks.
South Korea
MSIT imposes additional KC mark requirements for 6 GHz power spectral density limits. RF engineering talent scarcity constrains foundry expansion for 28nm RF-CMOS processes. Seoul-based smartphone OEMs specify sub-3mm z-height chip-scale packaged designs for flagship devices.
Wifi Chip Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Wi-Fi chip market. The upper tier commands premium sockets through baseband-Wi-Fi integration and deep OEM partnerships. Specialist players compete aggressively on cost-engineered solutions for mid-tier consumer devices. Competitive moves concentrate on foundry capacity allocation priority and strategic patent licensing positions.
Within the integrated tier, Qualcomm Technologies Inc. and Broadcom Inc. exemplify baseband-Wi-Fi convergence strategies. MediaTek Inc. occupies a position representing cost-engineered 802.11ax competition for volume consumer segments. These three entities anchor the competitive structure through differentiated approaches to silicon integration and customer segmentation.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| Broadcom Inc. |
| MediaTek Inc. |
| Intel Corporation |
| Texas Instruments Incorporated |
| Realtek Semiconductor Corporation |
| NXP Semiconductors |
| Infineon Technologies AG |
| Samsung Electronics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
FCC 6 GHz certification requirements gate both supplier qualification timelines and price differentiation across tri-band WiFi chip architectures, compressing margins for vendors unable to secure automated frequency coordination approvals ahead of enterprise refresh cycles. Module assemblers in China's Yangtze River Delta absorb extended MIIT testing protocols while premium socket holders command pricing power through integrated baseband-WiFi designs.
Pricing Analysis
Geographic price spreads widen between FCC-certified tri-band SKUs and legacy dual-band alternatives, with enterprise infrastructure vendors paying premiums for AFC-compliant silicon. Three-tier pricing structure across premium, standard, and economy levels reflects certification completeness, volume scale, and RF front-end integration depth. Pricing pressure stems from SiGe BiCMOS substrate cost volatility compressing power amplifier margins. IoT solution providers exhibit highest price sensitivity, while hyperscale cloud providers prioritize qualification speed over unit economics.
Supply Chain Analysis
Foundry booking queues for 28nm RF-CMOS processes now stretch beyond eighteen months across Taiwan and South Korea, constraining inventory availability for industrial automation integrators. Silicon supply draws from 12-inch wafer fabrication, germanium concentrate markets, and advanced packaging substrates. Single-source vulnerability concentrates in Taiwan's test houses, where vector network analyzer capacity for 6 GHz validation faces six-month backlogs. Distribution runs through direct ODM partnerships for enterprise infrastructure and module distributors for consumer OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrastructure refresh cycles are entering cyclical recovery as enterprise access point deployments accelerate behind 6 GHz spectrum liberalization, with FCC outdoor certification deadlines anchoring replacement demand.
For Market Incumbents: Fortify foundry allocation priority through multi-year capacity reservations at Taiwan Semiconductor Manufacturing and Samsung Foundry, locking 28nm RF-CMOS slots before smartphone OEMs absorb remaining capacity. Deepen patent licensing positions in OFDMA and 1024-QAM essential patent pools to offset stacking royalty exposure from Sisvel and Avanci structures.
For New Entrants and Emerging Players: Anchor in India's PLI-subsidized module assembly corridor, where Tamil Nadu and Karnataka EMS providers expand SMT lines for export-bound WiFi modules with reduced qualification barriers. Target industrial automation gateways in Germany's Ruhr region, where private 5G-WiFi convergence creates socket openings for integrated baseband vendors lacking incumbent OEM relationships.
For Investors and Strategic Acquirers: 6 GHz band harmonization progress across regulators reshapes the acquisition landscape, privileging vendors with region-specific certification inventories over pure-play technology developers. Five-to-ten year viability favors specialists with captive RF engineering talent and foundry partnerships rather than fabless design houses exposed to capacity allocation risk. Monitor BNetzA and MIC outdoor AFC certification timelines as inflection indicators for enterprise infrastructure demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Tri-Band Architecture Certification | FCC AFC compliance unlocks enterprise access point sockets in Dallas and Frankfurt. |
| Foundry Capacity Reservation | Multi-year bookings at TSMC and Samsung secure 28nm RF-CMOS allocation priority. |
| Matter Protocol Integration | Cross-platform certification captures smart home OEM redesign cycles in Shenzhen. |
| Private 5G-WiFi Convergence | Integrated baseband designs win systems-level sockets in Germany's Ruhr region. |
| India PLI Assembly Expansion | Tamil Nadu EMS lines capture export-bound module volume with subsidized cost structures. |
Research Methodology
A spread of perspectives from RF engineering directors at foundries, procurement leads at network equipment providers, regulatory affairs specialists, and module assembly operations managers converged on the working assumptions for capacity allocation and certification timelines. Secondary validation drew from FCC equipment authorization databases, ETSI harmonized standards filings, MIIT radio transmission equipment type-approval records, and foundry capex disclosures. Bottom-up triangulation across product-level bill-of-materials analysis and top-down reconciliation against foundry wafer output data anchored volume estimates.
Segmentation dimensions modeled include protocol generation, spatial stream configuration, application tier, and geographic regulatory cluster across the analysis window. CAGRs were derived from infrastructure refresh cycle timing, smartphone platform generation alignment, and industrial automation deployment trajectories. Forecast inputs incorporated foundry capacity expansion announcements, spectrum allocation regulatory milestones, and patent pool licensing cost structures.
Material uncertainties — foundry yield fluctuations, germanium concentrate price spikes, and regional certification timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding infrastructure replacement elasticity and module assembly cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market