
 Industrial Internet Chip Market | 2026-2036
Industrial Internet Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Internet Chip Market Analysis
Multi-sourced foundry partnerships is recalibrating how industrial chip vendors secure capacity amid supply volatility. Intel Corporation leverages captive fabrication to anchor its position in high-reliability processor segments. NXP Semiconductors specializes in automotive-qualified silicon that extends into factory-floor edge nodes. Texas Instruments Incorporated controls analog front-end integration that differentiates its sensor interface portfolios.
Industrial Internet Chips are semiconductor devices engineered for deterministic latency below ten milliseconds, operating across temperature extremes from negative forty to positive eighty-five degrees Celsius to enable real-time machine-to-machine communication in harsh environments. Their primary purpose is to execute localized data processing at the network edge, reducing bandwidth loads while maintaining sub-cycle control responsiveness for automated equipment. Processors and microcontrollers command the largest current revenue pools, reflecting their centrality to programmable logic controllers and robotic motion controllers. Edge computing technology within the architecture stack represents the fastest-expanding segment as latency requirements tighten for closed-loop industrial applications. FPGAs occupy a narrower but higher-margin niche where field-reconfigurable logic supports evolving communication protocols without hardware replacement.
FCC equipment authorization and NHTSA functional safety guidelines shape product validation requirements for US-deployed industrial connectivity silicon, while ISO 26262 and IEC 61508 standards govern failure-mode tolerances in safety-critical automation systems. REACH substance restrictions and RoHS compliance mandates from ECHA affect material selection and plating chemistry across European supply chains. Stakeholders must monitor how emerging cybersecurity certification frameworks for operational technology hardware reshape qualification timelines and customer procurement criteria.
Market Dynamics
Edge computing architectures are compressing decision latency requirements below ten milliseconds, forcing semiconductor vendors to redesign thermal envelopes and deterministic processing pipelines for factory-floor deployment.
Growth Catalysts
- EU AI Act compliance mandates:European machinery OEMs now specify certified edge processors for predictive maintenance systems, creating qualified supplier lists that favor pre-certified silicon vendors.
- Automotive-qualified silicon migration:Extended temperature-range chipsets originally developed for powertrain control are repurposing into industrial robotics and motion controllers.
- Germany's industrial corridor concentration:Automotive and machinery OEMs in Baden-Württemberg and Bavaria are integrating predictive maintenance chipsets at scale, anchoring regional demand.
Market Restraints
- Advanced node foundry concentration:Sub-7nm capacity constraints at Taiwan-based fabrication facilities limit supply security for high-complexity industrial SoCs.
- Raw material input volatility:Neon gas and palladium supply disruptions from Eastern European sources inflate wafer processing costs unpredictably.
- Functional safety certification friction:IEC 61508 SIL certification timelines extend 18-24 months, freezing product roadmaps for safety-critical automation segments.
Strategic Opportunities
- India manufacturing automation:PLI scheme incentives for electronics manufacturing are drawing industrial chip vendors to establish local validation labs and application engineering centers.
- Time-sensitive networking convergence:IEEE 802.1 TSN protocol stacks fused with deterministic processors enable new motion control architectures in packaging machinery.
- ECHA REACH substance restrictions:RoHS compliance mandates are accelerating lead-free plating chemistry transitions, rewarding early-adopter foundries with preferred supplier status.
Industry Challenges
- Mixed-signal design talent scarcity:Industrial chip vendors compete for analog-digital integration specialists capable of sub-millivolt precision sensor interfaces.
- Legacy PLC protocol integration:EtherCAT and PROFINET stack certification requires extensive field validation against thirty-year-old controller hardware still operating in installed bases.
- Multi-standard compliance stacking:Simultaneous FCC equipment authorization, CE marking, and ISO 26262 qualification extends product launch timelines by 40 percent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Internet Chip Market |
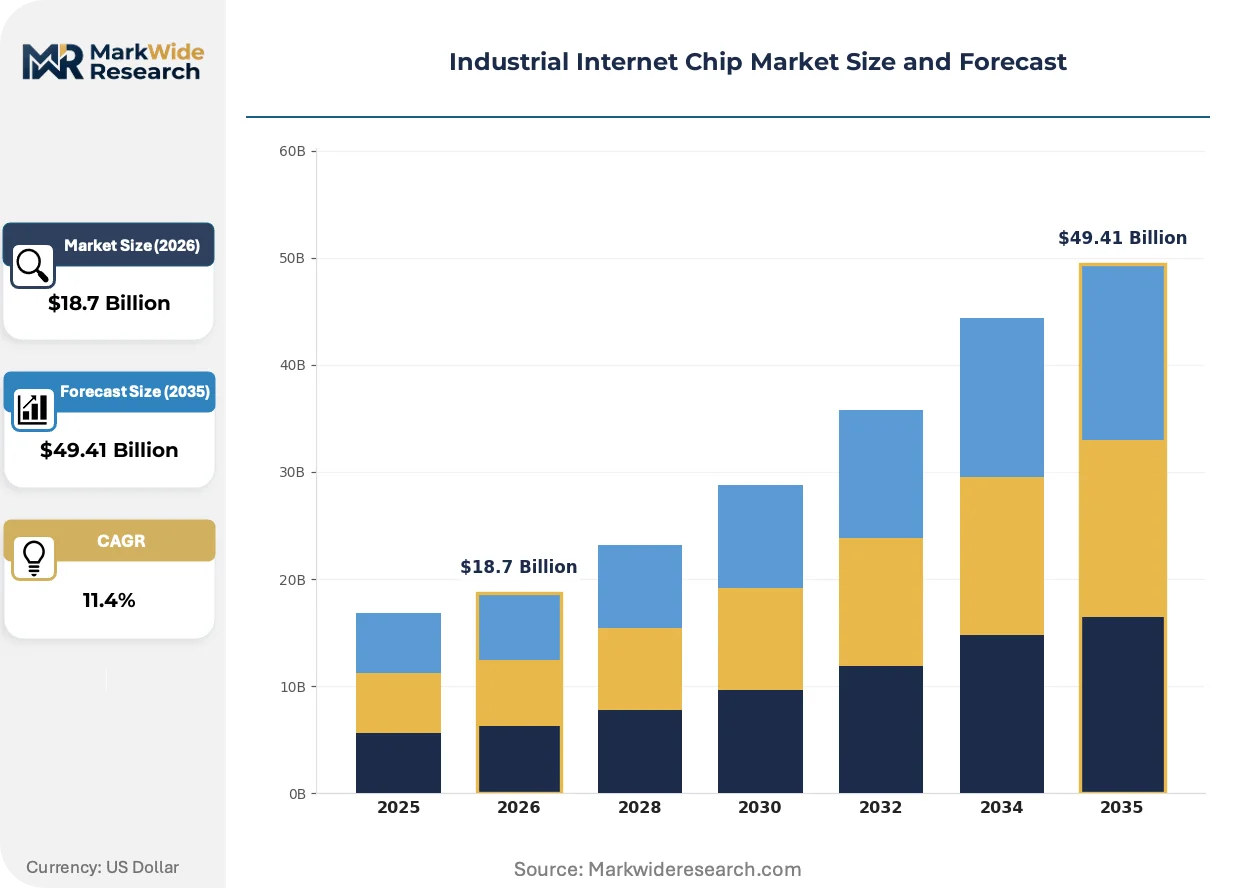
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Sensors, Processors, FPGAs Application: Manufacturing Automation, Smart Grids, Predictive Maintenance, Asset Tracking End User: Manufacturers, Utilities, Transportation, Agriculture Technology: IoT Platforms, Edge Computing, Cloud Integration, Machine Learning |
| Companies Covered | Intel Corporation, Texas Instruments Incorporated, NXP Semiconductors, Qualcomm Technologies Inc, STMicroelectronics NV, MediaTek Inc., Broadcom Inc., Infineon Technologies AG, Analog Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Internet Chip Market Emerging Trajectories
Deterministic edge processing is fragmenting centralized control architectures, distributing computational load across sensor nodes and actuators rather than consolidated PLCs.
Field-programmable gate arrays are decentralizing protocol adaptation responsibilities in industrial gateways. Automotive Tier-1 suppliers migrating into factory automation are adopting FPGA-based edge nodes to manage simultaneous EtherCAT, OPC-UA, and MQTT streams without hardware respins. This reconfigurability compresses customer qualification cycles from 18 months to 6 months for evolving Industry 4.0 connectivity standards.
The EU AI Act's risk classification framework is mandating conformity assessment procedures for AI-enabled industrial chips deployed in safety-related systems. Machinery OEMs in Germany and Italy are now requiring documented algorithmic transparency and bias testing from processor vendors. High-risk automation categories face notified body involvement, extending procurement validation timelines and favoring established suppliers with existing EU regulatory relationships.
Buyer consolidation among German automotive OEMs is concentrating procurement leverage for multi-year chipset supply agreements. Tier-1 motion control suppliers report compressed switching cycles as vehicle manufacturers standardize on single-source edge processor platforms across powertrain and body electronics. This concentration is visible most acutely in Stuttgart and Munich industrial clusters, where preferred vendor lists now exclude second-source qualification for non-safety applications.
Industrial Internet Chip Market Segmentation
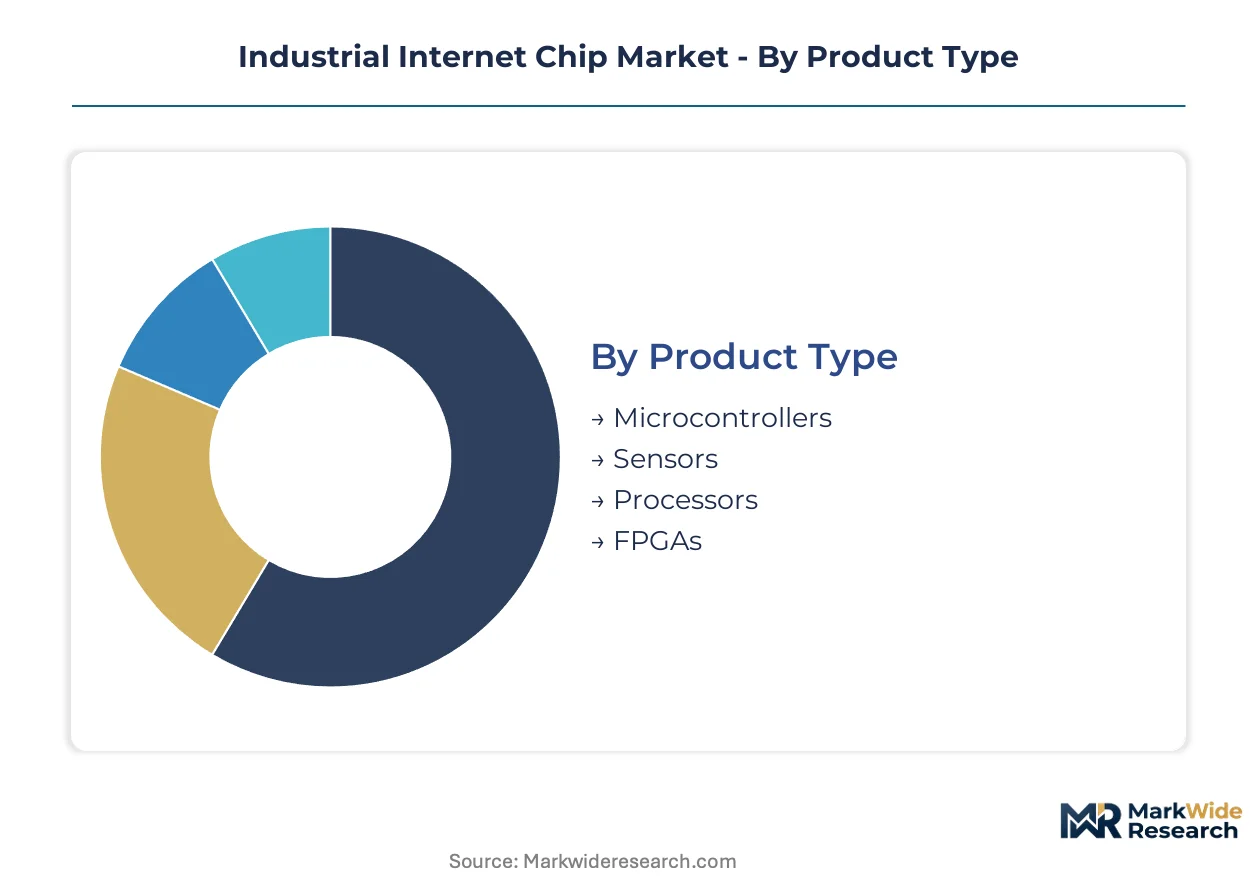
Industrial Internet Chip procurement hinges on matching thermal specifications, latency budgets, and protocol compatibility to specific operational environments. Buyers evaluate segments through the lens of deterministic performance under temperature extremes and certification requirements for safety-critical deployments.
Product Type:
Procurement teams prioritize thermal envelope specifications and deterministic latency guarantees when selecting silicon architectures for factory-floor deployment.
- Microcontrollers:These integrated units combine CPU cores with memory and programmable I/O on a single die, operating reliably across negative forty to positive eighty-five degrees Celsius. German automotive OEMs in Baden-Württemberg specify automotive-qualified microcontrollers for robotic motion controllers, prioritizing IEC 61508 SIL certification timelines that extend eighteen to twenty-four months.
- Processors:High-complexity SoCs deliver sub-ten-millisecond latency for closed-loop industrial applications through dedicated deterministic processing pipelines. Demand concentrates in Bavaria's machinery corridor where predictive maintenance systems require edge-capable processors capable of localized data processing without cloud dependency.
- Sensors:Analog front-end devices with sub-millivolt precision interfaces convert physical signals into digital data streams for machine-to-machine communication.
- FPGAs:Field-reconfigurable logic arrays enable protocol adaptation without hardware replacement, compressing customer qualification cycles from eighteen months to six months for evolving Industry 4.0 standards.
Microcontrollers lead on scale; FPGAs lead on momentum.
Application:
End-use environments dictate chip selection through humidity exposure, vibration tolerance, and real-time control responsiveness requirements.
- Manufacturing Automation:Programmable logic controllers and robotic motion controllers demand deterministic latency below ten milliseconds for sub-cycle control responsiveness. Stuttgart's automotive OEMs integrate edge processors directly into welding and assembly line equipment, driven by EU AI Act compliance mandates for AI-enabled predictive maintenance.
- Predictive Maintenance:Vibration analysis and thermal monitoring chipsets process sensor data locally to forecast equipment failures before operational disruption. Italian machinery OEMs in Emilia-Romagna deploy these systems for CNC machine tool monitoring, constrained by REACH substance restrictions affecting plating chemistry selection.
- Smart Grids:Power distribution networks utilize industrial connectivity silicon for real-time load balancing and fault isolation across transmission infrastructure.
- Asset Tracking:Location and condition monitoring systems rely on low-power wide-area connectivity for inventory and equipment visibility across distributed facilities.
Manufacturing Automation commands the largest deployment volumes; Predictive Maintenance is expanding most quickly as machinery OEMs retrofit installed bases.
End User:
Customer procurement authority varies by capital expenditure cycles and regulatory compliance exposure across industrial sectors.
- Manufacturers:Discrete and process industries deploy edge processors for quality control, robotic coordination, and supply chain synchronization. Munich-based automotive Tier-1 suppliers standardize on single-source edge processor platforms across powertrain and body electronics, consolidating procurement leverage through multi-year supply agreements.
- Utilities:Electricity and water infrastructure operators specify extended temperature-range chipsets for substation automation and distribution network monitoring, governed by FERC reliability standards in US deployments and national grid codes in European markets.
- Transportation:Fleet operators and logistics providers integrate asset tracking and condition monitoring silicon for vehicle health management and route optimization.
- Agriculture:Precision farming operations deploy soil moisture and equipment tracking sensors across distributed field operations with limited connectivity infrastructure.
Manufacturers drive current revenue concentration; Utilities present the steepest expansion trajectory as grid modernization accelerates.
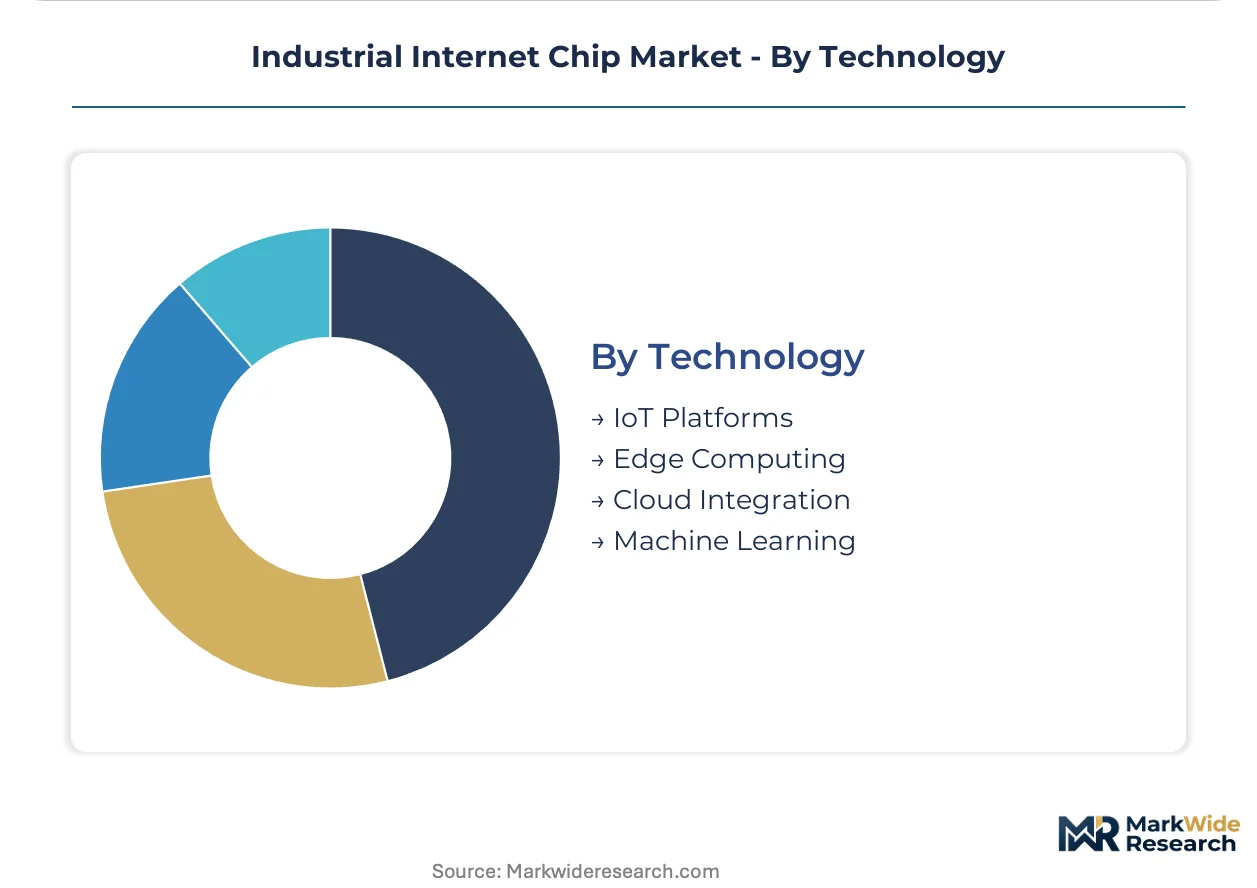
Technology:
Architecture stack selection determines where computational load resides relative to data sources and cloud endpoints.
- Edge Computing:Distributed processing architectures execute localized data analysis at sensor nodes and actuators rather than consolidated PLCs. Germany's industrial corridor leads adoption as latency requirements tighten for closed-loop packaging machinery and motion control applications.
- Machine Learning:Neural network accelerators embedded in industrial silicon enable pattern recognition for anomaly detection and quality inspection. The EU AI Act's risk classification framework mandates conformity assessment procedures for these AI-enabled chips in safety-related systems, extending procurement validation timelines.
- IoT Platforms:Connectivity middleware stacks manage device provisioning, data aggregation, and protocol translation across heterogeneous industrial equipment.
- Cloud Integration:Hybrid architectures synchronize edge-processed data with centralized analytics platforms for long-term trend analysis and enterprise resource planning.
Edge Computing leads on deployment momentum; Cloud Integration remains foundational for enterprise-scale analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor concentrates the highest deployment density of edge-capable processors for factory automation, with automotive OEMs in Stuttgart and Munich driving qualification requirements for predictive maintenance chipsets.
Germany
Automotive and machinery OEMs in Baden-Württemberg and Bavaria integrate predictive maintenance chipsets at scale, anchoring regional demand concentration. The EU AI Act mandates conformity assessment procedures for AI-enabled industrial chips in safety-related systems, extending procurement validation timelines. Stuttgart-based automotive Tier-1 suppliers standardize on single-source edge processor platforms across powertrain and body electronics.
United States
Discrete manufacturers deploy edge processors for quality control and robotic coordination across Midwest industrial belts. FCC equipment authorization and NHTSA functional safety guidelines shape product validation requirements for industrial connectivity silicon. Detroit-area automotive suppliers specify extended temperature-range chipsets for welding and assembly line equipment integration.
China
Electronics manufacturing clusters in the Yangtze River Delta and Pearl River Delta absorb industrial microcontrollers for programmable logic controllers and motion controllers. MIIT industrial internet policies accelerate domestic chipset procurement preferences for smart factory deployments. Shenzhen-based equipment builders integrate edge processors into packaging machinery for export markets.
Japan
Precision machinery builders in the Chubu region around Nagoya specify deterministic processors for sub-ten-millisecond latency requirements in motion control applications. METI's Society 5.0 initiative funds edge computing adoption in manufacturing automation. Toyota City suppliers repurpose automotive-qualified silicon for industrial robotics and predictive maintenance systems.
India
Electronics manufacturing incentives under the PLI scheme draw industrial chip vendors to establish local validation labs and application engineering centers. BIS certification requirements govern product qualification timelines for factory automation deployments. Gujarat and Tamil Nadu industrial corridors host expanding deployment of edge processors for textile and automotive component manufacturing.
Industrial Internet Chip Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive-to-industrial silicon migration strategies. The vendor base organizes around captive fabrication capabilities, fabless design specialization, and analog-digital integration expertise. Three archetypes dominate: diversified semiconductor conglomerates with captive foundries, automotive-qualified silicon specialists extending into factory automation, and mixed-signal integration experts controlling sensor interface portfolios. Capacity expansion through multi-sourced foundry partnerships and strategic technology licensing for deterministic processing pipelines represent the dominant competitive moves.
Within the diversified conglomerate tier, Intel Corporation anchors high-reliability processor segments through captive fabrication infrastructure. NXP Semiconductors occupies a position exemplifying automotive-qualified silicon migration into industrial edge nodes. Texas Instruments Incorporated represents analog front-end integration specialists differentiating sensor interface portfolios. These three entities collectively illustrate how thermal envelope specifications and deterministic latency guarantees shape procurement qualification pathways across German automotive OEMs and machinery builders.
| Leading Market Players |
|---|
| Intel Corporation |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Qualcomm Technologies Inc |
| STMicroelectronics NV |
| MediaTek Inc. |
| Broadcom Inc. |
| Infineon Technologies AG |
| Analog Devices Inc. |
| Others |
Supply Flow & Price Mechanics
German automotive OEM consolidation around single-source edge processor platforms is compressing supplier margins and forcing foundries to absorb certification costs upfront. This procurement concentration shifts pricing power toward volume buyers while fragmenting margin structures across qualification tiers.
Pricing Analysis
Input-cost pass-through from neon gas and palladium supply disruptions runs unevenly across product tiers. Pricing stratifies across automotive-qualified, industrial-grade, and commercial-temperature silicon tiers, with IEC 61508 SIL certification level and volume scale as primary price differentiation drivers. Cost compression in commercial-temperature segments is intensifying because foundries compete for non-automotive industrial slots. Automotive-qualified silicon buyers in Stuttgart and Munich industrial clusters exhibit the lowest price sensitivity due to multi-year supply agreement lock-ins, while packaging machinery OEMs in China show highest sensitivity to per-unit differentials.
Supply Chain Analysis
Certification and qualification gating concentrates supply relationships around foundries with pre-existing automotive safety credentials. Taiwan, South Korea, and the United States anchor advanced node and analog front-end production for industrial SoCs and sensor interfaces. Raw material dependencies draw from Eastern European neon gas sources and Russian palladium supplies, creating tariff exposure through sanctions-related logistics rerouting. Distribution runs through authorized distributors serving German machinery corridors and direct OEM relationships for Detroit and Nagoya automotive supplier clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as machinery OEMs retrofit installed bases with predictive maintenance chipsets requiring deterministic latency guarantees below ten milliseconds.
For Market Incumbents: Acquire mixed-signal design talent pools capable of sub-millivolt precision sensor interfaces. Foundry capacity in India under PLI scheme incentives provides geographic diversification against Taiwan concentration risk. Pre-certify silicon portfolios to EU AI Act high-risk categories before notified body involvement extends competitor qualification timelines. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for algorithmic transparency documentation services and bias-testing tooling partnerships with established silicon vendors. India's electronics manufacturing PLI scheme offers the most penetrable geography for validation lab establishment and application engineering center deployment. Lead with time-sensitive networking protocol stack integration for packaging machinery OEMs seeking IEEE 802.1 TSN compatibility without hardware respins. For Investors and Strategic Acquirers: Asymmetric upside sits with automotive-qualified silicon specialists extending into factory automation edge nodes. Five-to-ten-year viability hinges on captive fabrication or multi-sourced foundry partnerships securing sub-7nm and mature node capacity simultaneously. Watch for BIS certification requirement expansions in India as inflection indicator for local validation infrastructure investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-sourced Foundry Partnership | Secures capacity across Taiwan, South Korea, and India against single-source vulnerability. |
| Automotive-to-Industrial Silicon Migration | Repurposes IEC 61508 pre-certified designs for predictive maintenance edge nodes. |
| Deterministic Processing Pipeline Investment | Delivers sub-ten-millisecond latency for closed-loop motion control in Stuttgart automotive clusters. |
| EU AI Act Pre-certification | Accelerates procurement validation timelines for high-risk automation categories in Germany. |
| India Validation Lab Establishment | Captures PLI scheme incentives while serving Gujarat and Tamil Nadu industrial corridor demand. |
Methodological Framework
Coverage spans Germany, United States, China, Japan, and India, with primary inputs from each regional industrial cluster. Semiconductor vendor strategy executives, automotive Tier-1 procurement directors, machinery OEM plant engineers, foundry operations managers, and regulatory affairs leads provided qualitative ground-truth. Secondary validation drew from MIIT industrial internet policy filings, SEC 10-K semiconductor segment disclosures, EU AI Act implementing acts, and BIS certification registries. Bottom-up unit demand estimates triangulated against top-down industrial automation capex forecasts.
Rate-of-change decomposition structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, application environment, end-user sector, and technology stack position alongside regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves for edge computing and machine learning accelerators. Forecast inputs incorporated foundry capacity expansion announcements, EU AI Act enforcement timelines, and India PLI scheme participant commitments.
Revisions become necessary when Taiwan foundry capacity allocation shifts, REACH substance restriction expansions, or EU AI Act high-risk category reclassifications materialize. Forecasts reflect documented assumptions regarding automotive production cycles, industrial automation retrofit rates, and certification timeline stability. A model refresh is warranted upon material change in Germany automotive OEM procurement consolidation patterns or India electronics manufacturing incentive program modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Automotive Transceivers Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Optical Communications Market