
 Alpha Thalassemia Market | 2026-2036
Alpha Thalassemia Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha Thalassemia Market Analysis
Outcome-based reimbursement for chronic transfusion programs is pivoting how payers contract for thalassemia care, shifting risk toward providers who manage iron overload complications. Novartis Pharmaceuticals Corporation leverages its transfusion medicine portfolio to anchor hospital formulary relationships across Mediterranean and Southeast Asian patient corridors. Bluebird Bio sustains gene therapy development intensity despite manufacturing complexity, while CHIESI Farmaceutici S.p.A. differentiates through iron chelation delivery innovations that reduce dosing burden.
Alpha thalassemia comprises inherited hemoglobin disorders caused by deletions or mutations in one or more of the four alpha-globin genes on chromosome 16, with severity ranging from silent carrier status to hemoglobin Bart hydrops fetalis that demands prenatal intervention. The condition primarily burdens populations of Southeast Asian, Mediterranean, Middle Eastern, and African descent, requiring lifelong transfusion support or curative stem cell intervention in severe forms. Blood transfusion and iron chelation therapy occupy the mature core of current revenue, while gene therapy represents the fastest-growing segment as lentiviral vector manufacturing scales and reimbursement frameworks adapt to one-time curative pricing. Hospital end users concentrate margin pools through dedicated thalassemia centers that capture bundled payments for comprehensive disease management.
FDA orphan drug designations and EMA priority medicines status shape trial enrollment incentives and post-market surveillance obligations for developers targeting hemoglobinopathies. The EU AI Act and GDPR impose computational and data governance requirements on machine learning tools used for genotype-phenotype correlation in patient stratification. Stakeholders must monitor how CMS and national European health technology assessment bodies calibrate value thresholds for single-administration gene therapies against decades of transfusion and chelation costs.
Market Dynamics
Gene therapy manufacturing scale-up is compressing commercialization timelines for severe hemoglobinopathies, forcing hospital systems to reconfigure transfusion infrastructure around one-time curative interventions rather than chronic care models.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy and EMA priority medicines designations compress Phase II-III transition timelines for rare blood disorders, reducing capital-at-risk periods for developers targeting hemoglobin H disease.
- Centers of Excellence Networks:Specialized thalassemia treatment hubs in the United States consolidate patient volumes sufficient to justify dedicated gene therapy infusion suites and apheresis capabilities.
- Lentiviral Vector Manufacturing:Suspension-based production platforms are displacing adherent cell culture, improving lot-to-lot consistency for ex vivo gene modification therapies targeting alpha-globin gene defects.
Market Restraints
- Plasmid DNA Supply Concentration:Critical raw material for viral vector production concentrates among North American and European contract manufacturers, creating single-source vulnerability for gene therapy developers.
- Reimbursement Uncertainty:CMS and national European HTA bodies lack established frameworks for single-administration curative pricing against decades of transfusion and chelation cost baselines.
- Genotype-Phenotype Discordance:Variable clinical expression among identical alpha-globin gene deletions complicates patient stratification for interventional trials and commercial targeting.
Strategic Opportunities
- In Utero Intervention Protocols:Hemoglobin Bart hydrops fetalis represents an addressable mortality gap through prenatal stem cell or gene therapy approaches, with specialized fetal surgery centers in the United States and United Kingdom developing delivery capabilities.
- Iron Chelation Formulation Innovation:Long-acting subcutaneous or oral alternatives to deferoxamine infusion reduce dosing burden adherence gaps, particularly among adolescent and young adult patient segments.
- Point-of-Care Genotyping:CRISPR-based diagnostic platforms enable rapid alpha-thalassemia carrier screening in high-prevalence populations, expanding addressable screening volumes in Southeast Asian and Mediterranean corridors.
Industry Challenges
- Vector Manufacturing Talent Scarcity:Cell culture and downstream processing expertise for lentiviral production concentrates among a limited pool of biologics specialists, inflating compensation costs and constraining capacity expansion.
- Long-Tinal Follow-Up Infrastructure:Gene therapy developers must maintain 15-year post-administration surveillance registries to satisfy FDA and EMA pharmacovigilance obligations for integrating vector products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha Thalassemia Market |
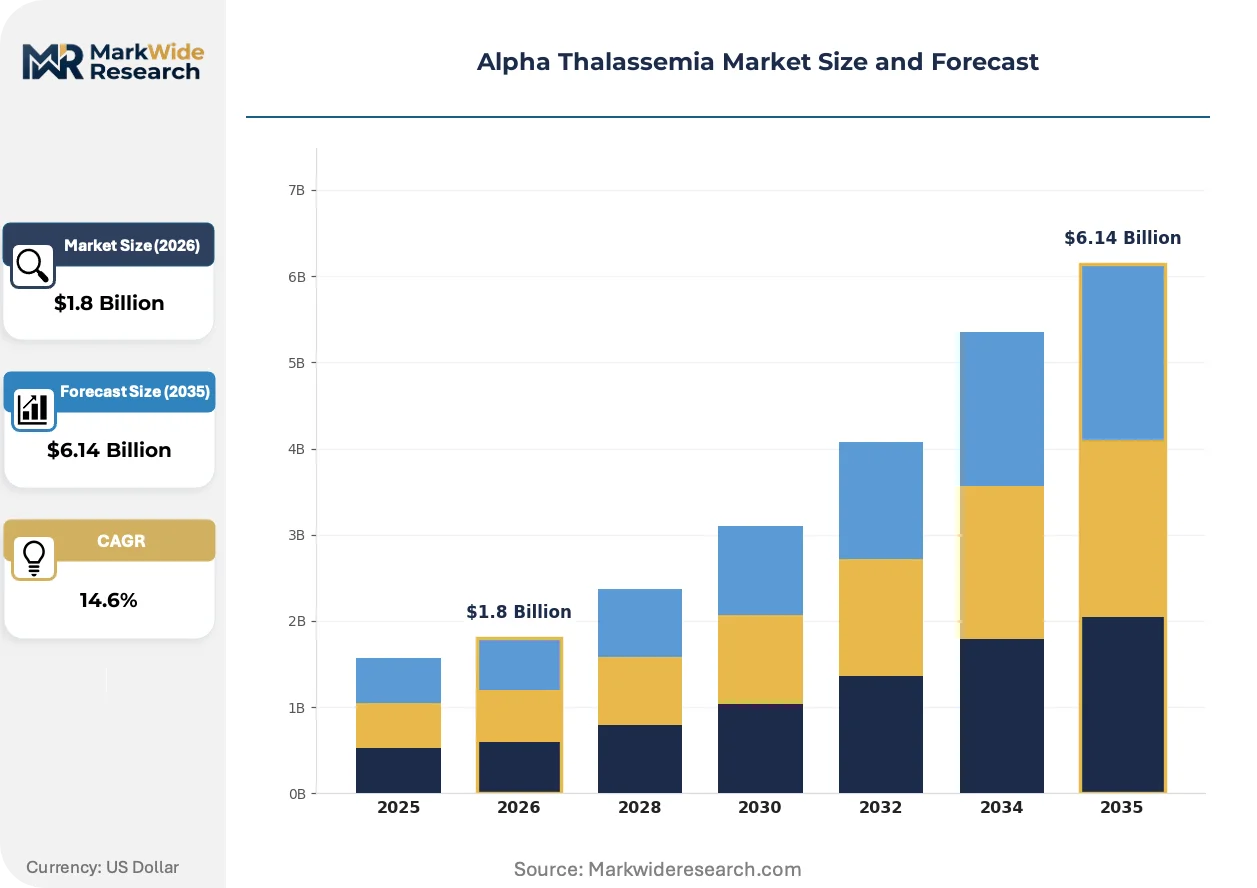
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Transfusion, Iron Chelation Therapy, Gene Therapy, Folic Acid Application: Clinical Trials, Blood Donation, Disease Management, Patient Education End User: Hospitals, Clinics, Research Institutes, Blood Banks Delivery Mode: Intravenous, Oral, Subcutaneous, Others |
| Companies Covered | Bluebird Bio, Sun Pharmaceutical Industries Ltd., Agios Pharmaceuticals, Taro Pharmaceutical Industries Ltd., CHIESI Farmaceutici S.p.A., Novartis Pharmaceuticals Corporation, Acceleron Pharma, FRESENIUS SE & Co. KGaA, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha Thalassemia Market Emerging Trajectories
Next-generation hemoglobinopathies interventions are unifying previously separate therapeutic modalities, compressing the boundary between transfusion medicine, transplantation, and genetic medicine into integrated care pathways.
Base editing technologies are unifying the precision of CRISPR-Cas9 with reduced double-strand break risk, enabling targeted correction of alpha-globin regulatory elements without exogenous DNA integration. Academic medical centers in Boston and London are advancing first-in-human protocols, with manufacturing partnerships scaling GMP-compatible ribonucleoprotein production. This approach is unifying the safety profile required for pediatric populations with the durability demands of lifelong hemoglobin correction.
The EU AI Act imposes risk-classification and documentation requirements on machine learning tools used for genotype-phenotype correlation and patient stratification in rare disease trials. Developers must establish algorithmic transparency and human oversight protocols for computational patient selection, adding compliance overhead to biomarker-driven enrollment. European thalassemia centers are responding by segregating AI-assisted screening tools from automated decision systems to maintain regulatory separation.
Hospital procurement for thalassemia care is consolidating around bundled payment models that capitate transfusion, chelation, and complication management into single contracts. United States sickle cell and thalassemia centers of excellence are displacing fee-for-service blood bank relationships with multi-year risk arrangements. This restructuring is most visible in California and New York, where Medicaid managed care organizations pilot outcomes-based contracts for chronic transfusion programs.
Alpha Thalassemia Market Segmentation
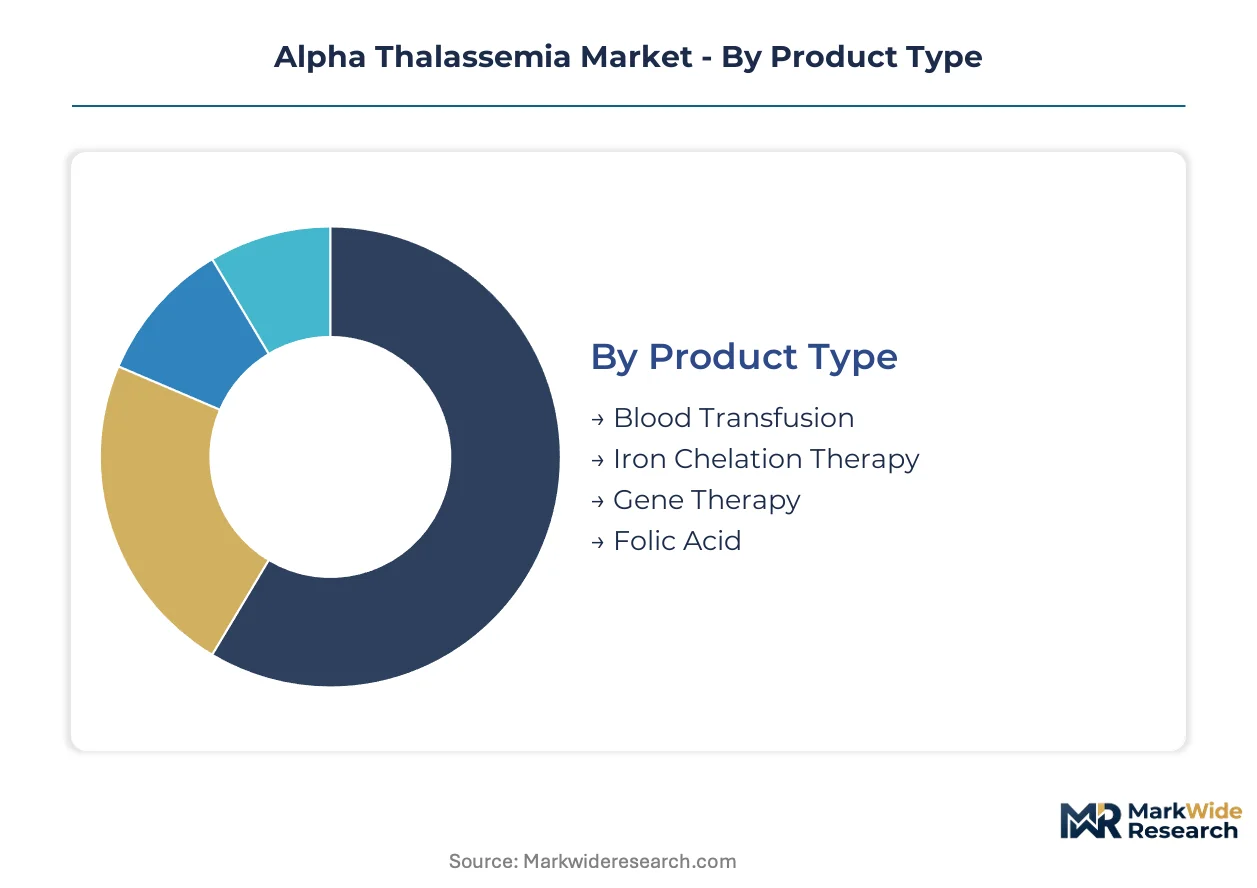
Segmentation in alpha thalassemia care reveals how therapeutic modalities compete for capital allocation across chronic management and curative intervention models. Hospital procurement strategies differ sharply between transfusion-dependent patient cohorts and candidates for one-time gene therapy administration.
Product Type:
Standardization dominates transfusion and chelation products, while gene therapy demands bespoke manufacturing protocols for each patient.
- Gene Therapy:Lentiviral vector-based ex vivo modification of autologous hematopoietic stem cells produces patient-specific therapeutic products. United States sickle cell and thalassemia centers of excellence are investing in apheresis and infusion infrastructure to capture these high-complexity cases. Manufacturing scale-up constraints limit addressable volume despite superior clinical outcomes.
- Blood Transfusion:Leukoreduced packed red blood cell units constitute the volume foundation of severe hemoglobin H disease management. Mediterranean and Southeast Asian patient corridors drive procurement scale, with hospital blood banks negotiating multi-year supply contracts against chronic demand baselines.
- Iron Chelation Therapy:Deferasirox oral tablets and deferoxamine infusions manage iron overload secondary to chronic transfusion.
- Folic Acid:Supplementation supports erythropoiesis in hemolytic states across all disease severity tiers.
Most installed capacity flows through Blood Transfusion. Expansion is steepest in Gene Therapy.
Application:
Revenue concentration shifts from episodic intervention toward longitudinal disease management platforms that integrate multiple therapeutic touchpoints.
- Disease Management:Comprehensive care programs bundle transfusion scheduling, iron monitoring, and complication surveillance into continuous patient relationships. United States Medicaid managed care organizations in California and New York are piloting outcomes-based contracts that capitate total cost of care.
- Clinical Trials:Gene therapy and base editing protocols require specialized investigative sites with GMP vector handling capabilities. Academic medical centers in Boston and London anchor multinational enrollment networks for alpha-globin targeting interventions.
- Blood Donation:Altruistic and directed donation programs supply phenotypically matched units for alloimmunized patients.
- Patient Education:Genetic counseling and carrier screening expansion addresses Southeast Asian and Mediterranean prevalence corridors.
Disease Management commands the largest share of recurring expenditure. Clinical Trials are expanding most quickly as pipeline assets advance.
End User:
Site-of-care economics favor centralized high-volume hubs over distributed low-complexity settings for advanced therapeutic delivery.
- Hospitals:Tertiary centers with dedicated thalassemia programs capture gene therapy referrals and complex transfusion medicine cases. Bundled payment models in the United States consolidate margin pools around comprehensive disease management rather than discrete service billing.
- Research Institutes:Academic medical centers manufacture clinical-grade vectors and conduct first-in-human gene editing protocols. Manufacturing partnerships with contract development organizations extend GMP capacity for lentiviral production.
- Clinics:Community settings manage stable transfusion patients and oral chelation monitoring.
- Blood Banks:Collection and processing infrastructure supplies phenotyped units for chronic transfusion programs.
Hospitals retain the dominant share of high-value therapeutic delivery. Research Institutes are gaining capacity fastest as manufacturing networks mature.
Delivery Mode:
Patient adherence and nursing burden drive formulation preferences across chronic versus acute intervention contexts.
- Intravenous:Blood transfusion and deferoxamine chelation require infusion center infrastructure with specialized nursing protocols. United States hospital systems are reconfiguring capacity as gene therapy reduces chronic transfusion dependence among eligible patients.
- Oral:Deferasirox dispersible tablets improve adolescent and young adult adherence compared to subcutaneous pump therapy. Formulation innovation targets reduced dosing frequency to close persistence gaps.
- Subcutaneous:Continuous deferoxamine infusion via portable pump remains standard for severe iron overload.
- Others:Intramuscular and intrathecal routes address specific complication management scenarios.
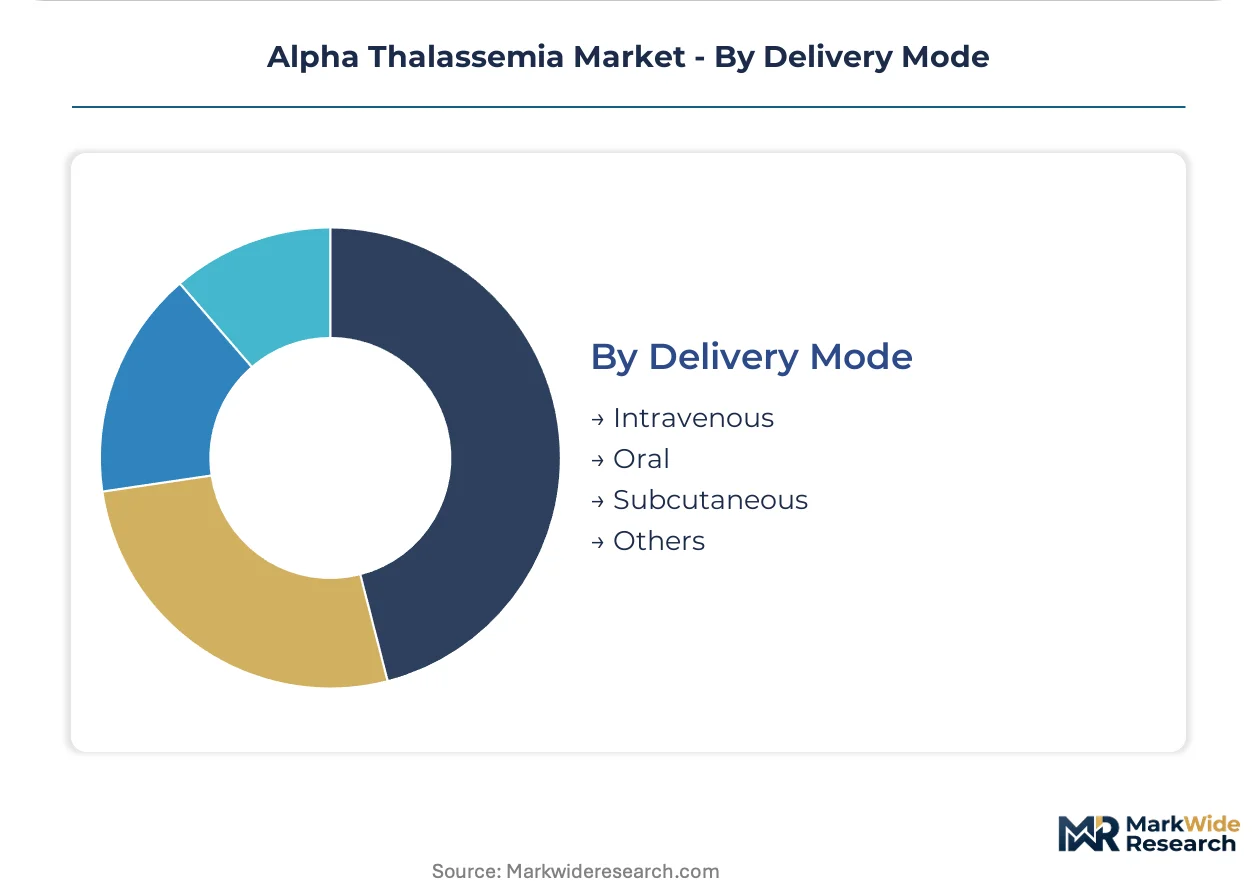
Intravenous delivery maintains the largest installed infrastructure base. Oral formulations are climbing the fastest as adherence-optimized products launch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand concentrates gene therapy trial enrollment for hemoglobinopathies, while Italy anchors Mediterranean transfusion medicine networks through specialized thalassemia centers.
United States
FDA breakthrough therapy designations compress development timelines for alpha-globin targeting interventions. CMS pilots outcomes-based reimbursement for chronic transfusion programs in California and New York Medicaid managed care markets. Boston and London academic medical centers anchor multinational enrollment networks for base editing protocols.
United Kingdom
Specialized fetal surgery centers in London develop in utero intervention capabilities for hemoglobin Bart hydrops fetalis. The MHRA operates accelerated access pathways for rare disease gene therapies under post-Brexit regulatory autonomy. Oxford and Cambridge manufacturing partnerships scale GMP-compatible ribonucleoprotein production for academic protocols.
Italy
CHIESI Farmaceutici S.p.A. anchors iron chelation innovation from its Parma headquarters, targeting Mediterranean patient corridors. EMA priority medicines status shapes trial enrollment incentives for severe hemoglobin H disease candidates. Milan and Rome thalassemia centers consolidate patient volumes sufficient to justify dedicated apheresis capabilities.
Thailand
Southeast Asian prevalence corridors drive carrier screening expansion and transfusion infrastructure investment. The national pharmaceutical regulator aligns with ASEAN harmonization frameworks for rare disease therapy approval. Bangkok hospital systems configure gene therapy infusion suites to capture referrals from neighboring high-prevalence countries.
Switzerland
Swissmedic's precision medicine frameworks accommodate one-time curative pricing models against decades of chronic care cost baselines. Novartis Pharmaceuticals Corporation leverages its Basel headquarters to anchor transfusion medicine portfolio relationships across European hospital formulary networks. Zurich and Geneva research institutes manufacture clinical-grade vectors for multinational trial supply.
Alpha Thalassemia Market Vendor Landscape
Top-tier vendors anchor gene therapy development, while mid-tier pharmaceutical manufacturers concentrate on transfusion support and iron chelation products. The competitive structure fragments across therapeutic modalities rather than consolidating around integrated care platforms. Three archetypes dominate: lentiviral vector specialists, transfusion medicine incumbents, and iron chelation formulation innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturing scale-up constraints limit addressable volume.
Within the gene therapy archetype, Bluebird Bio exemplifies lentiviral vector development intensity despite manufacturing complexity. Novartis Pharmaceuticals Corporation occupies a position among transfusion medicine incumbents leveraging hospital formulary relationships. CHIESI Farmaceutici S.p.A. represents iron chelation specialists targeting reduced dosing burden through formulation innovation.
| Leading Market Players |
|---|
| Bluebird Bio |
| Sun Pharmaceutical Industries Ltd. |
| Agios Pharmaceuticals |
| Taro Pharmaceutical Industries Ltd. |
| CHIESI Farmaceutici S.p.A. |
| Novartis Pharmaceuticals Corporation |
| Acceleron Pharma |
| FRESENIUS SE & Co. KGaA |
| Amgen Inc. |
| Others |
Supply Flow & Price Mechanics
Curative versus chronic care bifurcation separates gene therapy's one-time administration pricing from decades of transfusion and chelation cost baselines, with hospital procurement teams negotiating value-based contracts that capitate total cost of care against episodic billing. This divergence manifests in supply chain configurations where lentiviral vector manufacturing concentrates among North American and European contract manufacturers, while blood product supply chains distribute through regional hospital networks.
Pricing Analysis
Capacity additions in Switzerland and the United States are reshaping price floors for lentiviral vector production as suspension-based platforms displace adherent cell culture. Three-tier pricing structure across premium gene therapy, standard transfusion programs, and economy chelation generics reflects manufacturing complexity and clinical outcome differentiation. Cost compression in oral iron chelation intensifies because of patent expirations and generic entry. Medicaid managed care organizations in California exhibit highest price sensitivity for chronic transfusion programs, while private payers at centers of excellence accept premium pricing for curative interventions.
Supply Chain Analysis
Vector manufacturing talent scarcity in Boston, London, and Basel constrains lot-to-lot consistency for ex vivo gene modification therapies targeting alpha-globin defects. Plasmid DNA supply draws from North American and European contract manufacturers, while leukoreduced packed red blood cell units source from regional blood banking networks. Single-source vulnerability for critical raw materials creates supply chain risk. Distribution runs through specialized thalassemia centers of excellence that capture bundled payment contracts and maintain apheresis capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through FDA breakthrough therapy and EMA priority medicines pathways that compress development timelines and reshape reimbursement negotiations for rare blood disorders.
For Market Incumbents: Hedge manufacturing scale-up risk by securing multi-year plasmid DNA supply agreements with contract manufacturers before capacity constraints tighten. Anchor hospital formulary relationships through transfusion medicine portfolios that capture chronic care revenue while gene therapy eligibility criteria narrow addressable patient populations. Diversify into base editing technologies to offset lentiviral vector manufacturing complexity.
For New Entrants and Emerging Players: Academic medical center partnerships provide access to GMP vector handling capabilities and multinational enrollment networks for first-in-human protocols. Thailand's Southeast Asian prevalence corridor offers the most penetrable geography for point-of-care genotyping platforms and carrier screening expansion. Target fetal surgery centers developing in utero intervention capabilities as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scale-up constraints limit addressable volume for gene therapy developers despite superior clinical outcomes. Long-term viability favors platforms that unify transfusion medicine, transplantation, and genetic medicine into integrated care pathways. Watch FDA and EMA pharmacovigilance obligation enforcement as a signal for post-market surveillance infrastructure requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Suspension-based lentiviral production in Boston and London improves lot-to-lot consistency for ex vivo therapies. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-III transition timelines for hemoglobin H disease candidates. |
| Hospital System Partnership | United States sickle cell and thalassemia centers of excellence consolidate patient volumes for gene therapy infusion suites. |
| Reimbursement Strategy | CMS outcomes-based pilots in California and New York Medicaid reshape chronic transfusion program contracting. |
| Pipeline Diversification | Base editing technologies in Oxford and Cambridge manufacturing partnerships reduce double-strand break risk for pediatric populations. |
Methodological Framework
Multiple input streams — regulatory filings, clinical trial registries, hospital procurement databases, and payer policy documents — were reconciled against primary interviews with gene therapy development executives, formulary directors at thalassemia centers of excellence, regulatory affairs leads, and iron chelation portfolio managers. Secondary validation drew from FDA orphan drug designation records, EMA priority medicines submissions, ClinicalTrials.gov enrollment data, and CMS reimbursement policy bulletins. Bottom-up patient volume estimates and top-down market sizing approaches were triangulated to constrain variance.
Data-stream reconciliation across product type, application, end user, and delivery mode dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling. Treatment line stratification, regional regulatory cluster differentiation, and patient population severity tiers informed forecast inputs. Manufacturing capacity expansion timelines and reimbursement framework evolution anchored scenario testing.
Revisions become necessary when FDA or EMA accelerated approval pathway criteria shift, when plasmid DNA supply concentration triggers single-source disruptions, or when CMS value threshold calibrations for single-administration gene therapies diverge from transfusion cost baselines. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hypereosinophilic Syndrome Market
Hematology
Bone Marrow Transplant Market
Hematology
Hemoglobin Analyzer Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Rare Hematology Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Global Hematology Diagnostics Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Anemia Drugs Market
Hematology
Non-Hodgkin Lymphoma Treatment Market