
 Global Hodgkin Lymphoma Treatment Market | 2026-2036
Global Hodgkin Lymphoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hodgkin Lymphoma Treatment Market Foresight
Buyer concentration among integrated oncology networks is pivoting toward large hospital systems and specialty infusion centers that negotiate formulary placement directly. Bristol-Myers Squibb Company leverages its immuno-oncology portfolio to anchor positions in academic medical centers. Merck & Co. Inc. competes through PD-1 inhibitor access programs that sustain volume across community oncology practices. F. Hoffmann-La Roche Ltd differentiates via companion diagnostic bundling that controls treatment selection workflows.
Hodgkin lymphoma treatment encompasses multimodal therapeutic interventions targeting malignant Reed-Sternberg cells, combining cytotoxic agents, monoclonal antibodies, and radiation modalities to achieve durable remission in lymphoid tissue malignancies. Immunotherapy segments lead value generation as checkpoint inhibitors displace conventional chemotherapy in frontline settings, while targeted therapy occupies the fastest-expanding niche with antibody-drug conjugates addressing relapsed populations. Stem cell transplant remains a mature, high-acuity procedure concentrated at tertiary centers with specialized cellular processing capabilities.
The FDA maintains stringent oncology drug approval standards through breakthrough therapy and accelerated approval pathways, while the EMA enforces centralized marketing authorization with post-authorization efficacy studies under the EU pharmaceutical legislation. WHO inclusion of essential cancer medicines shapes procurement priorities in lower-income health systems. Stakeholders must monitor evolving reimbursement evidence requirements as health technology assessment bodies tighten cost-effectiveness thresholds for novel combination regimens.
Market Dynamics
Checkpoint inhibitors are compressing frontline chemotherapy protocols across oncology networks, forcing treatment hierarchies to restructure around immunotherapy-first sequencing and companion diagnostic dependencies.
Growth Catalysts
- Accelerated Approval Pathways:The FDA breakthrough therapy designation compresses development timelines for novel combination regimens, pulling forward commercial access by 18-24 months versus standard review.
- Academic Medical Center Consolidation:Integrated oncology networks in the United States and Germany are centralizing Hodgkin lymphoma care, creating concentrated demand pools that justify premium biologic procurement.
- Antibody-Drug Conjugate Pipelines:Next-generation ADCs targeting CD30-positive relapsed populations are expanding addressable patient cohorts beyond first-line settings into salvage therapy.
Market Restraints
- Companion Diagnostic Fragmentation:Biomarker testing workflows require specialized pathology infrastructure that concentrates at tertiary centers, limiting community oncology access to targeted therapies.
- Stem Cell Transplant Capacity Constraints:Autologous transplant procedures depend on cellular processing facilities concentrated in Japan, Germany, and select United States urban clusters, creating geographic access inequities.
- Reimbursement Evidence Thresholds:Health technology assessment bodies in England and France are tightening cost-effectiveness requirements for combination immunotherapy regimens, delaying formulary placement.
Strategic Opportunities
- India's Essential Medicines Expansion:WHO inclusion criteria are reshaping procurement priorities in lower-income health systems, creating volume opportunities for biosimilar checkpoint inhibitors.
- Outpatient Infusion Center Networks:Specialty infusion sites in Texas, Florida, and California are displacing hospital-based administration, reducing per-dose facility fees and expanding patient throughput.
- Real-World Evidence Mandates:The EMA post-authorization efficacy study framework creates competitive openings for manufacturers with established patient registry infrastructure.
Industry Challenges
- Cellular Therapy Manufacturing Scale-Up:CAR-T production requires vector manufacturing capacity that remains concentrated at single-source suppliers, creating batch failure vulnerabilities.
- Cross-Border Regulatory Divergence:Discordant labeling requirements between the FDA and PMDA force duplicate clinical program investments for Japan market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hodgkin Lymphoma Treatment Market |
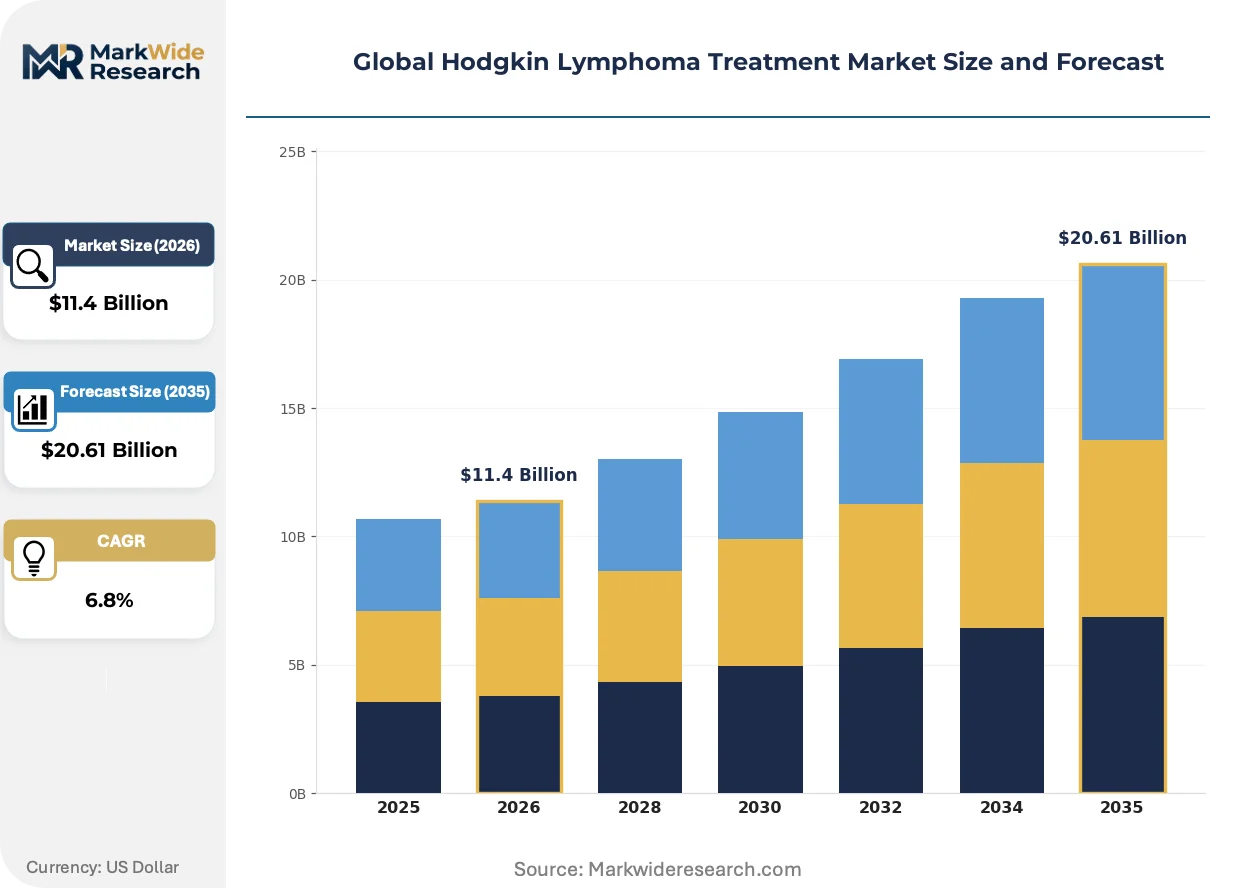
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Chemotherapy, Immunotherapy, Radiation Therapy, Targeted Therapy, Stem Cell Transplant Therapy Area: Early Stage, Advanced Stage, Relapsed, Refractory Patient Profile: Adult, Pediatric, Geriatric, Immunocompromised Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | Bristol-Myers Squibb Company, Merck & Co. Inc., F. Hoffmann-La Roche Ltd, Seagen Inc., Amneal Pharmaceuticals, Inc., Pfizer, Takeda Pharmaceutical Company Limited, Biogen Inc., AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hodgkin Lymphoma Treatment Market Shifts & Advancements
Biomarker-driven patient stratification is fragmenting the homogeneous chemotherapy model into precision-segmented treatment pathways, with diagnostic ownership becoming as contested as therapeutic market share.
PD-1 and PD-L1 checkpoint blockade is rewriting the standard-of-care hierarchy for advanced-stage Hodgkin lymphoma. Academic medical centers in Boston, Heidelberg, and Tokyo are adopting immunotherapy-first protocols for newly diagnosed patients. This shift is compressing cytotoxic chemotherapy volumes and reallocating infusion center capacity toward biologic administration.
The EMA centralized marketing authorization procedure now mandates post-authorization efficacy studies under EU pharmaceutical legislation revisions. Manufacturers face expanded evidence-generation obligations that extend 3-5 years beyond initial approval. Relapsed/refractory segments bear the heaviest compliance burden as regulators demand survival data that trials were not powered to deliver.
Integrated delivery networks are unbundling site-of-care decisions from physician preference, steering patients toward lowest-cost qualified infusion settings. Community oncology practices in the United States are losing Hodgkin lymphoma volumes to hospital outpatient departments and freestanding infusion centers. This channel migration is most pronounced in Medicare Advantage populations where plan-owned facilities capture referral flows.
Global Hodgkin Lymphoma Treatment Market Segmentation
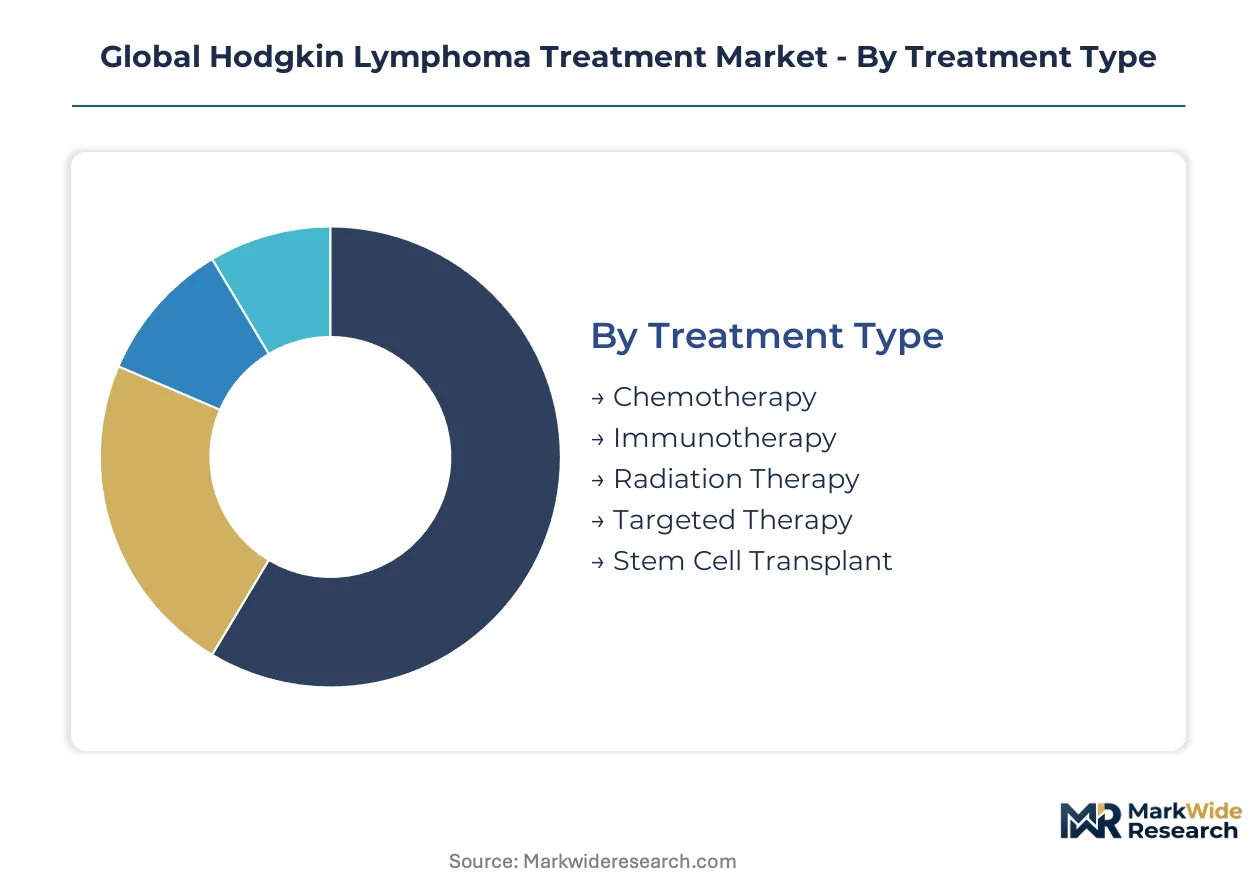
Treatment modality selection in Hodgkin lymphoma hinges on staging accuracy, biomarker status, and institutional capability. Segmentation reveals where capital deployment concentrates across manufacturing, clinical infrastructure, and patient access programs.
Treatment Type:
Capital intensity varies sharply across modalities, with cellular processing facilities and companion diagnostic infrastructure demanding the heaviest upfront investment.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 pathways require cold-chain distribution networks and specialized infusion nursing. Demand clusters at academic medical centers in Boston, Heidelberg, and Tokyo where biomarker testing workflows integrate with treatment selection.
- Targeted Therapy:Antibody-drug conjugates bind cytotoxic payloads to CD30-positive malignant cells, enabling precision delivery. Manufacturing scale-up for linker technologies concentrates at single-source suppliers, creating supply vulnerabilities for relapsed patient cohorts.
- Chemotherapy:Cytotoxic combinations remain the backbone for resource-limited settings and pediatric protocols.
- Radiation Therapy:Linear accelerator capacity constrains geographic access, particularly in lower-income health systems.
- Stem Cell Transplant:Autologous procedures depend on cellular processing laboratories concentrated in Japan, Germany, and select United States urban clusters.
Immunotherapy absorbs the bulk of installed capacity; targeted therapy is expanding most quickly.
Therapy Area:
Clinical trial enrollment and regulatory approval pathways diverge sharply by disease stage, reshaping manufacturer prioritization.
- Advanced Stage:Bulky disease and B-symptom presentations drive checkpoint inhibitor adoption as first-line intervention. The FDA breakthrough therapy designation has compressed development timelines for novel combinations in this segment.
- Relapsed:Salvage therapy protocols demand cross-functional coordination between medical oncology and transplant specialists. Antibody-drug conjugates are displacing conventional chemotherapy in second-line settings at centers with companion diagnostic capabilities.
- Early Stage:De-escalation trials are reducing chemotherapy exposure through PET-adapted protocols.
- Refractory:CAR-T investigation programs concentrate at tertiary centers with vector manufacturing partnerships.
Advanced stage commands the largest patient volume; relapsed segments are climbing the fastest.
Patient Profile:
Regulatory submission strategies and dosing protocols fragment across age and immune competence strata.
- Adult:Frontline immunotherapy protocols are standardizing at integrated oncology networks, with PD-1 inhibitor access programs sustaining volume across community practices.
- Pediatric:Long-term cardiotoxicity surveillance requirements shape chemotherapy selection, favoring protocols with reduced anthracycline exposure. Cooperative group trials in the United States and Europe define standard of care.
- Geriatric:Comorbidity burden drives de-escalation interest, though frailty scoring adoption remains uneven.
- Immunocompromised:HIV-associated Hodgkin lymphoma requires modified dosing and opportunistic infection prophylaxis.
Adult populations anchor commercial revenue; pediatric segments carry the steepest evidence-generation obligations.
Delivery Mode:
Site-of-care economics and patient convenience preferences are restructuring administration channel selection.
- Intravenous:Infusion center capacity constraints are shifting administration from hospital outpatient departments to freestanding specialty sites in Texas, Florida, and California. Medicare Advantage plan-owned facilities capture increasing referral flows.
- Subcutaneous:Self-administration potential reduces facility fee exposure, though cold-chain requirements limit community pharmacy dispensing.
- Oral:Fixed-duration regimens enable treatment completion without infusion logistics.
- Intramuscular:Limited current application in Hodgkin lymphoma protocols.
Intravenous delivery dominates current infrastructure; subcutaneous formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where reimbursement frameworks favor novel biologics and academic medical centers anchor treatment innovation. These three markets absorb the majority of checkpoint inhibitor volumes and set protocol standards that diffuse to secondary markets.
United States
FDA breakthrough therapy designations compress development timelines by 18-24 months, pulling forward commercial access for novel combinations. Integrated oncology networks in Boston and New York centralize Hodgkin lymphoma care, creating concentrated demand pools. Medicare Advantage plan-owned facilities in Texas and Florida capture increasing referral flows through site-of-care steering.
Germany
EMA centralized marketing authorization mandates post-authorization efficacy studies that extend evidence obligations 3-5 years beyond initial approval. Heidelberg anchors immunotherapy-first protocol adoption alongside Berlin-Brandenburg's tertiary transplant centers. Health technology assessment bodies tighten cost-effectiveness thresholds for combination regimens, delaying formulary placement in select regions.
Japan
PMDA discordant labeling requirements force duplicate clinical program investments for market access. Tokyo and Osaka metropolitan clusters concentrate autologous stem cell transplant capacity with specialized cellular processing facilities. The national health insurance system maintains distinct reimbursement categories for biologics that shape physician prescribing patterns.
United Kingdom
NICE technology appraisals enforce cost-effectiveness thresholds that filter novel combination regimens through multi-year evaluation cycles. London and Manchester academic centers participate in cooperative group trials defining pediatric protocol standards. NHS England's specialized commissioning framework concentrates CAR-T investigation programs at designated tertiary sites.
India
WHO essential medicines inclusion criteria reshape procurement priorities in public health systems, creating volume opportunities for biosimilar checkpoint inhibitors. Maharashtra and Karnataka host expanding oncology networks that bridge tertiary and community care tiers. CDSCO accelerated approval pathways for oncology biologics are shortening registration timelines for multinational sponsors.
Global Hodgkin Lymphoma Treatment Market Competitive Landscape
United States producers anchor the premium-tier immunotherapy segment; European specialists hold positions in companion diagnostics and antibody-drug conjugates. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with immuno-oncology portfolios, mid-cap biotechs with single-asset dependencies, and emerging biosimilar manufacturers targeting volume markets. Dominant competitive moves include M&A for pipeline assets and strategic partnerships for companion diagnostic bundling.
Within the integrated pharmaceutical tier, Bristol-Myers Squibb Company and Merck & Co. Inc. occupy positions defined by PD-1 inhibitor market presence, while F. Hoffmann-La Roche Ltd exemplifies the diagnostic-therapeutic bundling archetype through companion diagnostic control over treatment selection workflows. These three entities represent distinct strategic postures: portfolio breadth, access program scale, and vertical integration into biomarker infrastructure respectively.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck & Co. Inc. |
| F. Hoffmann-La Roche Ltd |
| Seagen Inc. |
| Amneal Pharmaceuticals, Inc. |
| Pfizer |
| Takeda Pharmaceutical Company Limited |
| Biogen Inc. |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Integrated oncology networks in the United States, Germany, and Japan concentrate procurement volume for checkpoint inhibitors, anchoring a value-based pricing model where outcomes data and biomarker stratification determine reimbursement tiers. Cold-chain distribution costs and companion diagnostic bundling compress margins for manufacturers lacking vertical control over pathology workflows.
Pricing Analysis
High-volume academic medical centers command preferential access terms against premium-priced community oncology practices absorbing full wholesale acquisition costs. Price differentiation hinges on biomarker testing integration and companion diagnostic ownership, with institutions controlling diagnostic workflows extracting 15-25% cost advantages. Pricing pressure stems from health technology assessment bodies tightening cost-effectiveness thresholds for combination regimens. Pediatric and geriatric segments exhibit highest price sensitivity due to limited formulary placement and reduced reimbursement bandwidth.
Supply Chain Analysis
Regional distribution centers in Indianapolis, Frankfurt, and Osaka anchor hub-and-spoke cold-chain networks for biologics requiring continuous temperature monitoring. Manufacturing concentration in Switzerland, Ireland, and Singapore for active pharmaceutical ingredients creates single-source dependencies for linker technologies in antibody-drug conjugates. Tariff exposure on Chinese-sourced raw materials and single-source vector manufacturing for cellular therapies elevate supply risk. Distribution runs through specialty infusion center networks displacing hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hodgkin lymphoma treatment market functions as a vertical-integration race where companion diagnostic ownership and cold-chain distribution control determine margin capture. Players are pursuing backward integration into biomarker testing infrastructure to lock in treatment selection workflows.
For Market Incumbents: Lock in formulary positions at consolidating integrated oncology networks through long-term outcomes-based contracts that bundle diagnostics with therapeutic access. Defend against biosimilar checkpoint inhibitor entrants by deepening pathology laboratory partnerships and securing exclusive companion diagnostic placement at tertiary transplant centers in Boston, Heidelberg, and Tokyo.
For New Entrants and Emerging Players: The gap between premium-priced PD-1 inhibitors and economy-tier chemotherapy protocols in India's public procurement systems offers white-space entry. Target Maharashtra and Karnataka oncology networks with biosimilar checkpoint inhibitors priced to WHO essential medicines thresholds. Pursue CDSCO accelerated approval pathways to compress registration timelines against multinational incumbents.
For Investors and Strategic Acquirers: The window for entry favors mid-cap biotechs with single-asset antibody-drug conjugate pipelines and established EMA post-authorization study infrastructure. Long-term viability centers on CAR-T manufacturing capabilities and vector production partnerships. Monitor FDA breakthrough therapy designation velocity as the signal for portfolio prioritization shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Bundling | Roche's vertical control over PD-L1 testing anchors treatment selection workflows at academic centers. |
| EMA Post-Authorization Study Investment | Extended evidence obligations create competitive moats for manufacturers with established patient registries. |
| Specialty Infusion Center Network Expansion | Texas and Florida site-of-care migration reduces facility fees and captures Medicare Advantage referral flows. |
| Biosimilar Checkpoint Inhibitor Registration | CDSCO accelerated pathways in India unlock volume opportunities in WHO essential medicines procurement. |
| CAR-T Vector Manufacturing Partnership | Single-source supplier concentration demands captive production capacity to mitigate batch failure risk. |
Research Methodology
Multi-period observation of FDA approval designations, EMA marketing authorization timelines, and formulary placement patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors at integrated oncology networks, and payer access specialists. Secondary validation drew from FDA filings, EMA centralized procedure documents, ClinicalTrials.gov enrollment data, and hospital procurement databases. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation refined segment estimates.
Input-output matrices mapped treatment modality adoption against biomarker testing penetration and reimbursement category evolution across the analysis window. Segmentation dimensions included treatment line, patient age strata, administration route, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical protocol adoption rates, with inputs from cold-chain distribution cost indices and companion diagnostic placement velocity.
Inputs from regulatory filing databases and GPO contract repositories were available through the study window; gaps in real-world evidence registry completeness introduce uncertainty bands around relapsed/refractory segment forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Thalassemia Treatment Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Venous Blood Collection Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Bone Marrow Transplant Market
Hematology
Multiple Myeloma Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Thrombocytopenia Treatment Market
Hematology
Myelofibrosis Treatment Market
Hematology
Patient Blood Management Market
Hematology
Global Hematology Market