
 Safety Lancet Market | 2026-2036
Safety Lancet Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Lancet Market Analysis
The capital-intensity divergence between automated assembly lines and manual packaging operations is collapsing as mid-tier manufacturers deploy robotics to close the gap. BD sustains North American hospital channel dominance through captive needle-forming capacity and direct distribution networks. Roche leverages its diagnostics ecosystem to bundle safety lancets with glucose monitoring platforms, locking in recurring consumable revenue. HTL-STREFA anchors European private-label supply through high-volume contract manufacturing agreements with pharmacy chains.
A safety lancet is a spring-loaded or pressure-activated puncture device incorporating an integrated needle or blade that retracts automatically after skin incision, typically engineered with 28-33 gauge needles and penetration depths of 1.5-2.5 millimeters to optimize capillary blood flow while minimizing tissue trauma. Its primary commercial purpose is to enable standardized, operator-protected blood sampling for point-of-care diagnostics, home glucose monitoring, and clinical laboratory specimen collection. Single-use lancets command the largest volume share across hospital-based care delivery, where infection control protocols prohibit reuse, while safety devices capture premium positioning through OSHA-compliant sharps protection engineering that eliminates post-incision needle exposure. Point-of-care testing represents the fastest-growing delivery mode as decentralized diagnostic workflows expand beyond traditional laboratory settings into retail clinics and ambulatory surgical centers.
The FDA enforces sharps injury prevention through its Needlestick Safety and Prevention Act requirements, while OSHA's Bloodborne Pathogens Standard mandates engineered safety controls in healthcare workplaces, collectively elevating retractable-lancet specifications above conventional alternatives in institutional procurement. The EU MDR and REACH frameworks impose biocompatibility and chemical substance restrictions on needle coatings and plastic housings, tightening market access for non-compliant manufacturers. Stakeholders must monitor evolving reimbursement codes for home versus clinical glucose testing as payors recalibrate coverage between self-management and supervised care delivery models.
Market Dynamics
Engineered sharps protection mandates from OSHA and the FDA are compressing procurement timelines across US hospital networks, forcing rapid specification upgrades from conventional lancets to retractable safety designs. This regulatory pressure is cascading through distribution channels, reshaping inventory management and supplier qualification protocols.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Mandated engineered safety controls in healthcare workplaces are elevating retractable-lancet specifications above conventional alternatives in institutional procurement.
- Home glucose monitoring:Diabetic patient self-management protocols are gaining clinical acceptance, accelerating demand for single-use safety devices optimized for capillary blood sampling.
- Point-of-care testing expansion:Decentralized diagnostic workflows are migrating beyond traditional laboratories into retail clinics and ambulatory surgical centers.
Market Restraints
- Specialized polymer feedstock volatility:Medical-grade ABS and polycarbonate resin prices fluctuate with petrochemical cycles, squeezing margin predictability for housing component manufacturers.
- Precision needle supply concentration:Captive needle-forming capacity concentrates among a limited set of vertically integrated producers, creating supply vulnerability for non-integrated assemblers.
- EU MDR biocompatibility requirements:Tightened chemical substance restrictions on needle coatings and plastic housings are extending compliance timelines and raising qualification costs.
Strategic Opportunities
- Retail pharmacy channel expansion:High-volume contract manufacturing agreements with pharmacy chains are opening private-label revenue streams for European producers.
- Integrated diagnostics bundling:Convergence of safety lancets with glucose monitoring platforms is locking in recurring consumable revenue through ecosystem lock-in.
- Robotics-enabled automation:Mid-tier manufacturers deploying automated assembly lines are collapsing the capital-intensity gap with tier-one producers.
Industry Challenges
- ISO 13485 certification timelines:Extended quality management system audits are delaying market entry for new device submissions.
- Legacy inventory obsolescence:Healthcare networks face write-down pressure from non-safety lancet stockpiles as procurement specifications tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Lancet Market |
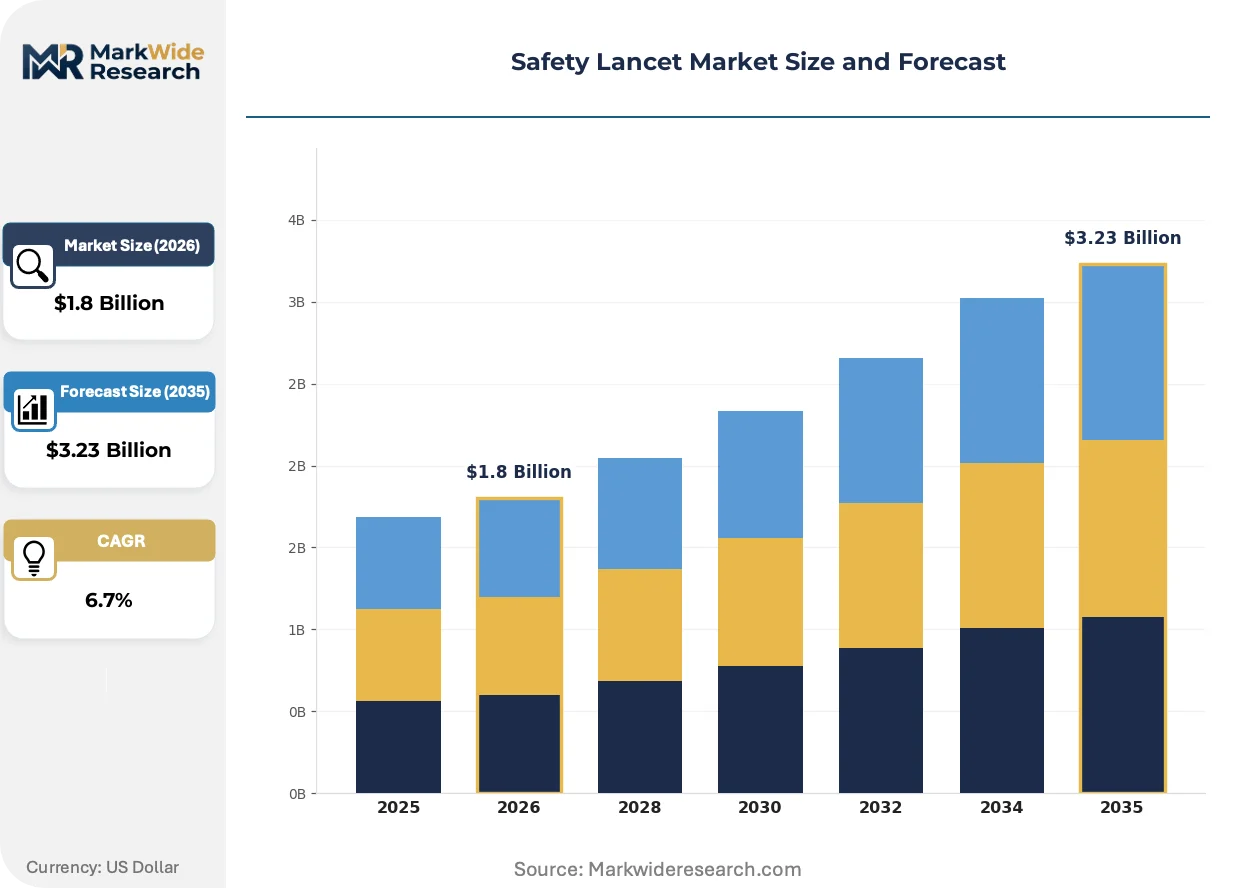
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Lancets, Single-Use Lancets, Disposable Lancets, Safety Devices Delivery Mode: Self-Management, Home Healthcare, Hospital-Based Care, Point-of-Care Testing End User: Diabetic Patients, Home Users, Medical Professionals, Laboratories Distribution Channel: Online, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Roche, Sarstedt AG & Co. KG, BD, HTL-STREFA, Greiner Bio-One International GmbH, Cardinal Health, Owen Mumford, Terumo, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Lancet Market Emerging Trajectories
Automation and regulatory convergence are redrawing competitive boundaries in safety lancet manufacturing. Device engineering is pivoting toward integrated protection mechanisms that eliminate operator exposure while maintaining sampling precision.
Spring-loaded retraction mechanisms are fragmenting the traditional distinction between premium and standard product tiers. Mid-tier manufacturers are adopting pressure-activated designs with automatic needle concealment, compressing the feature gap with established premium offerings. Hospital procurement committees are expanding vendor qualification to include these upgraded mechanical platforms.
REACH framework restrictions on chemical substances in needle coatings are forcing reformulation of lubricant and surface treatment chemistries. European manufacturers are accelerating biocompatibility testing programs to maintain CE marking validity under tightened substance restrictions. German producers with in-house polymer compounding capabilities are capturing specification leadership.
Home diagnostic consumption patterns are shifting volume toward pharmacy retail channels and away from hospital central supply. Patients managing diabetes through self-monitoring protocols are purchasing safety lancets through direct-to-consumer and retail clinic pathways. This channel rotation is visible across US and German markets where reimbursement structures favor self-management.
Safety Lancet Market Segmentation
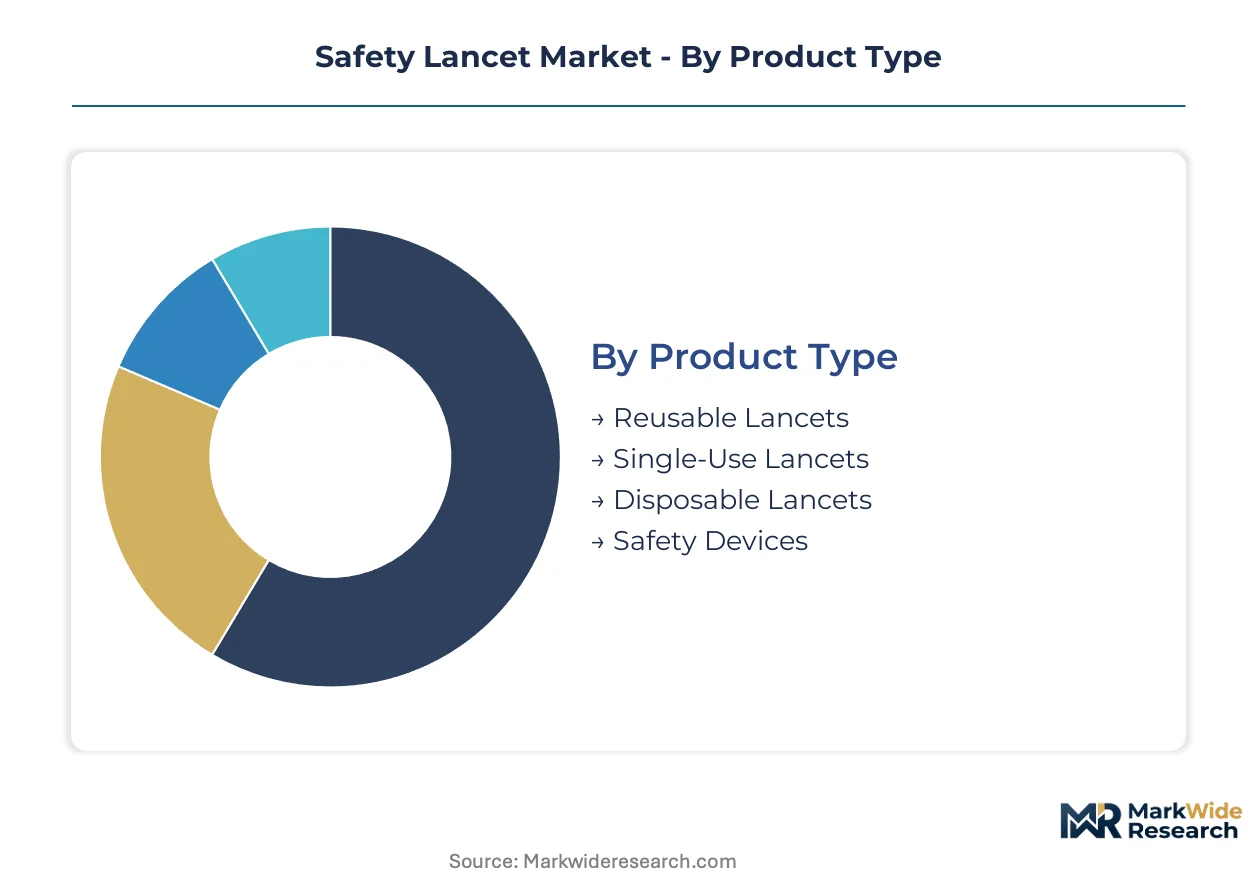
Safety lancet procurement specifications diverge sharply across clinical versus self-managed care settings, with regulatory mandates compressing the viable product mix in institutional channels while retail expansion opens volume pathways for simplified designs.
Product Type:
Single-use and safety-engineered formats face minimal substitution threat from reusable alternatives as OSHA and FDA sharps protection mandates harden procurement specifications against conventional designs.
- Single-Use Lancets:Polypropylene-housed devices with pre-sterilized 28-33 gauge needles dominate hospital central supply procurement where infection control protocols prohibit cross-patient contact. Demand concentrates in US acute care networks upgrading to OSHA-compliant inventory under the Bloodborne Pathogens Standard enforcement timeline.
- Safety Devices:Spring-loaded or pressure-activated mechanisms with automatic needle retraction eliminate post-incision exposure, commanding premium positioning in institutional procurement committees. German hospital networks anchor continental adoption through Greiner Bio-One and Sarstedt supply agreements that bundle retractable engineering with volume pricing.
- Disposable Lancets:Basic pressure-activated designs without integrated retraction mechanics serve cost-sensitive home glucose monitoring segments where regulatory pressure remains lighter.
- Reusable Lancets:Metal-bodied devices with replaceable needle cartridges retain niche presence in veterinary and research laboratory settings where single-patient use cycles reduce cross-contamination risk.
Single-use lancets retain volume leadership; safety devices hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates premium point-of-care formats from economy home healthcare units, with reimbursement differentials driving channel-specific specification divergence.
- Point-of-Care Testing:Retail clinic and ambulatory surgical center deployment demands compact, single-unit packaging compatible with decentralized diagnostic workflows. US retail pharmacy chains are expanding self-testing kiosk networks that bundle safety lancets with glucose and cholesterol screening platforms.
- Home Healthcare:Multi-unit blister packs with simplified activation mechanics serve Medicare-reimbursed diabetic self-management protocols where patient dexterity varies widely.
- Hospital-Based Care:Bulk-format dispensing systems integrate with automated supply cabinets in US and German acute care facilities.
- Self-Management:Direct-to-consumer channels favor travel-sized packaging with multilingual instructions for diabetic patient populations managing therapy independent of clinical supervision.
Home healthcare commands the largest installed base; point-of-care testing gains share fastest.
End User:
Application intensity varies dramatically between professional settings requiring OSHA documentation and home environments prioritizing ease-of-use over compliance certification.
- Diabetic Patients:The largest addressable population segment drives recurring consumable demand through daily glucose monitoring protocols, with US Medicare Advantage plans expanding coverage for self-testing supplies.
- Medical Professionals:Nursing staff and phlebotomy technicians operate under mandatory safety device requirements in hospital employment settings, with procurement committees disqualifying non-retractable alternatives.
- Home Users:Non-diabetic consumers purchasing wellness monitoring devices represent emerging demand for simplified safety lancet formats.
- Laboratories:High-throughput clinical reference labs specify automated lancing systems integrated with hematology analyzers, reducing manual handling requirements.
Diabetic patients generate the highest absolute volume; medical professionals enforce the strictest specification standards.
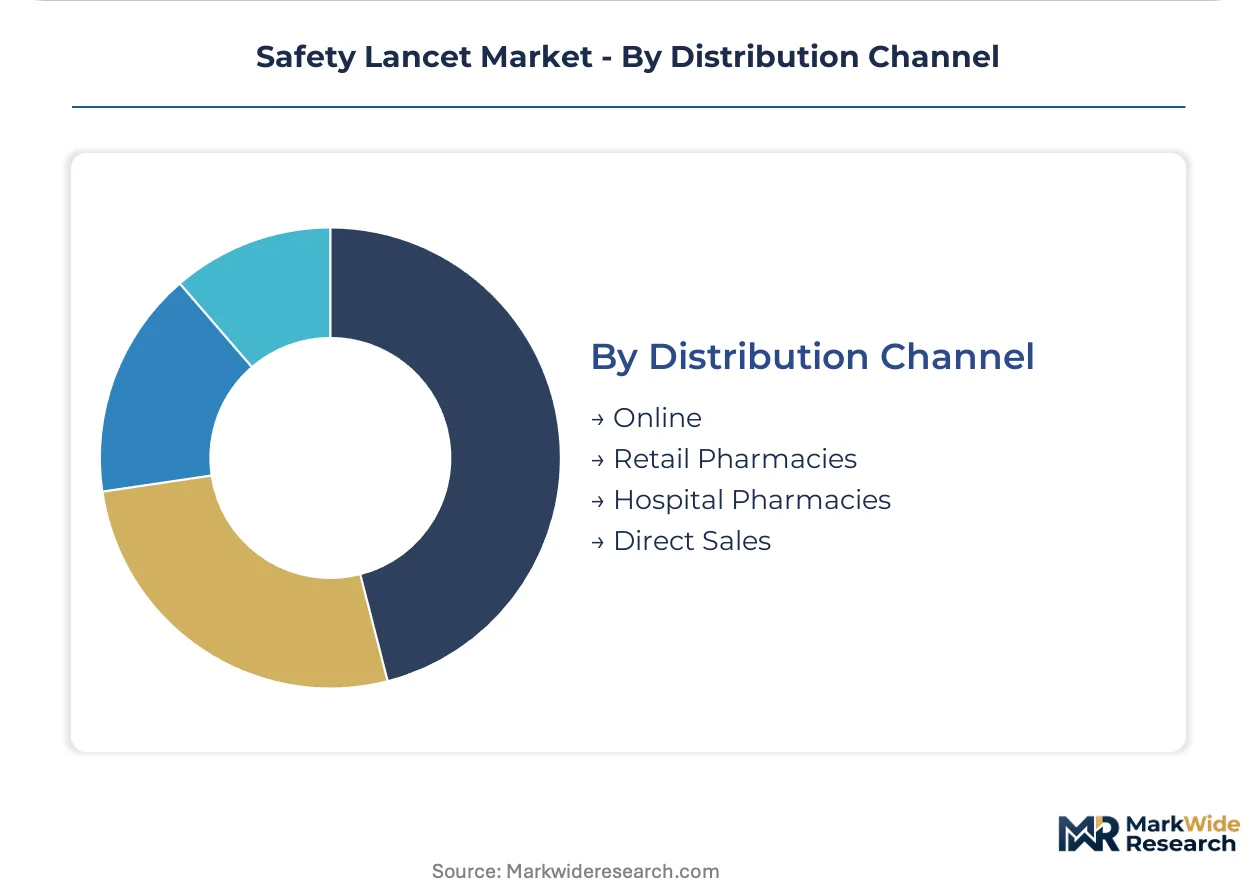
Distribution Channel:
Supply concentration among vertically integrated manufacturers shapes channel access, with direct sales relationships dominating institutional procurement and retail pharmacy chains driving private-label expansion.
- Retail Pharmacies:CVS, Walgreens, and Boots pharmacy networks are expanding private-label safety lancet offerings through contract manufacturing agreements with European producers, capturing margin from branded alternatives.
- Hospital Pharmacies:Group purchasing organizations consolidate procurement across US health systems, favoring suppliers with captive needle-forming capacity and direct distribution infrastructure.
- Online:Amazon and specialized diabetes supply platforms serve cash-pay patients seeking subscription-based replenishment models.
- Direct Sales:Roche and BD field organizations bundle safety lancets with glucose monitoring platform deployments, locking in recurring consumable revenue through ecosystem integration.
Hospital pharmacies retain procurement value leadership; retail pharmacy channels climb fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home glucose monitoring demand in Germany tolerates premium pricing for engineered safety features, while cost-sensitive diabetic populations in India prioritize basic disposable formats. Hospital procurement committees in the United States enforce strict OSHA compliance premiums. Chinese manufacturing clusters exploit this elasticity divergence through tiered export strategies.
United States
Hospital central supply networks drive institutional volume through group purchasing organization consolidation. OSHA's Bloodborne Pathogens Standard mandates retractable-lancet specifications in acute care employment settings. Minneapolis-based Cardinal Health anchors distribution infrastructure through automated supply cabinet integrations across Midwest health systems.
Germany
Vertically integrated manufacturers command continental supply chain leadership through captive needle-forming campuses. EU MDR biocompatibility requirements and REACH chemical restrictions tighten qualification timelines for housing component suppliers. Baden-Württemberg and Lower Saxony host Greiner Bio-One and Sarstedt production facilities serving hospital networks from Stuttgart to Hamburg.
China
Domestic glucose monitoring adoption accelerates through expanded basic medical insurance coverage for diabetic self-management. NMPA medical device registration reforms compress approval timelines for safety-engineered lancet submissions. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces export cost-optimized disposable formats to Southeast Asian and African markets.
India
Price-sensitive diabetic populations in Maharashtra and Gujarat states drive demand for economy-tier disposable lancets through retail pharmacy channels. CDSCO medical device rules impose quality management system requirements on importers and domestic assemblers. Karnataka's Bangalore-Tumkur corridor hosts contract manufacturers serving diagnostic platform integrators.
Japan
Aging demographics expand home healthcare monitoring penetration among Type 2 diabetic populations. PMDA pharmaceutical and medical device agency enforces stringent biocompatibility documentation for needle coating chemistries. Kansai region Osaka-based distributors bundle safety lancets with glucose meter platforms for pharmacy retail networks.
Safety Lancet Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium positioning concentrates among vertically integrated manufacturers with captive needle-forming capacity and direct hospital distribution networks. Mid-tier assemblers compete through robotics-enabled automation and private-label contract manufacturing. Competitive dynamics center on regulatory qualification speed and pharmacy channel expansion rather than pure price competition.
Among European vertically integrated specialists, Greiner Bio-One International GmbH and Sarstedt AG & Co. KG occupy positions exemplifying captive manufacturing depth, while HTL-STREFA represents the contract manufacturing archetype serving retail pharmacy private-label demand. BD anchors North American hospital channel access through direct distribution infrastructure. Roche exemplifies diagnostics ecosystem bundling, integrating safety lancets with glucose monitoring platforms to capture recurring consumable revenue.
| Leading Market Players |
|---|
| Roche |
| Sarstedt AG & Co. KG |
| BD |
| HTL-STREFA |
| Greiner Bio-One International GmbH |
| Cardinal Health |
| Owen Mumford |
| Terumo |
| Abbott |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification timelines gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant assemblers while rewarding vertically integrated manufacturers with premium positioning in hospital procurement committees.
Pricing Analysis
Consumable replenishment revenue from glucose monitoring ecosystems drives lifetime value across the installed base. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and after-sales bundling intensity. Pricing pressure stems from retail pharmacy private-label expansion as HTL-STREFA and European contract manufacturers capture margin from branded alternatives. Home glucose monitoring patients exhibit highest price sensitivity; hospital procurement committees demonstrate lowest sensitivity due to OSHA compliance mandates.
Supply Chain Analysis
Captive needle-forming capacity in Germany, the United States, and China concentrates upstream control over precision 28-33 gauge stainless steel components. Medical-grade ABS and polycarbonate feedstock draws from petrochemical complexes in the US Gulf Coast and German Rhine-Ruhr corridor. Single-source vulnerability in precision needle supply creates exposure for non-integrated assemblers. Distribution runs through group purchasing organizations in US hospital networks and direct-to-pharmacy agreements in European retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable lancet formats and emerging needle-free glucose monitoring technologies threaten substitution, compelling incumbents to defend consumable lock-in through ecosystem integration and regulatory compliance depth.
For Market Incumbents: Fortify captive needle-forming capacity through backward integration into precision stainless steel drawing operations, eliminating single-source exposure that constrains margin control. Deepen ISO 13485 certification depth across multiple production sites to accelerate qualification timelines against emerging European competitors. Defend against reusable lancet substitution by bundling safety devices with glucose meter platforms through direct sales relationships. For New Entrants and Emerging Players: Lead with private-label contract manufacturing agreements targeting US retail pharmacy chains seeking alternatives to BD and Roche branded offerings. Exploit underpenetrated point-of-care testing channels in ambulatory surgical centers where procurement specifications remain less consolidated than hospital central supply. Pursue robotics-enabled automation to collapse capital-intensity gaps with tier-one producers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-tier assembly operations as robotic deployment standardizes, improving return thresholds for contract manufacturing specialists. Five-to-ten year viability favors vertically integrated manufacturers with captive polymer compounding and needle-forming capabilities. Monitor NMPA registration reform velocity in China as signal for export capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR biocompatibility requirements tighten substance restrictions on needle coatings and housing polymers. |
| Hospital System Partnership | Group purchasing organization consolidation favors suppliers with direct distribution infrastructure and captive manufacturing. |
| Robotics-Enabled Automation | Automated assembly lines compress labor cost differentials between mid-tier and tier-one producers. |
| Retail Pharmacy Private-Label | CVS, Walgreens, and Boots chains capture margin through European contract manufacturing agreements. |
| Reimbursement Strategy | Medicare Advantage expansion for self-testing supplies locks in recurring consumable demand from diabetic patients. |
Methodological Framework
A standing panel of hospital procurement managers, GPO contracts specialists, biomedical engineers, and diabetes care educators provided ongoing calibration across primary fieldwork and secondary validation. Hospital supply databases, FDA 510(k) filings, CMS Medicare reimbursement schedules, and EU MDR notified body documentation anchored bottom-up volume estimates against top-down market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation modeling incorporated product type, delivery mode, end-user application, and regional regulatory cluster dimensions. CAGRs derived from iterative regression against diabetes prevalence trajectories, sharps injury prevention mandate enforcement timelines, and point-of-care testing adoption curves.
Forecasts assume regulatory continuity in OSHA Bloodborne Pathogens Standard, EU MDR, and FDA Needlestick Safety and Prevention Act enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as home glucose monitoring reimbursement structures and needle-free monitoring technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Tattoo Needles Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Global Needles Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Medical Bags Market
Medical Supplies
Swab Cups Market
Medical Supplies
South America Syringe Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Global Synthetic Absorbable Sutures Market